
 Italy Oil and Gas Downstream Market | 2026-2036
Italy Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Oil and Gas Downstream Market Foresight
Italy is narrowing its refining capacity surplus through strategic upgrades at Porto Marghera and Milazzo. Eni SPA leverages its integrated upstream-downstream footprint to sustain margin capture across refining and petrochemicals. Anonima Petroli Italiana anchors independent distribution strength through its extensive retail network. Shell Italia S.p.A competes on premium lubricant formulations for industrial and transportation end users.
The Italy oil and gas downstream sector encompasses refining, processing, and distribution of crude oil into fuels, lubricants, petrochemical feedstocks, and asphalts, with typical refinery complexity measured by the Nelson Complexity Index ranging from 6 to 12 for Italian facilities. Its primary purpose is converting raw hydrocarbons into finished products for mobility, heating, and manufacturing inputs. Refined fuels retain the largest volume share but face margin compression from electrification trends, while petrochemicals command higher value per barrel processed and attract reinvestment. Lubricants offer stable recurring revenue tied to industrial maintenance cycles and transportation fleet operations.
Italy's downstream operators navigate oversight from the Ministry of Ecological Transition, EU REACH chemical registration requirements, and CE marking for refined product quality standards. These frameworks mandate sulfur content reductions, biofuel blending obligations, and emissions disclosure that reshape refinery investment priorities and product slate decisions. Stakeholders must track biofuel mandate escalations and hydrogen refinery integration pilots to anticipate which assets retain competitive viability.
Market Dynamics
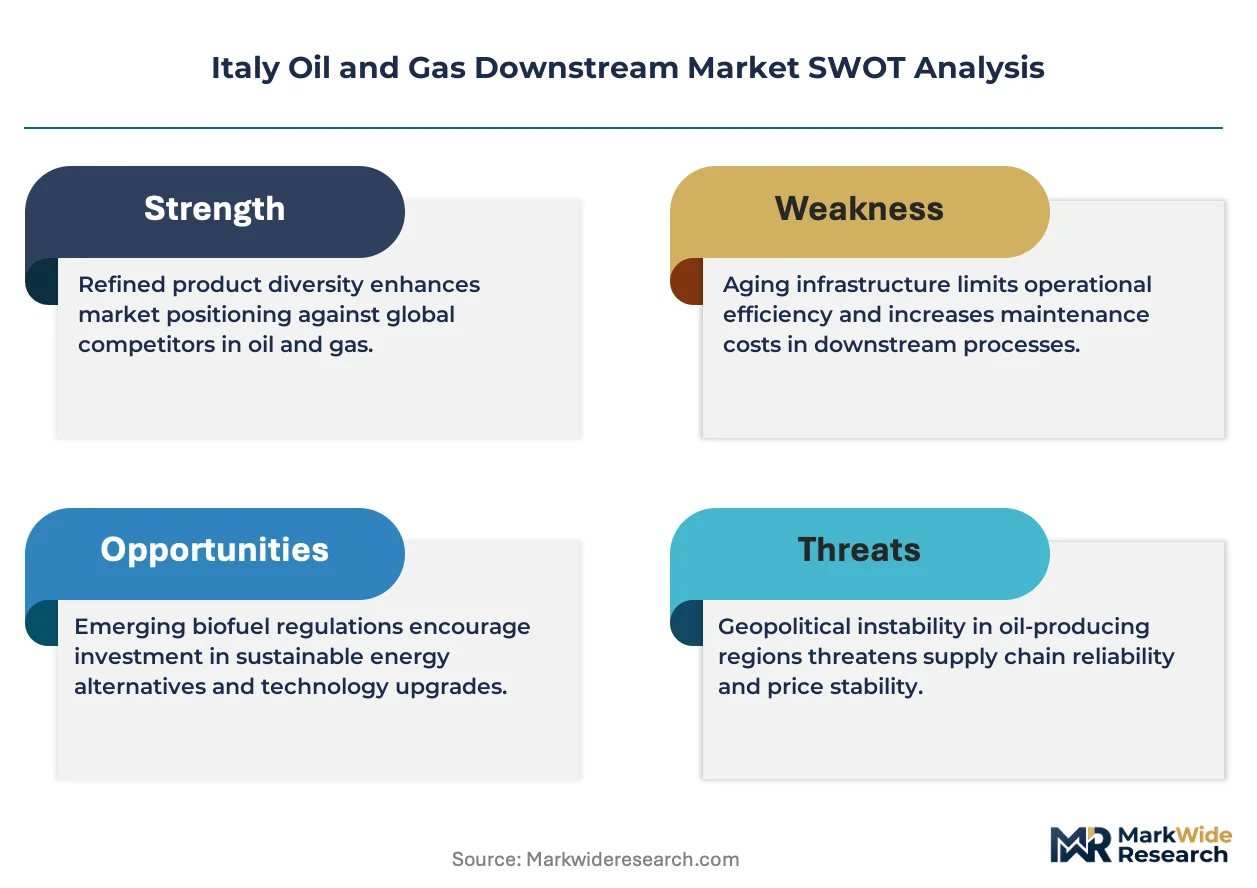
Italy's downstream operators face a structural squeeze between the EU Green Deal's carbon intensity mandates and the capital requirements for refinery hydrogen integration. The Ministry of Ecological Transition's biofuel blending escalations are forcing product slate reconfigurations faster than asset depreciation cycles allow.
Growth Catalysts
- F-Gas Regulation compliance deadlines:Refrigerant and aerosol propellant specifications are tightening, creating demand for low-GWP synthetic lubricants and processed gas formulations from Italian blenders.
- Po Valley petrochemical clustering:Ravenna's integrated refining-petrochemical corridor attracts specialty chemical investments that lift margin capture per barrel processed.
- Fleet electrification lag:Commercial vehicle operators in Lombardy and Veneto extend diesel asset lifecycles through premium lubricant upgrades, sustaining refined product offtake.
Market Restraints
- Crude supply concentration:Italian refiners depend on Russian and Caspian crude grades subject to sanctions volatility and freight rate spikes through the Turkish Straits.
- Carbon border adjustment exposure:The EU CBAM phases in embodied emissions reporting for imported refined products, disadvantaging Mediterranean import-reliant terminals against Northwest European integrated complexes.
- Electrification substitution:Battery electric vehicle penetration in Northern Italy's urban cores compresses gasoline demand faster than refinery rationalization can absorb.
Strategic Opportunities
- Sardinia bunkering hub development:Cagliari and Porto Torres terminals can capture Mediterranean marine fuel switching demand as IMO 2025 sulfur regulations tighten.
- CE marking for synthetic fuels:Power-to-liquid certification pathways open premium positioning for Italian refiners with carbon capture integration at Porto Marghera.
- Hydrogen refinery pilots:Eni's Maghera facility trials electrolytic hydrogen for hydrocracker feed, creating first-mover advantage in EU renewable fuel of origin certification.
Industry Challenges
- Process control engineering scarcity:Advanced refining units require distributed control system specialists that Italian technical institutes no longer graduate in sufficient volume.
- REACH registration timelines:Petrochemical intermediates face extended ECHA evaluation periods that delay new product commercialization by 18-24 months.
- Legacy terminal automation:Adriatic coastal storage facilities operate 1990s-era SCADA systems that resist cybersecurity retrofitting for EU NIS2 directive compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Oil and Gas Downstream Market |
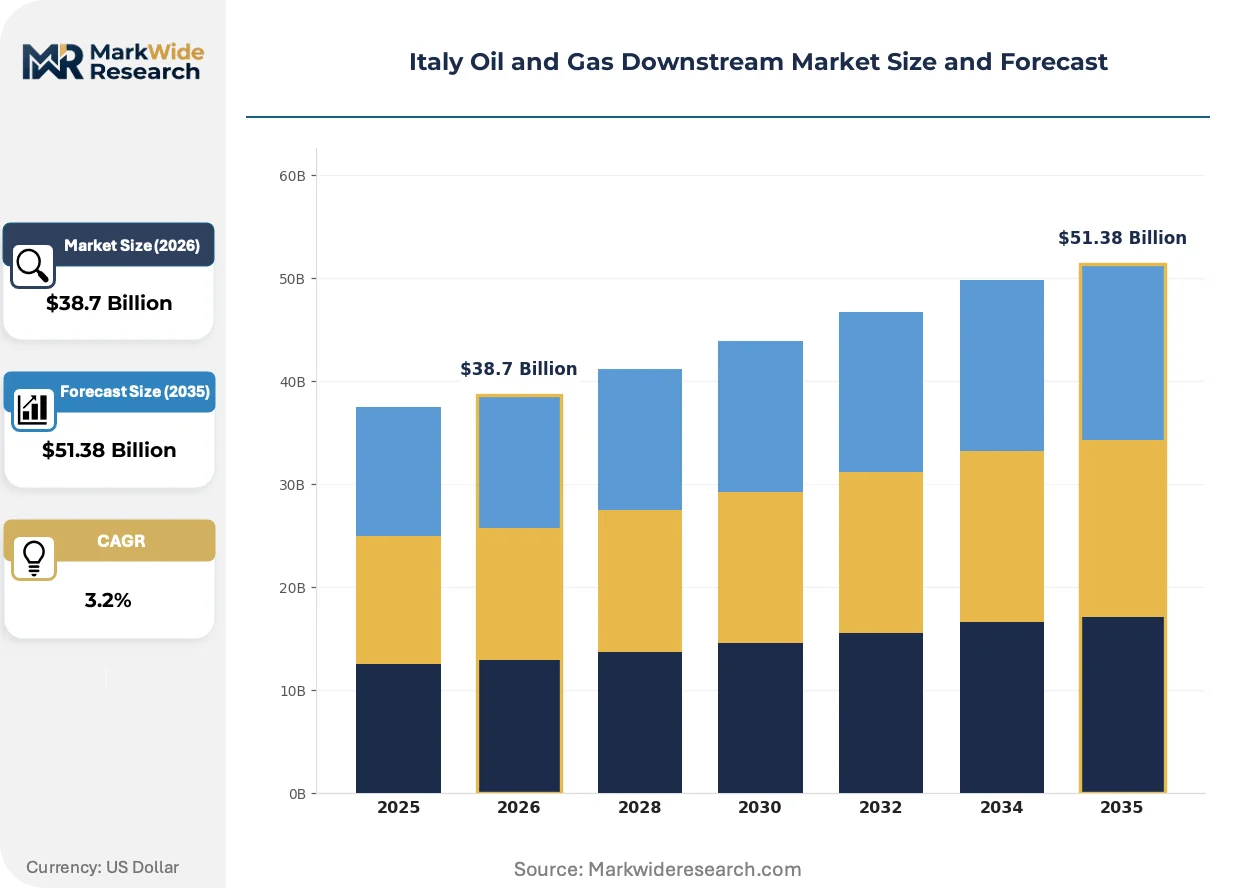
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $51.38 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Lubricants, Petrochemicals, Asphalts Application: Transportation, Industrial, Residential Heating, Power Generation Distribution Channel: Retail Outlets, Wholesale Distributors, Online Platforms, B2B Sales End User: Energy Companies, Transportation Firms, Manufacturing Units, Households |
| Companies Covered | PJSC Lukoil Oil Company, Edison S.p.A, Eni SPA, BP Italia S.p.A, Shell Italia S.p.A, Total SA, Anonima Petroli Italiana, OMV Italia S.r.l, Esso Italiana Srl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Oil and Gas Downstream Market Shifts & Advancements
Digital twins and predictive maintenance systems are compressing refinery turnaround intervals. Italian operators deploy these tools to sustain throughput against aging asset bases and stricter emissions accounting.
Advanced process control software is virtualizing traditional refinery engineering workflows. Eni and API deploy AspenTech and Honeywell simulation platforms that reduce unit optimization cycles from weeks to hours. This compression enables real-time margin optimization that manual blending desk operations cannot match.
REACH authorization requirements for polycyclic aromatic hydrocarbons in lubricant base stocks are forcing formulation changes. The ECHA sunset date for certain extender oils pushes blenders toward Group III synthetics or re-refined bases. Industrial lubricant suppliers in Emilia-Romagna reformulate metalworking fluids ahead of 2026 restrictions.
Long-term service agreements are replacing spot procurement for marine lubricants. Ship operators trading through Genoa and Trieste consolidate purchasing through single-supplier contracts covering technical support and used oil analysis. This bundling favors integrated suppliers with Italian port presence over commodity traders.
Italy Oil and Gas Downstream Market Segmentation
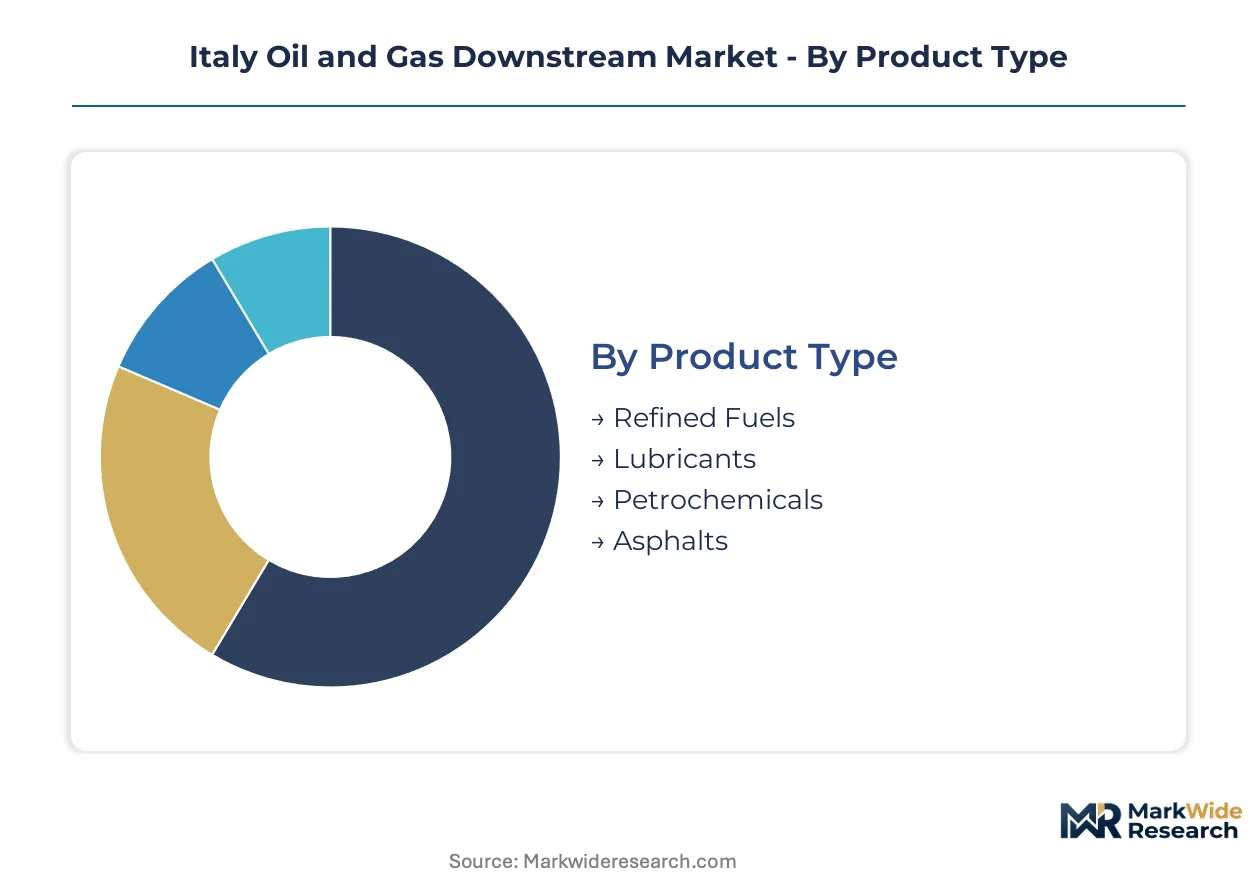
Segmentation in Italy's downstream oil and gas market reveals how product specifications, application intensity, and channel economics determine margin capture. Refiners and distributors configure asset deployment differently across each dimension, from high-volume fuel terminals to specialty lubricant blending facilities serving industrial maintenance contracts.
Product Type:
Mature categories dominate volume throughput while emerging segments attract reinvestment for margin defense against electrification pressures.
- Refined Fuels:Gasoline, diesel, and heating oil formulations processed through hydrocracking and catalytic reforming units at Italian refineries. Fleet operators in Lombardy and Veneto sustain diesel offtake through efficiency upgrades, though gasoline demand compresses from passenger EV penetration in Milan and Turin urban cores.
- Lubricants:Engine oils, industrial fluids, and metalworking formulations ranging from Group I mineral bases to Group III synthetics and re-refined stocks. REACH authorization deadlines for polycyclic aromatic hydrocarbons are forcing Emilia-Romagna blenders toward synthetic reformulations ahead of regulatory sunset dates.
- Petrochemicals:Olefins, aromatics, and polymer feedstocks produced at Ravenna and Porto Marghera integrated complexes.
- Asphalts:Road construction binders and roofing materials derived from vacuum residue processing.
Refined fuels handles the majority of throughput; petrochemicals is the fastest mover on share as crackers displace fuel production for margin capture.
Application:
Volume concentration follows industrial density corridors, with demand intensity varying sharply between mobility services and stationary energy uses.
- Transportation:Road, rail, marine, and aviation fuel offtake spanning private vehicles through commercial fleets. The Po Valley logistics corridor generates concentrated diesel demand from trucking operators serving Milan-Bologna freight routes, while IMO 2025 sulfur regulations redirect marine fuel procurement toward Cagliari bunkering terminals.
- Industrial:Process heat, feedstock inputs, and lubrication for manufacturing operations. Petrochemical off-takers at Ravenna cluster around ethylene crackers and polyethylene units, creating integrated demand for naphtha feedstocks and specialty chemical intermediates.
- Residential Heating:Distillate fuel oil and LPG combustion for space heating in Northern Italian housing stock.
- Power Generation:Fuel oil and diesel backup generation for grid stability and industrial captive power.
Transportation commands the largest volume position; industrial applications are climbing the fastest as manufacturers seek feedstock security.
Distribution Channel:
Channel economics split between high-frequency retail transactions and contracted B2B volumes with divergent working capital requirements.
- Retail Outlets:Branded and independent service stations dispensing fuels and convenience products. API's network density across Italian motorways captures highway corridor traffic, while Eni maintains premium positioning through integrated loyalty programs and non-fuel retail.
- Wholesale Distributors:Bulk fuel terminals and depots supplying commercial accounts and secondary retailers. Adriatic coastal storage facilities at Trieste and Venice handle import-reliant volumes subject to EU CBAM embodied emissions reporting as carbon border adjustments phase in.
- Online Platforms:Digital procurement portals for lubricants and specialty products.
- B2B Sales:Direct refinery and blender contracts with industrial end users and fleet operators.
Retail outlets process the highest transaction frequency; B2B sales are expanding most quickly as procurement consolidates under long-term supply agreements.
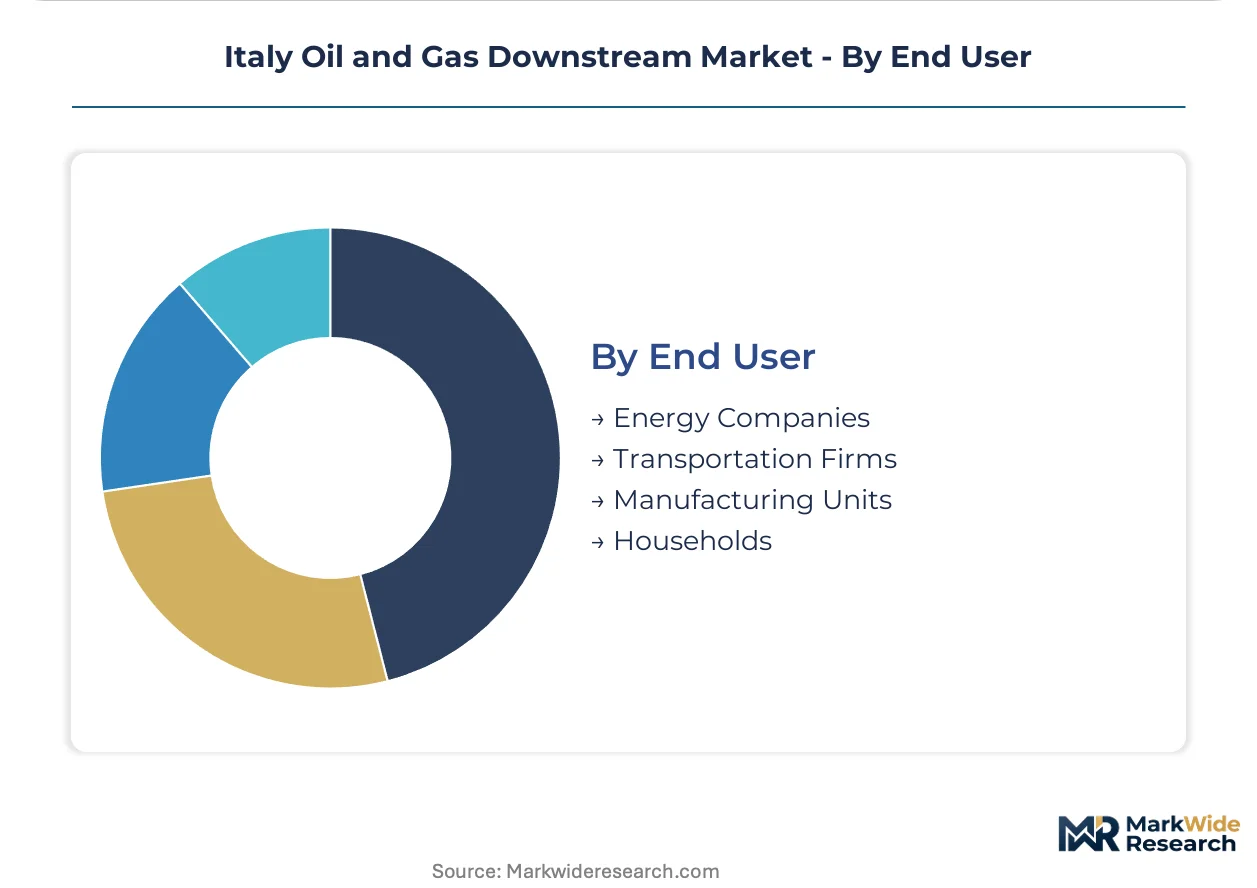
End User:
Customer scale determines contract structure, from spot-indexed utility procurement to formula-priced industrial supply agreements with technical service bundling.
- Energy Companies:Refiners, traders, and utilities managing hydrocarbon supply chains and generation assets. Eni SPA leverages vertical integration across upstream production, refining, and retail distribution to capture margin at multiple value chain points.
- Transportation Firms:Fleet operators, shipping lines, and logistics providers consuming fuels and lubricants at scale. Mediterranean marine operators trading through Genoa and Trieste are consolidating lubricant purchasing through single-supplier contracts covering technical support and used oil analysis.
- Manufacturing Units:Industrial facilities requiring process energy, feedstocks, and maintenance fluids.
- Households:Individual consumers purchasing motor fuels, heating oil, and packaged lubricants.
Energy companies anchor the largest contracted volumes; transportation firms are gaining share fastest as fleet electrification lags extend diesel asset lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian refining capacity clusters along the Adriatic coast and Sicily, with integrated complexes at Porto Marghera and Milazzo processing Caspian and Middle Eastern crude grades. The Po Valley industrial corridor generates concentrated demand from petrochemical off-takers and manufacturing clusters.
Lombardy
Milan's logistics hub sustains diesel demand from trucking operators serving the Milan-Bologna freight corridor. The Lombardy regional government enforces low-emission zone restrictions that accelerate fleet turnover toward Euro VI-compliant vehicles. Bergamo and Brescia manufacturing zones consume industrial lubricants for metalworking and textile machinery maintenance.
Veneto
Porto Marghera's refining complex anchors the region's downstream infrastructure, processing vacuum residue into asphalt and marine fuels. The Ministry of Ecological Transition's biofuel blending mandates force product slate reconfigurations at this facility. Mestre and Padua industrial districts purchase process heat and feedstock inputs from adjacent petrochemical units.
Emilia-Romagna
Ravenna's integrated refining-petrochemical corridor attracts specialty chemical investments that lift margin capture per barrel processed. REACH authorization deadlines for polycyclic aromatic hydrocarbons push Bologna-area lubricant blenders toward Group III synthetic reformulations. Modena and Reggio Emilia automotive suppliers sustain metalworking fluid demand through precision manufacturing contracts.
Sicily
Milazza's refinery processes heavy sour crudes into high-sulfur fuel oil and distillate streams for Mediterranean bunkering markets. The island's isolation from mainland pipeline networks creates import-dependent supply chains subject to freight rate volatility. Catania and Palermo terminals serve regional transportation demand with limited interconnection to Northern Italian distribution infrastructure.
Sardinia
Cagliari and Porto Torres terminals position to capture Mediterranean marine fuel switching demand as IMO 2025 sulfur regulations tighten. The island's strategic location on East-West shipping routes attracts bunkering investment from operators seeking alternatives to Gibraltar and Malta. Sassari industrial users rely on coastal imports for distillate supply given absent refinery capacity.
Italy Oil and Gas Downstream Market Competitive Landscape
Vertically integrated majors and independent distributors split the market between margin-capturing refining operations and high-frequency retail transactions. The competitive structure reflects asset-heavy upstream control versus network-density downstream reach. National oil companies and independent retailers constitute the dominant archetypes. Players defend position through refinery hydrogen integration pilots and long-term marine lubricant service contracts.
Among Italy-based operators, Eni SPA and Anonima Petroli Italiana represent contrasting strategic positions. Eni exemplifies the integrated archetype with captive upstream production and refining capacity. Anonima Petroli Italiana occupies the independent distributor tier through extensive retail network coverage. Shell Italia S.p.A anchors the multinational subsidiary segment competing on premium lubricant formulations.
| Leading Market Players |
|---|
| PJSC Lukoil Oil Company |
| Edison S.p.A |
| Eni SPA |
| BP Italia S.p.A |
| Shell Italia S.p.A |
| Total SA |
| Anonima Petroli Italiana |
| OMV Italia S.r.l |
| Esso Italiana Srl |
| Others |
Supply & Pricing Matrix
Overcapacity at Milazzo and Porto Marghera refineries compresses margin capture across Italian downstream operators, forcing product slate reconfigurations toward higher-value petrochemicals and specialty lubricants while biofuel blending mandates reshape cost structures. This utilization squeeze tightens pricing discipline among integrated majors and independent distributors competing for contracting transportation fuel demand.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across refrigerant-grade lubricants and processed gas formulations, with CE marking requirements separating certified synthetic blends from commodity mineral bases. Price differentiation hinges on REACH compliance status and hydrocracker integration depth, with Group III synthetics commanding premiums over re-refined stocks. Cost compression in gasoline refining is intensifying because electrification in Milan and Turin urban cores erodes offtake volumes faster than asset rationalization. Fleet operators in Lombardy exhibit highest price sensitivity due to thin logistics margins, while petrochemical off-takers at Ravenna prioritize feedstock security over unit cost.
Supply Chain Analysis
Italian refiners draw from Russian, Caspian, and Middle Eastern crude grades processed through Adriatic coastal terminals at Trieste and Venice. Raw material dependencies center on vacuum residue for asphalt production, naphtha for Ravenna crackers, and hydrogen feedstocks for hydrocracker units. Single-source vulnerability runs through Turkish Straits freight corridors subject to sanctions volatility and rate spikes. Distribution feeds from coastal import terminals to inland Po Valley demand clusters via pipeline networks and secondary barge routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian downstream operators face substitution defense against battery electric vehicle penetration in Northern Italy's urban cores, where passenger transport electrification compresses gasoline demand faster than refinery product slate shifts can offset.
For Market Incumbents: Entrench hydrogen integration pilots at Porto Marghera and Milazzo to secure EU renewable fuel of origin certification ahead of competitors. Deepen backward integration into carbon capture infrastructure to position for power-to-liquid premium pricing. Lock long-term marine lubricant service contracts with Mediterranean shipping operators through Genoa and Trieste to defend recurring revenue against commodity traders.
For New Entrants and Emerging Players: Sardinia's bunkering infrastructure presents underpenetrated white space as IMO 2025 sulfur regulations redirect Mediterranean marine fuel demand toward Cagliari and Porto Torres. Emilia-Romagna lubricant blenders face REACH-driven formulation gaps that create entry opportunity for synthetic base stock suppliers. Pursue technical partnership routes with Ravenna petrochemical complexes rather than greenfield refining investment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated lubricant distributors with marine service contracts and industrial maintenance agreements. Five-to-ten year viability favors assets with hydrogen refinery retrofit optionality and coastal terminal access. Monitor EU CBAM phase-in timelines and biofuel mandate escalation rates as inflection signals for import-reliant versus integrated complex competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Refinery Integration | Eni's Maghera electrolytic pilot secures first-mover advantage in EU renewable fuel certification pathways. |
| Marine Fuel Bunkering Expansion | Cagliari terminal development captures Mediterranean IMO 2025 low-sulfur demand away from Gibraltar. |
| Synthetic Lubricant Reformulation | REACH PAH sunset deadlines force Emilia-Romagna blenders toward Group III base stock transitions. |
| Carbon Capture Retrofit | Porto Marghera integration enables power-to-liquid premium positioning under CE marking protocols. |
| Long-term Service Contracting | Single-supplier marine lubricant agreements through Genoa consolidate purchasing and technical support bundling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Ministry of Ecological Transition policy filings, EU ECHA REACH registration databases, and IEA downstream energy statistics. Refinery operations directors, fleet procurement managers at Lombardy logistics operators, and marine fuel traders through Genoa and Trieste provided operational validation. Customs trade data, SEC filings from listed energy majors, and Adriatic terminal throughput records supplied quantitative grounding. Bottom-up asset-level modeling triangulates against top-down sectoral expenditure patterns.
Forecast inputs incorporate refinery capacity utilization trajectories, biofuel blending mandate escalation schedules, and electrification penetration curves across passenger and commercial vehicle segments. Segmentation dimensions span product type, application intensity, distribution channel economics, and end-user contract structures. CAGRs derive from regression against historical throughput volumes and projected demand elasticity under regulatory constraint. Hydrogen refinery pilot timelines and EU CBAM phase-in thresholds inform scenario boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive moves by national oil companies or private equity-backed terminal operators would shift outcomes. Regulatory acceleration beyond current EU Green Deal trajectories, breakthroughs in battery energy density, or Turkish Straits logistics disruptions represent specific revision risks. Quarterly review of refinery margin spreads, marine fuel sulfur spreads, and REACH authorization timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
North America Coiled Tubing Services Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Coal Mining Market