
 Trinidad and Tobago Oil and Gas Upstream Market | 2026-2036
Trinidad and Tobago Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Trinidad and Tobago Oil and Gas Upstream Market Analytics
Petrochemical buyers are redrawing offtake patterns as ammonia and methanol producers expand feedstock contracts. Shell Trinidad & Tobago Limited leverages its integrated gas-to-liquids position across the East Coast Marine Area. BP PLC anchors its Caribbean portfolio through continued investment in the Columbus Basin deepwater fields. EOG Resources, Inc. competes onshore in the South West Peninsula with tight-gas development programs.
Trinidad and Tobago Oil and Gas Upstream encompasses exploration, drilling, and production of hydrocarbons from offshore and onshore reservoirs, with subsea tiebacks to shallow-water platforms and onshore processing trains handling up to 4.2 billion cubic feet of natural gas daily at peak. Natural gas dominates production volumes, supplying the Point Lisas Industrial Estate and Atlantic LNG export trains. Seismic services and drilling services together command the largest share of contracted expenditure as operators renew 3D ocean-bottom surveys and high-specification jackup rig programs. Exploration activity concentrates in deepwater blocks where subsea technology reduces development breakevens.
The Ministry of Energy and Energy Industries administers production sharing contracts and bidding rounds, while the Environmental Management Authority enforces offshore environmental impact assessments. The country's national petroleum regulator sets local content thresholds that shape contractor selection and service company market access. Stakeholders must monitor the pace of deepwater licensing against the maturation timeline of existing shallow-water assets.
Market Dynamics
Deepwater exploration economics are tightening as subsea tieback technology compresses development breakevens below shallow-water legacy asset thresholds. The Ministry of Energy and Energy Industries' modernized production sharing contract terms are redirecting capital toward high-pressure high-temperature reservoirs that Atlantic LNG expansion plans require.
Growth Catalysts
- Atlantic LNG Train Expansion:Fourth-train development at the Point Fortin complex is locking in 15-year offtake commitments from domestic gas fields. Petrochemical buyers at Point Lisas are extending feedstock contracts to match.
- Deepwater Block Licensing:The Ministry of Energy and Energy Industries' 2023-2024 bidding rounds released Columbus Basin acreage with improved fiscal terms. Subsea processing units are reducing platform capital intensity.
- Tight-Gas Development:Onshore South West Peninsula programs are accessing sandstone reservoirs through extended-reach drilling. Local content thresholds are channeling service contracts toward domestic rig operators.
Market Restraints
- Mature Shallow-Water Decline:East Coast Marine Area fields are exhibiting 8-12% annual production decay. Replacement reserves require deeper, higher-pressure drilling.
- Steel and Equipment Cost Volatility:Jackup rig dayrates and subsea tree pricing fluctuate with global offshore construction demand. Caribbean supply chain concentration amplifies procurement risk.
- Carbon Intensity Scrutiny:The Environmental Management Authority's offshore environmental impact assessments are extending approval timelines for new drill permits.
Strategic Opportunities
- Cross-Border Gas Integration:Venezuelan maritime boundary negotiations could unlock Dragon Field tiebacks to Trinidad infrastructure. Pipeline interconnectivity would reshape Caribbean supply geography.
- Blue Ammonia Export Positioning:Carbon capture retrofits at existing methanol and ammonia trains are positioning Point Lisas for EU import demand under CBAM regulations.
- Decommissioning Services:First-generation platform removals in the 2030-2035 window are creating specialist contracting demand. Local yards at La Brea are upgrading heavy-lift capabilities.
Industry Challenges
- Subsea Engineering Talent Pipeline:High-pressure high-temperature well design expertise concentrates among a handful of international service contractors. The University of Trinidad and Tobago's petroleum engineering programs are expanding simulation lab capacity.
- Legacy Platform Integration:Subsea tiebacks to 1990s-era shallow-water facilities require control system retrofits and flow assurance reengineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trinidad and Tobago Oil and Gas Upstream Market |
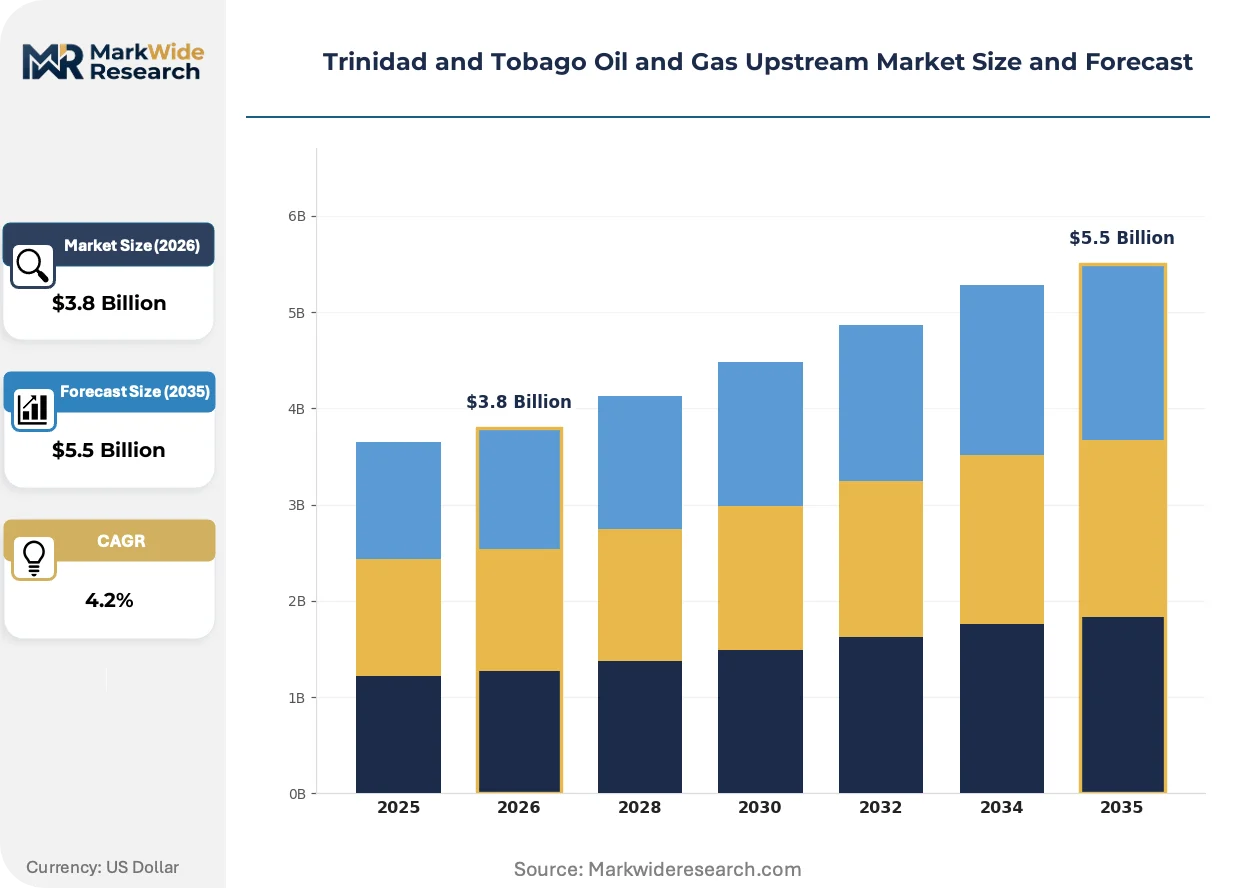
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Condensate, NGLs Technology: Exploration, Drilling, Production, Subsea End User: Refineries, Power Plants, Chemical Plants, Export Markets Service Type: Drilling Services, Seismic Services, Engineering Services, Maintenance Services |
| Companies Covered | EOG Resources, Inc., ExxonMobil, BP PLC, Renaissance Energy Ltd, Predator Oil & Gas, Perenco SA, Repsol, BHP Group PLC, Shell Trinidad & Tobago Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trinidad and Tobago Oil and Gas Upstream Market Evolving Landscape
Digital reservoir characterization and modular subsea systems are compressing development timelines for marginal deepwater discoveries. Operators are resequencing capital deployment to align with Atlantic LNG offtake windows.
Subsea multiphase pumping is displacing conventional platform-based separation infrastructure in the Columbus Basin. BP and Shell are deploying seaboost units at 1,200-meter depths to extend field life. This technology is displacing fixed-platform economics for reservoirs below 500 million cubic feet of recoverable reserves.
The Ministry of Energy and Energy Industries' local content framework is mandating 60% Trinidad and Tobago national participation in drilling services. Procurement officers are restructuring tender packages to qualify domestic vessel operators and onshore fabrication yards. Deepwater block operators are responding by partnering with local service consortia for seismic and logging contracts.
Power plant and petrochemical buyers are consolidating procurement through long-term take-or-pay structures that mirror Atlantic LNG contract terms. The Greater Port of Spain industrial corridor is seeing compressed switching cycles as ammonia producers lock in 10-year gas supply agreements. This concentration is most visible at Point Lisas where methanol capacity expansions are predicated on dedicated field development commitments.
Trinidad and Tobago Oil and Gas Upstream Market Segmentation
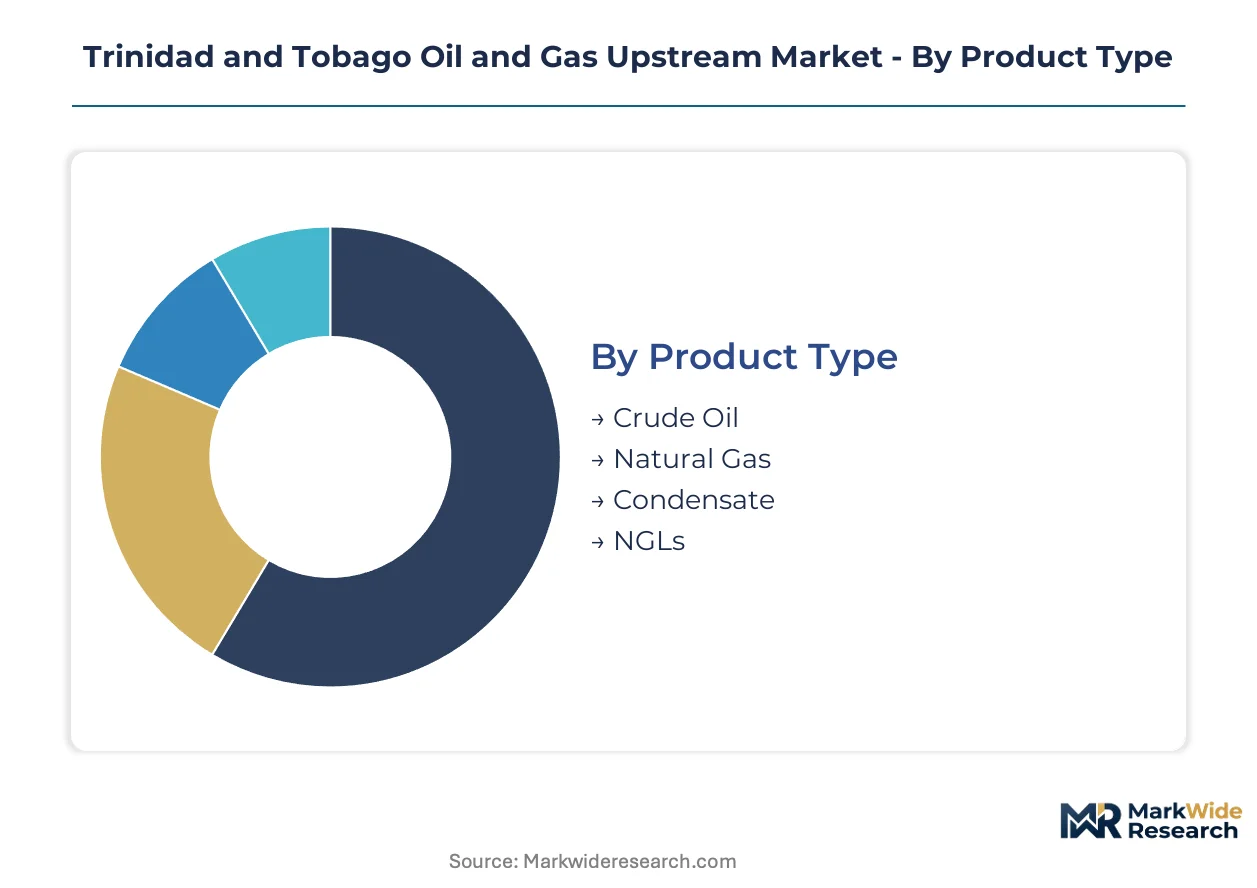
Segmentation in Trinidad and Tobago's upstream market reflects the dominance of natural gas over liquids, the concentration of demand in Point Lisas petrochemical complexes, and the regulatory pressure on local content thresholds that reshape contractor selection across service categories.
Product Type:
The Ministry of Energy and Energy Industries tracks production volumes through distinct hydrocarbon classifications, with fiscal treatment varying by product stream under production sharing contract terms.
- Natural Gas:Comprising methane-rich reservoirs from Columbus Basin deepwater and South West Peninsula tight-gas formations. Atlantic LNG trains and Point Lisas ammonia-methanol complexes absorb the bulk of offtake, with pipeline specifications requiring processing at Beachfield and Galeota onshore facilities.
- Crude Oil:Heavy-sour grades from mature East Coast Marine Area fields with API gravities below 20 degrees. Refinery feedstock demand concentrates at Petrotrin's Pointe-a-Pierre complex, though declining reservoir pressure limits sustained output.
- Condensate:Light liquid fractions separated at platform headers and onshore stabilizers, blending into domestic refinery slates.
- NGLs:Ethane, propane, and butane recovered at gas processing trains, supplying local LPG distribution and regional export markets.
Established volume favors Natural Gas; emerging adoption favors Condensate as deepwater liquids-rich discoveries mature.
Technology:
Capital deployment intensity separates exploration-phase seismic expenditure from production-phase facility commitments, with subsea tieback economics displacing conventional platform construction.
- Subsea:Multiphase pumping and seabed processing units at 1,200-meter depths in Columbus Basin blocks. BP and Shell deployments extend field life without fixed-platform capital, compressing development breakevens below legacy shallow-water thresholds.
- Production:Wellhead compression and artificial lift systems sustaining East Coast Marine Area output amid 8-12% annual decline rates. Control system retrofits integrate 1990s-era platforms with modern digital infrastructure.
- Drilling:Extended-reach programs accessing South West Peninsula sandstone reservoirs, with jackup rigs contracted under local content-mandated tender structures.
- Exploration:3D ocean-bottom seismic surveys across deepwater blocks licensed under modernized production sharing terms.
Subsea commands the steepest expansion trajectory; Drilling maintains the largest contracted expenditure base.
End User:
Demand concentration in the Greater Port of Spain industrial corridor creates procurement power asymmetries, with long-term take-or-pay structures locking in dedicated field development commitments.
- Chemical Plants:Ammonia and methanol producers at Point Lisas Industrial Estate, extending 10-year feedstock contracts to match Atlantic LNG expansion timelines. Carbon capture retrofits position facilities for EU CBAM-compliant blue ammonia exports.
- Power Plants:Generation assets in the Port of Spain corridor, consolidating procurement through structures mirroring Atlantic LNG contract terms.
- Export Markets:Atlantic LNG trains at Point Fortin, with fourth-train development locking in 15-year offtake commitments from domestic gas fields.
- Refineries:Domestic processing capacity at Petrotrin facilities, constrained by declining crude supply from maturing shallow-water assets.
Chemical Plants anchor contract duration; Export Markets drive upstream investment sequencing.
Service Type:
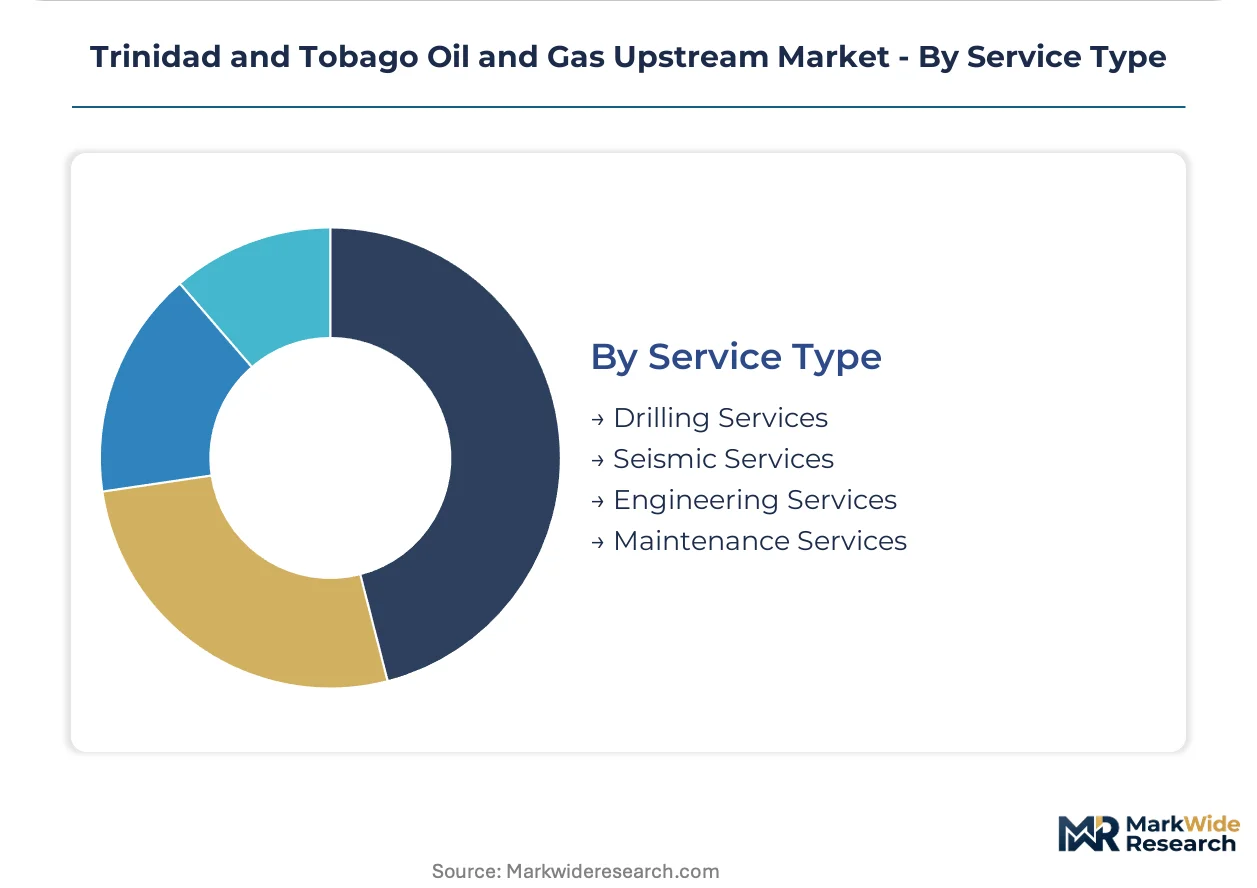
Local content thresholds at 60% national participation reshape competitive dynamics, with procurement officers restructuring tender packages to qualify domestic vessel operators and fabrication yards.
- Seismic Services:3D ocean-bottom surveys and reservoir characterization, with deepwater block operators partnering with local consortia for data acquisition. University of Trinidad and Tobago programs expand simulation lab capacity to support technical workforce development.
- Drilling Services:High-specification jackup rig programs and well construction, channeling contracts toward domestic rig operators under Ministry of Energy and Energy Industries mandates.
- Engineering Services:High-pressure high-temperature well design and subsea system integration, with expertise concentrating among international contractors partnering with local entities.
- Maintenance Services:Platform integrity management and decommissioning preparation, with La Brea yards upgrading heavy-lift capabilities for 2030-2035 removal campaigns.
Seismic Services lead technology transfer requirements; Maintenance Services gain share fastest as first-generation assets reach end-of-life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Galeota Ridge pipeline corridor anchors Trinidad and Tobago's upstream connectivity, linking offshore production trains to Atlantic LNG export facilities and Point Lisas petrochemical complexes. This infrastructure backbone concentrates drilling activity and service procurement across the island's eastern and southern coastal zones.
Greater Port of Spain Industrial Corridor
Atlantic LNG trains and ammonia-methanol complexes drive gas field development commitments. The Ministry of Energy and Energy Industries administers production sharing contracts from headquarters in Port of Spain. Point Lisas hosts the densest clustering of petrochemical buyers extending long-term offtake agreements.
East Coast Marine Area
Shell Trinidad & Tobago Limited operates integrated gas-to-liquids infrastructure across mature shallow-water blocks. The Environmental Management Authority enforces offshore environmental impact assessments for new drill permits. Beachfield gas processing trains handle feedstock conditioning for Atlantic LNG export specifications.
South West Peninsula
EOG Resources, Inc. targets tight-gas sandstone reservoirs through extended-reach drilling programs. Local content thresholds at 60% national participation channel rig contracts toward domestic operators. La Brea fabrication yards are upgrading heavy-lift capabilities for platform maintenance and decommissioning campaigns.
Columbus Basin Deepwater
BP PLC anchors Caribbean portfolio investment across high-pressure high-temperature reservoirs. Modernized production sharing contract terms from 2023-2024 bidding rounds redirect capital toward subsea tieback developments. Subsea multiphase pumping at 1,200-meter depths extends field life without fixed-platform capital intensity.
Point Fortin Export Complex
Fourth-train development locks in 15-year offtake commitments from domestic gas fields. The Ministry of Energy and Energy Industries monitors production volumes against Atlantic LNG expansion timelines. Onshore processing trains handle up to 4.2 billion cubic feet of natural gas daily at peak throughput.
Trinidad and Tobago Oil and Gas Upstream Market Competitive Landscape
Listed majors compete with private specialists across integrated gas-to-liquids value chains and tight-gas development programs. The upstream sector exhibits tiered concentration where international operators hold deepwater acreage while regional firms capture onshore service mandates. Two strategic archetypes dominate: integrated majors leveraging full-value-chain positions, and independent developers targeting specific reservoir types. Competitive moves center on subsea technology partnerships and local content consortium formations.
Within the integrated major tier, Shell Trinidad & Tobago Limited and BP PLC exemplify full-value-chain operators spanning exploration through LNG export. EOG Resources, Inc. represents the independent developer archetype focused on onshore tight-gas execution. These three anchors demonstrate how geographic scope and asset integration level separate competitive positioning in Trinidad and Tobago's upstream market.
| Leading Market Players |
|---|
| EOG Resources, Inc. |
| ExxonMobil |
| BP PLC |
| Renaissance Energy Ltd |
| Predator Oil & Gas |
| Perenco SA |
| Repsol |
| BHP Group PLC |
| Shell Trinidad & Tobago Limited |
| Others |
Value Network & Pricing Analysis
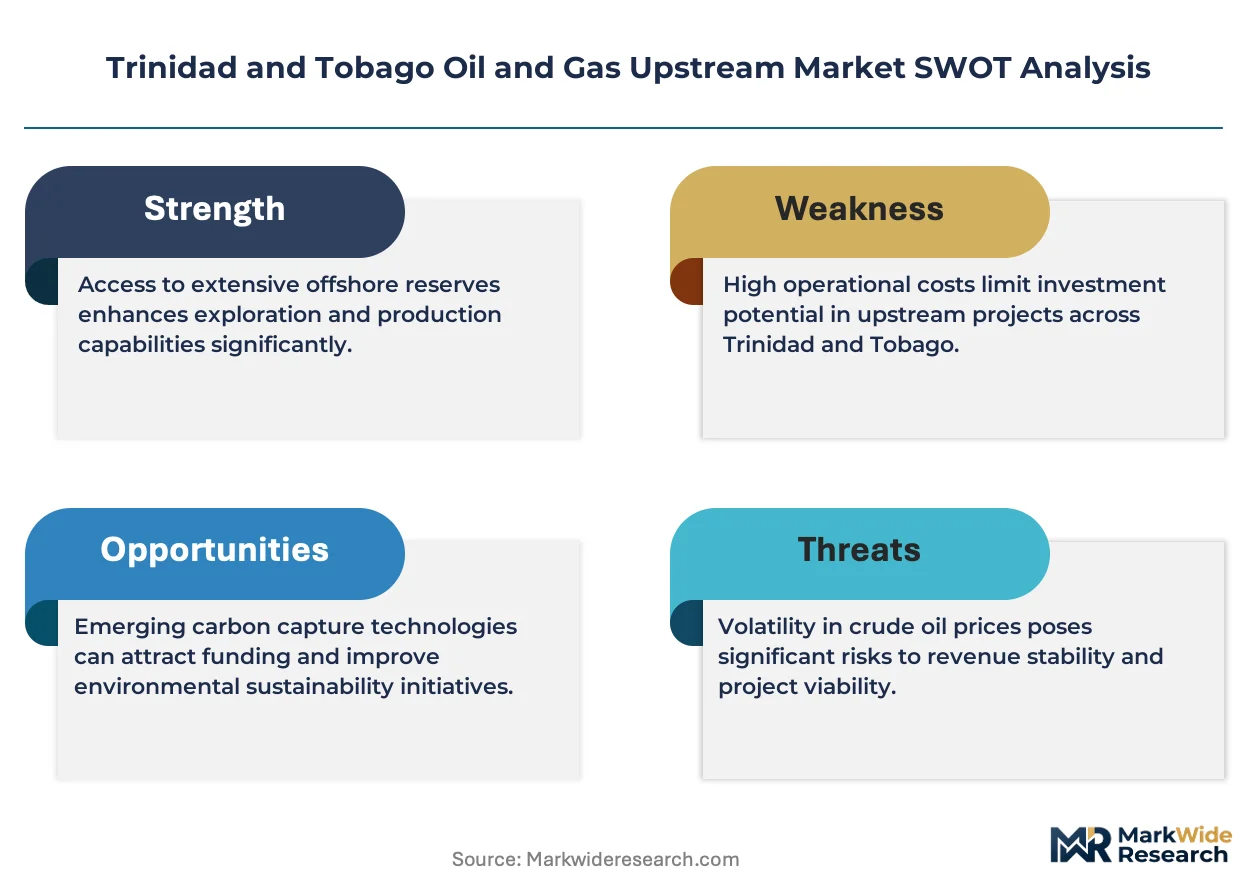
The Environmental Management Authority's offshore environmental impact assessment regime gates both drilling permit timelines and contractor qualification tiers, compressing margins for operators unable to front-load compliance costs while allowing certified specialists to command premium dayrates. This regulatory filter concentrates pricing power among service firms with established environmental track records, reshaping procurement decisions across Atlantic LNG expansion timelines.
Pricing Analysis
Volume-discount tiering structures dominate long-term offtake negotiations, with Atlantic LNG trains and Point Lisas ammonia producers locking in 10-15 year commitments that compress per-unit pricing at scale. Price differentiation rests on local content certification levels and subsea technology performance tiers, with Ministry of Energy-mandated 60% national participation thresholds creating dual-rate structures for domestic versus international contractors. Cost compression in shallow-water drilling services is intensifying because mature East Coast Marine Area fields require deeper, higher-pressure interventions without commensurate reserve upside. Petrochemical buyers at Point Lisas exhibit the highest price sensitivity due to margin-thin methanol and ammonia conversion economics, while deepwater block operators show relative inelasticity given subsea tieback technology's field-life extension value.
Supply Chain Analysis
Extended lead times for high-specification jackup rigs and subsea trees constrain inventory flexibility, with Caribbean supply chain concentration amplifying procurement risk for operators racing Atlantic LNG expansion windows. Geographic supply concentration centers on the United States for drilling equipment, Singapore for subsea fabrication, and Trinidad and Tobago for domestic vessel and yard services. Raw material dependencies draw from specialized steel alloys for high-pressure wellheads, subsea umbilicals, and platform structural components. Single-source vulnerability runs through the limited pool of international subsea engineering contractors with high-pressure high-temperature expertise. Distribution runs through the Galeota Ridge pipeline corridor linking offshore production to Atlantic LNG trains and Point Lisas processing complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trinidad and Tobago's upstream market represents an early-cycle expansion story anchored by Atlantic LNG fourth-train development and deepwater block maturation under modernized production sharing terms. Subsea technology adoption and local content framework evolution create dual tailwinds for qualified entrants.
For Market Incumbents: Consolidate drilling service market share through acquisition of domestic rig operators struggling with jackup dayrate volatility, while deepening backward integration into subsea equipment maintenance to capture 2030-2035 decommissioning demand. The Environmental Management Authority's extended permit timelines threaten operators without established environmental compliance infrastructure; vertical integration into carbon capture retrofit services at Point Lisas offers defensive positioning against EU CBAM compliance requirements. For New Entrants and Emerging Players: Lead with subsea multiphase pumping deployment partnerships targeting Columbus Basin marginal fields below 500 million cubic feet of recoverable reserves, where seaboost units displace fixed-platform economics. The most penetrable white space sits in decommissioning services, where La Brea yard capacity gaps and first-generation platform removal timelines create specialist contracting demand. A go-to-market angle through University of Trinidad and Tobago petroleum engineering program partnerships builds local content qualification while accessing technical talent pipelines. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated majors seeking to monetize mature shallow-water portfolios amid 8-12% annual East Coast Marine Area decline rates. Long-term viability frames around 5-10 year subsea technology adoption curves and Atlantic LNG offtake commitment durations. Acquisition target archetypes include domestic seismic service consortia with deepwater block operator relationships and heavy-lift yard operators upgrading La Brea capabilities. The signal to watch is Venezuelan maritime boundary negotiation progress, which would reshape Caribbean supply geography through Dragon Field tieback economics.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Technology Partnership | BP and Shell seaboost deployments at 1,200-meter depths extend field life without fixed-platform capital intensity. |
| Local Content Consortium Formation | Deepwater block operators partner with domestic service firms to meet Ministry of Energy 60% national participation thresholds. |
| Carbon Capture Retrofit Program | Point Lisas methanol and ammonia trains position for EU CBAM-compliant blue ammonia export demand. |
| Decommissioning Capability Buildout | La Brea yards upgrade heavy-lift infrastructure for 2030-2035 first-generation platform removal campaigns. |
| Cross-Border Pipeline Interconnectivity | Venezuelan Dragon Field tiebacks would reshape Caribbean gas supply geography through Trinidad infrastructure access. |
Research Methodology
Initial hypotheses were tested against primary input from offshore project engineers, Ministry of Energy licensing officials, petrochemical procurement managers at Point Lisas, and subsea technology specialists, then refined through secondary validation across customs and trade data, SEC filings from listed operators, Environmental Management Authority permit databases, and Caribbean energy infrastructure project tracking. Bottom-up field-level production estimates and top-down macroeconomic demand projections were triangulated to anchor volume forecasts.
Variance decomposition across product type, technology deployment, end-user concentration, and service category dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level production trajectories weighted by Atlantic LNG offtake commitment timelines and deepwater block licensing pace. Forecast inputs incorporated subsea technology breakeven thresholds, local content procurement mandates, and petrochemical feedstock contract duration patterns.
Forecasts assume regulatory continuity in Environmental Management Authority offshore assessment protocols and Ministry of Energy production sharing contract terms; material policy shifts around carbon intensity thresholds or local content percentage adjustments would require re-modeling. Commodity price volatility, jackup rig availability constraints, and Venezuelan geopolitical developments represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Middle East Wireline Logging Services Market