
 Oil and Gas Industry Turbomachinery Market | 2026-2036
Oil and Gas Industry Turbomachinery Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Industry Turbomachinery Market Analytics
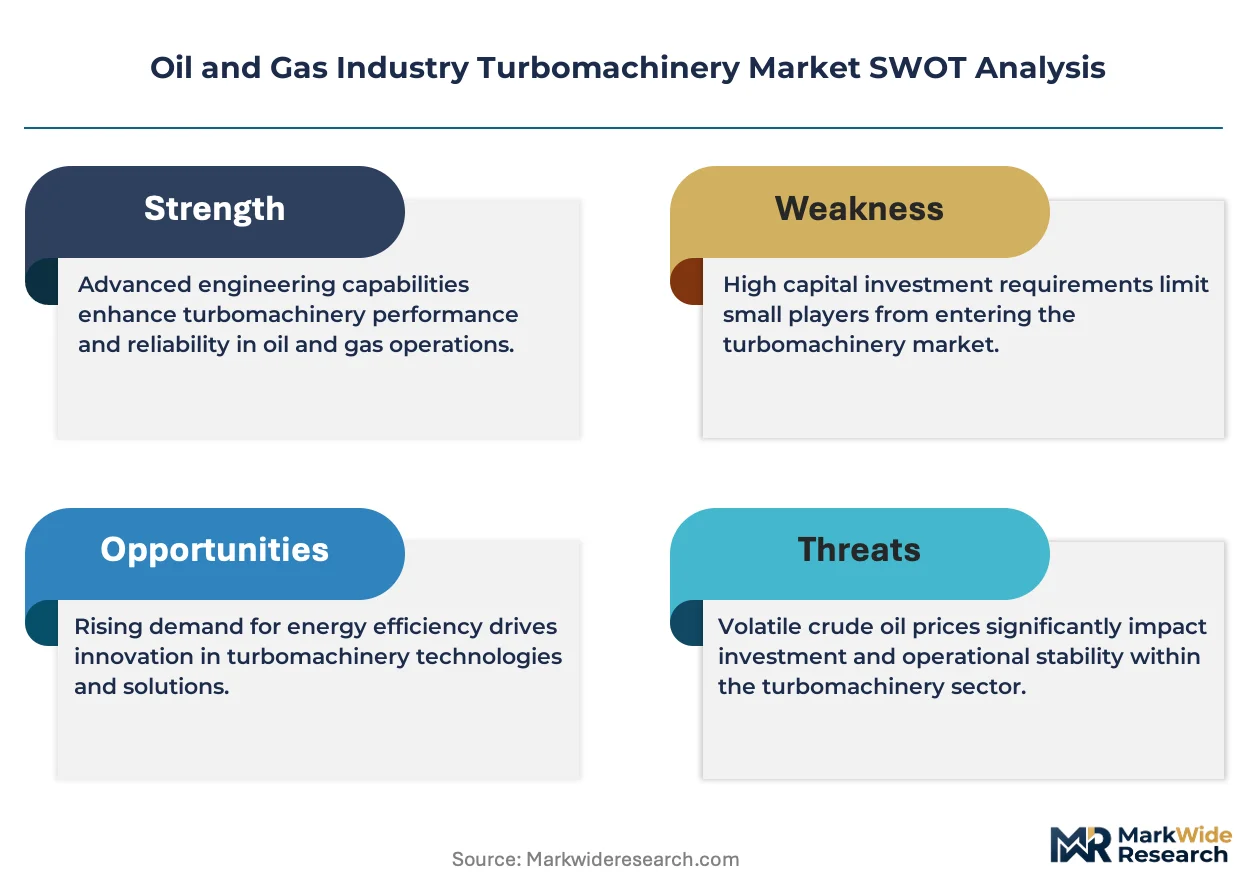
Multi-sourced procurement of high-horsepower turbomachinery is expanding as operators diversify vendor relationships to mitigate supply-chain risk. General Electric anchors its position through in-house casting and machining capabilities for heavy-frame gas turbines. Siemens competes with modular turbine-generator packages optimized for floating LNG applications. Baker Hughes differentiates via integrated compressor-permanent magnet motor systems that reduce footprint on offshore platforms.
Oil and gas industry turbomachinery encompasses rotating equipment—centrifugal and axial compressors, gas and steam turbines, expanders, and pumps—engineered to process hydrocarbons at pressures exceeding 100 bar and temperatures above 450°C, primarily for gas transmission, liquefaction, refining, and reservoir pressure maintenance. The compressor segment dominates installed base value due to continuous demand for gas lift and pipeline boosting across upstream and midstream operations. Gas turbine technology leads in power generation applications within refining and LNG trains, while centrifugal compressor configurations command premium pricing in subsea and Arctic deployments where reliability requirements are most severe.
EPA New Source Performance Standards and API 617/672 specifications shape equipment design mandates, compelling manufacturers to engineer lower-emission seals and variable-speed drive compatibility. OSHA Process Safety Management and BSEE well control regulations enforce integrity management protocols that extend replacement cycles and intensify aftermarket service attachment. Stakeholders must weigh capital deployment between brownfield reliability upgrades and greenfield electrification architectures as grid-connected turbomachinery gains traction.
Market Dynamics
EPA methane regulations and API 617 standards are compressing equipment replacement cycles while LNG export terminal construction in the United States pulls high-horsepower centrifugal compressors and gas turbines into multi-year procurement queues.
Growth Catalysts
- EPA New Source Performance Standards:The tightened methane emission limits force compressor seal retrofits and variable-speed drive installations across Permian Basin gathering systems, sustaining aftermarket demand.
- Floating LNG modularization:Offshore liquefaction projects favor skid-mounted turbine-generator packages that cut field construction time and labor exposure.
- Reservoir pressure maintenance:Mature fields in the Gulf Coast corridor deploy gas lift compressors to sustain production decline curves, locking in continuous equipment utilization.
Market Restraints
- Specialized alloy supply concentration:Superalloy forgings for high-temperature turbine blades concentrate among a handful of European and Japanese suppliers, creating single-source vulnerability.
- API 617 8th edition compliance costs:The updated lateral rotor dynamics and seal testing requirements extend engineering cycles and qualification expenses for new compressor designs.
- Electrification substitution:Grid-connected permanent magnet motor drives displace mechanical drive gas turbines in onshore processing where power infrastructure exists.
Strategic Opportunities
- Subsea compression white space:Wet gas compressor installations on the Norwegian continental shelf and offshore Brazil create demand for all-electric subsea systems rated beyond 10 MW.
- Arctic LNG deployment:Cryogenic-rated gas turbines and expanders for Russia's Yamal and Gydan peninsula projects require cold-start capabilities to minus 52°C.
- Carbon capture integration:Amine-based post-combustion capture retrofits on refinery fired heaters need auxiliary compression trains for CO2 dehydration and pipeline injection.
Industry Challenges
- Rotordynamics specialist scarcity:API 617 lateral critical speed analysis and torsional vibration modeling require engineering talent pools concentrated among aging consultants and OEM engineering centers.
- Legacy control system integration:Digital turbine control retrofits onto 1980s-era mechanical-hydraulic governors demand custom protocol bridges and cybersecurity hardening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Industry Turbomachinery Market |
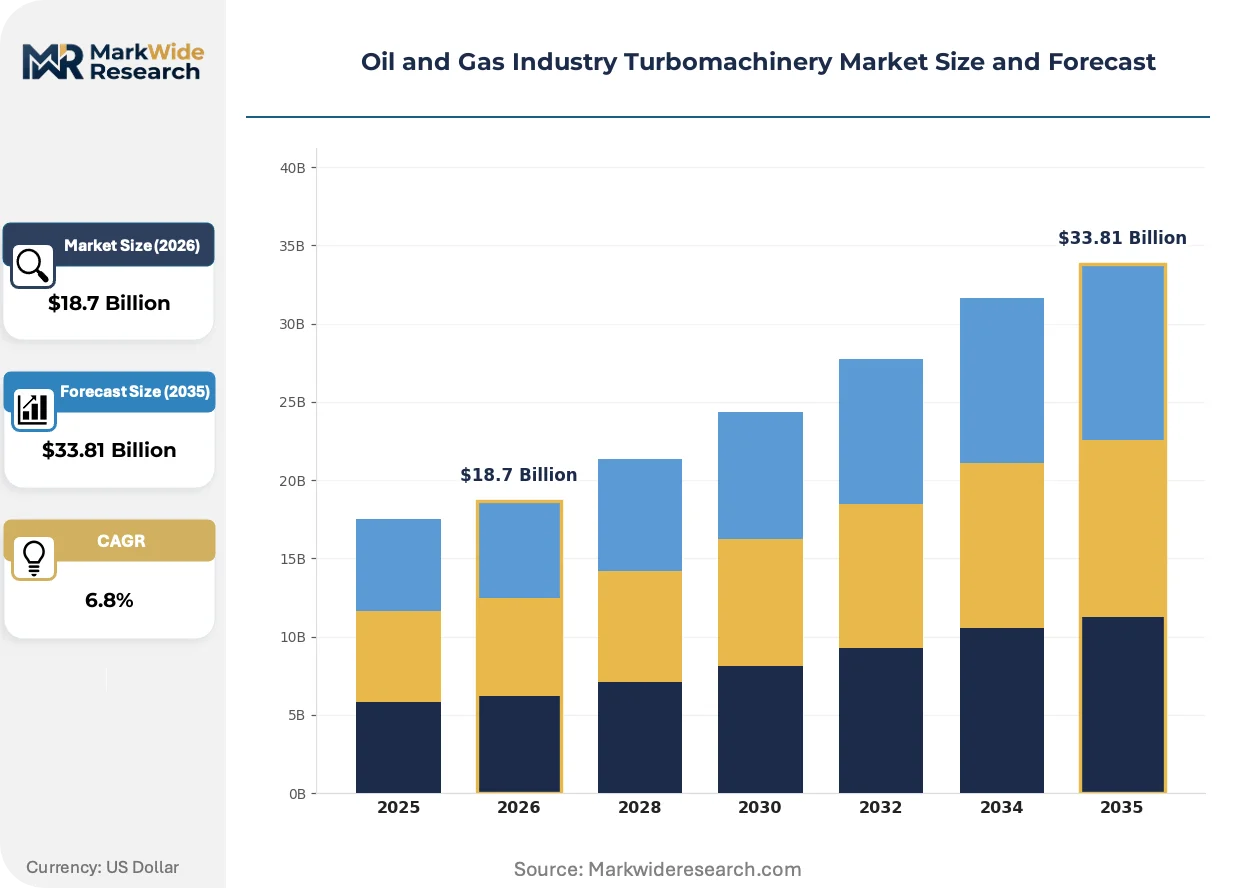
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressor, Turbine, Pump, Expander Technology: Gas Turbine, Steam Turbine, Reciprocating Compressor, Centrifugal Compressor Application: Upstream, Midstream, Downstream, Refining End User: Exploration Companies, Production Facilities, Service Providers, Pipeline Operators |
| Companies Covered | Atlas Copco, MAN Energy Solutions, General Electric, Elliott Group, Caterpillar Inc., Siemens, Sulzer, Mitsubishi Heavy Industries, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Industry Turbomachinery Market Evolving Landscape
Additive manufacturing of nickel superalloy turbine blades is collapsing lead times for spare rotating components while magnetic bearing technology eliminates lube oil systems from high-speed compressor trains.
Digital twin implementations for centrifugal compressors combine physics-based rotor models with real-time vibration telemetry from casing-mounted accelerometers. LNG train operators in Qatar and Australia deploy these systems to shift from time-based overhauls to condition-directed maintenance. The technology is rewriting service contract structures by unbundling parts, labor, and predictive analytics into separately priced modules.
EPA's supplemental methane proposal extends emission monitoring requirements to existing compressor stations beyond new source thresholds. Pipeline operators face retrofit deadlines for continuous methane monitoring and pneumatic device replacements. Midstream assets in the Appalachian and Permian basins absorb the bulk of compliance capital, with some operators accelerating electrification of compressor drives to eliminate pneumatic methane venting entirely.
Integrated turbomachinery packages now bundle compressor, motor, variable frequency drive, and auxiliaries onto single skids with unified control architecture. EPC contractors for U.S. Gulf Coast LNG projects favor these configurations to reduce field wiring and commissioning duration. The shift compresses vendor accountability into fewer interface points while raising barriers for component specialists lacking package integration capabilities.
Oil and Gas Industry Turbomachinery Market Segmentation
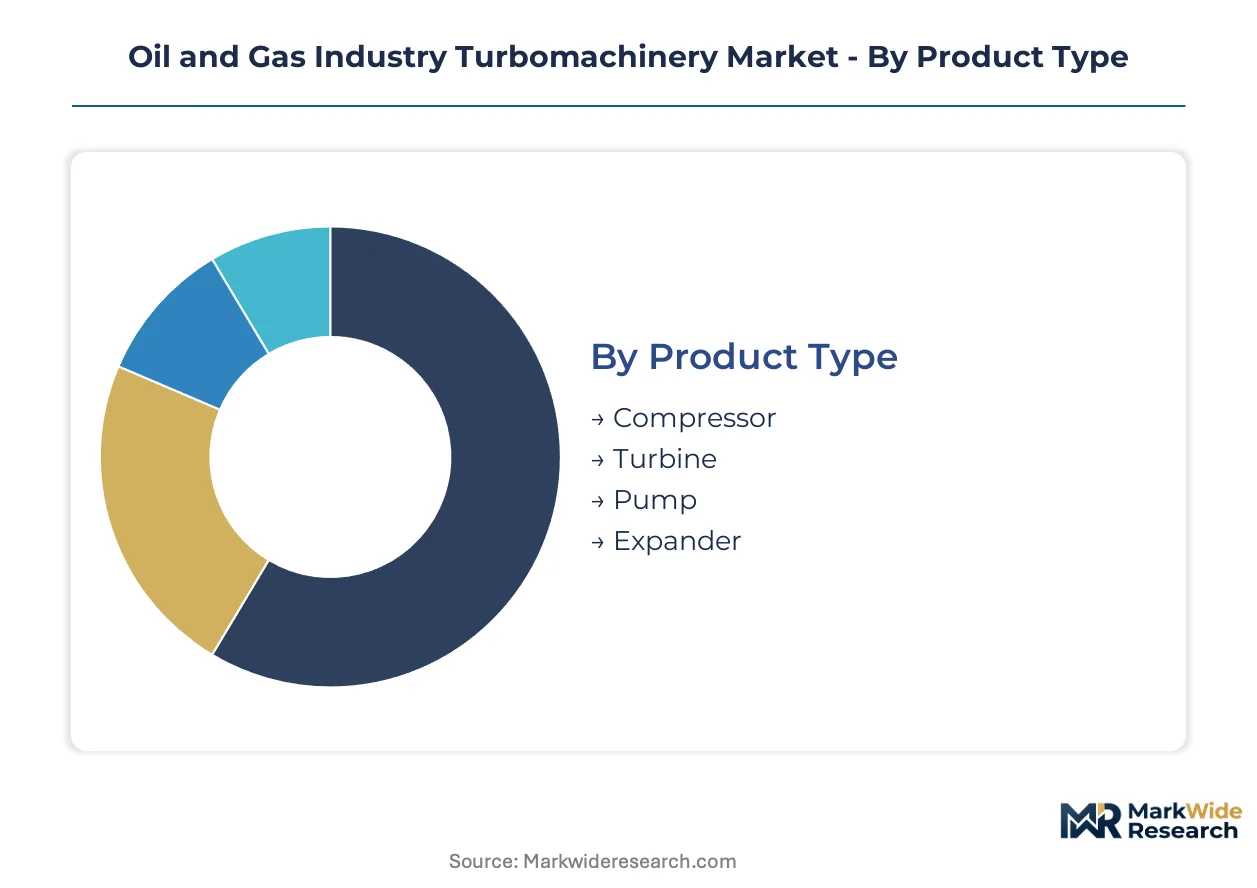
Turbomachinery procurement patterns diverge sharply across operational contexts, with compression intensity, power density requirements, and emission constraints dictating equipment selection. Segment boundaries reflect distinct engineering specifications, maintenance protocols, and capital deployment cycles that shape vendor engagement models.
Product Type:
Equipment classification centers on thermodynamic function and rotating assembly architecture, with each category commanding distinct spare parts ecosystems and service attachment rates.
- Compressor:Centrifugal and axial configurations dominate installed base value through continuous-duty gas lift and pipeline boosting applications. Permian Basin gathering systems and Gulf Coast LNG export terminals sustain replacement demand for high-horsepower units rated above 10 MW.
- Turbine:Heavy-frame gas turbines anchor power generation within refining complexes and liquefaction trains, with EPA methane regulations accelerating seal retrofits and control system upgrades across existing installations.
- Pump:Multistage centrifugal pumps handle crude oil transfer and injection services, with subsea boosting systems gaining traction in deepwater Brazil and West Africa developments.
- Expander:Cryogenic turboexpanders recover energy from natural gas pressure letdown in LNG peak-shaving facilities and NGL extraction plants.
Compressor leads on scale; turbine leads on momentum.
Technology:
Prime mover and compression mechanism selection hinges on pressure ratio requirements, available energy source, and footprint constraints across onshore and offshore deployments.
- Gas Turbine:Mechanical-drive configurations power compressors in remote locations lacking grid infrastructure, though electrification substitution threatens market share in Permian Basin processing facilities with pipeline power access.
- Steam Turbine:Cogeneration applications in refining and petrochemical complexes leverage waste heat recovery, with API 612 compliance driving rotor dynamics investments for high-speed units.
- Reciprocating Compressor:Positive displacement technology serves high-pressure injection and small-scale gathering where centrifugal efficiency thresholds are uneconomic.
- Centrifugal Compressor:API 617 8th edition compliance extends engineering cycles for new designs, with wet gas compression emerging as a subsea differentiator on the Norwegian continental shelf.
Centrifugal compressor commands the largest installed base; wet gas subsea variants are climbing the fastest.
Application:
Operational stage determines duty cycle severity, environmental exposure, and regulatory jurisdiction governing equipment specification.
- Upstream:Gas lift compression and artificial lift systems sustain production decline curves in mature Gulf Coast fields, with EPA New Source Performance Standards forcing pneumatic device replacements.
- Midstream:Pipeline boosting and storage injection services concentrate procurement in Appalachian and Permian basin corridors, where electrification of compressor drives eliminates methane venting from pneumatic controllers.
- Downstream:LNG liquefaction trains pull high-horsepower turbomachinery into multi-year procurement queues, with modular floating applications favoring skid-mounted packages.
- Refining:Fluid catalytic cracking air blowers and hydrocracker hydrogen recycle compressors operate under OSHA Process Safety Management integrity protocols that extend replacement cycles.
Midstream absorbs the highest unit volume; downstream liquefaction shows the steepest expansion trajectory.
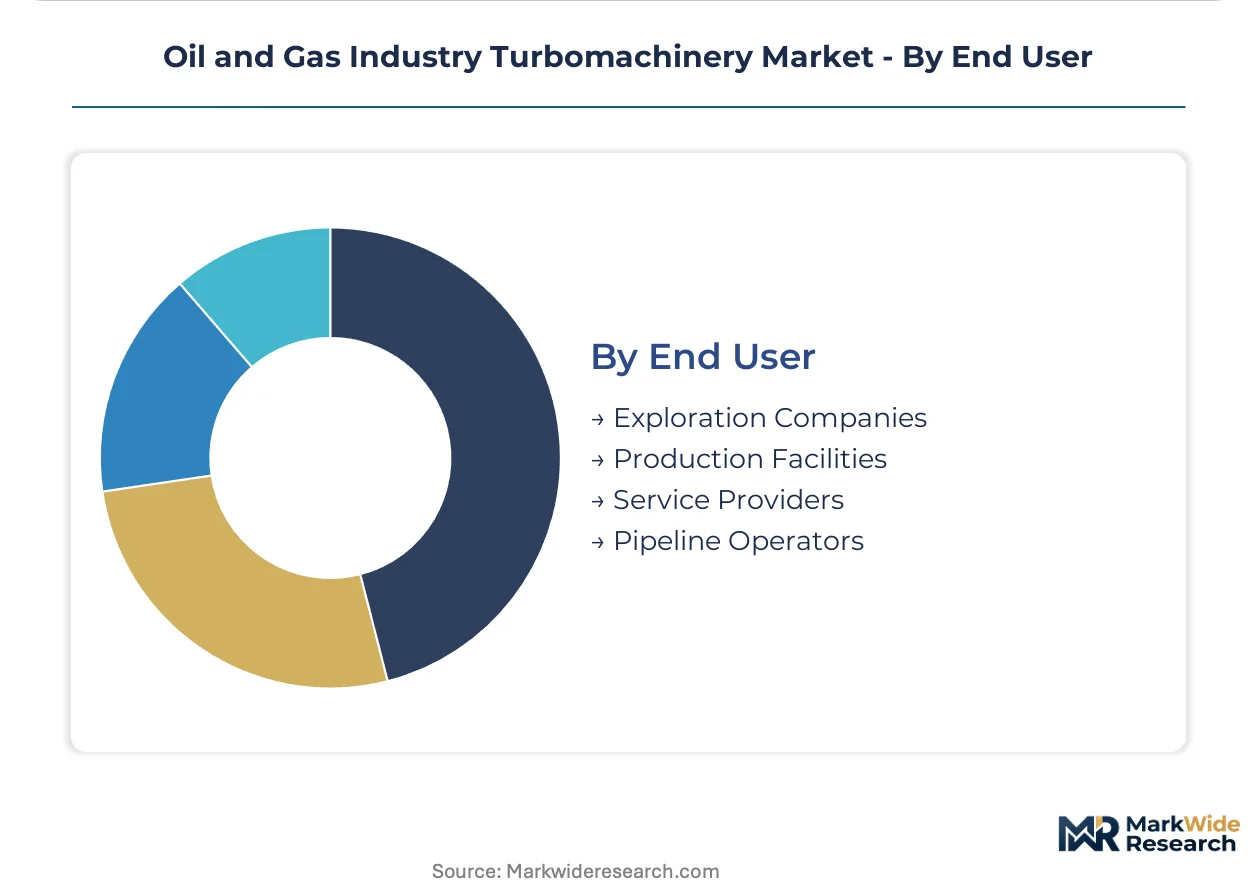
End User:
Procurement authority and lifecycle cost accountability vary across organizational models, influencing contract structures from equipment-only to full-wrap EPC arrangements.
- Exploration Companies:Capital discipline favors leased compression and power generation equipment, limiting owned turbomachinery exposure to core production assets.
- Production Facilities:Operating companies prioritize reliability-centered maintenance programs, with digital twin implementations shifting from time-based overhauls to condition-directed service.
- Service Providers:Rental compression fleets and contract compression operators aggregate demand across multiple upstream clients, capturing scale advantages in maintenance and spare parts inventory.
- Pipeline Operators:FERC-regulated interstate pipelines face EPA methane monitoring mandates for existing compressor stations, driving retrofit capital toward continuous emission monitoring and electrification.
Pipeline operators lead on replacement-driven demand; service providers lead on fleet expansion velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast corridor anchors turbomachinery procurement intensity, with LNG export terminals and Permian Basin gathering systems sustaining multi-year equipment queues across compressor and gas turbine categories.
United States
EPA New Source Performance Standards force methane seal retrofits and pneumatic device replacements across Appalachian and Permian Basin compressor stations. FERC-regulated interstate pipelines face continuous emission monitoring mandates that redirect capital toward electrification of compressor drives. The Gulf Coast LNG corridor from Corpus Christi to Lake Charles concentrates liquefaction train construction pulling high-horsepower turbomachinery into extended procurement cycles.
Norway
Wet gas compression installations on the Norwegian continental shelf drive demand for all-electric subsea systems rated beyond 10 MW in deepwater developments. The country's petroleum regulator enforces integrity management protocols that extend replacement cycles and intensify aftermarket service requirements. Equinor-operated fields in the North Sea and Barents Sea anchor subsea compression deployment velocity.
Qatar
North Field expansion projects sustain procurement of cryogenic-rated gas turbines and expanders for mega-train liquefaction capacity additions. The national energy company's localization requirements shape vendor qualification and joint venture structures for equipment supply. Ras Laffan Industrial City concentrates fabrication and commissioning activity for LNG train turbomachinery packages.
Brazil
Pre-salt deepwater developments deploy subsea boosting systems and multistage centrifugal pumps for crude oil transfer from seabed to floating production units. ANP regulatory frameworks mandate equipment certification standards that extend qualification timelines for imported turbomachinery. The Santos Basin cluster anchors demand for high-reliability rotating equipment in ultra-deepwater conditions.
Saudi Arabia
Master Gas System expansion and unconventional gas development sustain demand for centrifugal compressors in gas gathering and processing infrastructure. The national oil company's in-country value program localizes manufacturing and service capabilities for rotating equipment. The Eastern Province industrial corridor around Jubail concentrates gas processing and power generation turbomachinery deployment.
Oil and Gas Industry Turbomachinery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modularization and digital service architectures to bypass capital-intensive manufacturing positions. The market structure concentrates around integrated OEMs with captive casting and machining capabilities, while specialized component suppliers occupy subordinate positions in rotor dynamics and control systems. Three archetypes dominate: heavy-frame turbine manufacturers with backward integration into superalloy supply, modular package integrators optimizing for floating LNG applications, and aftermarket service specialists unbundling predictive analytics from traditional maintenance contracts. Competitive intensity centers on vertical integration depth and digital twin deployment velocity rather than price-based positioning.
Within the integrated OEM tier, General Electric, Siemens, and Baker Hughes exemplify divergent strategic postures. General Electric anchors its position through in-house casting and machining capabilities for heavy-frame gas turbines. Siemens occupies a position emphasizing modular turbine-generator packages optimized for floating LNG applications. Baker Hughes represents the integrated compressor-permanent magnet motor system archetype that reduces footprint on offshore platforms. These three companies collectively illustrate how vendor accountability compression into fewer interface points raises barriers for component specialists lacking package integration capabilities.
| Leading Market Players |
|---|
| Atlas Copco |
| MAN Energy Solutions |
| General Electric |
| Elliott Group |
| Caterpillar Inc. |
| Siemens |
| Sulzer |
| Mitsubishi Heavy Industries |
| Baker Hughes |
| Others |
Value Network & Pricing Analysis
Nickel superalloy ingot prices on the London Metal Exchange cascade through three distinct equipment pricing tiers, with API 617-certified compressor trains commanding substantial premiums over standard industrial units while foundry capacity constraints in Europe and Japan amplify volatility for project-based quotations.
Pricing Analysis
Input-cost pass-through from superalloy forgings and precision casting operations dominates pricing structures, with manufacturers indexing long-term offtake contracts to nickel and cobalt benchmark movements. Price differentiation separates API 617 8th edition-compliant systems from legacy API 614 packages through rotor dynamics certification and seal testing documentation. Cost compression in standard-duty centrifugal compressors is intensifying because electrification substitution erodes mechanical-drive gas turbine attach rates. Exploration companies leasing compression fleets exhibit highest price sensitivity, while national oil companies with in-country value mandates absorb premiums for localized manufacturing and service infrastructure.
Supply Chain Analysis
API 617 and API 672 qualification protocols gate entry for forged rotors, superalloy castings, and magnetic bearing systems, compressing the supplier base to OEMs with captive metallurgical laboratories and witnessed testing facilities. Manufacturing concentrates in the United States, Germany, and Japan for heavy-frame gas turbines, while South Korea and China dominate auxiliary components and variable frequency drive production. Superalloy supply draws from a handful of European and Japanese specialty foundries, creating single-source vulnerability for high-temperature turbine blades. Distribution runs through EPC contractors and direct OEM relationships for integrated packages, with aftermarket parts flowing through authorized service centers and regional stocking locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oil and gas turbomachinery market represents a late-cycle quality story, with EPA methane regulations and API 617 8th edition standards redirecting procurement toward premium-specification equipment with documented emissions performance and enhanced rotor dynamics.
For Market Incumbents: Acquire rotordynamics engineering talent pools and API 617 certification capabilities to consolidate positions before electrification substitution accelerates in Permian Basin processing facilities. Defensive moves center on backward integration into superalloy casting operations to secure blade supply and on digital twin deployment to capture condition-directed maintenance contracts from reliability-centered operators. Electrification of compressor drives poses the central threat to mechanical-drive gas turbine market share. For New Entrants and Emerging Players: EPA methane regulations in the United States open a window for continuous emission monitoring system providers and electrification retrofit specialists serving FERC-regulated interstate pipelines. White-space targets include subsea wet gas compression for Norwegian and Brazilian deepwater developments and modular skid-mounted packages for floating LNG applications. The most penetrable segment is aftermarket control system retrofits for 1980s-era mechanical-hydraulic governors, approached through cybersecurity-hardened protocol bridge solutions. For Investors and Strategic Acquirers: Asymmetric upside sits with aftermarket service specialists possessing predictive analytics capabilities and magnetic bearing technology portfolios. Long-term viability favors asset-light digital service providers over capital-intensive foundry operations, with acquisition targets centering on firms unbundling predictive maintenance from traditional parts-and-labor contracts. The signal to watch is LNG project final investment decision velocity in the Gulf Coast corridor as an inflection indicator for high-horsepower equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | Secures blade supply for API 617-compliant gas turbines against European foundry concentration. |
| Digital Twin Deployment for Condition-Directed Maintenance | Rewrites service contract structures for centrifugal compressors in Qatar and Australia LNG trains. |
| Electrification Retrofit for Compressor Drives | Eliminates pneumatic methane venting under EPA New Source Performance Standards across Permian Basin. |
| Modular Skid-Mounted Package Integration | Reduces field construction time for floating LNG projects favored by EPC contractors. |
| Magnetic Bearing Technology Adoption | Eliminates lube oil systems from high-speed compressor trains in subsea and Arctic deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with turbomachinery procurement managers at national oil companies, EPC contractor engineering directors, aftermarket service heads at major OEMs, and plant reliability engineers at Gulf Coast refineries with secondary validation against API 617/672 specification documents, EPA regulatory filings, FERC infrastructure dockets, and customs trade data for superalloy imports. Bottom-up equipment shipment tallies and top-down energy infrastructure investment flows were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through documented replacement cycles, LNG train construction timelines, and regulatory compliance deadlines across the analysis window. The analytical framework modeled segmentation dimensions spanning product type, thermodynamic technology, operational application, and end-user procurement authority, with CAGRs derived from equipment unit economics and installed base depreciation curves. Forecast inputs incorporated EPA methane rule implementation schedules, floating LNG project development pipelines, and electrification substitution rates in grid-accessible processing regions.
Revisions become necessary when EPA regulatory timelines shift, superalloy supply disruptions materialize, or LNG export terminal construction accelerates beyond contracted equipment capacity. Forecasts reflect documented assumptions regarding replacement cycle extension, aftermarket service attachment rates, and modular package adoption velocity. A model refresh is warranted upon material change in electrification infrastructure deployment across the Permian Basin and Gulf Coast corridor.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Intelligent Well Completion Market