
 Southeast Asia Oil and Gas Market | 2026-2036
Southeast Asia Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Oil and Gas Market Analytics
Carbon steel is hardening its position as the dominant material for subsea pipeline infrastructure across Southeast Asian offshore fields, replacing corrosion-prone grades in deepwater developments. PETRONAS leverages integrated upstream-to-downstream operations across Malaysia's Sarawak and Sabah basins. Shell Plc anchors its regional portfolio through floating LNG and deepwater exploration in Malaysian and Brunei waters. TotalEnergies SE differentiates via ultra-deepwater projects in Myanmar and Indonesia.
Southeast Asia oil and gas encompasses the exploration, production, refining, and distribution of hydrocarbon resources including crude oil with API gravities ranging from light sweet to heavy sour, natural gas in conventional and unconventional reservoirs, liquefied natural gas processed to minus 162 degrees Celsius for marine transport, and refined products such as gasoline, diesel, and jet fuel. The primary purpose is to supply energy for power generation, industrial process heat, residential heating and cooking, and transportation fuels across the region's emerging economies. Crude oil and natural gas segments dominate current revenue, while LNG infrastructure is expanding fastest as Thailand and Singapore build import terminals. The service type dimension shows production and refining capturing the deepest margin pools, though exploration activity is reviving in frontier basins off Indonesia and Vietnam.
Indonesia's Ministry of Energy and Mineral Resources enforces domestic market obligation regulations that reserve portions of natural gas output for local buyers, reshaping contract structures and export availability. Thailand's Department of Mineral Fuels and Vietnam's Ministry of Industry and Trade administer production-sharing contract frameworks that determine how international operators access offshore blocks and recover costs. Malaysia's PETRONAS governs licensing through its Petroleum Management Unit, setting local content requirements that influence contractor selection and supply chain formation. Stakeholders must weigh regulatory stability against reserve depletion timelines when committing capital to multibillion-dollar developments spanning politically diverse jurisdictions.
Market Dynamics
Indonesia's domestic market obligation policy is forcing gas contract restructuring across Southeast Asian upstream portfolios, redirecting supply flows toward Java-Bali industrial corridors and compressing export arbitrage windows for legacy LNG commitments.
Growth Catalysts
- Floating LNG Infrastructure:Malaysia's PETRONAS and Brunei's energy ministry are sanctioning floating liquefaction vessels for stranded deepwater gas fields, unlocking reserves previously classified as commercially stranded.
- Domestic Market Obligation Enforcement:Indonesia's Ministry of Energy and Mineral Resources mandates gas reservation quotas for fertilizer, petrochemical, and power generation offtakers, anchoring local demand absorption.
- Carbon Steel Pipeline Deployment:Deepwater developments off Vietnam and Myanmar are specifying corrosion-resistant carbon steel grades for subsea flowlines, extending field life in high-pressure, high-temperature reservoirs.
Market Restraints
- Capital Intensity of Ultra-Deepwater Projects:Front-end engineering and design costs for Myanmar and Indonesian pre-salt analogs require multi-billion-dollar commitments before reserve certification.
- Regulatory Fragmentation Across ASEAN:Thailand's production-sharing contract terms diverge from Vietnam's tax-and-royalty frameworks, forcing operators to maintain parallel compliance architectures.
- Geographic Supply Concentration:Malaysia's Sarawak and Sabah basins host disproportionate regional LNG export capacity, creating single-source dependency for Japanese and Korean term buyers.
Strategic Opportunities
- Myanmar Frontier Exploration:Ultra-deepwater blocks in the Rakhine Basin remain underpenetrated relative to Indonesian and Vietnamese mature provinces, offering first-mover reserve replacement.
- CCUS Integration with Gas Processing:Singapore's carbon tax regime and Indonesia's planned carbon capture mandates are creating offtake markets for depleted reservoir sequestration.
- Small-Scale LNG Distribution:Islanded industrial zones in the Philippines and eastern Indonesia lack pipeline connectivity, opening bunkering and virtual pipeline service models.
Industry Challenges
- Subsea Engineering Talent Scarcity:Vietnam and Myanmar lack sufficient reservoir simulation and flow assurance specialists to staff planned deepwater developments.
- Legacy Infrastructure Integration:Brownfield tiebacks in Malaysia's mature basins require retrofitting digital twin architectures onto 1980s-vintage platform control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Oil and Gas Market |
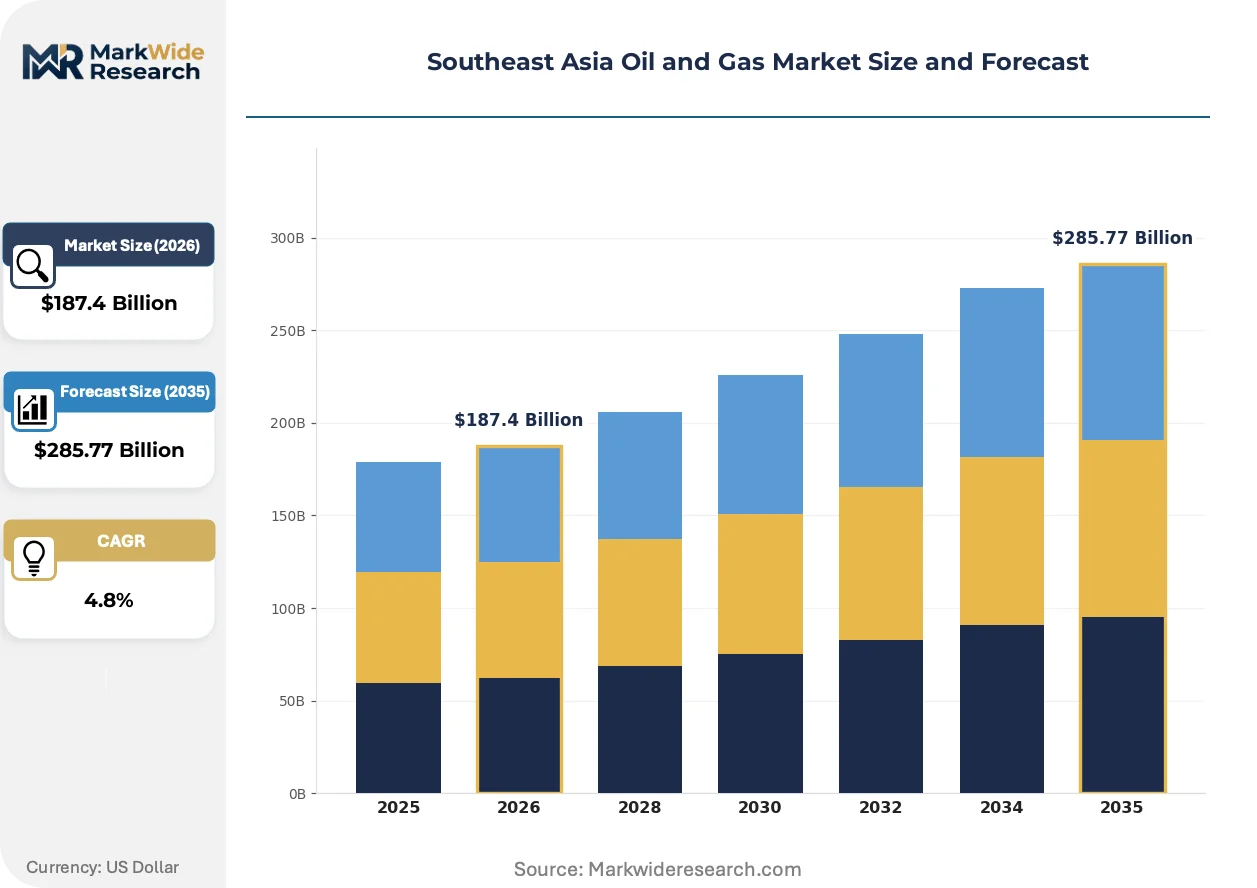
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crude Oil, Natural Gas, LNG, Refined Products Application: Power Generation, Industrial, Residential, Transportation Service Type: Exploration, Production, Refining, Distribution End User: Utilities, OEMs, Contractors, Retailers |
| Companies Covered | PetroVietnam, TotalEnergies SE, Petroliam Nasional Berhad (PETRONAS), Eni SpA, Chevron Corporation, PT Pertamina, Shell Plc, PNOC (Philippine National Oil Company), PTT Public Company Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Oil and Gas Market Evolving Landscape
Digital reservoir characterization and modular liquefaction architectures are compressing development timelines for marginal gas discoveries across Southeast Asian frontier basins. These shifts are redrawing competitive boundaries between integrated national oil companies and international operators.
Carbon steel grades with enhanced corrosion resistance are overtaking duplex stainless specifications for subsea pipeline networks in the South China Sea. Indonesian and Vietnamese offshore project teams are specifying these materials for water depths exceeding 1,500 meters. The substitution is compressing fabrication lead times and reducing import dependency on European specialty steel mills.
Thailand's Department of Mineral Fuels has tightened local content requirements for production-sharing contract extensions, mandating domestic engineering procurement and construction participation. International operators must now joint-venture with Thai fabrication yards for platform topsides. The policy is forcing supply chain reconfiguration for Malaysian contractors who previously centralized fabrication in Johor.
Power generation utilities in Vietnam's southern economic zone are compressing gas procurement contract durations, shifting from twenty-year term agreements to five-year baseload with spot-indexed supplements. This behavioral pivot reflects coal displacement urgency and LNG import terminal commissioning schedules. The pattern is most pronounced in Ba Ria-Vung Tau province, where new combined-cycle capacity is coming online ahead of pipeline infrastructure.
Southeast Asia Oil and Gas Market Segmentation
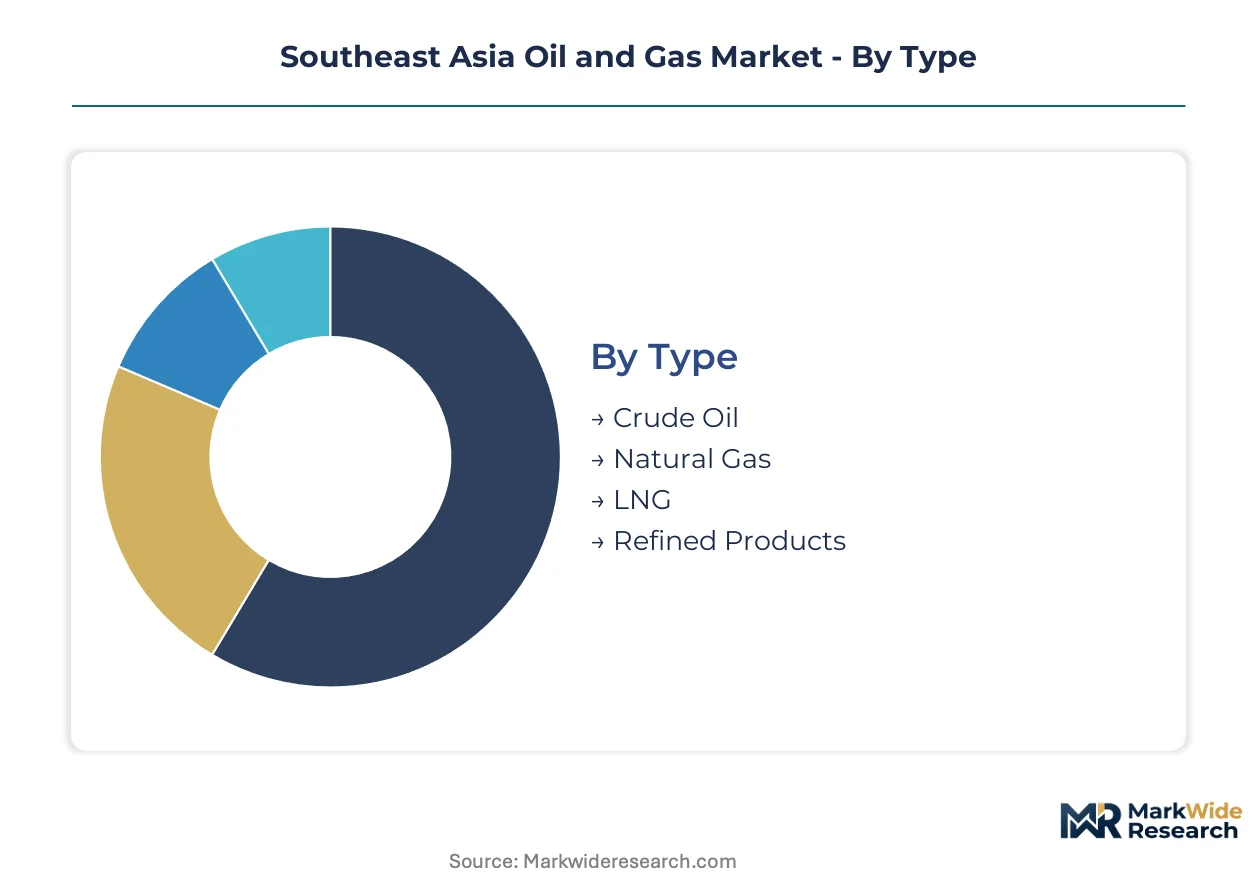
Segmentation reveals how capital allocation and regulatory exposure diverge across Southeast Asian hydrocarbon value chains. Each dimension—type, application, service, and end user—carries distinct margin profiles and policy sensitivities that reshape portfolio construction for operators and investors.
Type:
Cost tier differentiation separates premium-priced LNG from commoditized crude streams in Southeast Asian trading corridors.
- Crude Oil:API gravities span light sweet to heavy sour grades. Indonesian Duri crude and Vietnamese Bach Ho output anchor regional refinery feedstock demand, though declining mature basin production is tightening regional supply availability.
- Natural Gas:Conventional and unconventional reservoirs supply Java-Bali power corridors and Vietnam's southern industrial zone under Indonesia's domestic market obligation quotas. Pipeline infrastructure constraints concentrate offtake near production nodes.
- LNG:Liquefied natural gas processed to minus 162 degrees Celsius enables marine transport from Malaysian Sarawak terminals to Thai and Singapore import facilities. Floating liquefaction vessels are unlocking stranded deepwater fields off Brunei and East Malaysia.
- Refined Products:Gasoline, diesel, and jet fuel outputs from Singapore refining hub and Indonesian Cilacap complex serve transportation and aviation demand across ASEAN trade lanes.
Volume sits with crude oil and natural gas; growth tilts toward LNG as Thailand and Singapore commission new import terminals.
Application:
Customer maturity separates baseload power utilities from spot-responsive industrial offtakers in contract structuring.
- Power Generation:Gas-fired capacity expansion in Indonesia and Vietnam displaces coal baseload. Java-Bali corridor utilities anchor twenty-year term contracts, while Vietnam's southern economic zone operators compress durations to five-year baseload with spot-indexed supplements.
- Industrial:Fertilizer and petrochemical plants in Indonesia's domestic market obligation framework receive priority gas allocation. Thai manufacturing clusters demand flexible procurement terms responsive to export order cycles.
- Residential:LPG distribution networks serve cooking and heating demand across Philippine archipelago and eastern Indonesian islands lacking pipeline connectivity. Small-scale LNG bunkering is emerging as a virtual pipeline substitute.
- Transportation:Diesel and gasoline retail sales concentrate in urban corridors of Bangkok, Jakarta, and Ho Chi Minh City. Marine bunkering demand centers on Singapore Strait and Malacca Passage shipping lanes.
Power generation commands contract duration; industrial offtake is expanding most quickly as manufacturing capacity relocates to Vietnam and Indonesia.
Service Type:
Margin depth separates capital-intensive production from logistics-constrained distribution activities.
- Exploration:Frontier basin drilling in Myanmar's Rakhine Basin and Indonesian pre-salt analogs requires multi-billion-dollar front-end engineering commitments before reserve certification. International operators partner with national oil companies for block access.
- Production:Upstream operations across Malaysia's Sarawak and Sabah basins generate the deepest margin pools through integrated LNG export chains. Brownfield tiebacks in mature Malaysian fields require retrofitting digital architectures onto 1980s-vintage platform control systems.
- Refining:Singapore refining hub and Indonesian Cilacap complex process regional crude into specification products for ASEAN markets. Capacity expansion lags demand growth in Vietnam and Philippines.
- Distribution:Pipeline infrastructure constraints in Philippine and eastern Indonesian islanded zones create virtual pipeline opportunities through small-scale LNG bunkering and compressed natural gas trucking.
Production and refining capture margin depth; exploration is gaining share fastest as Indonesia and Vietnam revive frontier block licensing.
End User:
Procurement scale separates integrated utilities from fragmented contractor demand in supply chain configuration.
- Utilities:State-owned power generation companies in Indonesia, Vietnam, and Thailand negotiate term gas contracts under production-sharing contract frameworks. Thailand's Department of Mineral Fuels mandates domestic engineering procurement and construction participation for contract extensions.
- OEMs:Original equipment manufacturers for gas turbines and compression systems supply Indonesian and Vietnamese power plant developers. Local content requirements force joint-ventures with Thai and Malaysian fabrication yards.
- Contractors:Engineering procurement and construction firms execute platform topsides and subsea pipeline installations. Malaysia's PETRONAS Petroleum Management Unit sets contractor qualification standards that influence regional supply chain formation.
- Retailers:Fuel station networks and LPG distributors serve end-consumer demand across urban corridors and islanded communities. Singapore's carbon tax regime is reshaping procurement priorities for downstream marketing operations.
Contractor expenditure dominates capital deployment; utility demand is climbing the fastest as coal displacement accelerates across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Indonesia's Java-Bali corridor and Vietnam's southern economic zone, where gas-fired power capacity is displacing coal baseload. Malaysia's Sarawak and Sabah basins anchor regional LNG export infrastructure. Thailand and Singapore are commissioning new import terminals to absorb supply.
Indonesia
Java-Bali industrial corridors absorb domestic market obligation gas allocations for fertilizer and petrochemical feedstock. The Ministry of Energy and Mineral Resources enforces reservation quotas that redirect supply from export contracts toward local buyers. East Java's Gresik industrial cluster hosts expanding gas-fired power capacity ahead of pipeline infrastructure completion.
Vietnam
Ba Ria-Vung Tau province anchors gas demand from new combined-cycle plants displacing coal generation. The Ministry of Industry and Trade administers production-sharing contracts that determine international operator access to offshore blocks. The southern economic zone's industrial parks are compressing procurement contract durations from twenty-year terms to five-year baseload with spot-indexed supplements.
Malaysia
Sarawak and Sabah basins host disproportionate regional LNG export capacity serving Japanese and Korean term buyers. PETRONAS Petroleum Management Unit governs licensing and sets local content requirements influencing contractor selection. Bintulu's LNG complex remains the single largest liquefaction hub in Southeast Asia.
Thailand
Manufacturing clusters in the Eastern Economic Corridor demand flexible gas procurement terms responsive to export order cycles. The Department of Mineral Fuels mandates domestic engineering procurement and construction participation for production-sharing contract extensions. Rayong province's petrochemical complexes anchor industrial gas offtake.
Myanmar
Rakhine Basin ultra-deepwater blocks remain underpenetrated relative to mature Indonesian and Vietnamese provinces. The national energy ministry oversees frontier exploration licensing requiring multi-billion-dollar front-end engineering commitments. Offshore acreage offers first-mover reserve replacement for international operators partnering with national oil companies.
Southeast Asia Oil and Gas Market Competitive Landscape
Portfolio diversification dominates the current landscape as operators rebalance between LNG export chains and domestic market obligation supply. The market structures around integrated national oil companies, international majors with deepwater specialization, and regional state-owned enterprises with distribution networks. Three archetypes define positioning: upstream-integrated LNG exporters, deepwater frontier specialists, and domestic market obligation suppliers. Competitive moves center on floating liquefaction vessel deployment and carbon capture integration with gas processing infrastructure.
Among integrated national oil companies, Petroliam Nasional Berhad (PETRONAS) and PT Pertamina occupy positions spanning upstream production through LNG export and domestic distribution. Shell Plc and TotalEnergies SE exemplify the international major archetype with floating LNG and ultra-deepwater specialization. PetroVietnam represents the state-owned enterprise model with offshore production and downstream integration.
| Leading Market Players |
|---|
| PetroVietnam |
| TotalEnergies SE |
| Petroliam Nasional Berhad (PETRONAS) |
| Eni SpA |
| Chevron Corporation |
| PT Pertamina |
| Shell Plc |
| PNOC (Philippine National Oil Company) |
| PTT Public Company Limited |
| Others |
Value Network & Pricing Analysis
Subsea engineering talent scarcity in Vietnam and Myanmar compresses labor-cost differentials between premium-tier integrated service contracts and standard engineering procurement construction agreements. This workforce concentration widens pricing spreads as operators absorb premium rates for flow assurance specialists or accept extended lead times from lower-cost fabrication yards in Johor.
Pricing Analysis
Volume sits with commoditized crude term contracts while margins concentrate in LNG offtake agreements and ultra-deepwater production-sharing contracts. Price differentiation separates premium corrosion-resistant carbon steel specifications from standard pipeline grades, with certification to PETRONAS Petroleum Management Unit standards commanding material premiums. Cost compression in standard-tier engineering services is intensifying because Thai local content requirements force joint-venture structures that duplicate overhead. Industrial offtakers in Vietnam's southern economic zone exhibit highest price sensitivity through compressed five-year baseload terms, while Japanese and Korean LNG term buyers show lowest sensitivity due to energy security premiums.
Supply Chain Analysis
Reverse-logistics flows for subsea equipment refurbishment center on Singapore's marine service hubs, where retired platform components from Malaysia's mature Sarawak basins feed remanufacturing pipelines for redeployment in Indonesian frontier developments. Geographic supply concentration rests on Malaysia for LNG liquefaction infrastructure, Singapore for refining and technical services, and Indonesia for domestic market obligation gas allocation. Raw material dependencies draw from Japanese and Korean specialty steel mills for high-pressure pipeline grades and European licensors for floating liquefaction vessel technology. Single-source vulnerability runs through Malaysia's Bintulu LNG complex as the dominant regional export node. Distribution runs through term-contract LNG shipping lanes to Thai and Singapore import terminals, supplemented by spot-indexed cargoes for utility buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play as Indonesia's domestic market obligation enforcement forces smaller export-dependent operators into distressed asset sales or joint-venture absorption by integrated national oil companies.
For Market Incumbents: Deploy floating liquefaction vessel standardization as the primary lever to compress development timelines for stranded deepwater gas fields across Brunei and East Malaysia. Anchor position through backward integration into carbon steel pipeline fabrication via joint-ventures with Johor yards to satisfy Thai local content mandates. Counter the threat of contract duration compression by Vietnamese utilities through indexed pricing mechanisms that transfer commodity risk. For New Entrants and Emerging Players: Islanded industrial zones in the Philippine archipelago represent an underserved buyer archetype lacking pipeline connectivity and receptive to small-scale LNG bunkering solutions. Target Myanmar's Rakhine Basin ultra-deepwater blocks as the most penetrable geography given limited incumbent presence relative to mature Indonesian provinces. Pursue virtual pipeline service models with compressed natural gas trucking as the go-to-market angle for eastern Indonesian manufacturing clusters. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap engineering procurement construction specialists holding PETRONAS contractor qualifications given accelerating brownfield tieback demand across Malaysia's mature basins. Long-term viability favors operators with integrated LNG export chains and domestic market obligation supply flexibility across multiple ASEAN jurisdictions. Monitor Indonesia's Ministry of Energy and Mineral Resources enforcement patterns for domestic market obligation quota expansion as the signal indicating upstream portfolio restructuring intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Floating LNG Vessel Deployment | Unlocks stranded deepwater reserves off Brunei and East Malaysia previously classified as commercially unviable. |
| Carbon Steel Pipeline Standardization | Compresses fabrication lead times for Vietnamese and Myanmar deepwater developments while reducing European import dependency. |
| Domestic Market Obligation Compliance | Secures priority offtake allocation from Indonesia's Ministry of Energy and Mineral Resources for fertilizer and power feedstock. |
| CCUS Integration with Gas Processing | Captures carbon capture offtake markets under Singapore's carbon tax regime and Indonesia's planned reservoir sequestration mandates. |
| Small-Scale LNG Distribution Buildout | Addresses virtual pipeline gaps in Philippine and eastern Indonesian islanded zones lacking conventional infrastructure. |
Research Methodology
Multi-period observation of production-sharing contract award patterns, domestic market obligation quota allocations, and floating liquefaction vessel sanctioning timelines anchored the trend analysis, supplemented by interviews with upstream portfolio managers at integrated national oil companies, project development leads at international operators, procurement officers at Thai and Vietnamese utilities, and engineering directors at fabrication yards. Secondary validation drew from Indonesia's Ministry of Energy and Mineral Resources regulatory filings, Vietnam's Ministry of Industry and Trade licensing announcements, PETRONAS Petroleum Management Unit contractor qualification databases, and ASEAN customs trade data. Bottom-up field-level production estimates triangulated against top-down regional demand projections from power generation commissioning schedules.
Segment-weighting applied differential growth assumptions across crude oil, natural gas, LNG, and refined product categories, with additional modeling for service type dimensions spanning exploration, production, refining, and distribution. The analytical framework incorporated fuel source differentiation, project scale tiers, regulatory framework clusters, and regional grid interconnection status throughout the forecast period. CAGRs derived from regression analysis of historical capacity additions against announced project pipelines, with specific inputs for Indonesia's domestic market obligation enforcement intensity and Vietnam's coal displacement urgency metrics.
Revisions become necessary when regulatory enforcement patterns shift, frontier exploration licensing accelerates in Myanmar, or carbon capture mandates expand beyond Singapore's current regime. Forecasts reflect assumptions about continued domestic market obligation policy stability, floating liquefaction technology cost curves, and regional LNG shipping capacity availability. Practitioners should monitor Indonesia's Ministry of Energy and Mineral Resources quota announcements, Vietnamese utility procurement contract duration trends, and PETRONAS contractor qualification standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Oil Tank Rotating Stacker Market