
 Russia Oilfield Services Market | 2026-2036
Russia Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Oilfield Services Market Analysis
Western Siberia is rewriting the competitive map for Russian oilfield services as operators push into deeper, more complex reservoirs. NaftaGaz JSC leverages its captive drilling fleet to dominate onshore workover contracts in the Khanty-Mansiysk Autonomous Okrug. Eriell anchors its position through specialized horizontal drilling crews deployed across the Volga-Ural basin. SLB competes by controlling premium logging-while-drilling technology that remains difficult to substitute under current import substitution mandates.
Russia oilfield services encompass the technical execution of drilling, completion, workover, and production optimization activities across onshore and offshore hydrocarbon assets, typically involving bottomhole assembly design, mud weight management, and wellbore integrity protocols measured to API specification 5CT. Drilling Services generates the largest revenue pool due to sustained capital allocation toward greenfield development in Eastern Siberia, while Hydraulic Fracturing represents the fastest-expanding technology segment as operators apply multi-stage completion designs to low-permeability formations. National Oil Companies concentrate procurement authority through consolidated tender processes, though Independent Producers are gaining share by farming into legacy fields requiring workover-intensive redevelopment.
The Russian Ministry of Energy enforces equipment localization quotas that reshape supplier eligibility, while GOST standards and technical regulations of the Eurasian Economic Union dictate wellhead and Christmas tree certification requirements for market access. Rosneft-Burenie and Gazprom Bureniye LLC navigate these compliance layers through in-house manufacturing of drilling tools at Russian-based facilities. Stakeholders must monitor how sanctions architecture evolves against the trajectory of domestic substitutability for high-specification directional drilling systems.
Market Dynamics
The Russian Ministry of Energy's localization mandates are forcing oilfield services suppliers to rebuild supply chains around domestic manufacturing of high-specification directional drilling systems previously sourced from Western vendors.
Growth Catalysts
- Localization Quotas:The Russian Ministry of Energy mandates minimum domestic content thresholds for imported drilling equipment, creating captive demand for locally manufactured bottomhole assemblies and wellhead systems.
- Tight Oil Development:Multi-stage hydraulic fracturing programs targeting the Bazhenov shale formation require specialized horizontal drilling crews and pressure pumping fleets.
- Eastern Siberia Greenfields:Capital allocation toward new basin development in the Vankor and Verkhnechonsk clusters sustains long-term drilling service contracts.
Market Restraints
- Import Substitution Lag:Domestic manufacturers face 18-24 month lead times to replicate logging-while-drilling telemetry specifications previously supplied by SLB and Halliburton.
- Sanctions Architecture:Restrictions on semiconductor and high-grade steel exports constrain production of measurement-while-drilling tools at Russian fabrication facilities.
- Technical Limitation:Indigenous directional drilling motors lack the power density required for extended-reach laterals beyond 3,000 meters in the Bazhenov shale.
Strategic Opportunities
- Workover-Intensive Redevelopment:Legacy fields in the Volga-Ural basin require artificial lift optimization and sidetrack drilling services as reservoir pressure declines.
- Arctic Offshore:Prirazlomnoye and Novoportovskoye field expansions create demand for ice-resistant drilling platforms and subsea completion systems.
- Digital Twin Integration:Convergence of real-time drilling data analytics with predictive maintenance algorithms offers differentiation for service providers targeting Rosneft's digitalization roadmap.
Industry Challenges
- Directional Drilling Expertise Gap:Shortages of geosteering specialists and MWD engineers limit crew deployment velocity for horizontal well programs.
- GOST Certification Timelines:Wellhead and Christmas tree approvals under Eurasian Economic Union technical regulations require 12-16 month validation cycles that delay contract mobilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Oilfield Services Market |
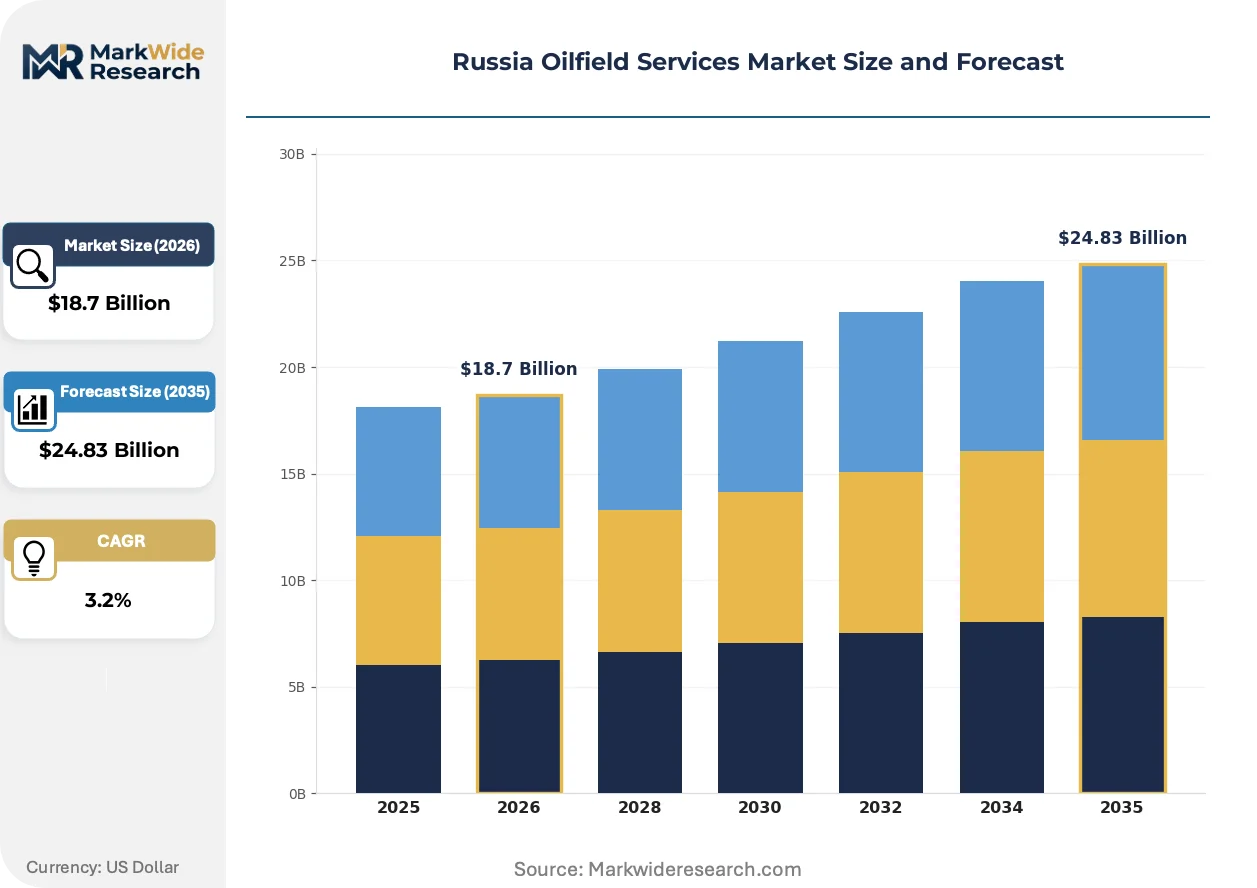
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $24.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Completion Services, Workover Services, Production Services Technology: Offshore Platforms, Hydraulic Fracturing, Well Logging, Enhanced Oil Recovery End User: National Oil Companies, Independent Producers, Oilfield Contractors, Service Providers Drilling Method: Vertical Drilling, Horizontal Drilling, Directional Drilling, Managed Pressure Drilling |
| Companies Covered | NaftaGaz JSC, Eriell, Gazprom Bureniye LLC, SLB, Weatherford, Rosneft-Burenie, INTEGRA, Baker Hughes, Surgutneftegas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Oilfield Services Market Emerging Trajectories
Digitalization and supply chain reconfiguration are converging to reshape how Russian operators contract for drilling execution, with technology migration patterns now dictated by equipment availability rather than performance optimization alone.
Geosteering software platforms are migrating from real-time gamma-ray correlation to resistivity-based formation evaluation while drilling. Independent producers in Western Siberia are adopting these systems at accelerated pace to improve landing precision in thin oil columns. The technology shift is compressing reliance on mud-logging interpretation and displacing traditional sample-based formation evaluation.
The Eurasian Economic Union's technical regulations on wellhead equipment certification are tightening material traceability requirements for Christmas tree assemblies. Russian fabricators must now document metallurgical sourcing through GOST-accredited laboratories to maintain market access. This regulatory friction most affects low-specification suppliers serving marginal field operators in the Timan-Pechora basin.
Service contract structures are fragmenting from integrated drilling packages toward discrete, phase-based procurement. National oil companies now unbundle directional drilling, logging, and cementing services to qualify multiple domestic vendors per tender. This buying-pattern shift is most visible in Khanty-Mansiysk Autonomous Okrug tenders, where Rosneft subsidiaries award separate contracts for surface and intermediate hole sections.
Russia Oilfield Services Market Segmentation
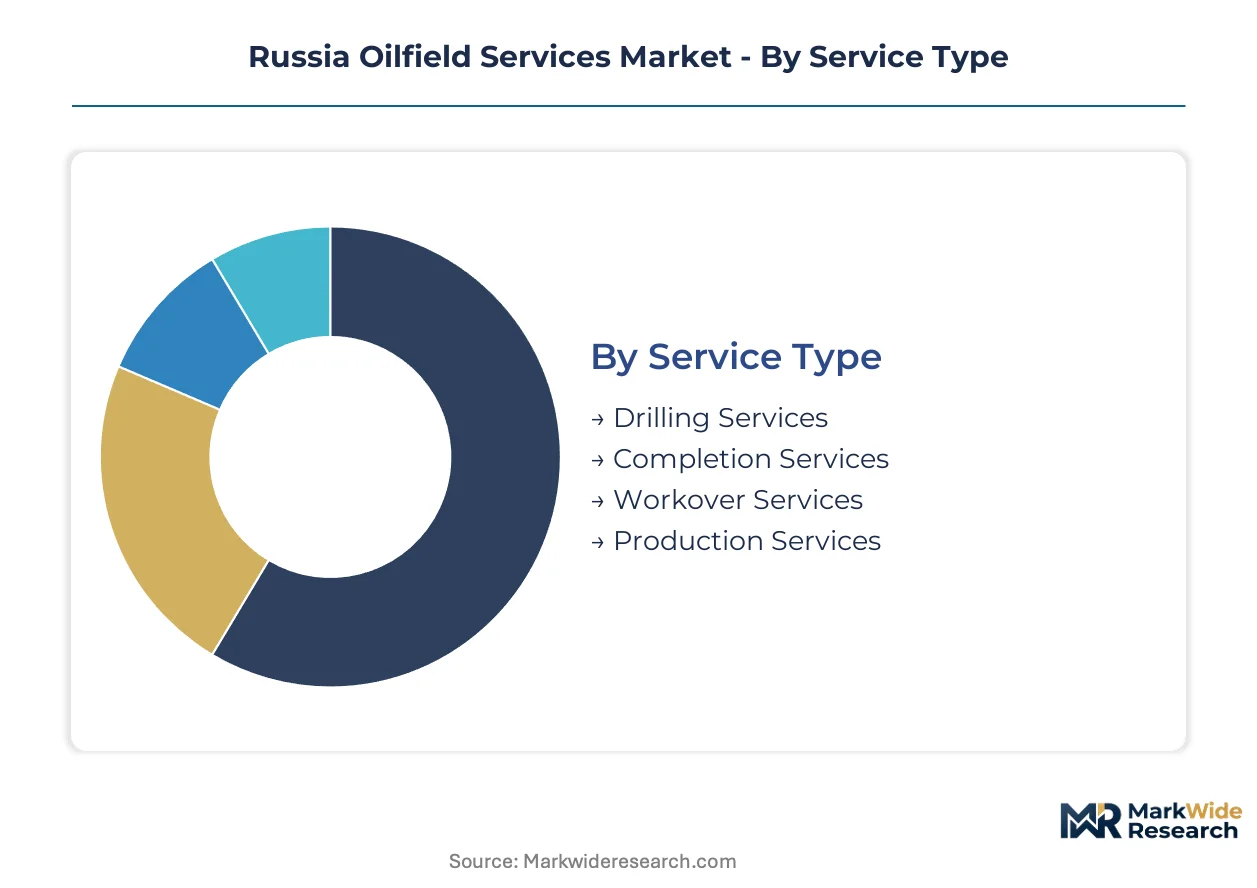
Segmentation in Russia's oilfield services market reveals how procurement authority and technical capability distribute across distinct contracting channels. Each dimension—service type, technology, end user, and drilling method—carries unique localization pressures and capital intensity profiles that determine vendor eligibility and margin structure.
Service Type:
Cost tier separates these service categories, with capital-intensive drilling commanding premium pricing while workover and production services operate on volume-based contracting models.
- Drilling Services:Encompasses wellbore construction from spud to total depth, including casing running, cementing, and directional steering. Rosneft subsidiaries in Eastern Siberia anchor demand through multi-year rig contracts for greenfield development in the Vankor cluster.
- Completion Services:Covers perforation, gravel packing, and intelligent well installation. Tight oil operators in the Bazhenov shale are concentrating procurement here as multi-stage hydraulic fracturing designs require specialized liner hanger systems and packer assemblies.
- Workover Services:Well intervention for recompletion and mechanical repair. Aging fields in the Volga-Ural basin sustain steady demand for rigless coiled tubing units and snubbing services.
- Production Services:Artificial lift optimization and surface facility maintenance. Independent producers in Western Siberia contract these on day-rate structures tied to barrel throughput.
Drilling Services holds installed capacity. Completion Services is rotating up the share rankings.
Technology:
Application focus distinguishes these technology segments, spanning extraction intensity, reservoir characterization, and recovery maximization methods.
- Offshore Platforms:Fixed and floating production systems for Arctic and Caspian developments. Prirazlomnoye field expansion in the Pechora Sea anchors procurement of ice-resistant jack-up rigs.
- Hydraulic Fracturing:Pressure pumping and proppant placement for unconventional reservoirs. Multi-stage completion designs in the Bazhenov shale are expanding fleet utilization for 15,000-psi rated pumping equipment.
- Well Logging:Formation evaluation through wireline and logging-while-drilling tools. SLB's premium telemetry systems face substitution pressure as domestic vendors replicate resistivity measurement specifications.
- Enhanced Oil Recovery:Thermal, chemical, and gas injection methods for mature fields. Rosneft pilots polymer flooding in Western Siberia's depleted sandstone reservoirs.
Offshore Platforms commands the heaviest capital commitment. Hydraulic Fracturing is gaining share fastest.
End User:
Customer type determines contract structure, with consolidated tender processes at national oil companies contrasting fragmented procurement by independent operators.
- National Oil Companies:Rosneft and Gazprom subsidiaries centralize procurement through framework agreements. These entities enforce localization quotas that reshape supplier eligibility for drilling equipment tenders.
- Independent Producers:Smaller operators farming into legacy fields. Western Siberian independents are expanding hydraulic fracturing programs as ministry requirements tighten on imported equipment.
- Oilfield Contractors:Integrated service companies managing drilling campaigns on behalf of license holders. Eriell and Rosneft-Burenie compete for integrated project management roles.
- Service Providers:Specialized vendors for discrete technical functions. Logging and cementing specialists face unbundling pressure as NOCs fragment procurement into phase-based awards.
National Oil Companies hold installed capacity. Independent Producers is rotating up the share rankings.
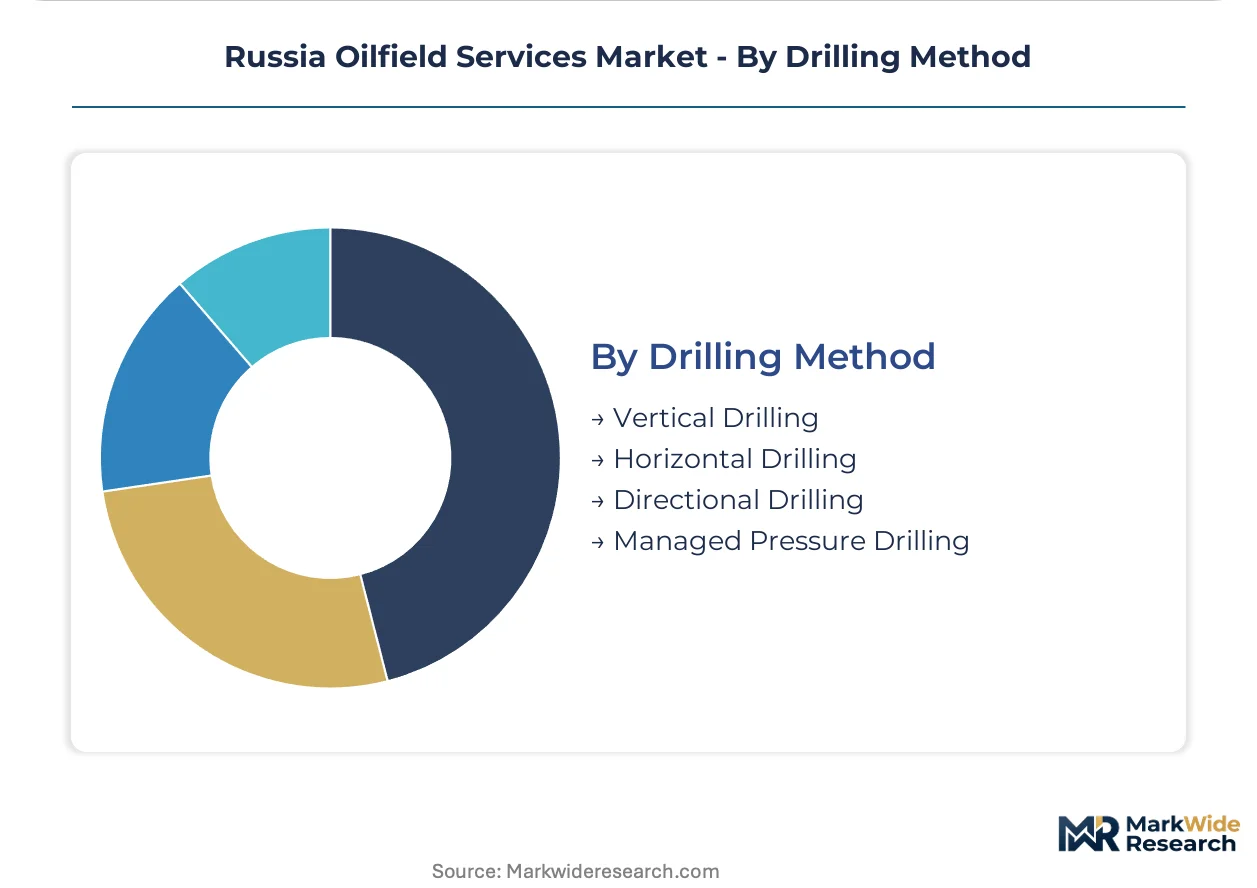
Drilling Method:
Technical complexity and lateral reach capability segment these approaches, with horizontal and managed pressure methods commanding premium day rates over conventional vertical drilling.
- Horizontal Drilling:Laterals extending 1,500-3,000 meters through reservoir pay zones. Bazhenov shale development in Western Siberia concentrates demand for geosteering crews and rotary steerable systems.
- Directional Drilling:Deviated wellbores with controlled azimuth and inclination. Indigenous motor technology lacks power density for extended-reach laterals, constraining deployment velocity.
- Vertical Drilling:Straight-hole construction for conventional reservoirs. Mature field redevelopment in the Volga-Ural basin sustains demand for cost-efficient vertical rig mobilization.
- Managed Pressure Drilling:Annular pressure control for narrow margin formations. Eastern Siberia's heterogeneous pressure regimes are expanding adoption of closed-loop circulation systems.
Horizontal Drilling holds installed capacity. Managed Pressure Drilling is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Russian Ministry of Energy anchors the dominant geography through localization mandates that reshape procurement eligibility across federal districts. Regional differentiation stems from basin maturity, infrastructure density, and proximity to fabrication centers serving import substitution programs.
Western Siberia
The Khanty-Mansiysk Autonomous Okrug concentrates hydraulic fracturing demand as independent producers expand multi-stage completion programs in the Bazhenov shale. The Ministry of Energy's domestic content thresholds force operators to source bottomhole assemblies from Tyumen-based fabricators. Surgut anchors the service contractor ecosystem, with drilling crews rotating between legacy field workovers and tight oil greenfields.
Eastern Siberia
The Vankor and Verkhnechonsk clusters sustain long-term rig contracts for directional drilling services targeting heterogeneous pressure regimes. Rosneft subsidiaries enforce phase-based procurement unbundling that fragments integrated service packages. Krasnoyarsk Krai hosts the primary logistics corridor for equipment mobilization to remote well sites.
Volga-Ural Basin
Mature sandstone reservoirs in Tatarstan and Bashkortostan generate workover-intensive demand for artificial lift optimization and sidetrack drilling. The Eurasian Economic Union's GOST certification timelines delay Christmas tree approvals for marginal field operators. Ufa anchors domestic manufacturing of drilling motors facing power density limitations for extended-reach laterals.
Timan-Pechora
Offshore Prirazlomnoye expansion and Novoportovskoye field development create demand for ice-resistant platforms and subsea completion systems. Metallurgical traceability requirements under Eurasian Economic Union technical regulations constrain low-specification wellhead suppliers. Arkhangelsk serves as the northern logistics hub for Arctic offshore mobilization.
Caspian Region
Deepwater exploration commitments sustain premium logging-while-drilling contracts despite sanctions constraints on telemetry component sourcing. Astrakhan Oblast hosts fabrication facilities attempting to replicate resistivity measurement specifications previously imported. The region's service intensity per well exceeds onshore averages due to complex salt dome geology.
Russia Oilfield Services Market Vendor Landscape
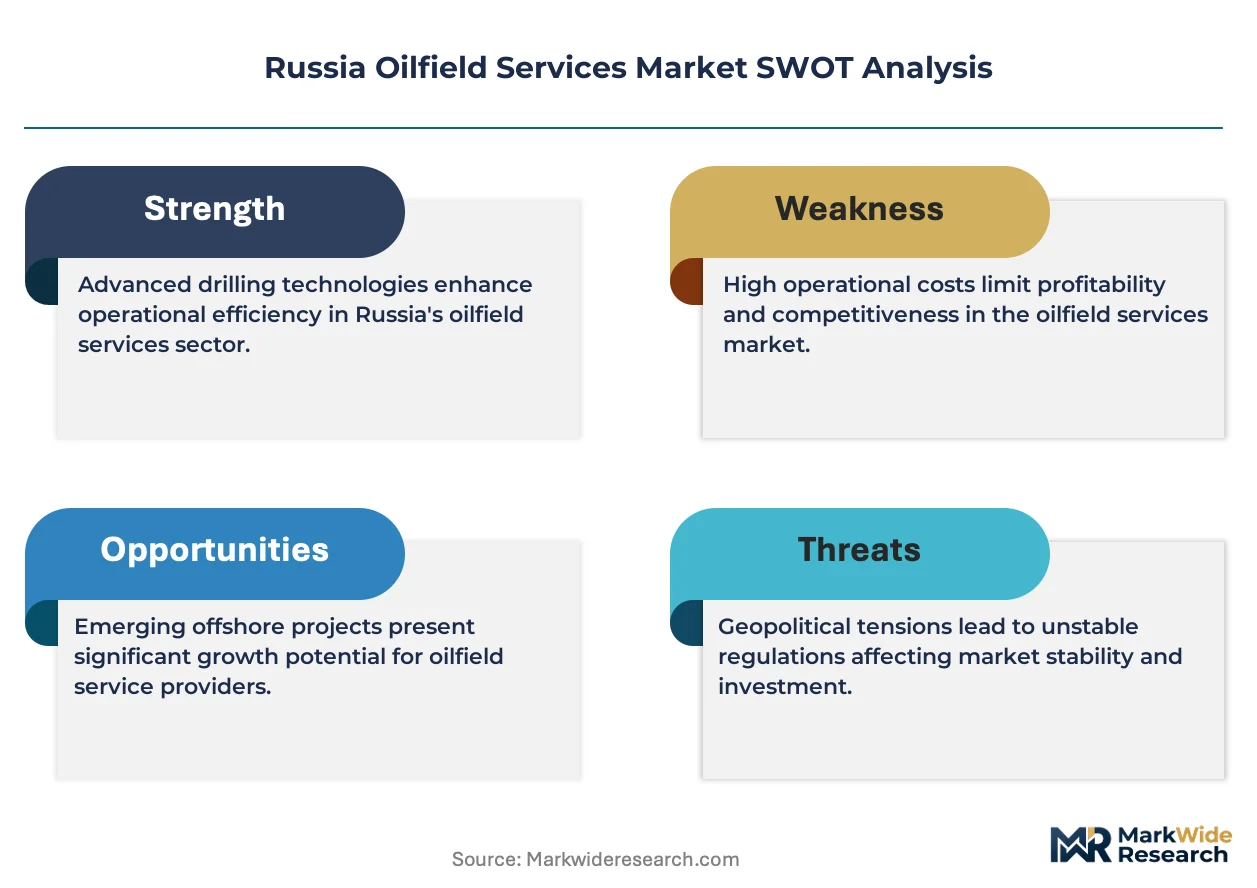
Capability concentration sits with technology-intensive specialists; scale advantage sits with vertically integrated national oil company subsidiaries. The market structure reflects a bifurcated tiering where premium directional drilling and logging services resist full domestic substitution, while commoditized drilling and workover segments consolidate around captive NOC fleets. Three archetypes dominate: state-backed integrated drillers with in-house manufacturing, international technology providers navigating sanctions through localized joint ventures, and independent specialists capturing unbundled tender lots. Competitive moves center on backward integration into tool fabrication and strategic licensing arrangements for telemetry intellectual property.
Among state-backed integrated drillers, Rosneft-Burenie and Gazprom Bureniye LLC exemplify the captive fleet archetype through in-house production of drilling tools at Russian-based facilities. SLB occupies a position representing the international technology provider tier, controlling premium logging-while-drilling systems that remain difficult to substitute under current localization mandates. Eriell anchors the independent specialist segment through deployment of horizontal drilling crews across multiple basins.
| Leading Market Players |
|---|
| NaftaGaz JSC |
| Eriell |
| Gazprom Bureniye LLC |
| SLB |
| Weatherford |
| Rosneft-Burenie |
| INTEGRA |
| Baker Hughes |
| Surgutneftegas |
| Others |
Supply Flow & Price Mechanics
Sanctions exposure on semiconductor and high-grade steel exports determines both pricing tier spreads and supply chain shape across Russian oilfield services, compressing margins on measurement-while-drilling tools while inflating premiums for telemetry systems that evade import controls.
Pricing Analysis
Tyumen-to-Krasnoyarsk price spreads for directional drilling crews now exceed those between domestic and imported logging equipment, as localization mandates force operators to absorb higher costs for indigenous bottomhole assemblies. Three-tier pricing structure across premium, standard, and economy levels separates SLB's resistivity-based formation evaluation from Eriell's geosteering packages and regional rig operators' vertical drilling day rates. Cost compression in standard-tier horizontal drilling services is intensifying because Rosneft subsidiaries unbundle procurement into phase-based awards. Independent producers in Western Siberia exhibit highest price sensitivity, while Gazprom Bureniye LLC maintains lowest sensitivity through captive fleet absorption of equipment premiums.
Supply Chain Analysis
Rosneft-Burenie and Gazprom Bureniye LLC hold concentrated in-house manufacturing capacity for drilling motors and wellhead systems at Russian-based fabrication facilities. Supply draws from domestic steel mills in Chelyabinsk and Ufa, Chinese semiconductor intermediaries routed through Central Asian logistics corridors, and German engineering components stockpiled before sanctions implementation. Single-source vulnerability on logging-while-drilling telemetry chips sourced from TSMC-concentrated foundries threatens fleet utilization for multi-stage fracturing programs. Distribution runs through Surgut and Tyumen logistics hubs serving Western Siberian operators, with Arkhangelsk anchoring Arctic offshore mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russian oilfield services are approaching a platform-economics inflection as real-time drilling data analytics converge with predictive maintenance algorithms, creating interoperability standards that favor providers controlling both downhole telemetry and surface digital infrastructure.
For Market Incumbents: Build certification moats around GOST-accredited metallurgical laboratories to defend against low-specification suppliers in the Timan-Pechora basin. Backward integration into resistivity measurement tool fabrication at Tyumen facilities counters SLB's premium telemetry dominance. Channel control through Surgut-based crew deployment hubs limits Eriell's geographic expansion velocity. Investment in MWD engineer training programs addresses the geosteering specialist shortage constraining horizontal well deployment. For New Entrants and Emerging Players: Marginal field operators in Tatarstan and Bashkortostan represent the most penetrable entry point for rigless coiled tubing and artificial lift optimization services. Workover-intensive redevelopment contracts in the Volga-Ural basin offer lower capital barriers than greenfield drilling tenders dominated by NOC captive fleets. A go-to-market angle anchored on 12-16 month GOST certification acceleration partnerships with Eurasian Economic Union technical regulators differentiates against established players with slower approval cycles. For Investors and Strategic Acquirers: The market sits at a supply-chain-reconfiguration phase that favors vertically integrated tool fabricators with in-house directional drilling expertise. Long-term viability across the five-to-ten year window hinges on domestic substitutability trajectories for high-specification rotary steerable systems. Acquisition targets should display captive manufacturing of bottomhole assemblies combined with deployed crew scale in Western Siberia. The signal to watch is Rosneft's digitalization roadmap procurement awards for integrated digital twin platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tool Fabrication | Rosneft-Burenie's Ufa manufacturing facility reduces dependency on sanctioned German engineering components. |
| GOST Certification Acceleration Partnership | Eurasian Economic Union technical regulation alignment compresses 16-month Christmas tree approval timelines for marginal field operators. |
| Digital Twin Platform Integration | Real-time drilling data convergence with predictive maintenance algorithms captures Rosneft digitalization procurement awards. |
| Crew Deployment Hub Expansion | Surgut-based logistics concentration improves mobilization velocity for Bazhenov shale multi-stage completion programs. |
| MWD Engineer Training Program Scale-Up | Geosteering specialist pipeline expansion addresses the expertise gap limiting horizontal well deployment beyond 3,000 meters. |
Methodological Framework
Desk research of EIA production databases, Russian Ministry of Energy localization mandate filings, and Eurasian Economic Union technical regulation documents preceded structured interviews with drilling operations managers at Rosneft subsidiaries, procurement leads at Gazprom Bureniye LLC, geosteering specialists at Eriell, and Tyumen-based fabrication facility engineers. Primary fieldwork across the Khanty-Mansiysk Autonomous Okrug and Krasnoyarsk Krai validated secondary data on crew deployment patterns and equipment utilization rates. Bottom-up rig count modeling triangulated against top-down capital expenditure disclosures from national oil company framework agreements.
Assumptions held fixed include current sanctions architecture on semiconductor and steel exports, Eurasian Economic Union GOST certification timelines, and Rosneft's stated digitalization roadmap priorities. Variables included domestic substitutability rates for logging-while-drilling telemetry, phase-based procurement unbundling velocity, and Arctic offshore project sanctioning cadence. The analytical framework modeled service type, technology, end user, and drilling method segments across the projection horizon. CAGRs derived from rig contract day-rate trajectories and hydraulic fracturing fleet expansion schedules, with Eastern Siberia greenfield development and Bazhenov shale tight oil programs as primary volume drivers.
Practitioners should monitor sanctions list updates, domestic motor power density improvement announcements from Ufa manufacturers, and Rosneft tender unbundling patterns for early signals requiring forecast revision. Quarterly review of GOST certification approval velocities, crew deployment rates in Western Siberia, and telemetry component import substitution progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Planned LNG Market
Oil & Gas
Dry Natural Gas Market