
 United States SLI Battery Market | 2026-2036
United States SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United States SLI Battery Market Insights
Modular battery tray configurations and service-bundle packaging is broadening fleet procurement flexibility. Clarios leverages its vertically integrated recycling network to secure lead supply continuity. East Penn Manufacturing anchors its position through deep channel control across independent auto parts distributors. Interstate Batteries competes on brand strength in the retail replacement segment.
A United States SLI battery is a lead-acid or advanced lead-acid electrochemical storage device engineered to deliver high cold-cranking amperage for engine starting, plus sustained reserve capacity for lighting and ignition systems, typically operating at 12 volts with plate grids alloyed with calcium or antimony. Flooded lead-acid products still dominate unit volume across passenger vehicle applications, though absorbed glass mat configurations are capturing margin pools in premium commercial fleet contracts. Lithium-ion technology remains nascent in this category but is attracting R&D investment from powertrain suppliers targeting motorcycle and marine starting applications where weight reduction commands pricing power.
The EPA enforces lead smelter emissions standards and spent battery recycling rules that shape manufacturing location decisions and material sourcing economics. NHTSA vehicle safety regulations influence battery mounting, venting, and crashworthiness specifications for OEM supply qualification. OSHA workplace exposure limits for lead affect plant automation investment and labor cost structures. Stakeholders must monitor how state-level clean fleet mandates in California and New York filter into commercial vehicle battery specification requirements.
Market Dynamics
Fleet electrification timelines and EPA lead recovery mandates are restructuring procurement economics for starting-lighting-ignition batteries across commercial logistics and passenger vehicle channels.
Growth Catalysts
- Commercial Fleet Replacement Cycles:Logistics operators are compressing SLI battery refresh intervals to minimize roadside failure risk in just-in-time delivery networks. This sustains aftermarket volume independent of new vehicle sales velocity.
- Resource Conservation and Recovery Act Enforcement:Tighter EPA standards for spent battery collection and lead smelter emissions are consolidating recycling infrastructure. This secures domestic material loops and reduces virgin lead price volatility for manufacturers.
- Absorbed Glass Mat Penetration:Premium commercial contracts are specifying AGM configurations for vibration resistance and deep-cycle durability. This technology commands margin expansion in fleet accounts versus flooded lead-acid commodity pools.
Market Restraints
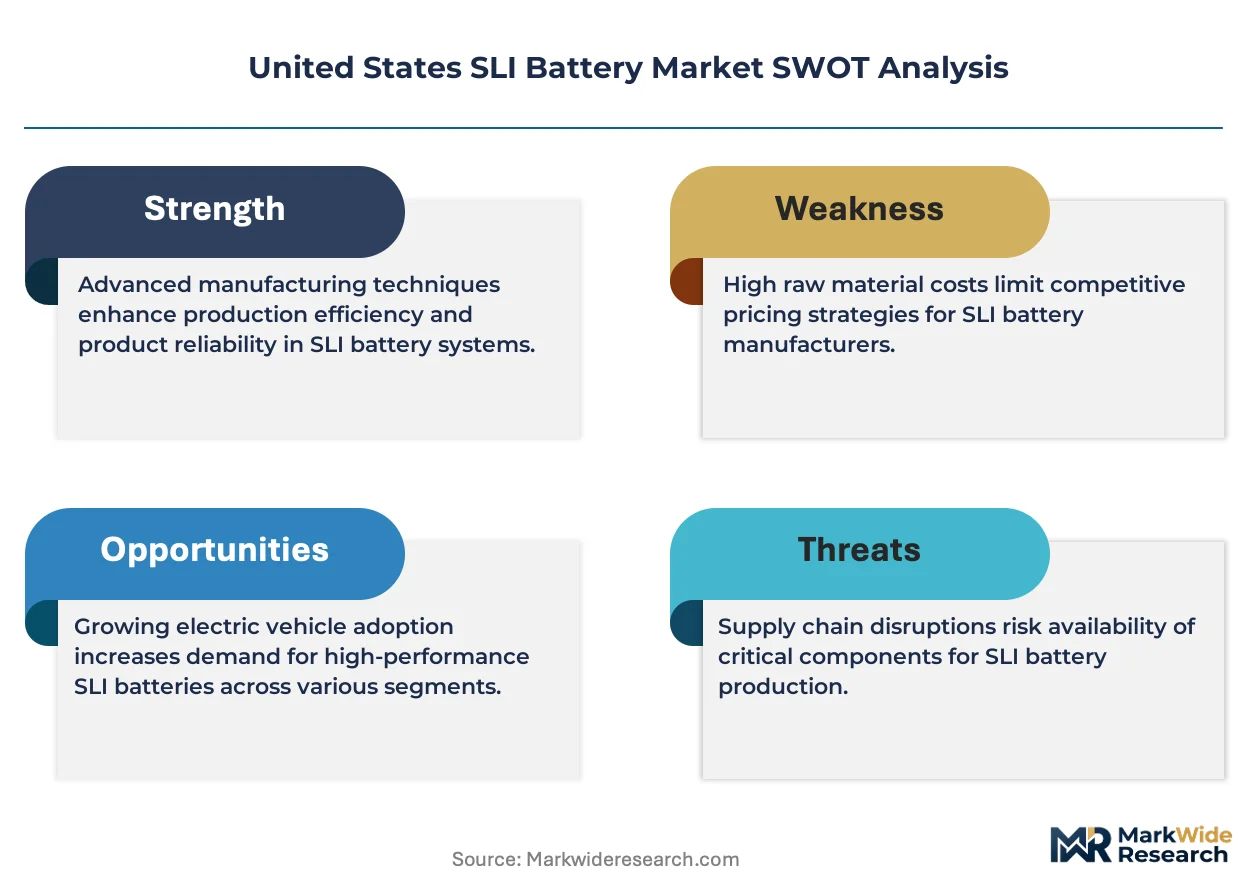
- Lead Price Volatility:Global refined lead supply concentrates in Chinese smelter capacity. Tariff exposure and energy cost spikes at these facilities transmit directly to US battery input costs.
- Technical Energy Density Ceiling:Lead-acid chemistry cannot achieve the mass reduction required for hybrid powertrain auxiliary power units. This limits SLI category expansion into 48-volt mild-hybrid architectures.
- OSHA Workplace Exposure Limits:Stricter federal lead-blood-level thresholds for manufacturing employees are accelerating automation capital requirements. Smaller independent assemblers face disproportionate compliance burden.
Strategic Opportunities
- State Clean Fleet Mandates:California and New York commercial vehicle electrification rules are creating specification windows for high-performance SLI units in transitional diesel-electric platforms.
- Marine and Motorcycle Lithium Substitution:Weight-sensitive starting applications represent viable entry points for lithium-ion technology suppliers. These segments tolerate premium pricing for mass reduction benefits.
- Independent Auto Parts Channel Digitization:E-commerce platforms are disintermediating traditional warehouse distributor tiers. Direct-to-installer fulfillment models enable margin recapture for battery brands with logistics infrastructure.
Industry Challenges
- Skilled Battery Technician Shortage:Proper installation of advanced AGM and enhanced flooded battery variants requires specific charging protocol knowledge. Fleet maintenance departments lack standardized certification pathways for these technologies.
- Legacy Inventory System Integration:Battery-specific state-of-charge tracking and warranty registration systems do not interface cleanly with existing fleet management software. This creates data fragmentation for multi-location operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States SLI Battery Market |
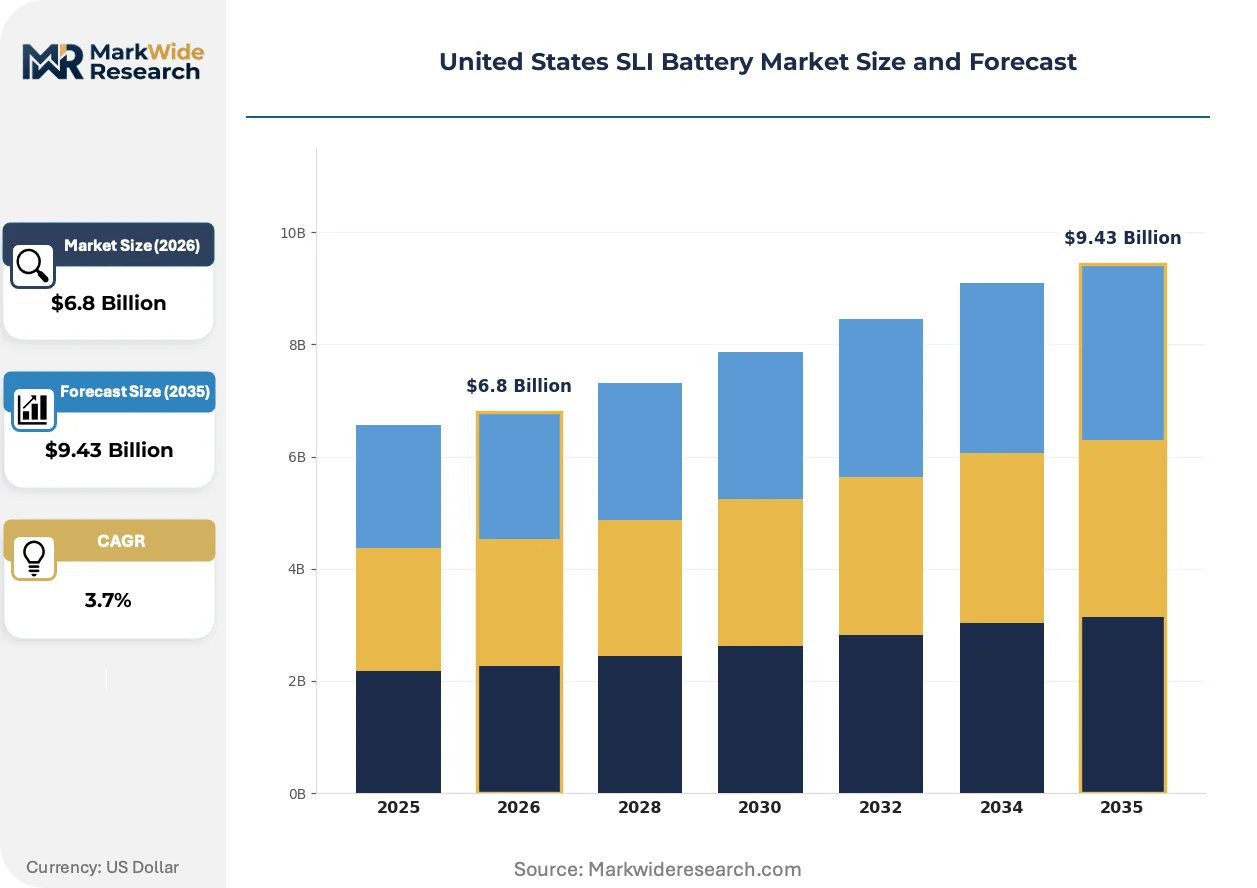
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded, AGM, Gel, Lithium Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Boats End User: OEMs, Aftermarket Providers, Distributors, Retailers Technology: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Advanced Lead-Acid |
| Companies Covered | Clarios, East Penn Manufacturing, EnerSys, Exide Technologies, Crown Battery, GS Yuasa Corporation, C&D Technologies, Johnson Controls, Interstate Batteries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States SLI Battery Market Trends and Innovations
Battery architecture is fragmenting across chemistry variants while regulatory pressure on material provenance intensifies traceability requirements throughout the value chain.
Smart battery management circuitry is converging with traditional SLI hardware to enable state-of-health monitoring and predictive failure alerting. Commercial fleet telematics providers are integrating these sensors into vehicle-area-network architectures. This convergence is compressing unplanned downtime costs and shifting procurement criteria toward connected-unit premiums.
EPA enforcement of the Resource Conservation and Recovery Act is tightening documentation requirements for lead-acid battery lifecycle tracking. Manufacturers must now certify smelter sourcing and recycling partner compliance to maintain OEM qualification. The Great Lakes automotive corridor faces the steepest adaptation burden due to concentrated production volume and legacy facility ages.
Fleet maintenance departments are unbundling battery replacement from full-service contracts to capture parts-margin directly. Independent service networks are responding with mobile installation units and core-return logistics. This behavioral shift is most visible in long-haul trucking operations across the I-75 manufacturing belt where downtime costs exceed $500 per hour.
United States SLI Battery Market Segmentation
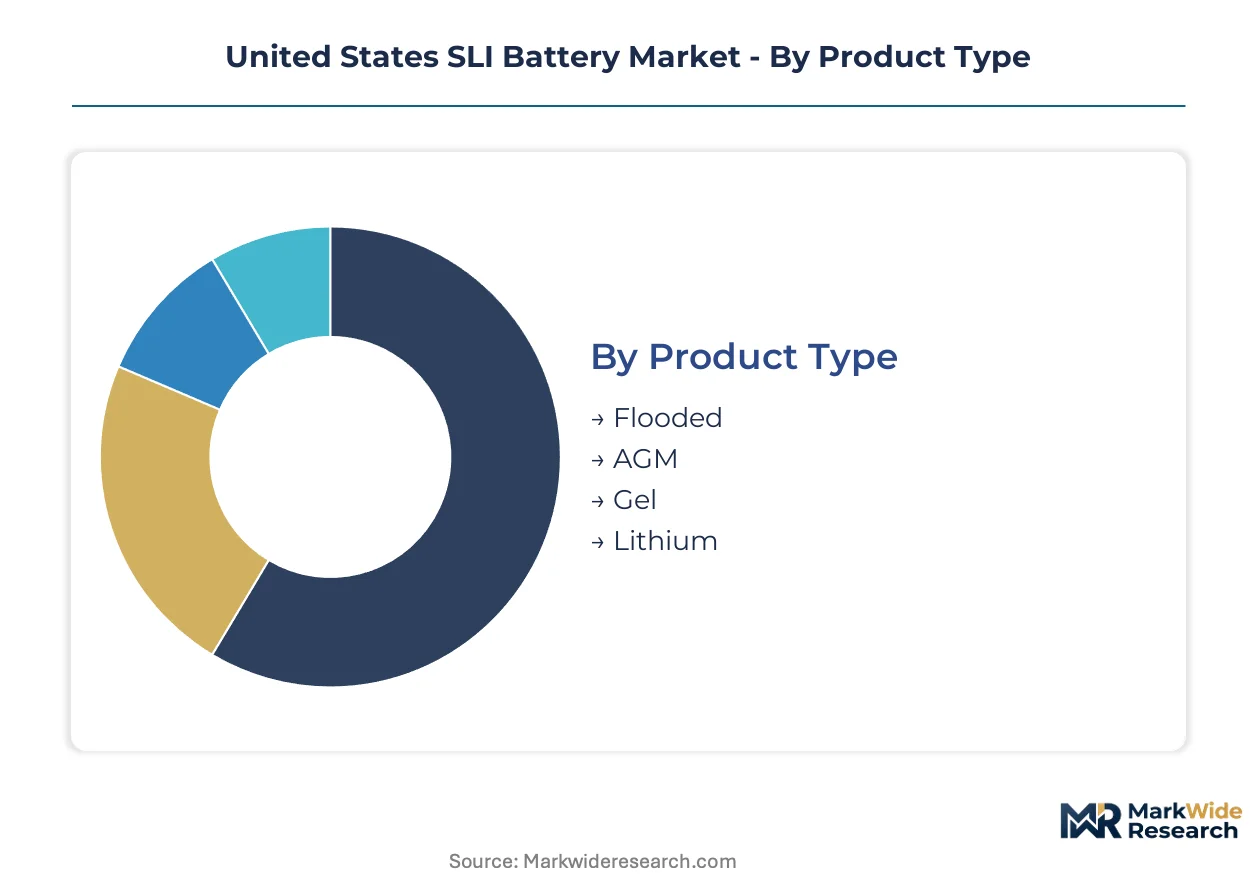
SLI battery procurement patterns diverge sharply across product architectures and channel configurations. Fleet operators prioritize durability specifications while retail replacement demand responds to price-point sensitivity and installation convenience.
Product Type:
Standardization dominates flooded lead-acid production while AGM and lithium variants command premium customization for specialized duty cycles.
- Flooded:Conventional liquid-electrolyte construction with vented cell design remains the default specification for passenger vehicle original equipment. Michigan and Ohio assembly plants consume the highest volume of standardized flooded units for mass-market light truck platforms.
- AGM:Absorbed glass mat separators eliminate free electrolyte and deliver superior vibration resistance for commercial fleet applications. Long-haul trucking operators across the I-75 corridor specify AGM for extended service intervals in just-in-time logistics networks.
- Gel:Silica-thickened electrolyte formulation suits deep-cycle marine starting applications where tilt tolerance matters. Coastal boatyards in Florida and the Great Lakes represent concentrated demand pockets.
- Lithium:Lithium iron phosphate chemistry penetrates weight-sensitive motorcycle and powersport segments where mass reduction justifies cost premiums. California and Arizona recreational vehicle registrations drive early adoption curves.
Most installed capacity flows through Flooded. Expansion is steepest in AGM.
Application:
Volume concentration sits with light-duty automotive while margin expansion concentrates in commercial and marine channels requiring enhanced durability specifications.
- Passenger Vehicles:Light-duty cars and SUVs represent the baseline volume pool with replacement cycles tied to average vehicle age. The Great Lakes manufacturing corridor generates concentrated demand from Detroit-area assembly operations.
- Commercial Vehicles:Class 3-8 trucks and delivery vans impose severe duty cycles with frequent engine starts and auxiliary power draws. Fleet operators in Texas and California compress replacement intervals to minimize roadside failure exposure.
- Motorcycles:Powersport applications prioritize cranking power-to-weight ratios for small-displacement engines. Seasonal registration patterns in the Upper Midwest create demand spikes aligned with riding season onset.
- Boats:Marine starting batteries must withstand moisture exposure and intermittent deep discharge without capacity degradation. Coastal states from Maine to Florida maintain year-round replacement demand from commercial fishing and recreational boating fleets.
Passenger Vehicles anchor unit volume. Commercial Vehicles capture the steepest margin expansion trajectory.
End User:
Channel control determines pricing power with direct OEM contracts favoring volume scale and aftermarket routes enabling margin recapture through service bundling.
- OEMs:Original equipment contracts require qualification to NHTSA safety standards and just-in-sequence delivery to assembly plants. Detroit Three automakers and transplant facilities in Kentucky and Tennessee dominate procurement volume.
- Aftermarket Providers:Independent service networks and mobile installation units capture parts margin previously retained by full-service dealers. Fleet maintenance departments in long-haul trucking are unbundling battery replacement from comprehensive maintenance agreements.
- Distributors:Warehouse and jobber networks intermediate between manufacturers and independent repair shops. Clarios and East Penn Manufacturing maintain deep channel control across this tier through exclusive territory arrangements.
- Retailers:Big-box auto parts chains and e-commerce platforms serve the do-it-yourself replacement segment. Interstate Batteries competes on brand recognition in this price-sensitive channel.
Distributors handle the largest flow of replacement volume. Aftermarket Providers are gaining share fastest through direct fleet contracting.
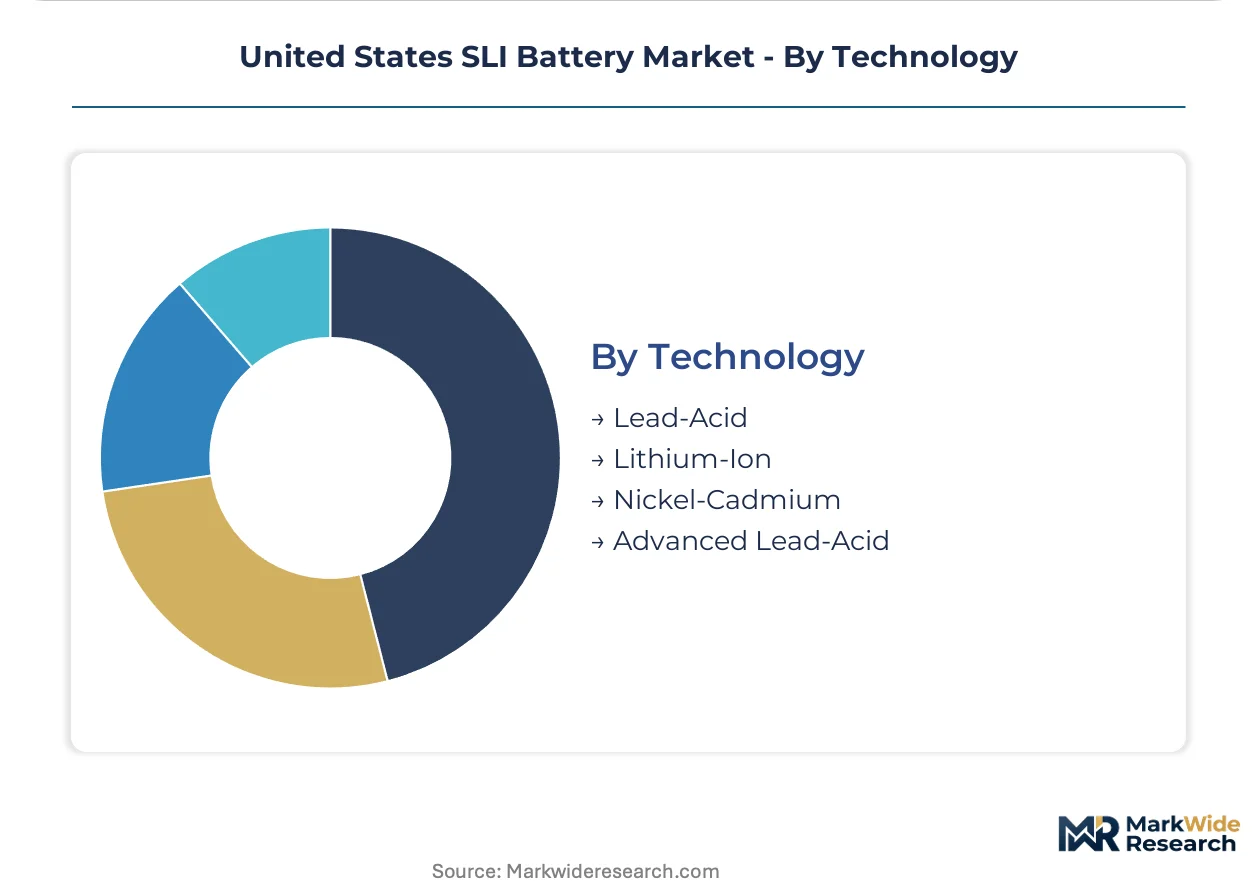
Technology:
Lead-acid chemistry maintains cost advantage while advanced formulations and lithium alternatives carve out performance-premium niches.
- Lead-Acid:Conventional calcium-alloy grid construction delivers cost-optimized starting power for standard automotive applications. EPA smelter emissions standards under the Resource Conservation and Recovery Act shape domestic manufacturing economics.
- Lithium-Ion:Lithium iron phosphate cells enable 70% mass reduction versus equivalent lead-acid capacity. Motorcycle and marine starting applications in California and Florida absorb early production volumes.
- Nickel-Cadmium:Legacy chemistry persists in specialized aviation and military starting applications requiring extreme temperature tolerance. Defense procurement through Department of supply chains sustains minimal domestic production.
- Advanced Lead-Acid:Enhanced flooded and AGM variants incorporate carbon additives and improved grid alloys for extended cycle life. Commercial fleet specifications in the Great Lakes corridor are migrating toward these formulations.
Lead-Acid retains the dominant installed base. Advanced Lead-Acid formulations are expanding most quickly in premium commercial contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SLI battery manufacturing in the United States traces its industrial lineage to early twentieth-century lead smelting operations along the Great Lakes, where proximity to automotive assembly plants established a vertically integrated production corridor that persists today.
Great Lakes Manufacturing Corridor
Michigan, Ohio, and Indiana host concentrated automotive assembly operations that generate OEM demand for standardized flooded lead-acid units. EPA enforcement of Resource Conservation and Recovery Act smelter emissions standards shapes facility upgrade cycles across aging plants in Detroit and Toledo. The I-75 logistics belt sustains aftermarket volume through fleet maintenance depots serving just-in-time trucking networks.
Southeast Battery Distribution Hub
Florida and Georgia anchor marine starting battery demand from recreational boating and commercial fishing fleets requiring gel and AGM configurations. State coastal management regulations influence battery disposal protocols for waterfront service operations. Charleston and Savannah port complexes concentrate import logistics for lead alloy raw materials feeding regional assembly plants.
Texas Commercial Fleet Center
Class 8 trucking operators across Dallas-Fort Worth and Houston compress SLI replacement intervals to minimize roadside failure exposure in energy sector logistics. Texas Commission on Environmental Quality rules on spent battery collection intersect with federal EPA standards. The Permian Basin oilfield service corridor generates specialized demand for vibration-resistant AGM units in heavy-duty work trucks.
California Electrification Frontier
State Air Resources Board clean fleet mandates for commercial vehicles create specification windows for high-performance SLI units in transitional diesel-electric platforms. California OSHA maintains workplace lead exposure thresholds that accelerate automation investment at West Coast distribution facilities. Los Angeles-Long Beach port drayage fleets represent early testing grounds for smart battery management integration with telematics systems.
Pacific Northwest Lithium Testing Ground
Motorcycle and powersport registrations in Washington and Oregon absorb early lithium iron phosphate starting battery volumes where mass reduction commands pricing power. State department of transportation weight-bridge regulations indirectly favor lighter battery technologies in commercial vehicle applications. Seattle-area marine yards test lithium substitution for sailboat auxiliary power systems.
United States SLI Battery Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive recycling networks and deep channel control across independent distribution tiers. Two distinct archetypes dominate: vertically integrated producers managing lead supply chains from smelting through retail, and brand-focused assemblers competing on installer relationships and warranty service infrastructure. Consolidation pressure concentrates among mid-scale operators lacking EPA-compliant recycling partnerships or automated assembly capacity. Dominant competitive moves include backward integration into lead smelting assets and geographic expansion of mobile installation service networks.
Among established domestic manufacturers, Clarios exemplifies the integrated archetype through its closed-loop material recovery operations, while East Penn Manufacturing occupies a position defined by territory-exclusive distributor arrangements. Interstate Batteries represents the brand-centric model competing on retail recognition and installer certification programs. These three anchors illustrate how competitive positioning diverges between supply-chain control and channel-facing service intensity.
| Leading Market Players |
|---|
| Clarios |
| East Penn Manufacturing |
| EnerSys |
| Exide Technologies |
| Crown Battery |
| GS Yuasa Corporation |
| C&D Technologies |
| Johnson Controls |
| Interstate Batteries |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange refined lead pricing cascades through the United States SLI battery supply chain, compressing margins at independent assemblers while integrated manufacturers capture value through captive smelter networks and long-term offtake arrangements with Great Lakes recycling facilities.
Pricing Analysis
Three-tier pricing structure across premium AGM, standard enhanced flooded, and economy flooded levels governs procurement contracts, with certification to NHTSA safety standards and EPA smelter compliance driving tier placement. Brand premiums for established distributors command 8-15 point spreads over private-label alternatives. Cost compression in the economy tier is intensifying because Chinese refined lead import tariffs transmit directly to battery input costs. Fleet operators exhibit the lowest price sensitivity due to unplanned downtime costs exceeding $500 per hour, while retail DIY buyers concentrate demand at entry price points.
Supply Chain Analysis
Inbound freight costs for lead alloy raw materials from Mexico and Canada shape regional assembly economics, with rail rates from Charleston and Savannah port complexes influencing Southeast distribution margins. Domestic production draws from Mexican lead concentrate and Canadian refined metal, with secondary lead recovery from Great Lakes recycling facilities supplying 60-70% of grid alloy requirements. Single-source vulnerability concentrates in Chinese refined lead capacity, where energy cost spikes and export licensing shifts create input price volatility. Distribution runs through territory-exclusive warehouse distributors serving independent auto parts networks, with direct-to-installer fulfillment emerging in fleet maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States SLI battery market functions as a regulatory compounder, where EPA enforcement of Resource Conservation and Recovery Act smelter emissions standards is consolidating recycling infrastructure and rewarding integrated operators with compliant closed-loop networks.
For Market Incumbents: Extend backward integration into lead smelting assets to secure material supply continuity against Chinese refined lead price volatility. Deepen channel control across independent auto parts distributors through exclusive territory arrangements that lock out emerging competitors. Invest in automated assembly capacity to offset OSHA workplace lead exposure compliance costs that disproportionately burden smaller operators. For New Entrants and Emerging Players: Lithium iron phosphate technology for motorcycle and marine starting applications offers the most penetrable wedge, where mass reduction commands pricing power and incumbent lead-acid manufacturers lack established brand equity. Target California and Florida recreational vehicle registrations with direct-to-consumer e-commerce fulfillment bypassing traditional warehouse distributor tiers. Pursue certification partnerships with powersport OEMs to accelerate adoption curves in weight-sensitive segments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale operators possessing EPA-compliant recycling partnerships but lacking automated assembly capacity, where consolidation premiums will concentrate as OSHA thresholds tighten. The five-to-ten year viability window favors integrated manufacturers with captive lead supply over brand-dependent assemblers exposed to raw material volatility. Monitor California Air Resources Board clean fleet mandate implementation timelines as the inflection signal for high-performance SLI specification windows in transitional diesel-electric platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive supply from Great Lakes recycling facilities insulates against Chinese refined lead tariff exposure and price volatility. |
| AGM Capacity Expansion | Premium commercial fleet contracts specifying vibration-resistant configurations command margin expansion over flooded commodity pools. |
| Smart Battery Management Integration | Telematics convergence with state-of-health monitoring compresses unplanned downtime costs for long-haul trucking operators. |
| Direct-to-Installer Fulfillment Buildout | E-commerce platforms disintermediate warehouse distributors and enable margin recapture in fleet maintenance unbundling trends. |
| EPA Recycling Partnership Certification | Resource Conservation and Recovery Act compliance documentation maintains OEM qualification and secures domestic material loops. |
Research Methodology
Bottom-up fleet operator and aftermarket channel modeling reconciled against top-down lead smelter capacity and battery production tracking forms the analytical core of this study. Primary interviews with commercial fleet maintenance directors, independent auto parts distributor principals, EPA compliance officers at recycling facilities, and OEM platform engineering teams informed demand-side assumptions. Secondary validation drew from EPA enforcement action databases, NHTSA safety standard filings, London Metal Exchange lead price archives, and state-level vehicle registration statistics from Michigan, Ohio, and California.
Historical trendline analysis of replacement cycle compression and chemistry migration patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product architecture, application duty cycle, channel configuration, and technology chemistry dimensions. CAGRs were derived from regression-adjusted trend extrapolation incorporating fleet electrification timeline scenarios and regulatory enforcement intensity assumptions specific to EPA smelter emissions standards and OSHA workplace lead exposure thresholds.
The model holds under stable EPA enforcement intensity and moderate lead price volatility; deviation in Chinese export licensing regimes or accelerated commercial vehicle electrification mandates would shift volume trajectories and margin pools. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
United Kingdom SLI Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
East Africa Battery Market
Batteries
Global Industrial Battery Market
Batteries
East Asia Battery Market
Batteries
Silicon Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
VRLA Batteries Market
Batteries
Battery-Powered Riveter Market
Batteries
North America NMC Battery Pack Market
Batteries
Battery Separators Market
Batteries
South Europe Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Aluminum Based Battery Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market