
 Cylindrical Lithium Battery Winding Machine Market | 2026-2036
Cylindrical Lithium Battery Winding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cylindrical Lithium Battery Winding Machine Market Insights
Electric vehicle production is recalibrating equipment procurement priorities across the cylindrical cell supply chain. Wuxi Lead Intelligent Equipment leverages its Jiangsu manufacturing base to dominate domestic automated winding line deliveries. Hitachi High-Tech Corporation sustains technology leadership in precision tension control systems for high-speed electrode winding. Manz AG competes through specialized coating and winding integration platforms serving European automotive cell plants.
Cylindrical lithium battery winding machines automate the sequential layering of anode, separator, and cathode materials into jellyroll configurations, with tension control precision typically maintained within ±2% to prevent electrode deformation during high-speed operations. These systems serve the commercial purpose of producing standardized 18650, 21700, and 4680 cell formats at throughputs exceeding 200 ppm for electric vehicle and energy storage applications. Automated winding technology leads the technology segment as OEMs phase out manual lines for traceability and yield consistency, while high capacity configurations capture expanding margin pools from 4680-format cell ramp-ups. Electric vehicles anchor the end user segment, though energy storage systems represent the fastest-growing demand category as grid-scale battery deployments accelerate.
China's NMPA and MIIT enforce GB standards and dual carbon goals that mandate equipment energy efficiency and manufacturing process emissions disclosures, directly shaping winding machine specification requirements for domestic cell producers. The EU AI Act and F-Gas Regulation, alongside REACH compliance for electrode material handling, condition market access for European-bound equipment suppliers. Stakeholders must monitor evolving cell format roadmaps and corresponding tooling changeover flexibility as battery architectures shift between cylindrical, prismatic, and solid-state configurations.
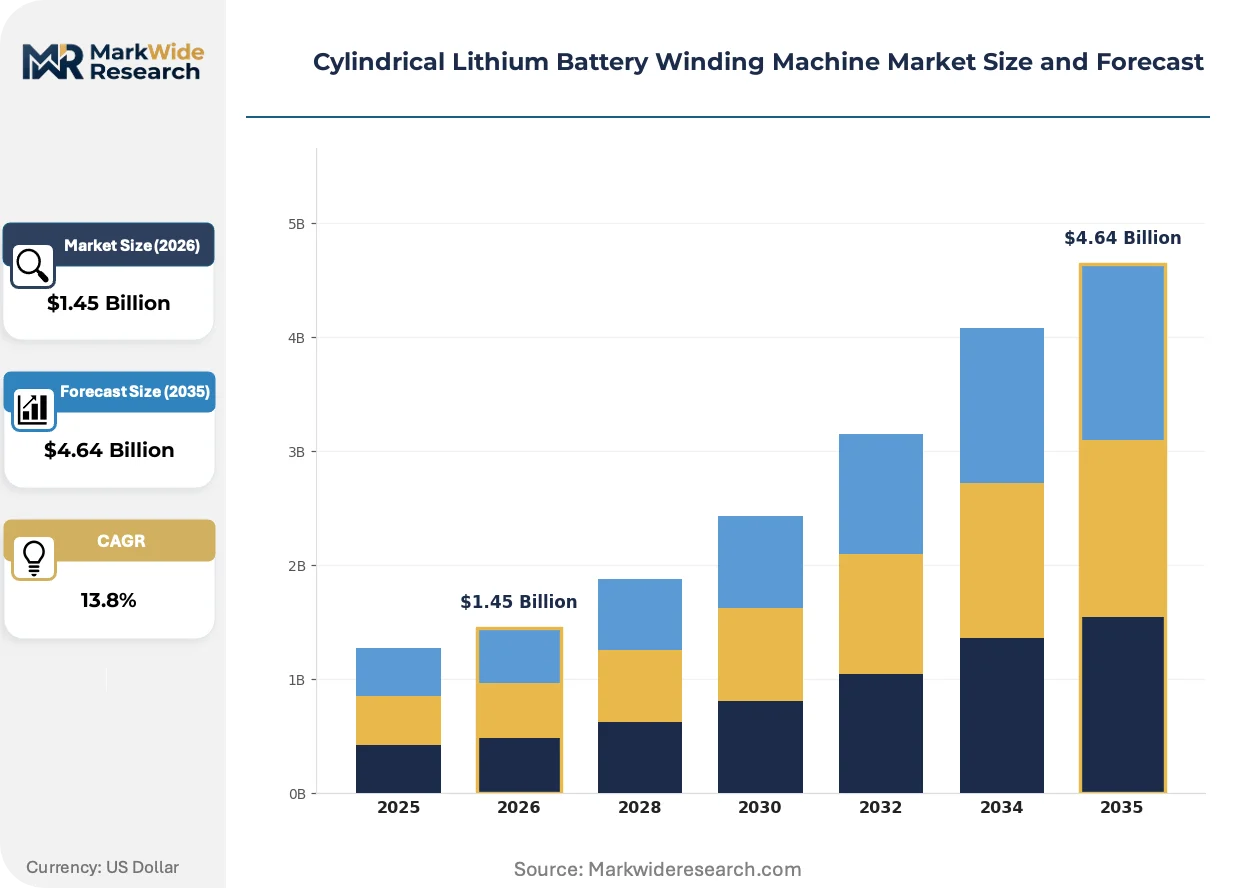
Market Dynamics
Cell format standardization around the 4680 cylindrical architecture is compressing tooling changeover flexibility requirements while amplifying procurement volumes for high-throughput automated winding lines among electric vehicle battery pack producers.
Growth Catalysts
- GB Standards Certification Mandates:China's NMPA and MIIT enforcement of battery manufacturing safety protocols under GB standards is compelling domestic cell producers to upgrade to traceable automated winding systems with integrated quality monitoring.
- 4680 Format Ramp-ups:Electric vehicle OEMs are consolidating cell procurement around larger-diameter cylindrical formats that demand precision tension control systems capable of handling thicker electrode coatings at sustained speeds.
- Jiangsu-Guangdong Equipment Clustering:Proximity of winding machine manufacturers to cathode material plants and cell assembly facilities in these provinces is shortening equipment commissioning cycles and technical service response times.
Market Restraints
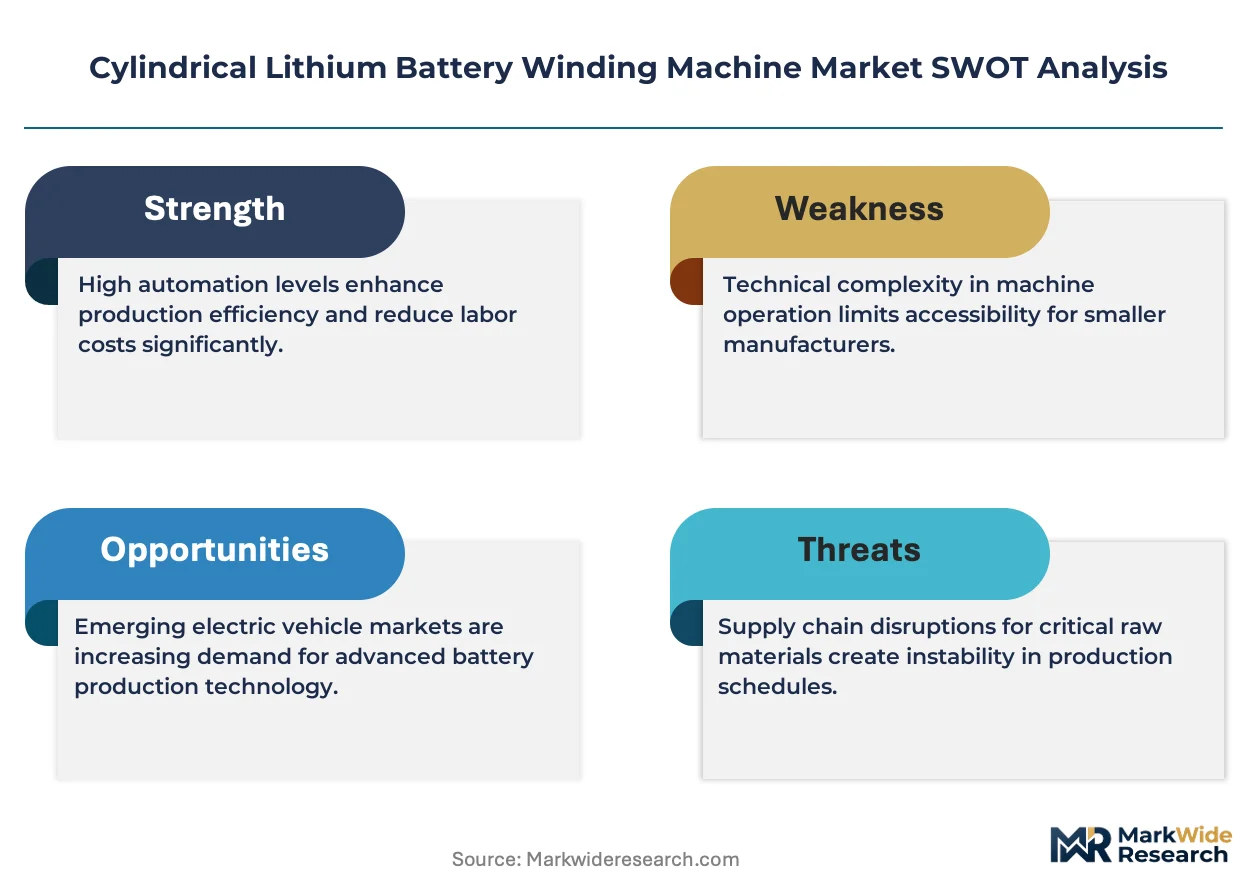
- Copper Foil and Separator Input Volatility:Electrode substrate supply constraints and price swings for high-purity copper foil and ceramic-coated separators are compressing margin predictability for winding line operators.
- Single-Source Precision Component Risk:Tension control sensors and servo motor assemblies for high-speed winding applications concentrate among Japanese and German component suppliers, creating vulnerability to export licensing delays.
- Solid-State Cell Substitution Timeline:Accelerated development of solid-state battery architectures with stacked rather than wound electrode configurations threatens long-term demand for cylindrical winding equipment.
Strategic Opportunities
- Energy Storage System Deployment Surge:Grid-scale battery installations for renewable energy integration represent an underpenetrated end-use vertical with less stringent format standardization than automotive applications.
- EU AI Act Compliance Services:European-bound equipment suppliers can capture value-add revenue streams by embedding automated defect detection and process optimization algorithms that satisfy algorithmic transparency requirements.
- Coating-Winding Integration Convergence:Equipment platforms combining electrode coating and winding operations in single continuous lines are reducing work-in-process inventory and cleanroom footprint for cell producers.
Industry Challenges
- Mechatronics Specialist Scarcity:The intersection of precision mechanical engineering, real-time control systems, and battery electrochemistry requires hybrid skill sets that remain scarce in manufacturing labor markets.
- Dual Carbon Disclosure Timelines:China's MEE mandates for equipment energy efficiency and process emissions reporting are compressing certification cycles and requiring retrofits of existing winding line installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cylindrical Lithium Battery Winding Machine Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $4.64 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Winding, Manual Winding, Hybrid Systems, Coil Winding End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Applications Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Solutions Application: Power Tools, Electric Bikes, Drones, Medical Devices |
| Companies Covered | Manz AG, CKD Corporation, Wuxi Lead Intelligent Equipment, Shenzhen Yinghe Technology, Hitachi High-Tech Corporation, Nagano Automation, Fuji Machinery, Sovema Group, Golden Milky Battery Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cylindrical Lithium Battery Winding Machine Market Trends and Innovations
Active electrode coating thicknesses and winding speeds are advancing in lockstep, forcing simultaneous innovation in tension control algorithms and thermal management systems across equipment portfolios.
Multi-layer electrode stacking with z-fold separator insertion is overtaking conventional jellyroll winding for next-generation high-nickel cathode cells. Automotive cell producers in South Korea and Japan are piloting these systems at reduced speeds to validate defect rates. This architecture is overtaking legacy winding methods by enabling thicker electrode loading without the radial stress concentrations that degrade cycle life in cylindrical formats.
REACH compliance for solvent recovery in electrode coating operations is mandating closed-loop thermal oxidizer integration with winding line exhaust systems. European equipment suppliers must now certify entire production line emissions profiles rather than discrete machine components. Cell plants in Germany and Hungary are absorbing capital cost premiums of fifteen to twenty-five percent to satisfy these extended compliance boundaries.
Equipment-as-a-service contracting with throughput-based payment structures is fragmenting traditional capital purchase patterns among mid-tier cell producers. Third-party financing vehicles are assuming residual value risk for automated winding lines while capturing margin from performance guarantees. This model is most visible in India and Southeast Asia where domestic cell startups lack balance sheet capacity for full equipment ownership.
Cylindrical Lithium Battery Winding Machine Market Segmentation
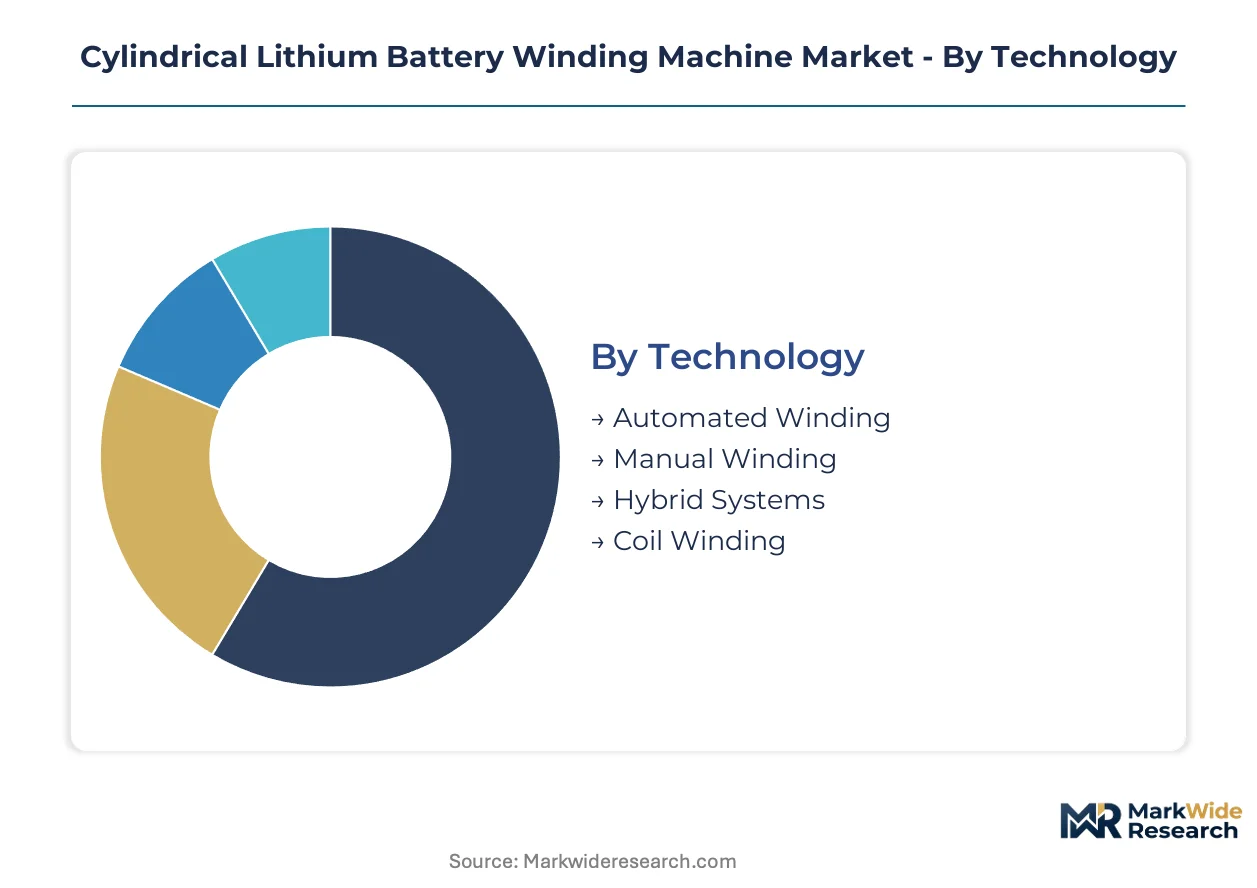
Segmentation in the cylindrical lithium battery winding machine market reveals how capital allocation priorities diverge across automation levels, end-use requirements, and throughput specifications. Equipment buyers face distinct trade-offs between precision tolerances, changeover flexibility, and regulatory compliance burdens depending on their operational scale and target cell formats.
Technology:
Capital intensity peaks with fully automated winding lines, where servo-controlled tension systems and integrated vision inspection layers compound upfront investment requirements.
- Automated Winding:Systems deploy precision servo motors and real-time tension feedback loops maintaining ±2% deviation thresholds during high-speed electrode layering. Electric vehicle battery pack producers in Jiangsu and Guangdong provinces are consolidating procurement around these lines as NMPA traceability mandates tighten. The 4680 format ramp-up is amplifying demand for automated platforms capable of handling thicker electrode coatings without radial stress deformation.
- Manual Winding:Operators perform sequential anode-separator-cathode layering with mechanical assistance but without closed-loop control systems. Prototype cell development and specialty medical battery production in Japan retain limited manual capacity for low-volume, high-mix applications where tooling flexibility outweighs throughput economics.
- Hybrid Systems:Semi-automated platforms combine manual electrode loading with automated winding heads, reducing capital outlay while preserving quality monitoring capabilities.
- Coil Winding:Distinct from jellyroll architectures, these systems produce wound inductor components for battery management system circuitry rather than cell electrodes.
Most installed capacity flows through Automated Winding. Expansion is steepest in Hybrid Systems as mid-tier producers seek intermediate automation without full capital commitment.
End User:
Volume concentration and margin structure diverge sharply between automotive-scale procurement and specialized industrial applications with fragmented demand patterns.
- Electric Vehicles:OEMs specify winding lines capable of 200+ ppm throughput with integrated coating-winding convergence for 4680 cell production. China's dual carbon disclosure requirements under MEE mandates are compelling domestic producers to specify energy-efficient automated platforms with emissions monitoring capabilities.
- Energy Storage Systems:Grid-scale battery deployments tolerate wider format variation than automotive applications, creating demand for flexible winding platforms with rapid tooling changeover. Utility-scale projects in Germany and Hungary are absorbing REACH-compliant equipment with closed-loop solvent recovery integration.
- Consumer Electronics:Legacy 18650 and 21700 formats dominate this segment, with winding lines optimized for smaller-diameter electrodes and higher winding speeds.
- Industrial Applications:Forklift batteries, stationary backup power, and material handling equipment drive intermittent demand with less stringent precision requirements.
Electric Vehicles commands the largest share of installed winding capacity. Energy Storage Systems is climbing the fastest as renewable integration targets accelerate grid-scale procurement.
Capacity:
Throughput tier selection directly determines equipment footprint, cleanroom integration complexity, and the economics of continuous versus batch production modes.
- High Capacity:Continuous-line configurations process electrode materials at sustained speeds exceeding 200 ppm, requiring precision thermal management and tension control algorithms. European automotive cell plants in Germany specify these platforms for 4680 ramp-ups under EU AI Act algorithmic transparency requirements for automated defect detection.
- Medium Capacity:Batch-oriented systems serve cell producers with diversified format portfolios, offering tooling changeover capabilities that high-throughput lines sacrifice.
- Low Capacity:Pilot-line and R&D applications utilize compact winding platforms with manual intervention points for process development.
- Custom Solutions:Engineered-to-order platforms address non-standard cell geometries or specialized electrode chemistries outside mainstream format roadmaps.
High Capacity installations dominate capital deployment. Custom Solutions is expanding most quickly as solid-state and sodium-ion cell architectures deviate from cylindrical jellyroll conventions.
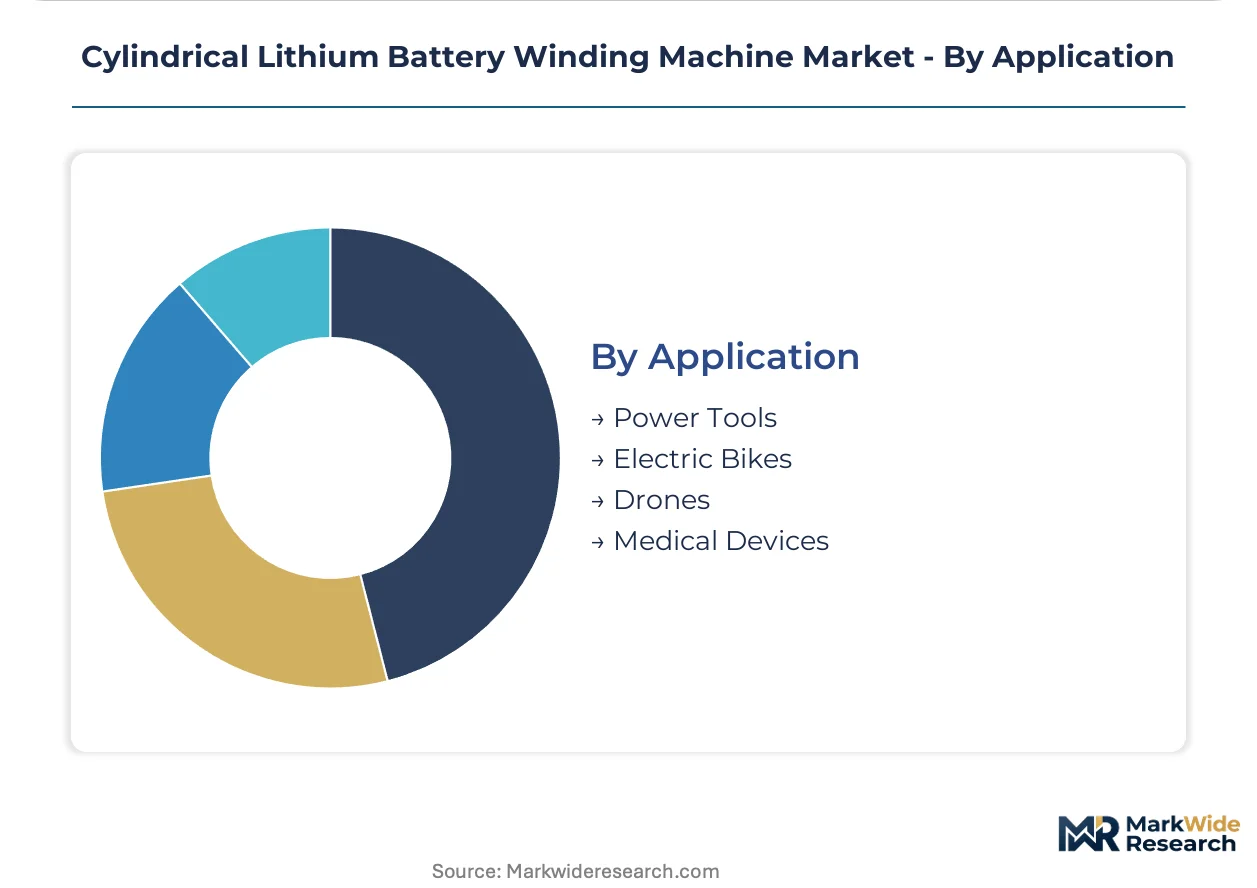
Application:
End-use device specifications propagate backward through the supply chain to constrain electrode thickness, winding precision, and thermal management requirements.
- Power Tools:High-discharge 18650 and 21700 cells demand winding platforms capable of consistent electrode alignment under vibration-prone operating conditions.
- Electric Bikes:Pack-assemblers source cylindrical cells with moderate energy density requirements, prioritizing cost-optimized winding equipment over precision premium tiers.
- Drones:Lightweight high-power cells require thin-electrode winding with strict weight consistency controls for aerial applications.
- Medical Devices:Implantable and portable diagnostic equipment drives demand for ultra-precise winding with comprehensive traceability documentation under FDA and Japan PMDA quality system regulations.
Power Tools channels the majority of cylindrical cell winding output. Medical Devices shows the steepest expansion trajectory as implantable battery applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors equipment procurement momentum as domestic cell producers consolidate automated winding line orders. Electric vehicle battery pack manufacturers in Wuxi and Suzhou industrial parks are compressing commissioning cycles through proximity to cathode material suppliers. China's NMPA and MIIT enforcement of GB standards is mandating traceable quality monitoring systems across all new installations.
China
Domestic equipment makers cluster in Jiangsu and Guangdong provinces near cathode plants and cell assembly facilities. NMPA and MIIT are tightening GB certification requirements for battery manufacturing safety. Wuxi Lead Intelligent Equipment leverages its Jiangsu base to dominate domestic automated winding line deliveries to electric vehicle producers.
Germany
Automotive cell plants in Bavaria and Baden-Württemberg specify high-throughput platforms for 4680 ramp-ups. The EU AI Act and REACH compliance mandate algorithmic transparency for automated defect detection and closed-loop solvent recovery integration. Equipment suppliers absorb fifteen to twenty-five percent capital cost premiums to satisfy extended emissions certification boundaries.
Japan
Precision tension control technology development concentrates in Nagoya and Tokyo metropolitan manufacturing corridors. METI guidelines and JIS standards govern equipment energy efficiency disclosures for domestic cell producers. Pilot facilities in Osaka prefecture are testing multi-layer electrode stacking systems for high-nickel cathode cells at reduced speeds.
South Korea
Battery producers in Gyeonggi-do and Chungcheong provinces are expanding procurement of high-capacity winding configurations. MFDS quality system regulations align with automotive OEM traceability requirements for electrode alignment precision. Daegu-Gyeongbuk industrial complexes host coating-winding integration platform development for continuous production lines.
United States
Cell manufacturing investments in Michigan and Nevada are driving demand for automated winding systems with rapid tooling changeover capabilities. The IRA domestic content provisions are conditioning equipment procurement decisions for federally subsidized battery plants. Detroit-area engineering centers are recruiting mechatronics specialists to bridge precision mechanical and real-time control system integration.
Cylindrical Lithium Battery Winding Machine Market Competitive Landscape
Capacity expansion dominates the current landscape as equipment suppliers race to capture 4680-format ramp-up orders. The vendor base separates into three distinct tiers: integrated platform specialists serving automotive-scale procurement, regional fabricators targeting mid-tier cell producers, and precision component suppliers controlling tension control sensor supply. Strategic archetypes include coating-winding integration specialists, high-speed automation pure-plays, and hybrid system providers bridging manual and automated workflows. Geographic expansion and technology licensing are the dominant competitive moves, with European suppliers embedding AI Act-compliant algorithms and Chinese manufacturers extending service networks into Southeast Asia.
Among Germany-based integrated platform specialists, Manz AG occupies a position exemplifying coating-winding convergence for European automotive cell plants. Japanese precision automation groups, represented by Hitachi High-Tech Corporation, anchor the high-speed tension control technology tier. Chinese equipment fabricators, with Wuxi Lead Intelligent Equipment representing the domestic leader archetype, sit within the high-volume automated winding line segment serving Jiangsu and Guangdong province clusters. These three company types collectively illustrate how geographic proximity to cathode material plants and regulatory compliance specialization are fragmenting competitive positioning across regional markets.
| Leading Market Players |
|---|
| Manz AG |
| CKD Corporation |
| Wuxi Lead Intelligent Equipment |
| Shenzhen Yinghe Technology |
| Hitachi High-Tech Corporation |
| Nagano Automation |
| Fuji Machinery |
| Sovema Group |
| Golden Milky Battery Equipment |
| Others |
Pricing and Supply Chain Analysis
Copper foil and ceramic-coated separator feedstock costs cascade through three distinct equipment pricing tiers, with Japanese and German precision component premiums amplifying margin pressure for mid-tier Chinese fabricators serving Jiangsu province cell plants.
Pricing Analysis
Distributor margin layers concentrate around 12-18% for European-bound equipment under EU AI Act compliance bundling, while direct-to-OEM procurement in China's Jiangsu-Guangdong corridor captures volume discounts tied to 4680-format line commitments. Three-tier pricing structure across premium, standard, and economy levels separates algorithmic transparency-certified European platforms from traceability-compliant domestic Chinese lines and non-certified legacy manual systems. Pricing pressure stems from mechatronics specialist scarcity inflating commissioning and service attach rates. Energy storage system buyers exhibit highest price sensitivity due to format flexibility requirements, whereas automotive cell producers absorb premium tiers for tension control precision.
Supply Chain Analysis
Single-source vulnerability sits with Japanese tension control sensor suppliers and German servo motor assemblies, exposing equipment lead times to export licensing delays. Manufacturing concentration clusters in China, Japan, and Germany, with Jiangsu province hosting cathode material plants that feed regional winding machine fabricators. Critical component dependencies include high-purity copper foil, ceramic-coated separators, and precision ball screw assemblies. Tariff exposure runs through EU-bound equipment shipments facing carbon border adjustment mechanism scrutiny. Distribution runs through direct OEM relationships for automotive-scale procurement and third-party financing vehicles for mid-tier cell producers in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in coating-winding integration platforms and EU AI Act compliance service bundles, as cell producers absorb 15-25% capital premiums for extended emissions certification.
For Market Incumbents: Lock in cathode plant adjacencies through Jiangsu-Guangdong service network density, prioritizing rapid commissioning cycles that offset solid-state cell substitution threats. Defend against emerging coating-winding convergence specialists by embedding closed-loop thermal oxidizer integration as standard configuration. Vertical integration into precision tension control sensor sourcing mitigates single-source vulnerability from Japanese component suppliers. For New Entrants and Emerging Players: Enter via energy storage system deployments in Germany and Hungary, where REACH-compliant equipment gaps persist among grid-scale battery integrators. White-space opportunity concentrates in hybrid system configurations for mid-tier Indian and Southeast Asian cell startups lacking balance sheet capacity for full automation. Go-to-market leverage rests on equipment-as-a-service contracting with throughput-based payment structures. For Investors and Strategic Acquirers: Consolidation pressure builds where coating-winding integration capabilities fragment across regional fabricators without algorithmic transparency certification. Long-term viability favors platforms with dual carbon disclosure compliance and 4680-format tooling flexibility. Acquisition target archetype: mid-cap European specialists with EU AI Act-compliant defect detection algorithms. Signal to watch: solid-state cell pilot line announcements from South Korean and Japanese automotive producers.| Strategic Initiative | Industry Significance |
|---|---|
| Coating-Winding Integration Platform Development | Reduces work-in-process inventory and cleanroom footprint for European automotive cell plants. |
| EU AI Act Algorithmic Transparency Certification | Enables automated defect detection revenue streams in Germany and Hungary cell facilities. |
| Jiangsu-Guangdong Service Network Expansion | Shortens technical response times for domestic Chinese electric vehicle battery producers. |
| Equipment-as-a-Service Contracting Model | Captures mid-tier Indian and Southeast Asian cell startup demand without ownership burden. |
| Precision Tension Control Sensor Backward Integration | Mitigates export licensing risk from Japanese and German single-source suppliers. |
Research Methodology
Direct dialogue with equipment procurement directors at cell plants, mechatronics engineering leads, cathode material plant managers, and aftermarket service heads grounded qualitative findings, cross-referenced with MIIT equipment certification databases, NMPA manufacturing safety filings, EU AI Act regulatory texts, and customs trade data for winding machine component flows. Bottom-up installation counts triangulated against top-down capital expenditure disclosures from battery producers across the analysis window.
Installed base projections and revenue estimates emerged from modeling across technology tiers, end-use segments, capacity configurations, and regional regulatory clusters throughout the forecast period. CAGRs derived from equipment shipment trajectories weighted by 4680-format ramp-up intensity and energy storage system deployment acceleration. Key inputs included electrode coating thickness roadmaps, dual carbon disclosure timeline enforcement, and solid-state cell pilot line announcements.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time equipment commissioning data and unannounced solid-state cell format transitions introduce uncertainty bands around outer-year projections. Forecasts reflect documented assumptions regarding GB standards enforcement continuity and REACH compliance boundary stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
FORTELION Battery Module Market
Batteries
Middle-East Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Forklift Battery Charger Market
Batteries
Battery Separators Market
Batteries
Battery Pack Balancer Market
Batteries
N-Type Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
HIT Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Second-Life Automotive Battery Module Systems Market