
 North Europe Renewable Energy Market | 2026-2036
North Europe Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
North Europe Renewable Energy Market Analytics
The gap between premium offshore wind projects and commodity onshore solar installations is expanding in North Europe. Ørsted AS leverages its integrated development model across the Danish and German North Sea to dominate high-margin offshore zones. Vestas Wind Systems AS sustains technology leadership through turbine scaling and grid integration capabilities. Statkraft AS anchors its position in Norwegian hydropower while navigating expansion into floating offshore wind.
North Europe renewable energy encompasses electricity and heat generation systems that harness wind, solar radiation, water flow, and organic feedstocks, typically operating at 33-45% capacity factors for offshore wind and 10-25% for utility solar depending on latitude and seasonal variation. The primary purpose is decarbonizing power and heating sectors while ensuring grid stability across interconnected Nordic and Baltic systems. Wind turbines command the largest installed base and capital allocation, with offshore variants capturing premium returns due to higher capacity factors and seabed lease scarcity. Solar panels represent the fastest-growing technology segment as Sweden and Finland deploy bifacial modules in agrivoltaic configurations. Hydropower systems remain the foundational baseload resource in Norway and parts of Sweden, though environmental permitting constrains new large-scale development.
The EU Green Deal, REPowerEU framework, and national carbon neutrality laws in Denmark, Sweden, and Finland are tightening emissions benchmarks and accelerating renewable procurement mandates for utilities and industrial offtakers. ECHA chemical registration requirements and national environmental impact assessments shape equipment material choices and project approval timelines. Grid operators in the region must balance interconnection upgrades with storage deployment to absorb variable generation. Stakeholders should monitor auction design evolution and cross-border cable commissioning schedules to time capital commitments effectively.
Market Dynamics
Offshore wind seabed lease scarcity in the Danish and German North Sea is concentrating capital deployment among integrated developers with grid connection capabilities, compressing project timelines and raising barriers for new entrants lacking transmission access.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:Denmark, Sweden, and Finland have enacted binding 2045-2050 net-zero laws that accelerate renewable procurement obligations for utilities and industrial offtakers, tightening emissions benchmarks annually.
- REPowerEU framework:This EU-wide initiative redirects subsidy flows toward hydrogen-ready offshore wind and biomethane injection, reshaping national auction design and grid priority rules across Nordic member states.
- Geothermal district heating:Copenhagen and Stockholm municipal networks are accelerating borefield deployment, displacing natural gas in dense urban heat loads through shallow and deep geothermal hybrid systems.
Market Restraints
- Neodymium-dysprosium supply concentration:Rare earth magnet dependence for direct-drive offshore turbines concentrates sourcing risk in Chinese processing capacity, exposing developers to export quota volatility and price spikes.
- ECHA REACH substance authorization:Epoxy resin systems and fire-retardant coatings face escalating registration costs and sunset clause timelines, extending equipment procurement lead times for turbine manufacturers.
- Interconnection queue congestion:TenneT and Energinet transmission upgrade schedules lag behind generation buildout, forcing developers to absorb curtailment risk or invest in co-located battery storage.
Strategic Opportunities
- Floating offshore wind in Norwegian deepwater:Equinor and Statkraft pilot projects at Hywind Tampen demonstrate commercial viability beyond fixed-foundation depth limits, opening acreage in the Norwegian Sea previously inaccessible.
- Agrivoltaic bifacial deployment:Southern Sweden and Finland are piloting elevated solar arrays over cereal crops, generating dual revenue streams for agricultural landowners while preserving soil carbon.
- Power-to-X offtake contracts:REPowerEU hydrogen import quotas are stimulating electrolyzer-backed wind PPAs, with Maersk and SAS signing synthetic fuel prepurchase agreements that de-risk capital-intensive project finance.
Industry Challenges
- High-voltage cable installation vessel scarcity:The specialized fleet for 220kV+ subsea export cables numbers fewer than ten units globally, creating bottlenecks for North Sea array commissioning schedules.
- Environmental permitting expertise gaps:National agencies in Norway and Sweden lack sufficient marine ecologists to process simultaneous offshore wind EIAs, extending approval timelines to 4-7 years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Europe Renewable Energy Market |
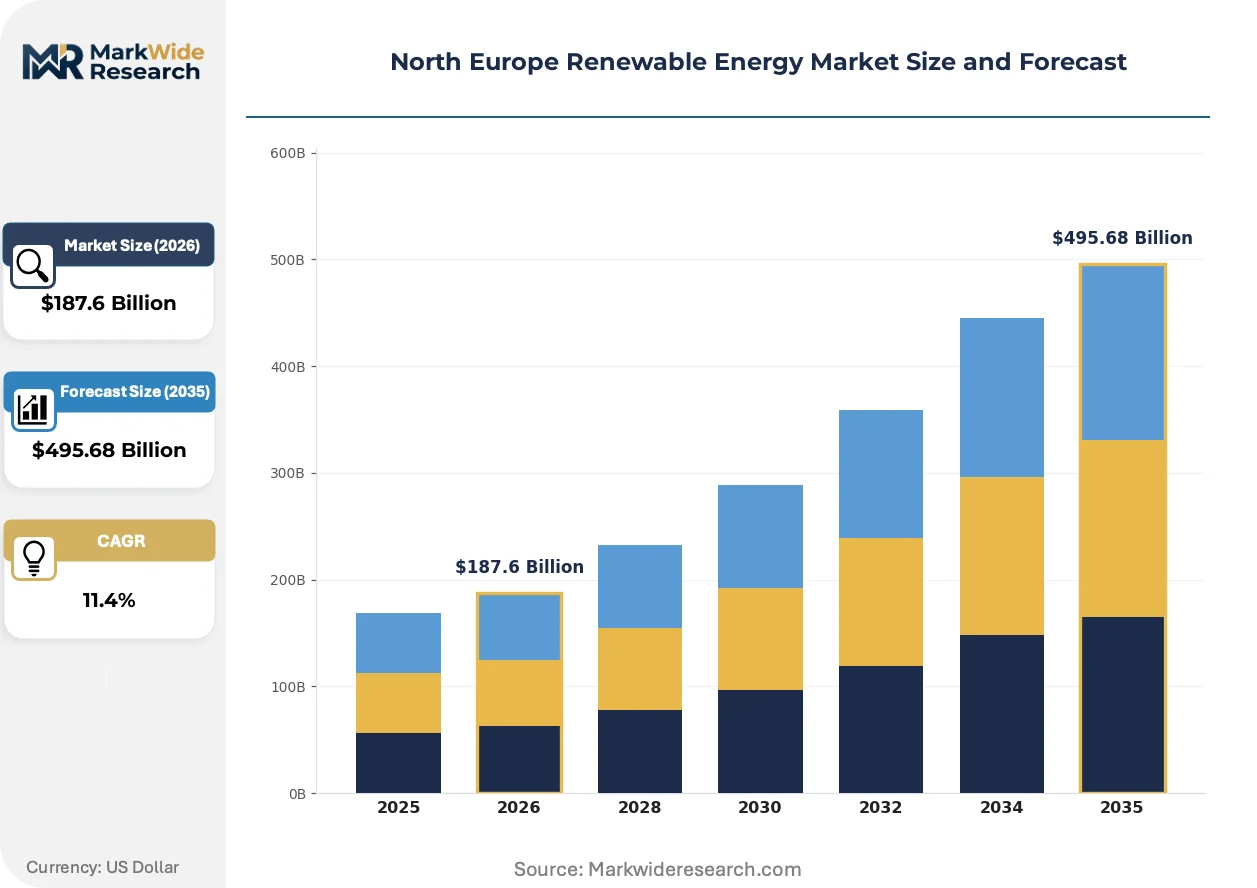
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wind Turbines, Solar Panels, Hydropower Systems, Biomass Reactors Application: Grid Supply, Off-Grid Solutions, Heating, Transportation Service Type: Installation, Maintenance, Consulting, Financing End User: Utilities, Industrial Sector, Commercial Buildings, Residential Users |
| Companies Covered | Ørsted AS, Vestas Wind Systems AS, Statkraft AS, Vattenfall AB, E-CO Energi Holding AS, RWE, ENGIE, EDP Renováveis, Acciona SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Europe Renewable Energy Market Evolving Landscape
Digital twin and predictive maintenance platforms are compressing offshore wind OPEX while floating foundation designs unlock deeper water sites previously excluded from development pipelines.
Modular high-temperature electrolyzer stacks are integrating with offshore wind substations to produce hydrogen at point of generation, eliminating costly cable runs to shore. Ørsted and RWE are piloting this configuration at Danish North Sea sites, enabling direct ammonia or e-methanol synthesis without grid interconnection delays. The approach is reshaping project economics by capturing otherwise curtailed generation and accessing premium industrial offtake contracts.
EU CSRD sustainability disclosure rules now mandate granular Scope 3 emissions reporting for listed utilities and energy developers, forcing supply chain audits of turbine blade recyclability and rare earth provenance. Danish and German regulators are embedding these standards into auction qualification criteria, disadvantaging developers with opaque subcontractor networks. Equipment suppliers are responding with blockchain-tracked material passports and certified recycled steel content.
Industrial offtakers in pulp, paper, and data center verticals are consolidating renewable procurement through long-term corporate PPAs rather than spot market exposure, compressing developer counterparty risk assessments. Stockholm and Helsinki data center clusters are driving this shift, requiring 24/7 carbon-free matching rather than annualized renewable energy certificates. This behavioral change is favoring developers with storage-hybrid offerings and firm generation profiles over intermittent-only projects.
North Europe Renewable Energy Market Segmentation
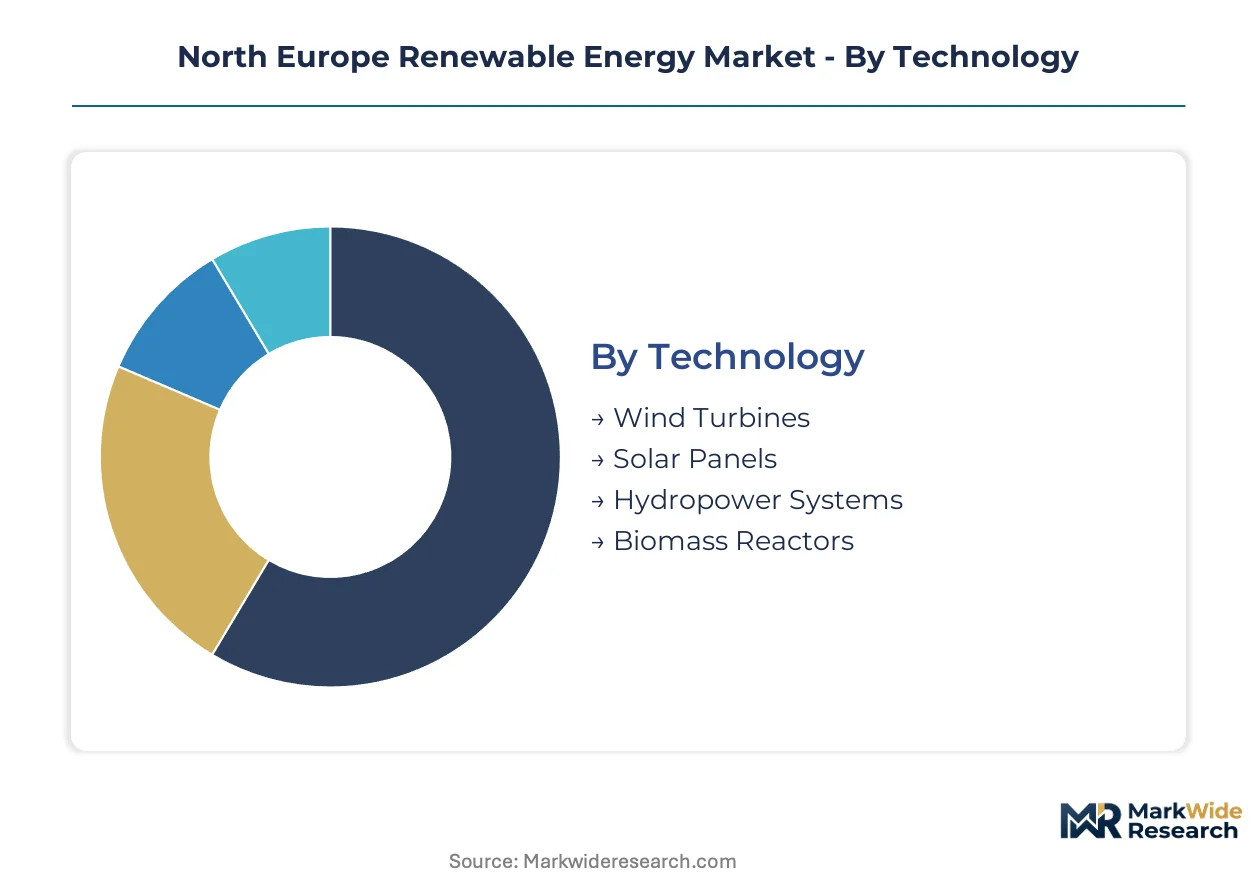
Technology and application splits in North Europe reveal divergent capital intensity profiles. Offshore wind demands integrated development capabilities while solar scales through distributed deployment models.
Technology:
Wind turbines and hydropower function as embedded baseload infrastructure requiring grid synchronization, while solar and biomass operate across standalone and integrated configurations depending on offtake contracts.
- Wind Turbines:Offshore variants with 12-15MW rated capacity dominate Danish and German North Sea lease rounds. Ørsted and RWE concentrate deployment in corridors with TenneT grid connection schedules, facing vessel scarcity for 220kV cable installation.
- Solar Panels:Bifacial modules mounted on elevated agrivoltaic structures are expanding across southern Sweden and Finland. Agricultural landowners secure dual revenue streams while preserving soil carbon under CSRD disclosure pressures.
- Hydropower Systems:Norwegian reservoirs provide 96% of national electricity supply. Statkraft manages run-of-river and pumped storage assets constrained by environmental permitting timelines.
- Biomass Reactors:Copenhagen and Stockholm district heating networks deploy combined heat and power units. Municipal utilities displace natural gas through organic feedstock combustion with guaranteed heat offtake.
Wind turbines lead volumes today; solar panels are gaining share fastest.
Application:
Cost tier separation distinguishes capital-heavy grid infrastructure from modular behind-meter deployments requiring minimal transmission investment.
- Grid Supply:Utility-scale generation feeding Nordic synchronous area demands HVDC interconnection upgrades. Developers absorb curtailment risk or co-locate battery storage as Energinet queues lengthen.
- Off-Grid Solutions:Remote industrial sites and island communities deploy hybrid wind-solar-battery configurations. Mining operators in northern Norway and Sweden sign direct PPAs bypassing distribution tariffs.
- Heating:District networks in Denmark and Sweden accelerate geothermal borefield deployment. Copenhagen municipality targets complete natural gas displacement through shallow and deep geothermal hybrids.
- Transportation:Electrolyzer-backed wind farms supply hydrogen for Maersk shipping and SAS aviation synthetic fuel contracts. REPowerEU quotas stimulate power-to-X offtake agreements de-risking project finance.
Grid supply commands capital deployment today; transportation applications are expanding most quickly.
Service Type:
Customer type fragmentation separates turnkey EPC contractors from recurring revenue service providers with divergent margin profiles.
- Installation:Turnkey EPC contracts for offshore wind arrays require specialized jack-up vessels and seabed preparation. Danish contractors face 4-7 year environmental approval timelines due to marine ecologist shortages at national agencies.
- Maintenance:Predictive analytics platforms using digital twin technology compress offshore wind OPEX. Vestas and Siemens Gamesa service agreements cover 20-25 year asset lifespans with availability guarantees.
- Consulting:Environmental impact assessment and grid connection advisory supports developer auction preparation. Firms navigate ECHA REACH substance authorization for epoxy resin systems and fire-retardant coatings.
- Financing:Green bond issuance and project finance structuring accommodates REPowerEU hydrogen-ready certification requirements. Institutional investors demand CSRD-aligned Scope 3 emissions disclosure from supply chain audits.
Installation captures largest contract values today; financing services are climbing the fastest.
End User:
Volume concentration versus margin premium splits the market between price-tolerant utilities and procurement-consolidated industrial offtakers.
- Utilities:State-owned and municipal generators in Denmark, Sweden, and Norway hold seabed leases and hydropower concessions. EU Green Deal binding net-zero laws tighten annual emissions benchmarks and renewable procurement obligations.
- Industrial Sector:Pulp, paper, and data center clusters in Stockholm and Helsinki sign 24/7 carbon-free matching PPAs. Operators reject annualized renewable energy certificates in favor of firm generation profiles with storage hybrids.
- Commercial Buildings:Corporate real estate in Copenhagen and Oslo deploys rooftop solar with battery backup. Lease structures pass through energy savings to tenants under green building certification requirements.
- Residential Users:Distributed solar and heat pump adoption accelerates through national subsidy schemes. Swedish and Finnish households access preferential financing for bifacial module installation with agrivoltaic compatibility.
Utilities dominate installed capacity today; industrial sector offtake is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine engineering specialists and offshore construction crews cluster around North Sea port cities, anchoring project execution capacity across the Nordic basin. This workforce concentration shapes capital deployment patterns and development timelines.
Norway
Equinor and Statkraft drive floating offshore wind pilots at Hywind Tampen in the Norwegian Sea. The Norwegian Water Resources and Energy Directorate oversees seabed licensing rounds. Stavanger anchors subsea engineering expertise for deepwater foundation deployment.
Denmark
Ørsted dominates Danish North Sea lease rounds through integrated development models. The Danish Energy Agency administers subsidy-free auction designs under EU Green Deal alignment. Copenhagen municipal utilities displace natural gas through geothermal district heating expansion.
Sweden
Vattenfall and municipal generators deploy bifacial agrivoltaic arrays across southern counties. The Swedish Energy Agency channels REPowerEU funds toward hydrogen-ready offshore zones. Stockholm data center clusters demand 24/7 carbon-free matching through corporate PPAs.
Germany
RWE concentrates capital in TenneT-connected North Sea corridors facing cable vessel scarcity. The Federal Network Agency implements offshore wind auction schedules tied to grid commissioning timelines. Hamburg port infrastructure supports heavy component staging for turbine installation.
Finland
Fortum and regional utilities scale elevated solar over cereal crops in agricultural zones. The Finnish Energy Authority administers national subsidy schemes for distributed generation. Helsinki metropolitan data centers drive firm renewable procurement with storage hybrid requirements.
North Europe Renewable Energy Market Competitive Landscape
Top-tier vendors anchor integrated offshore development, while specialized equipment suppliers and municipal utilities occupy distinct competitive tiers. The market structures around seabed lease holders with transmission access, turbine manufacturers with scaling capabilities, and state-backed generators with concession portfolios. Three archetypes dominate: integrated offshore developers, technology-agnostic EPC contractors, and hydropower incumbents diversifying into floating wind. Competitive moves concentrate on securing interconnection queue positions and forming power-to-X offtake consortia.
Within the integrated developer tier, Ørsted AS and RWE exemplify capital deployment concentration in premium offshore zones with grid priority access. Vestas Wind Systems AS occupies a position among turbine-scale technology providers serving multiple developer clients across the Danish and German North Sea. Statkraft AS anchors the state-backed generator archetype, leveraging Norwegian hydropower concessions while navigating floating wind expansion beyond fixed-foundation depth limits.
| Leading Market Players |
|---|
| Ørsted AS |
| Vestas Wind Systems AS |
| Statkraft AS |
| Vattenfall AB |
| E-CO Energi Holding AS |
| RWE |
| ENGIE |
| EDP Renováveis |
| Acciona SA |
| Others |
Value Network & Pricing Analysis
Integrated offshore developers with TenneT grid connection commitments command premium pricing power through bundled EPC and transmission services, while commodity solar module suppliers compete on unbundled component costs. This bifurcation concentrates margins in seabed lease holders and compresses returns for standardized equipment manufacturers facing Chinese import competition.
Pricing Analysis
Bundled full-service contracts for offshore wind arrays separate from unbundled solar module and inverter sales. Three-tier pricing structure across premium offshore zones, standard onshore wind, and economy solar installations reflects seabed scarcity and grid priority access. Cost compression in utility-scale solar intensifies because Chinese bifacial module imports flood Nordic markets. Municipal utilities show highest price sensitivity due to fixed-rate heat supply obligations, while data center operators accept premium firm-generation tariffs.
Supply Chain Analysis
Freight costs for 12-15MW turbine nacelles and 80-meter blades dominate landed equipment expenses, favoring port-proximate staging in Esbjerg and Hamburg. Manufacturing concentrates in Denmark, Germany, and China for turbine assemblies, with Norway anchoring subsea foundation fabrication. Rare earth magnet supply draws from Chinese processing capacity for direct-drive generators. Single-source vulnerability in neodymium-dysprosium refining exposes developers to export quota disruptions. Distribution runs through specialized heavy-lift vessel operators and HVDC cable installation fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North Europe renewable energy functions as a stable compounder anchored by binding EU Green Deal net-zero mandates that tighten annually regardless of macroeconomic cycles.
For Market Incumbents: To counter vessel scarcity bottlenecks in 220kV cable installation, Ørsted and RWE should secure long-term charter agreements with the specialized global fleet. Backward integration into foundation fabrication at Baltic port facilities reduces exposure to Korean and Chinese steel supply disruptions. Prioritize CSRD-aligned supply chain audits to maintain auction qualification eligibility as Danish and German regulators embed disclosure standards into bid criteria. For New Entrants and Emerging Players: REPowerEU hydrogen-ready certification in Germany and Denmark opens a window for electrolyzer-integrated wind developers to capture power-to-X offtake contracts. Floating offshore wind in Norwegian deepwater offers the most penetrable geography, with Statkraft pilot projects validating commercial viability beyond fixed-foundation limits. Enter through joint development agreements with municipal utilities seeking geothermal district heating partners in Copenhagen and Stockholm networks. For Investors and Strategic Acquirers: State-backed oil majors transitioning to offshore wind are the most active acquirer in this space, seeking development pipelines and seabed lease portfolios. Five-to-ten-year viability hinges on interconnection queue positions rather than generation assets alone. Monitor TenneT and Energinet transmission upgrade schedules as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Consolidation | Ørsted and RWE concentrate Danish North Sea positions to secure TenneT grid priority. |
| Floating Foundation Deployment | Equinor pilots at Hywind Tampen unlock Norwegian Sea acreage beyond fixed-foundation depths. |
| Power-to-X Integration | Electrolyzer-backed wind farms supply Maersk and SAS synthetic fuel contracts under REPowerEU quotas. |
| Agrivoltaic Bifacial Expansion | Southern Swedish landowners generate dual revenue streams through elevated solar over cereal crops. |
| CSRD Supply Chain Audit | Blockchain-tracked material passports satisfy EU disclosure mandates embedded in auction qualification. |
Research Methodology
Coverage spans Norway, Denmark, Sweden, Germany, and Finland, with primary inputs from each market. The research combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from IEA reports, EIA data, FERC filings, and project development databases. Bottom-up capacity and installation forecasts triangulate against top-down regulatory mandate analysis.
Rate-of-change decomposition separates technology cost curves from policy-driven deployment acceleration across the analysis window. The analytical framework models segmentation by fuel source, generation capacity tier, project scale, and regional grid type. CAGRs derive from installed base trajectories, auction schedule pipelines, and interconnection commissioning timelines. Forecast inputs incorporate seabed lease round schedules and REPowerEU hydrogen import quota implementation.
Revisions become necessary when transmission upgrade delays, rare earth export restrictions, or marine permitting backlogs materialize beyond baseline assumptions. Forecasts reflect documented expectations regarding vessel fleet expansion and environmental agency staffing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Heating Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Solar Watch Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Hybrid Power System Market