
 Deep Cycle Battery Market | 2026-2036
Deep Cycle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Cycle Battery Market Outlook
Skilled battery electrochemist availability is collapsing across North American and European manufacturing zones, forcing producers to automate or relocate technical operations. CATL sustains cost leadership through vertical integration into cathode precursors and separator production. LG Energy Solution anchors premium supply contracts with marine and stationary storage OEMs in Europe and North America. Samsung SDI differentiates via high-nickel NCM cell architectures for performance-intensive applications.
Deep cycle batteries are rechargeable electrochemical storage devices engineered for sustained discharge cycles at high depth-of-discharge, typically constructed with thick plate electrodes, antimonial or calcium alloy grids, and electrolyte formulations optimized for cycle life rather than cranking power. Lithium-ion chemistries now lead product type growth due to superior energy density and cycle longevity, while lead acid retains cost-sensitive segments in emerging markets. Marine and renewable energy storage applications command the fastest expansion, with off-grid installation configurations capturing margin pools in remote and islanded power systems.
EPA emissions rules and OSHA workplace safety standards govern US battery manufacturing facilities, while the EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds for market access. China's MIIT enforces GB standards for cell safety and performance certification. Stakeholders must monitor evolving chemistry-specific compliance timelines and build qualification pathways before regional mandates harden into trade barriers.
Market Dynamics
Lithium-ion cell chemistry is fragmenting competitive boundaries between marine propulsion and stationary storage applications, forcing incumbent lead-acid manufacturers to defend margin pools in forklift and telecom backup segments.
Growth Catalysts
- US Inflation Reduction Act:Production tax credits for domestic battery cell manufacturing are accelerating capital deployment into Michigan and Nevada gigafactory sites.
- Marine electrification:Harbor authorities in Rotterdam and Singapore are mandating shore power and electric tugboat specifications that require high-cycle lithium storage.
- Off-grid solar:Islanded microgrids in Southeast Asia and Sub-Saharan Africa are bypassing diesel gensets entirely for solar-plus-storage configurations.
Market Restraints
- Lithium carbonate volatility:Chilean and Australian spodumene concentrate pricing swings compress cell producer margins unpredictably.
- Chinese supply concentration:Cathode precursor refining clusters in Jiangsu province create single-point vulnerability for non-Chinese pack assemblers.
- Lead-acid residual cost advantage:Flooded and AGM variants retain total-cost-of-ownership superiority in price-sensitive forklift leasing pools.
Strategic Opportunities
- Second-life automotive packs:Retired EV batteries from Nissan and Tesla vehicles are repurposing into stationary storage at 40-60% of new cell cost.
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are drawing Samsung SDI and BYD toward Gujarat and Tamil Nadu.
- EU Battery Regulation:Mandatory recycled content thresholds and carbon footprint labeling create first-mover advantage for European cell producers with closed-loop supply chains.
Industry Challenges
- Electrochemist scarcity:North American and European manufacturing zones face collapsing availability of PhD-level battery scientists, forcing automation of R&D functions.
- GB standard compliance:China's MIIT certification timelines for new cell formats delay product launches by 12-18 months versus domestic competitors.
- Legacy system integration:Marine and telecom customers require backward compatibility with 48V and 24V DC architectures, complicating lithium pack design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Cycle Battery Market |
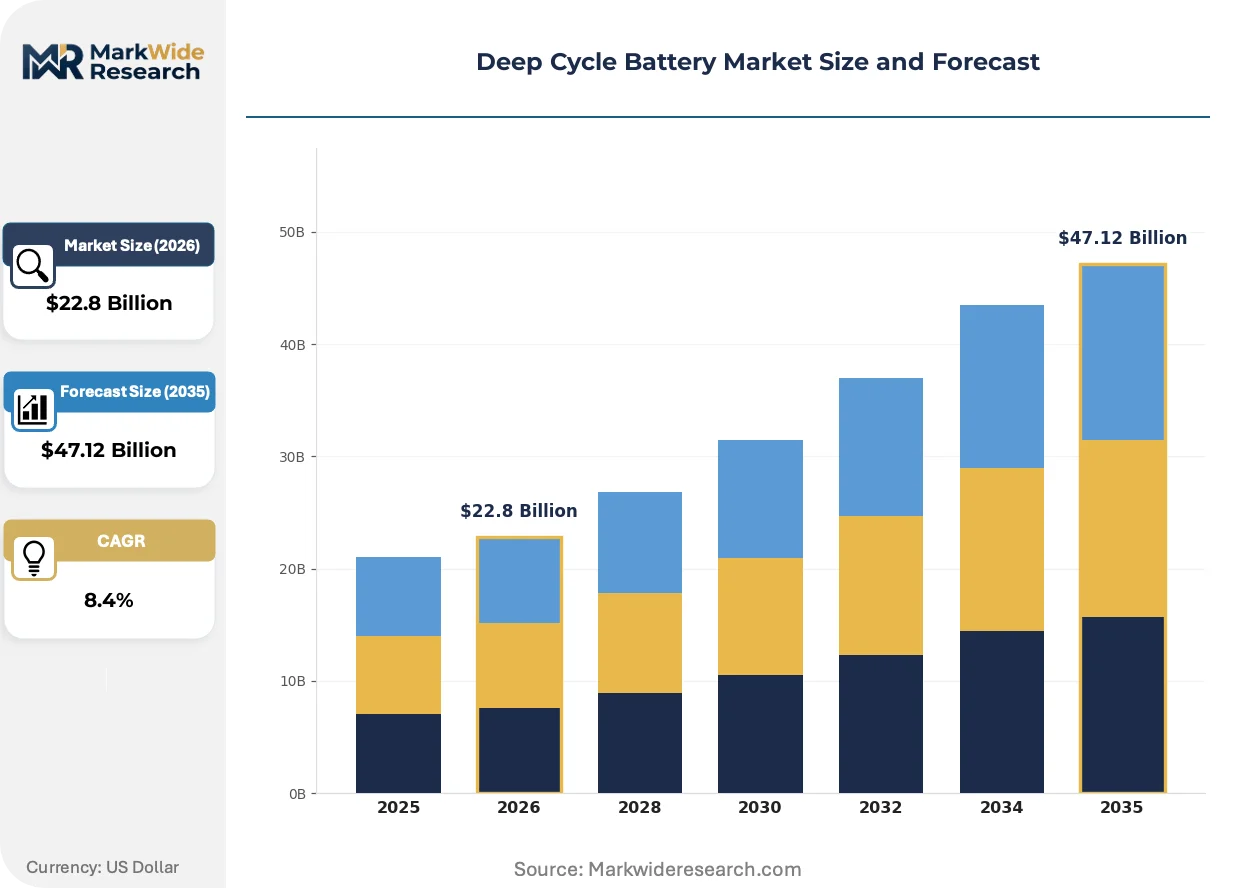
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-Ion, AGM, Gel Application: Renewable Energy Storage, Marine, Electric Vehicles, UPS End User: Residential, Commercial, Industrial, Transportation Installation: On-grid, Off-grid, Portable, Fixed |
| Companies Covered | SK On, EVE Energy, CATL, Gotion High-Tech, Samsung SDI, BYD, Panasonic, Sunwoda, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Cycle Battery Market Strategic Shifts
Solid-state electrolyte research, sodium-ion commercialization, and AI-driven battery management systems are simultaneously advancing, creating overlapping technology waves rather than a single dominant trajectory.
Lithium iron phosphate chemistry is fragmenting the utility-scale storage segment from premium nickel-manganese-cobalt variants. Grid operators in Texas and California are specifying LFP for 4-8 hour duration applications where energy density matters less than cycle stability and thermal safety. This chemistry divergence is enabling Chinese cell producers to bypass Korean competitors' high-nickel IP positions entirely.
The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds for market access starting in 2027. Cell producers must document lifecycle emissions from mining through manufacturing, with stricter thresholds tightening in 2030 and 2035. European marine OEMs and stationary storage integrators are qualifying suppliers now to avoid supply disruption when compliance becomes mandatory.
Direct-to-installer procurement is compressing distribution layers in residential solar-plus-storage markets. California and Australian installers are bypassing traditional electrical distributors to source battery packs directly from contract manufacturers, capturing margin that previously accrued to wholesale channels. This channel disintermediation is most visible in sub-20kWh residential systems where installation simplicity reduces technical support requirements.
Deep Cycle Battery Market Segmentation
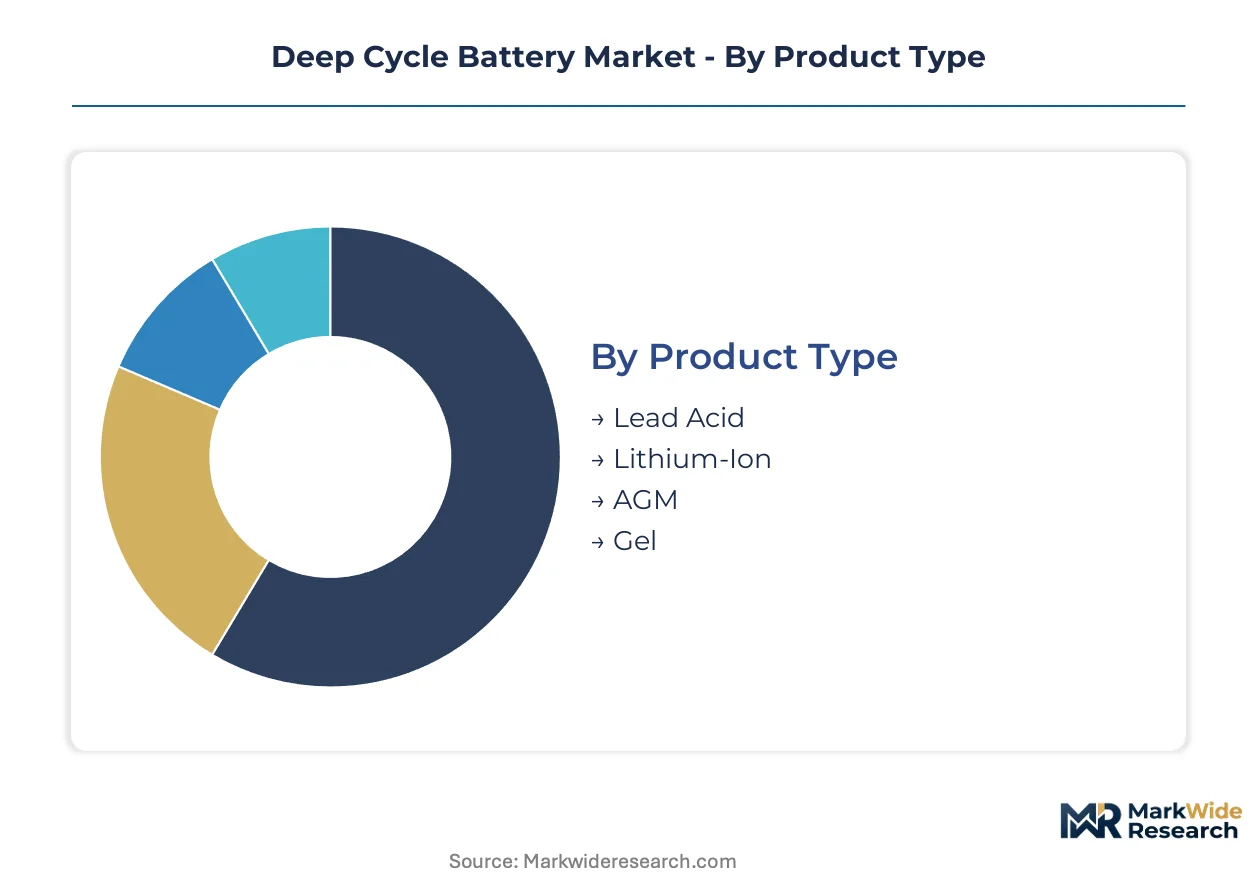
Segmentation in the deep cycle battery market reveals how chemistry choices, application requirements, and installation constraints fragment procurement patterns. Understanding these divisions exposes where cell producers can defend margin pools against commoditization pressures.
Product Type:
Margin concentration tracks chemistry sophistication, with premium lithium-ion formats commanding pricing power against legacy lead-acid alternatives.
- Lithium-Ion:High-energy-density cells utilizing nickel-manganese-cobalt or lithium iron phosphate cathodes deliver 3,000-6,000 cycles at 80% depth-of-discharge. Marine electrification in Rotterdam harbor and utility-scale solar in Texas are concentrating procurement of LFP variants for thermal stability.
- Lead Acid:Thick-plate flooded or valve-regulated designs with antimonial grids provide 500-1,200 cycles at lower capital cost. Forklift leasing pools in price-sensitive emerging markets retain this chemistry for total-cost-of-ownership advantages.
- AGM:Absorbent glass mat separators enable maintenance-free operation with improved cycle life over flooded equivalents. Telecom backup installations in remote sites favor this format for reduced servicing requirements.
- Gel:Silica-thickened electrolyte formulations resist stratification and tolerate deep discharge better than standard AGM. Off-grid solar in Sub-Saharan Africa deploys gel cells for temperature resilience.
The dominant share belongs to lead-acid formats, while lithium-ion is closing the gap fastest.
Application:
Application-driven segmentation separates stationary storage from mobile power, with divergent performance specifications creating distinct supplier qualification pathways.
- Renewable Energy Storage:Grid-tied and islanded solar-plus-storage configurations require 4-8 hour discharge duration with daily cycling capability. California and Texas grid operators are specifying lithium iron phosphate for utility-scale installations.
- Marine:Electric propulsion and auxiliary power systems demand vibration resistance, salt corrosion tolerance, and high peak discharge capability. Singapore and Rotterdam harbor authorities are mandating shore power compatibility that accelerates lithium adoption.
- Electric Vehicles:Secondary traction batteries for low-speed electric vehicles and conversion kits require compact packaging and rapid recharge acceptance. Southeast Asian two-wheeler electrification is expanding this segment.
- UPS:Uninterruptible power supply applications prioritize standby float life and instantaneous switchover over deep cycling. Data center operators in Northern Virginia specify this format for backup reliability.
Renewable energy storage holds the largest volume position, though marine applications are expanding most quickly.
End User:
End-user categories stratify by procurement scale and technical sophistication, from individual residential buyers to industrial fleet operators.
- Industrial:Material handling fleets, telecom infrastructure, and manufacturing facilities purchase through multi-year supply agreements with stringent qualification protocols. Warehouse operators in Michigan and Nevada are electrifying forklift fleets under IRA production credit incentives.
- Commercial:Retail, hospitality, and office building operators seek behind-the-meter storage for demand charge management. California commercial solar installers are bypassing distributors for direct manufacturer procurement.
- Residential:Homeowners deploying solar-plus-storage systems prioritize installation simplicity and warranty terms over technical specifications. Australian and California markets show strongest penetration here.
- Transportation:Marine vessel operators, RV owners, and specialty vehicle fleets require dual-purpose or deep-cycle optimized designs. Electric tugboat specifications in European ports are reshaping this category.
Industrial end users command the dominant procurement volume, while residential adoption is climbing the fastest.
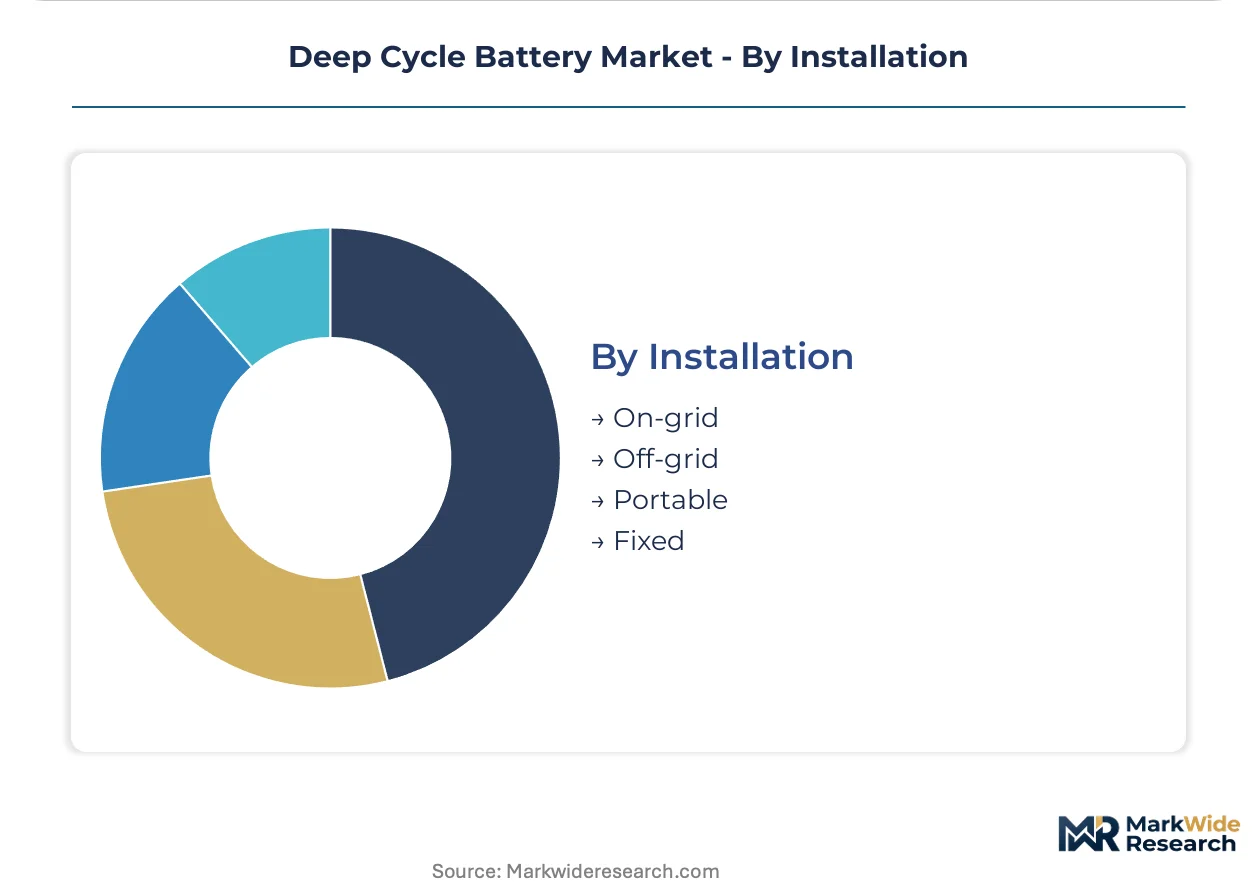
Installation:
Installation type determines system architecture complexity and regulatory compliance pathways, from utility-interconnected to fully autonomous configurations.
- Off-grid:Standalone power systems combining solar arrays, battery banks, and inverters operate without utility interconnection. Islanded microgrids in Southeast Asia and Sub-Saharan Africa are bypassing diesel gensets entirely for these configurations.
- On-grid:Grid-tied storage enables net metering participation, frequency regulation services, and backup power during outages. Texas and California markets dominate this installation type.
- Fixed:Permanently mounted battery systems in utility-scale or commercial installations require concrete pads, climate-controlled enclosures, and fire suppression systems. Gigafactory-scale production in Nevada and Michigan supplies this segment.
- Portable:Mobile power stations and recreational vehicle battery systems emphasize weight reduction and plug-and-play connectivity. Camping and outdoor recreation markets in Australia and the western United States drive demand here.
Fixed installations retain the dominant share, yet off-grid configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification requirements in China anchor the dominant geography, with GB standards enforcement creating compliance timelines that delay non-domestic product launches. Regional procurement patterns diverge sharply between subsidy-driven manufacturing zones and markets where carbon footprint disclosure mandates reshape supplier qualification.
United States
Marine electrification in California ports and IRA production tax credits in Michigan and Nevada are accelerating lithium cell manufacturing deployment. EPA emissions rules and OSHA workplace safety standards govern facility operations. Gigafactory construction in the Mountain West and Midwest concentrates cathode and cell production near raw material processing hubs.
China
Dual carbon goals and MIIT GB standards enforcement redirect manufacturing toward cleaner chemistries in Jiangsu and Guangdong provinces. CATL, BYD, and EVE Energy operate gigafactories that supply domestic and export markets. Cathode precursor refining clusters in Jiangsu province create supply concentration that non-Chinese pack assemblers must navigate.
Germany
EU Battery Regulation carbon footprint thresholds and recycled content mandates drive qualification activity among marine OEMs and stationary storage integrators. ECHA chemical safety protocols and REACH compliance govern material inputs. Industrial battery demand concentrates in Bavaria and Baden-Württemberg automotive supplier networks.
South Korea
High-nickel NCM cell architectures for performance-intensive applications anchor premium supply positioning. MFDS and METI coordination on safety standards shapes export compatibility. Samsung SDI and LG Energy Solution manufacturing in the Seoul Capital Area supplies European and North American marine and stationary storage contracts.
India
PLI scheme production-linked incentives for advanced chemistry cell manufacturing draw Samsung SDI and BYD toward Gujarat and Tamil Nadu. BIS certification requirements and CEA grid interconnection standards govern product approval. Off-grid solar deployment in Rajasthan and Karnataka bypasses diesel gensets for solar-plus-storage configurations.
Deep Cycle Battery Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with chemistry sophistication separating premium positioning from commodity supply. The vendor base concentrates around three strategic groupings: vertically integrated Chinese producers with captive precursor supply, Korean specialists in high-nickel architectures, and diversified electronics conglomerates with automotive heritage. Dominant competitive moves include backward integration into cathode materials and geographic diversification of cell manufacturing to qualify for regional content requirements.
Within the integrated manufacturing tier, CATL and BYD represent cost-optimized scale archetypes with in-house precursor production. Samsung SDI exemplifies premium-tier positioning through high-nickel chemistry specialization. LG Energy Solution anchors mid-market supply with diversified end-use coverage across marine and stationary applications.
| Leading Market Players |
|---|
| SK On |
| EVE Energy |
| CATL |
| Gotion High-Tech |
| Samsung SDI |
| BYD |
| Panasonic |
| Sunwoda |
| LG Energy Solution |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between cathode precursor suppliers and Michigan gigafactory operators lock in lithium carbonate supply visibility while capping price volatility exposure for cell producers qualifying under IRA domestic content rules. These contractual structures simultaneously secure raw material access and compress working capital requirements for vertically integrated manufacturers expanding in Nevada and Arizona.
Pricing Analysis
Price spreads between Jiangsu-produced LFP cells and Korean-manufactured high-nickel NCM packs exceed 30% at equivalent energy capacity, reflecting chemistry-specific processing cost differentials. Three-tier pricing structure across premium marine certification, standard utility-scale, and economy forklift leasing segments tracks UL 1973 and IEC 62619 compliance tiers. Cost compression in standard-tier utility storage is intensifying because Chinese LFP producers are bypassing distributor markups through direct installer contracts. Forklift leasing pools in emerging markets exhibit highest price sensitivity, while Rotterdam harbor electric tugboat specifications show lowest.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are inflating inbound logistics costs for European pack assemblers sourcing cathode precursors from Jiangsu province. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material production anchored in Chinese refining clusters. The supply chain draws from Australian spodumene concentrate, Chilean lithium brine, and Indonesian nickel laterite. Single-source vulnerability in Jiangsu precursor refining creates qualification delays for non-Chinese pack assemblers. Distribution runs through direct manufacturer-to-installer channels in residential solar-plus-storage and traditional electrical distributors in industrial UPS applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deep cycle battery market operates as a defensive-moat industry where regulatory entrenchment through IRA domestic content rules and EU Battery Regulation carbon footprint thresholds creates durable switching costs for qualified suppliers.
For Market Incumbents: Shield market position through captive cathode precursor production in Michigan and Nevada to secure IRA tax credit eligibility. Accelerate GB standard pre-certification for new cell formats to compress China market entry timelines against domestic competitors. Invest in closed-loop recycling infrastructure to meet EU Battery Regulation recycled content thresholds before 2027 compliance deadlines. For New Entrants and Emerging Players: After-sales service networks for marine vessel operators represent a service-layer gap where incumbent cell producers under-serve with technical support. Target India PLI scheme qualification through Gujarat or Tamil Nadu manufacturing partnerships to access production-linked incentives. Penetrate Sub-Saharan African off-grid solar configurations where diesel genset displacement creates first-mover advantage for solar-plus-storage integrators lacking established supplier relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale cell producers with captive cathode precursor supply and existing marine OEM qualification pathways. Long-term viability over the projection horizon favors manufacturers with demonstrated compliance across IRA, EU Battery Regulation, and MIIT GB standards simultaneously. Monitor sodium-ion chemistry commercialization timelines as inflection indicator for lithium-ion substitution risk in price-sensitive stationary storage applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captive lithium carbonate processing in Nevada secures IRA domestic content credit eligibility for cell producers. |
| GB Standard Pre-Certification Investment | Early MIIT compliance pathways compress product launch timelines versus non-domestic competitors in China. |
| Closed-Loop Recycling Infrastructure | EU Battery Regulation recycled content mandates create qualification advantage for European marine OEM contracts. |
| Direct Installer Channel Development | Bypassing electrical distributors in California residential solar captures margin previously accruing to wholesale channels. |
| Sodium-Ion Chemistry R&D Partnership | Alternative chemistry positioning hedges against lithium carbonate volatility in price-sensitive forklift leasing segments. |
Study Parameters
Operator-level perspectives from marine procurement officers, off-grid solar installers, gigafactory operations managers, and cathode precursor trading desks anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from EIA battery storage deployment data, IEA renewable integration reports, MIIT GB standard filings, and EU Battery Regulation implementation guidance. Bottom-up cell production capacity modeling triangulated against top-down renewable energy storage procurement forecasts.
Sensitivity analysis across lithium carbonate price scenarios, IRA credit phase-out assumptions, and EU carbon footprint threshold stringency shaped the analytical framework. Segmentation dimensions modeled include chemistry type, application end-use, installation configuration, and regional regulatory cluster. CAGRs were derived through regression analysis of historical procurement patterns against policy incentive trajectories. Key forecast inputs span harbor electrification mandates in Rotterdam and Singapore, plus India PLI scheme capacity deployment timelines.
Forecasts assume regulatory continuity in IRA tax credit structures, EU Battery Regulation enforcement schedules, and MIIT GB standard certification timelines; material policy shifts would require re-modeling. Specific risks that could revise projections include lithium supply nationalization in Chile, accelerated sodium-ion commercialization displacing LFP in utility storage, or marine electrification mandate delays in European ports. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Atomic Battery Market
Batteries
India Battery Cell Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Secondary Battery Market
Batteries
North Europe Battery Market
Batteries
Micro Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Military Battery Market
Batteries
India Micro Batteries Market
Batteries
North America Rechargeable Battery Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
US Solar Battery Market