
 Vanadium Redox Flow Batteries (VRFB) Market | 2026-2036
Vanadium Redox Flow Batteries (VRFB) Market Size, Share, and Industry Trends Forecast 2026-2036
Vanadium Redox Flow Batteries (VRFB) Market Analytics
Australia is fragmenting into multiple VRFB demand clusters as mining operators and renewable developers pursue independent storage procurement. VRB Energy leverages its vanadium supply partnerships to anchor project economics across Pacific installations. Rongke Power sustains manufacturing scale through captive electrolyte production and domestic Chinese project pipelines. Invinity Energy Systems differentiates through modular architecture that reduces on-site commissioning complexity for industrial offtakers.
Vanadium Redox Flow Batteries employ aqueous vanadium electrolyte solutions in electrochemical cells where energy capacity scales independently from power rating through external tank sizing. The technology achieves over 20,000 charge cycles with minimal capacity degradation, serving primarily as long-duration storage for grid stabilization and renewable firming. Grid-Scale Systems command the dominant revenue share due to capital intensity and extended discharge requirements from utility purchasers. Energy Storage Systems applications attract the fastest growth trajectory as developers pair VRFB assets with solar and wind generation seeking shiftable output. Industrial Facilities end users generate concentrated margin pools where on-site reliability requirements justify premium pricing for customized integration.
China's MIIT enforces GB standards for battery energy storage system safety and grid connection compatibility, shaping product certification requirements for manufacturers targeting domestic deployment. The EU Green Deal and F-Gas Regulation indirectly steer European developers toward aqueous chemistries including vanadium flow systems for utility storage procurement. Australia's CEA and state-level regulators mandate storage co-location standards for remote renewable projects, creating compliance-driven demand corridors. Stakeholders must monitor electrolyte cost volatility and vanadium feedstock sourcing concentration as decisive variables in project bankability assessments.
Market Dynamics
Vanadium electrolyte supply concentration in China and Russia is forcing battery manufacturers to secure captive feedstock through long-term offtake agreements or backward integration into mining assets, reshaping project economics and procurement timelines across utility-scale deployments.
Growth Catalysts
- China's dual carbon goals:The MIIT's GB standards for grid-connected energy storage mandate safety and interconnection protocols that directly expand domestic VRFB procurement pipelines for renewable integration projects.
- Remote mining electrification:Australian mining operators in Western Australia and Queensland deploy VRFB systems to displace diesel generation, creating compliance-driven demand corridors under CEA storage co-location mandates.
- Aqueous chemistry preference:The EU F-Gas Regulation restricts fluorinated electrolytes in utility-scale batteries, steering European developers toward vanadium flow systems for long-duration storage tenders.
Market Restraints
- Vanadium price volatility:Feedstock costs fluctuate with steel alloy demand cycles, compressing project margins when vanadium pentoxide prices spike above electrolyte production thresholds.
- System footprint requirements:External tank sizing for multi-hour discharge duration demands substantial land allocation, limiting deployment in dense urban substations and constrained industrial sites.
- Lithium-ion substitution pressure:Compressed lithium iron phosphate pricing from Chinese manufacturing scale-up threatens VRFB competitiveness in 2-4 hour duration segments.
Strategic Opportunities
- Industrial microgrids:Data centers and semiconductor fabs in Taiwan and South Korea seek 8-12 hour backup duration, opening premium pricing segments where cycle life economics outweigh capex premiums.
- Electrolyte leasing models:Third-party ownership of vanadium electrolyte assets separates energy capacity costs from power hardware, reducing upfront capital barriers for municipal utilities.
- Hybrid renewable pairing:Solar-wind-battery configurations in South Africa's Northern Cape and Eastern Cape provinces leverage VRFB duration to firm intermittent generation for mining offtakers.
Industry Challenges
- Electrochemical engineering talent scarcity:Flow battery stack design and membrane optimization require specialized expertise concentrated in Chinese and Japanese research institutions, constraining Western manufacturing scale-up.
- Extended certification timelines:Utility interconnection approval processes for novel storage chemistries stretch 18-24 months in fragmented US state regulatory environments, delaying revenue recognition.
- Legacy SCADA integration complexity:VRFB control systems must interface with existing grid operator dispatch protocols, requiring custom software development for each utility procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanadium Redox Flow Batteries (VRFB) Market |
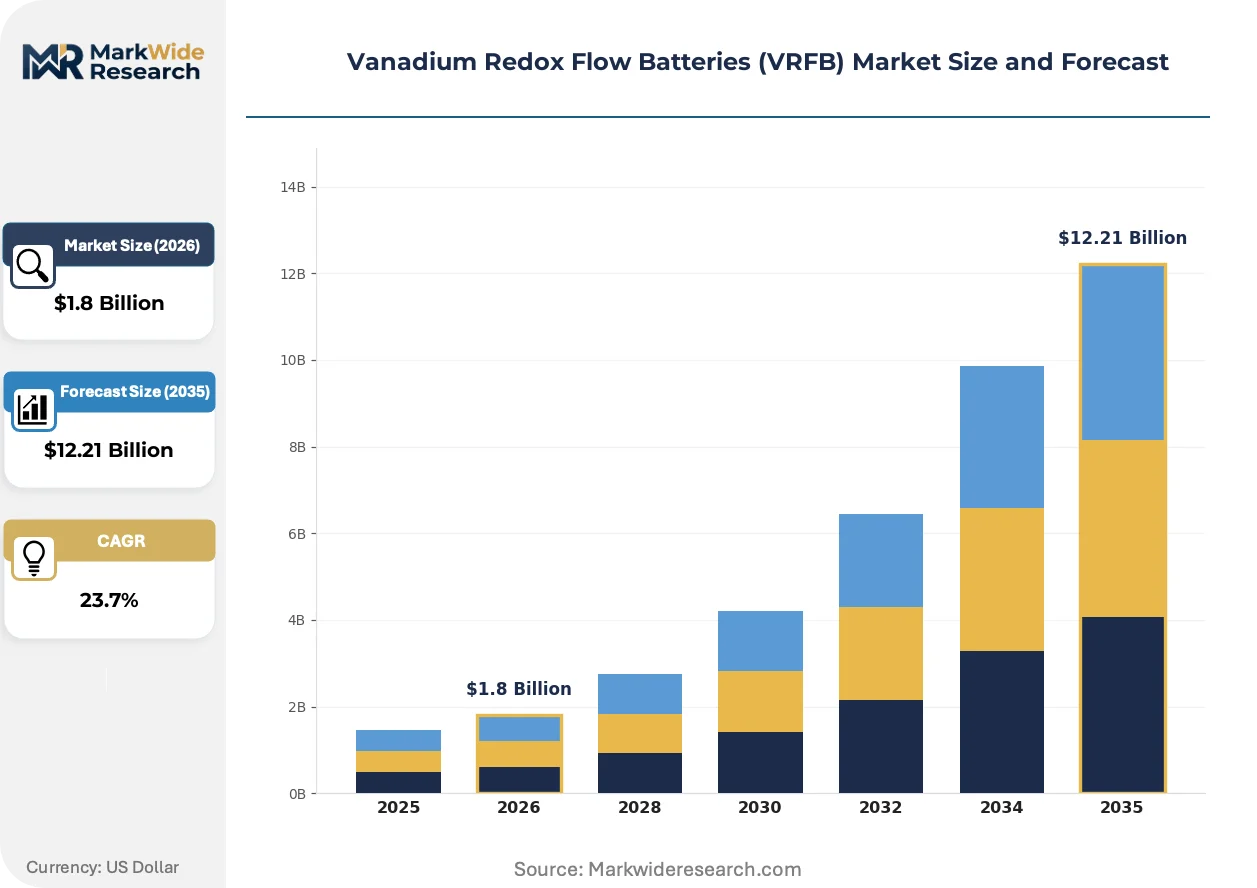
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Batteries, Portable Batteries, Hybrid Systems, Grid-Scale Systems Application: Energy Storage Systems, Renewable Integration, Remote Power Supply, Backup Power Solutions End User: Utilities, Commercial Infrastructure, Industrial Facilities, Residential Users Technology: Electrochemical Systems, Flow Systems, Charge Management Systems, Monitoring Systems |
| Companies Covered | VRB Energy, Largo Inc., Rongke Power, ESS Inc., SCHMID Group, Sumitomo Electric Industries, CellCube (Enerox GmbH), Shanghai Electric, Invinity Energy Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanadium Redox Flow Batteries (VRFB) Market Evolving Landscape
Stack architecture and electrolyte management systems are digitizing operational parameters, compressing maintenance cycles and enabling predictive performance optimization across dispersed utility assets.
Membrane-less cell designs employing laminar flow principles are digitizing capital cost structures by eliminating perfluorinated ion exchange materials, the single most expensive stack component. Australian and Chinese pilot installations validate 15-20% stack cost reduction. Industrial offtakers in mining and metals processing prioritize these architectures for remote deployments where membrane replacement logistics prove prohibitive.
The EU CSRD and accompanying taxonomy technical screening criteria classify long-duration storage as sustainable economic activity, digitizing capital allocation toward aqueous flow chemistries. European development finance institutions now mandate technology eligibility under green bond frameworks. German and Spanish utility tenders increasingly specify 6+ hour duration requirements that exclude lithium-ion competitors.
Energy-as-a-service contracting is displacing traditional equipment purchase models for C&I storage deployments. Mining operators in Chile's Atacama Desert and Australia's Pilbara region contract for guaranteed availability rather than capital ownership. This transfers performance risk to system integrators while accelerating deployment velocity for cash-constrained remote operations.
Vanadium Redox Flow Batteries (VRFB) Market Segmentation
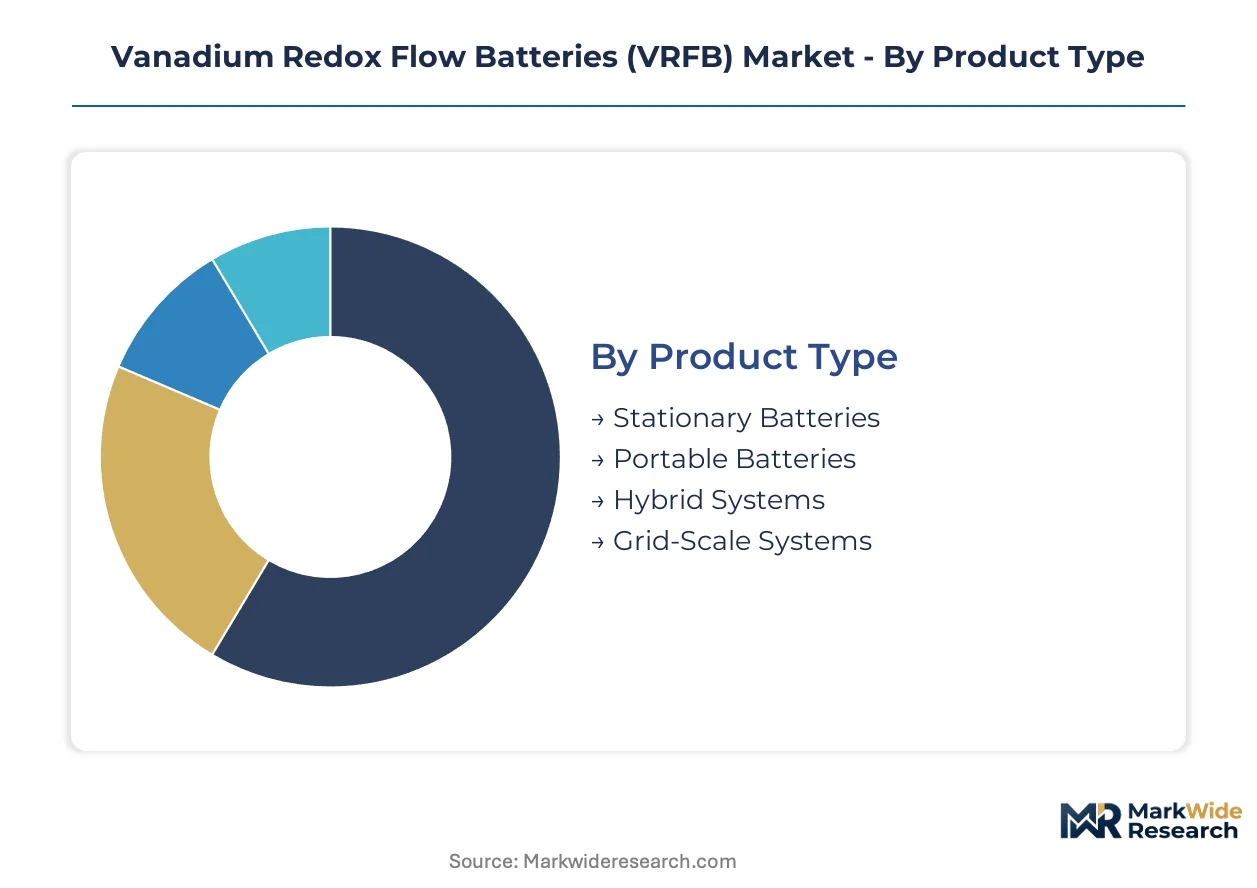
VRFB market segmentation reveals how power rating independence from energy capacity creates distinct procurement patterns across stationary and mobile applications. Each category reflects divergent capital intensity tolerances, cycle life requirements, and integration complexity thresholds that shape supplier positioning.
Product Type:
Cost tier differentiation separates mass-manufactured stationary units from bespoke grid-scale installations requiring extended discharge architectures.
- Stationary Batteries:Fixed-installation units with standardized tank configurations serve commercial and light industrial microgrids. Australian mining camps in Queensland deploy these for diesel displacement under CEA co-location mandates.
- Portable Batteries:Modular containerized systems enable rapid redeployment across construction sites and temporary extraction operations. Remote South African platinum mines lease these units through energy-as-a-service contracts to avoid capital ownership.
- Hybrid Systems:Integrated VRFB-solar or VRFB-wind configurations optimize land use for constrained sites.
- Grid-Scale Systems:Multi-megawatt installations with external tank farms dominate utility procurement pipelines.
Grid-Scale Systems holds installed capacity. Hybrid Systems is rotating up the share rankings.
Application:
Application focus determines whether procurement prioritizes discharge duration, response speed, or integration density with existing generation assets.
- Energy Storage Systems:Grid-connected assets providing frequency regulation and peak shaving command premium pricing from utilities seeking 6+ hour duration. German network operators specify these systems under EU taxonomy-aligned tenders.
- Renewable Integration:Solar-wind pairing applications firm intermittent output for mining offtakers in Chile's Atacama and Australia's Pilbara. The segment climbs fastest as developers seek shiftable generation capacity.
- Remote Power Supply:Off-grid installations displace diesel generation in extraction and processing operations.
- Backup Power Solutions:Critical facility protection for data centers and semiconductor fabs demands instantaneous switching capability.
Energy Storage Systems anchors procurement volume. Renewable Integration is climbing the fastest.
End User:
Customer type governs contract structure, with utilities favoring equipment purchase and industrial offtakers migrating toward performance-based service agreements.
- Utilities:Transmission system operators procure multi-hour duration assets for grid stabilization. China's State Grid and Southern Power Grid dominate procurement under MIIT GB standards for grid-connected storage.
- Industrial Facilities:Mining, metals processing, and chemical plants seek 8-12 hour backup duration where cycle life economics outweigh upfront capital premiums. Taiwanese semiconductor fabs represent concentrated demand.
- Commercial Infrastructure:Data centers and logistics hubs deploy mid-scale systems for demand charge management.
- Residential Users:Limited penetration due to footprint constraints and capital intensity relative to lithium alternatives.
Utilities command procurement scale. Industrial Facilities is expanding most quickly.
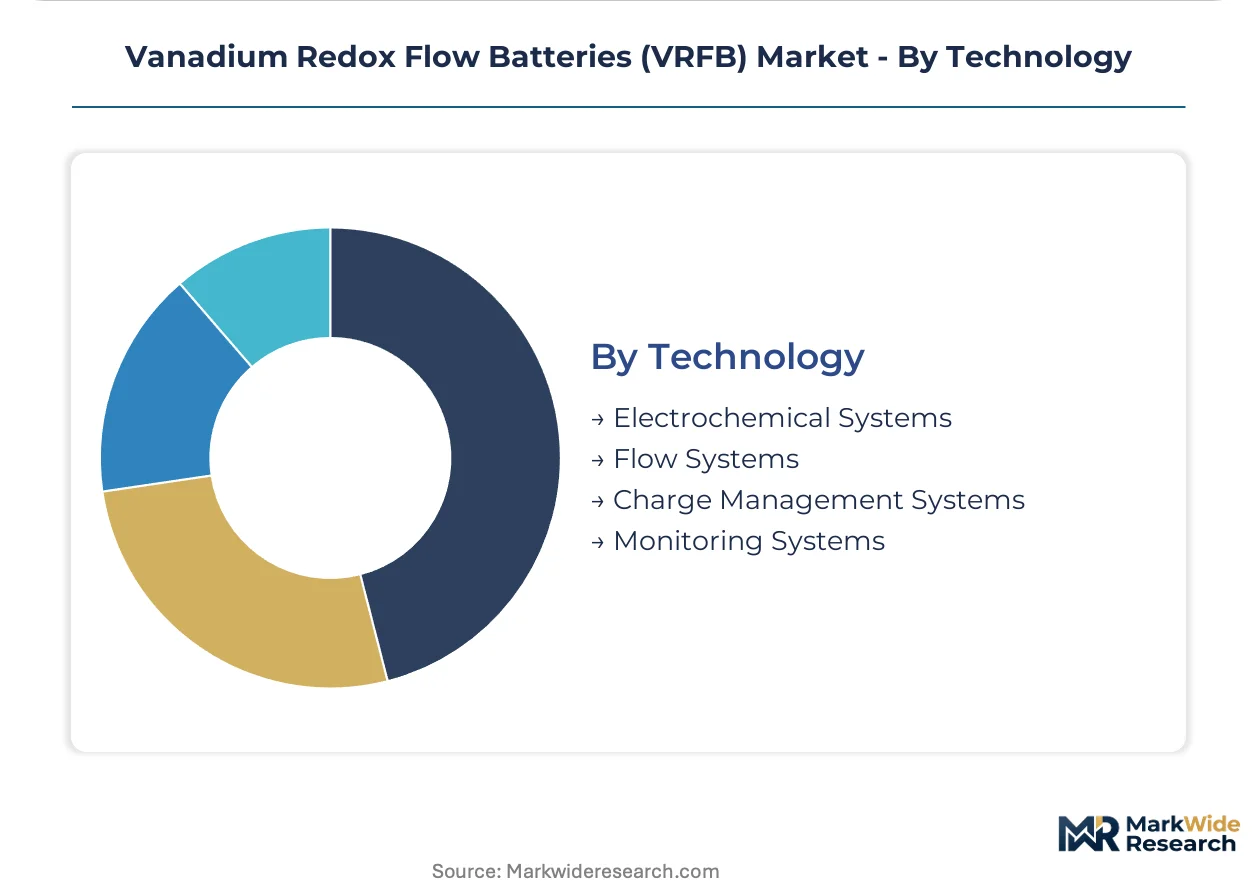
Technology:
Technology layer determines whether competitive differentiation centers on stack cost reduction, electrolyte management precision, or system-level optimization.
- Electrochemical Systems:Cell stack architectures incorporating membrane-less laminar flow designs eliminate perfluorinated ion exchange materials. Australian pilot installations validate 15-20% capital cost reduction.
- Flow Systems:Electrolyte circulation and tank infrastructure govern energy capacity scaling independent of power rating. Russian and Chinese vanadium feedstock concentration forces manufacturers into long-term offtake agreements.
- Charge Management Systems:Power conversion and inverter integration optimize round-trip efficiency.
- Monitoring Systems:Predictive maintenance algorithms compress operational downtime across dispersed assets.
Flow Systems dominates capital allocation. Electrochemical Systems is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for grid-connected energy storage anchor procurement pipelines in China, the dominant geography for VRFB manufacturing scale-up. Australia's CEA mandates and the EU F-Gas Regulation create parallel demand corridors that reshape deployment patterns across three continents.
China
State Grid and Southern Power Grid dominate utility procurement under MIIT GB standards that mandate safety protocols for renewable integration projects. The dual carbon goals accelerate domestic manufacturing scale-up through captive electrolyte production in Liaoning and Sichuan provinces. Yangtze River Delta battery integrators supply stack components to provincial solar-wind hybrid installations.
Australia
Western Australian and Queensland mining operators deploy VRFB systems to displace diesel generation under CEA storage co-location mandates for remote renewable projects. The country's national energy regulator enforces grid interconnection standards that favor long-duration aqueous chemistries. Pilbara region solar-wind hybrid installations drive concentrated commercial deployments for iron ore extraction operations.
Germany
Transmission system operators specify 6+ hour duration requirements under EU taxonomy-aligned tenders that exclude lithium-ion competitors. The EU F-Gas Regulation restricts fluorinated electrolytes, steering developers toward vanadium flow systems. Bavarian and North Rhine-Westphalian utility procurement pipelines prioritize grid stabilization assets for renewable firming.
United States
FERC Order 841 enables storage participation in wholesale markets, though fragmented state regulatory environments stretch utility interconnection approvals to 18-24 months. California and Texas grid operators issue long-duration storage solicitations that attract VRFB developers seeking 8+ hour discharge economics. Southwestern solar-wind-battery configurations leverage duration requirements for mining and data center offtakers.
Japan
METI procurement guidelines for grid-connected storage prioritize cycle life economics in island grid applications where replacement logistics prove costly. Domestic research institutions concentrate electrochemical engineering expertise for flow battery stack optimization. Kyushu and Hokkaido renewable integration projects deploy pilot installations for grid stabilization in constrained transmission corridors.
Vanadium Redox Flow Batteries (VRFB) Market Competitive Landscape
State-affiliated energy conglomerates and independent flow battery specialists split the market between captive supply chains and modular architecture differentiation. Chinese manufacturers leverage backward integration into vanadium mining assets to control feedstock costs, while Western developers emphasize standardized containerized systems for rapid deployment. Three archetypes dominate: electrolyte-integrated conglomerates, modular system specialists, and hybrid renewable integrators. Capacity expansion in Chinese manufacturing hubs and strategic partnerships for remote mining deployments constitute the dominant competitive moves reshaping procurement timelines.
Among electrolyte-integrated conglomerates, Rongke Power and Shanghai Electric exemplify the archetype through captive production capabilities and domestic project pipelines. VRB Energy occupies a position within the supply-chain-anchored tier, leveraging vanadium partnerships across Pacific installations. Invinity Energy Systems represents the modular architecture specialists, reducing commissioning complexity for industrial offtakers through standardized containerized designs. These three companies illustrate how geographic origin and structural positioning determine competitive approach without overlapping segment focus.
| Leading Market Players |
|---|
| VRB Energy |
| Largo Inc. |
| Rongke Power |
| ESS Inc. |
| SCHMID Group |
| Sumitomo Electric Industries |
| CellCube (Enerox GmbH) |
| Shanghai Electric |
| Invinity Energy Systems |
| Others |
Value Network & Pricing Analysis
Liaoning and Sichuan provinces anchor vanadium electrolyte production capacity, concentrating feedstock conversion economics in China's interior and amplifying pricing leverage for domestic integrators against Pacific competitors. This geographic clustering compresses procurement timelines for State Grid tenders while exposing offshore developers to currency-adjusted cost volatility.
Pricing Analysis
Chinese domestic pricing diverges from Australian and German delivered costs by the landed logistics differential plus tariff exposure. Project-based contract structures dominate utility procurement, with price differentiation driven by GB certification tier and electrolyte volume scale. Cost compression in mid-scale installations is intensifying because lithium iron phosphate alternatives compress duration-competitive segments. Mining operators in Western Australia exhibit highest price sensitivity, while Taiwanese semiconductor fabs accept premium positioning for 8-12 hour reliability guarantees.
Supply Chain Analysis
Vanadium pentoxide feedstock draws from Chinese and Russian mining concentration, with electrolyte production tethered to Liaoning conversion facilities and Sichuan chemical processing clusters. Critical dependencies include vanadium ore grade, sulfuric acid purity, and ion exchange membrane supply. Single-source vulnerability in Chinese electrolyte conversion exposes non-domestic developers to allocation risk during peak procurement windows. Distribution runs through State Grid and Southern Power Grid procurement pipelines for utility-scale deployments, with containerized systems reaching mining offtakers via energy-as-a-service integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VRFB market reads as a service-attach opportunity because electrolyte leasing and predictive maintenance contracts expand recurring revenue faster than hardware sales alone. Performance-based availability agreements now command margin premiums exceeding traditional equipment margins.
For Market Incumbents: Insulate project economics through captive vanadium offtake agreements or backward integration into mining assets, neutralizing feedstock volatility that compresses margins when steel alloy demand cycles spike. Prioritize certification investment under MIIT GB standards and EU taxonomy alignment to defend position against lithium iron phosphate substitution in 2-4 hour segments. For New Entrants and Emerging Players: Pursue industrial microgrid white space in Taiwan semiconductor fabs and South Korean data centers, where 8-12 hour duration requirements and cycle life economics create penetrable segments outside utility procurement concentration. Target energy-as-a-service contracting models for Chilean and South African mining offtakers, transferring performance risk while accelerating deployment velocity without capital ownership barriers. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-transition play because grid stabilization requirements and renewable firming mandates embed durable demand regardless of near-term chemistry competition. Acquisition targets should exhibit electrolyte supply anchoring or modular architecture IP. The signal to watch is German and Spanish tender specifications for 6+ hour duration, which validate aqueous flow chemistry eligibility against lithium-ion exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Leasing Model Deployment | Separates energy capacity costs from power hardware, reducing upfront capital barriers for municipal utilities under FERC Order 841. |
| Membrane-less Stack Architecture Scale-up | Eliminates perfluorinated ion exchange materials, validating 15-20% capital cost reduction in Australian pilot installations. |
| Long-term Vanadium Offtake Agreement | Secures captive feedstock through Russian or Chinese mining partnerships, reshaping project bankability assessments. |
| EU Taxonomy-aligned Certification Investment | Unlocks green bond eligibility under CSRD technical screening criteria for German network operator tenders. |
| Hybrid Renewable Integration Partnership | Optimizes solar-wind-battery configurations for Pilbara iron ore operations under CEA storage co-location mandates. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration against secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Primary interviews with stack manufacturers and electrolyte suppliers combined with customs records and SEC filings enabled bottom-up and top-down triangulation across the analysis window.
Scenario-bracketing framed the analytical approach, modeling across power rating tiers, application segments, end-user categories, and regional regulatory clusters throughout the forecast period. CAGRs derived from installation capacity buildout trajectories and electrolyte cost curve projections, with vanadium price volatility and lithium iron phosphate pricing pressure as key sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial commodity cycles, currency exchange rates, or steel alloy demand would shift the trajectory. Cross-checking against IEA long-duration storage deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Vanadium Redox Batteries Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
South Europe Battery Market
Batteries
Battery Cases Market
Batteries
Global Electric Scooter Batteries Market
Batteries
South Asia Battery Market
Batteries
Lead Acid Battery Market
Batteries
North Africa Battery Market
Batteries
Battery Light Towers Market
Batteries
Iron Salt Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Battery Swapping Market
Batteries
Battery Voltage Recorder Market
Batteries
North America NMC Battery Pack Market
Batteries
Battery Anode Materials Market
Batteries
Military Battery Packs Market