
 DMC for Battery Market | 2026-2036
DMC for Battery Market Size, Share, and Industry Trends Forecast 2026-2036
DMC for Battery Market Insights
Modular electrolyte formulation kits are rebalancing how battery manufacturers source dimethyl carbonate, shifting procurement from bulk commodity purchases to specification-matched solvent blends. LG Chem Ltd. leverages captive DMC refining to secure electrolyte cost positions in Korean gigafactory corridors. CATL anchors its DMC supply through backward integration into coal-to-olefin derivatives in Ningxia. Samsung SDI Co., Ltd. differentiates via ultra-high-purity grades for solid-state cell prototyping.
Dimethyl carbonate for battery applications is a colorless, low-viscosity organic solvent with molecular formula C₃H₆O₃, typically synthesized through transesterification of propylene oxide with methanol or via direct methanol carbonylation, and it functions primarily as a linear carbonate co-solvent in lithium-ion electrolytes to reduce viscosity and improve low-temperature conductivity. Lithium-ion cells dominate DMC consumption due to established electrolyte formulations and expanding gigafactory output. Solid-state technology represents the fastest-growing technology segment for DMC demand as developers adapt hybrid electrolytes bridging liquid and ceramic interfaces. Sodium-ion batteries are emerging as a volume alternative where DMC serves in hard-carbon anode electrolyte systems.
China's MEE enforces wastewater and VOC emission limits on DMC producers under dual carbon mandates, while REACH in Europe governs chemical registration and SVHC disclosure for imported electrolyte solvents. South Korea's K-Battery regulations through METI-aligned standards push domestic DMC purity thresholds higher for export-qualified cells. Stakeholders must track how regional carbon border adjustments and battery passport requirements reshape solvent sourcing economics across production networks.
Market Dynamics
Dimethyl carbonate supply chains are compressing around integrated refining corridors as battery OEMs demand solvent-to-electrolyte traceability under tightening carbon accounting rules.
Growth Catalysts
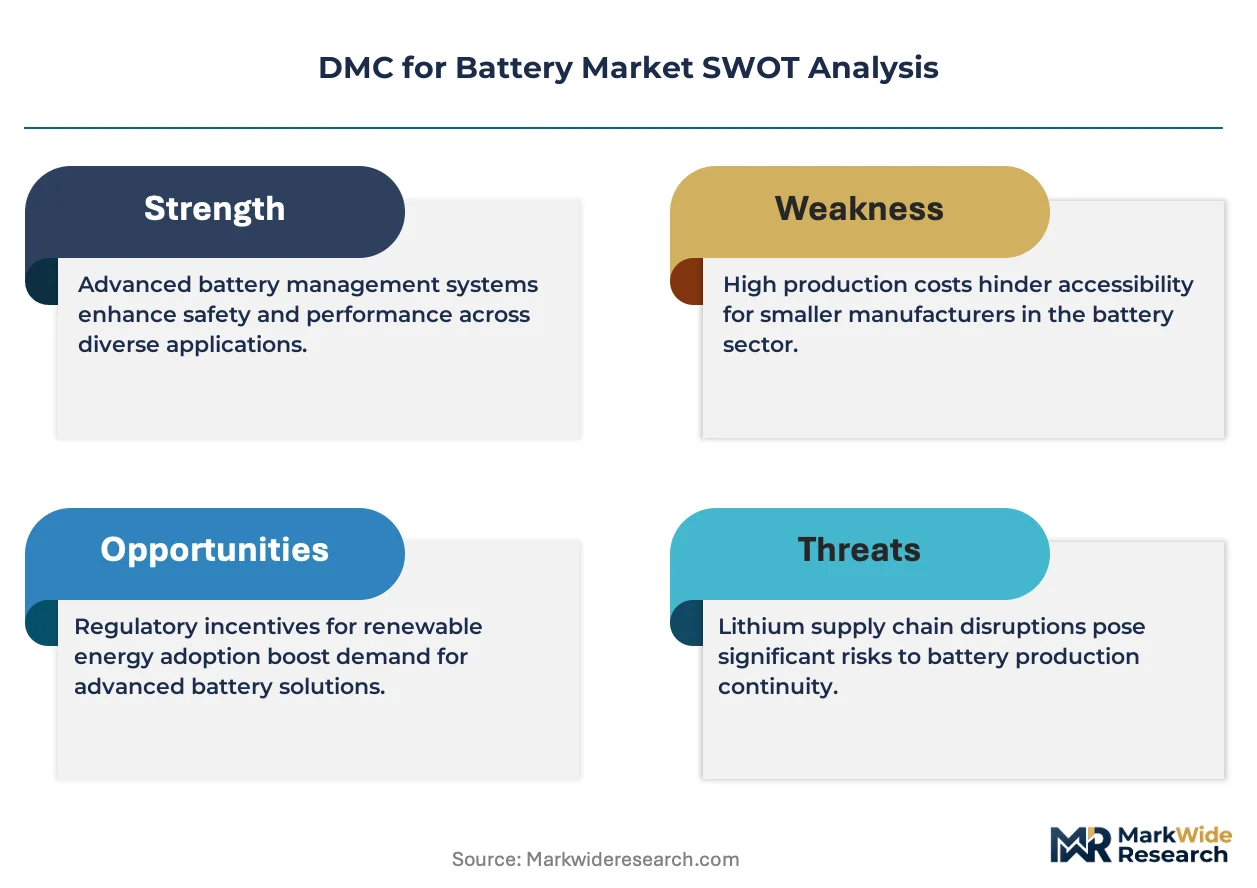
- Dual carbon mandates:China's MEE enforcement of VOC emission limits accelerates adoption of carbonylation-based DMC synthesis with lower carbon intensity profiles.
- Solid-state prototyping:Hybrid electrolyte development for ceramic-polymer interfaces pulls ultra-high-purity DMC grades into pilot production lines.
- Jiangsu-Shandong corridor:Concentrated DMC-to-electrolyte infrastructure reduces logistics costs and enables just-in-time solvent delivery to gigafactory clusters.
Market Restraints
- Methanol feedstock volatility:DMC production costs track methanol spot markets, creating margin compression during energy price spikes.
- Propylene oxide supply concentration:Transesterification route DMC remains exposed to PO supply disruptions concentrated in East Asian petrochemical complexes.
- REACH SVHC disclosure:European electrolyte solvent imports face escalating registration burdens and substance-of-concern documentation requirements.
Strategic Opportunities
- Sodium-ion hard-carbon systems:Emerging anode formulations for Na-ion cells create parallel DMC demand outside lithium supply chains.
- Modular formulation kits:Specification-matched solvent blends replace bulk commodity purchases, enabling premium pricing for tailored electrolyte packages.
- K-Battery export alignment:South Korea's METI-aligned purity thresholds create qualification pathways for DMC producers meeting Korean cell export standards.
Industry Challenges
- High-purity distillation expertise:Battery-grade DMC requires sub-10 ppm impurity control that exceeds traditional industrial solvent capabilities.
- Electrolyte-to-cell integration timelines:Solvent qualification cycles must compress to match accelerating cell chemistry iteration rates at OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DMC for Battery Market |
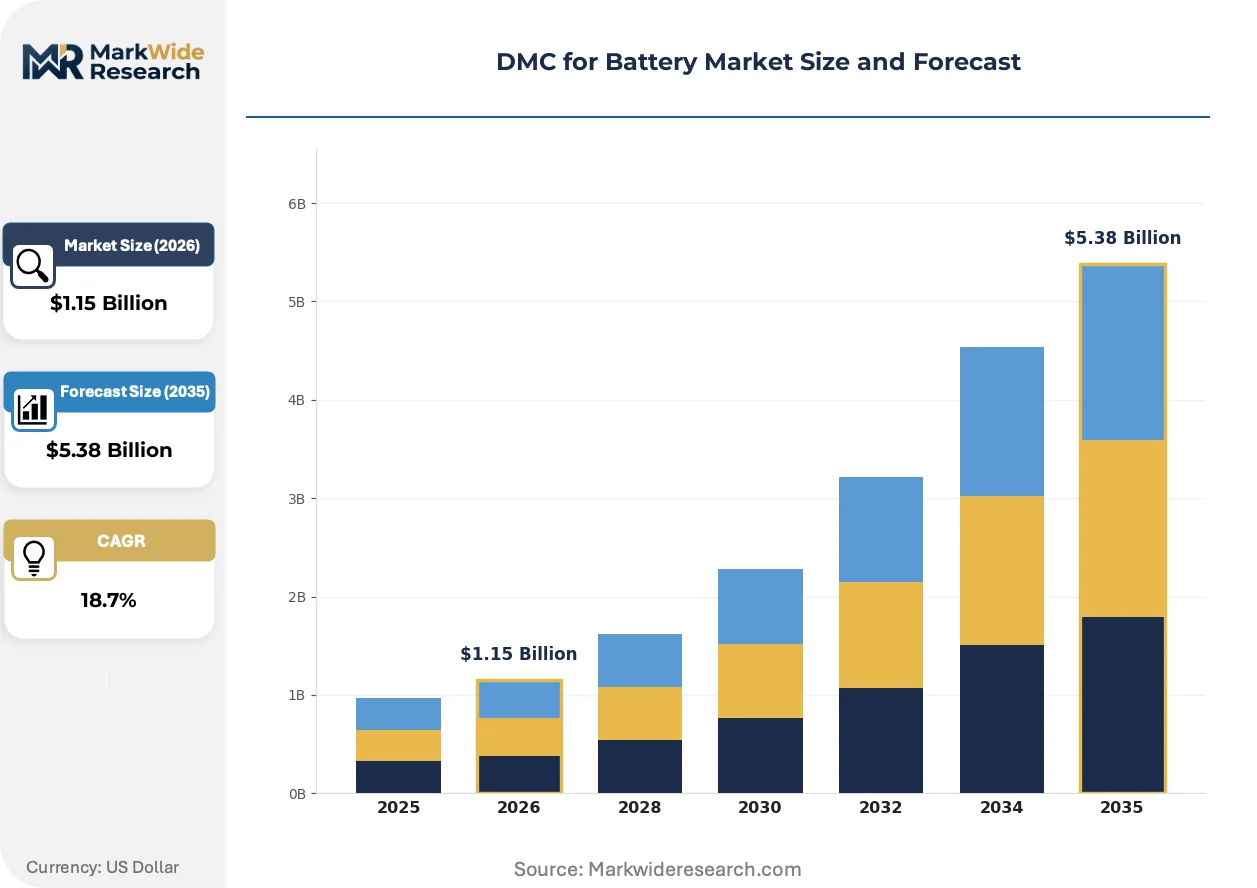
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $5.38 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Sodium-ion Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Equipment End User: Manufacturers, Distributors, Retailers, Government Agencies Technology: Fast Charging, Modular Design, Smart Battery Management, Solid State |
| Companies Covered | LG Chem Ltd., Samsung SDI Co., Ltd., Panasonic Corporation, BYD Company Limited, Contemporary Amperex Technology Co. Limited (CATL), Johnson Controls International plc, SK Innovation Co., Ltd., GS Yuasa Corporation, CAPCHEM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DMC for Battery Market Trends and Innovations
Electrolyte formulation is fragmenting from standardized recipes toward application-specific solvent architectures that trade off conductivity, viscosity, and thermal stability.
Direct methanol carbonylation is unifying DMC production around single-step synthesis routes with superior carbon efficiency. Korean and Chinese producers are retrofitting coal-to-chemicals complexes with carbonylation units at scale. This technology is unifying cost structures across integrated petrochemical networks while displacing transesterification capacity in older facilities.
REACH SVHC disclosure requirements are tightening documentation burdens for electrolyte solvent imports into European battery supply chains. ECHA substance-of-concern listings now capture several DMC synthesis intermediates, forcing reformulation of legacy supply contracts. German and French cell manufacturers are accelerating qualification of carbonylation-route DMC to preempt registration complications.
Battery OEMs are consolidating solvent procurement around specification-matched electrolyte kits rather than discrete chemical purchases. Korean gigafactory operators now contract directly for DMC-to-electrolyte conversion services, bypassing traditional chemical distributor networks. This channel restructuring concentrates purchasing power among cell producers while fragmenting the vendor base into specialty formulators and captive refiners.
DMC for Battery Market Segmentation
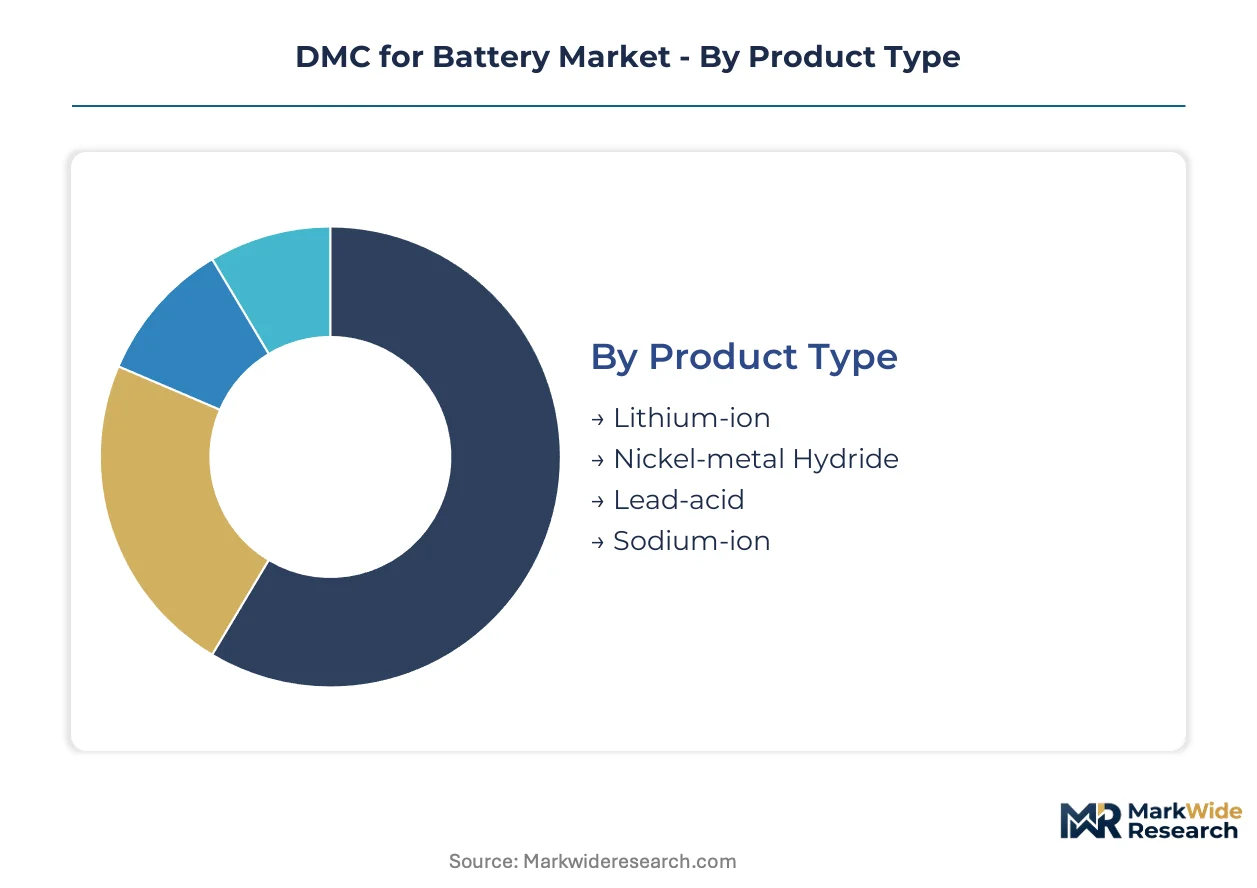
Segmentation in the DMC for Battery Market reveals how solvent specifications diverge across cell chemistries and end-use thermal profiles. Buyers prioritize conductivity, viscosity, and purity thresholds differently based on application voltage and cycling demands.
Product Type:
Battery chemistry determines DMC grade requirements through operating voltage windows and electrolyte salt compatibility.
- Lithium-ion:Standard carbonate electrolytes use DMC as a linear co-solvent with ethylene carbonate to achieve low-temperature conductivity below -20°C. Demand concentrates in Jiangsu province gigafactory corridors serving EV OEMs with high-volume procurement contracts.
- Sodium-ion:Hard-carbon anode formulations employ DMC in ether-carbonate hybrid electrolytes optimized for Na-ion intercalation kinetics. Pilot production lines in Shandong province are qualifying battery-grade DMC for emerging Na-ion cell manufacturing.
- Nickel-metal Hydride:Aqueous alkaline electrolytes limit DMC applicability to specialty additive roles in hybrid vehicle systems.
- Lead-acid:Sulfuric acid chemistry excludes carbonate solvents entirely; DMC penetration remains negligible.
Lithium-ion leads volumes today; Sodium-ion is gaining share fastest.
Application:
End-use thermal and safety profiles reshape DMC purity and formulation service requirements.
- Electric Vehicles:High-voltage battery packs demand ultra-high-purity DMC with sub-10 ppm moisture and metallic impurity control for 800V architectures. Korean and Chinese OEMs specify carbonylation-route solvents to meet carbon intensity disclosure requirements under tightening battery passport rules.
- Energy Storage Systems:Grid-scale installations prioritize cost-optimized DMC grades with extended thermal stability for 20-year operational lifespans. Chinese integrators in Ningxia source from coal-to-chemicals carbonylation corridors to align with dual carbon procurement mandates.
- Consumer Electronics:Compact cell formats drive demand for low-viscosity DMC enabling fast-charge electrolyte formulations at reduced solvent loadings.
- Industrial Equipment:Forklift and material handling batteries specify industrial-grade DMC with relaxed purity thresholds compared to mobility applications.
Electric Vehicles dominates procurement value; Energy Storage Systems shows the steepest expansion trajectory.
End User:
Channel position determines whether buyers source commodity DMC or specification-matched electrolyte services.
- Manufacturers:Cell producers with captive electrolyte blending capabilities purchase battery-grade DMC in bulk tanker quantities, negotiating directly with carbonylation facility operators in Shandong and Jiangsu.
- Distributors:Chemical traders aggregate transesterification-route DMC from multiple producers, serving mid-tier battery assemblers without solvent refining expertise.
- Retailers:Aftermarket battery channels source packaged electrolyte formulations with pre-blended DMC content for replacement cell servicing.
- Government Agencies:Strategic reserve procurement and research funding programs in China specify domestic carbonylation-route DMC to support supply chain security objectives.
Manufacturers command the largest procurement volumes; Government Agencies are expanding fastest through strategic reserve programs.
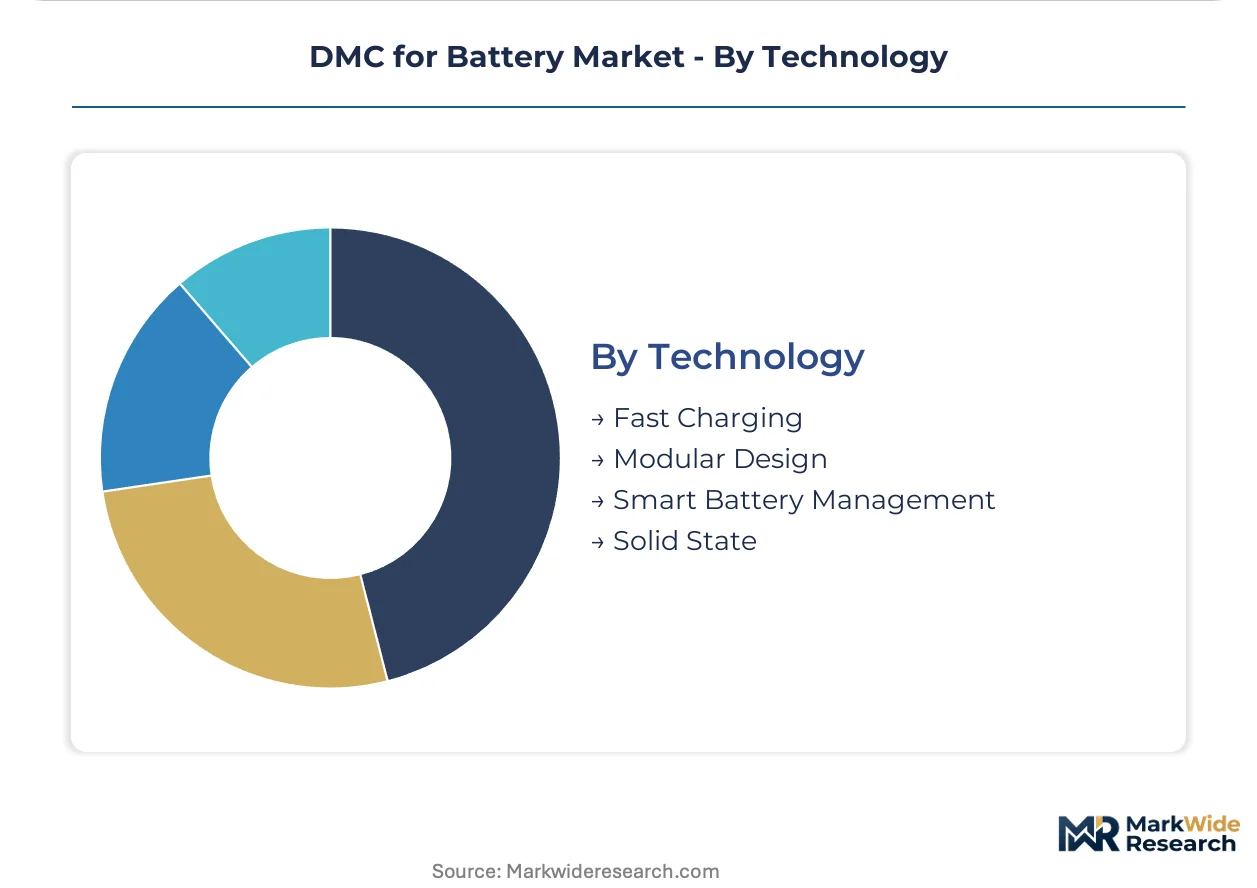
Technology:
Cell architecture innovations recalibrate DMC functional requirements across conductivity, flammability, and interface compatibility.
- Solid State:Hybrid ceramic-polymer electrolytes incorporate DMC as a plasticizer and wetting agent at ceramic-polymer interfaces. Samsung SDI and Korean research institutes qualify ultra-high-purity grades for sulfide-based solid-state prototyping lines.
- Fast Charging:High-rate cell designs favor low-viscosity DMC formulations enabling lithium-ion transport at 4C and 6C charge rates without electrolyte decomposition.
- Smart Battery Management:Sensor-integrated packs drive demand for electrolyte batches with traceable impurity profiles to support predictive degradation modeling.
- Modular Design:Swappable cell architectures standardize DMC-based electrolyte formulations across multiple pack configurations to simplify reverse logistics and recycling.
Fast Charging anchors current DMC consumption; Solid State is climbing the fastest as pilot production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dimethyl carbonate for battery applications originated in Japanese and Korean petrochemical corridors during the 1990s lithium-ion commercialization wave. Production expertise subsequently migrated to Chinese coal-to-chemicals complexes. Today, supply chains concentrate in East Asian integrated refining networks serving gigafactory demand.
China
Jiangsu and Shandong provinces host concentrated DMC-to-electrolyte supply corridors where integrated producers serve CATL and BYD gigafactory clusters. MEE enforcement of dual carbon mandates tightens VOC emission limits on transesterification facilities, accelerating carbonylation route adoption. Ningxia's coal-to-olefin derivatives corridor anchors backward-integrated DMC supply for battery-grade solvent production.
South Korea
Korean cell manufacturers drive ultra-high-purity DMC demand for solid-state prototyping and 800V EV architectures. METI-aligned K-Battery regulations push domestic purity thresholds higher for export-qualified cells to European and North American markets. Seoul Capital Area refiners supply integrated electrolyte formulation services directly to Samsung SDI and LG Chem gigafactory networks.
Japan
Japanese producers pioneered battery-grade DMC distillation expertise now licensed across Asian production networks. METI industrial policy supports domestic carbonylation facility upgrades to maintain supply chain security amid import dependency concerns. Osaka-Kansai chemical complexes retain specialized capacity for sub-10 ppm impurity control serving premium electrolyte segments.
United States
US battery manufacturing expansion under IRA production tax credits pulls imported DMC through West Coast and Gulf Coast port corridors. EPA oversight of chemical facility emissions shapes domestic production investment decisions as carbonylation route economics improve. Michigan and Ohio gigafactory clusters negotiate direct solvent supply contracts bypassing traditional distributor networks.
Germany
German cell manufacturers accelerate qualification of carbonylation-route DMC to preempt ECHA REACH SVHC registration complications for imported electrolyte solvents. North Rhine-Westphalia's chemical industry infrastructure supports formulation services for European battery passport compliance. Bavarian automotive OEMs specify carbon intensity disclosure requirements that reshape solvent sourcing from Asian suppliers.
DMC for Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade and carbon-intensity certification dimensions. The vendor base compresses around integrated refiners with captive electrolyte formulation capabilities and specialty chemical distributors serving mid-tier assemblers. Three archetypes dominate: petrochemical majors with backward-integrated DMC production, independent solvent refiners focused on battery-grade distillation, and electrolyte formulators sourcing specification-matched solvent blends. Capacity expansion and direct OEM contracting represent the dominant competitive moves as channel power shifts toward cell manufacturers.
Within the integrated petrochemical tier, LG Chem Ltd. and Samsung SDI Co., Ltd. exemplify Korean producers leveraging captive refining positions. Contemporary Amperex Technology Co. Limited anchors Chinese supply through coal-to-chemicals corridor control. These companies occupy positions where solvent-to-electrolyte traceability supports carbon accounting compliance under tightening battery passport regulations.
| Leading Market Players |
|---|
| LG Chem Ltd. |
| Samsung SDI Co., Ltd. |
| Panasonic Corporation |
| BYD Company Limited |
| Contemporary Amperex Technology Co. Limited (CATL) |
| Johnson Controls International plc |
| SK Innovation Co., Ltd. |
| GS Yuasa Corporation |
| CAPCHEM |
| Others |
Pricing and Supply Chain Analysis
High-purity distillation expertise concentration in Osaka-Kansai chemical complexes creates labor-cost differentials that widen pricing spreads between premium battery-grade DMC and industrial solvent grades. Korean and Chinese producers leverage lower technical wage structures to compress mid-tier pricing while Japanese specialists command premiums for sub-10 ppm impurity control.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates DMC procurement contracts, with ultra-high-purity carbonylation-route solvents commanding substantial premiums over transesterification grades. Price differentiation rests on carbon intensity certification and battery passport compliance rather than basic purity metrics alone. Cost compression in standard grades is intensifying because methanol feedstock volatility transmits directly into margin pressure. Energy storage integrators in Ningxia exhibit highest price sensitivity, while Korean solid-state prototyping lines show least sensitivity due to qualification-driven procurement.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Busan, and Shanghai anchor hub-and-spoke patterns for electrolyte solvent delivery to European, Korean, and Chinese gigafactory clusters respectively. Production concentrates in China, South Korea, and Japan, with Jiangsu-Shandong corridors hosting integrated DMC-to-electrolyte refining networks. Raw material flows draw from methanol steam reforming and coal-to-olefin derivatives, with propylene oxide supply concentrated in East Asian petrochemical complexes. Single-source vulnerability around PO feedstock exposes transesterification-route producers to disruption. Distribution runs through direct OEM contracting channels that bypass traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DMC for battery applications has entered a late-cycle quality phase where specification-matched electrolyte kits displace commodity solvent purchases, with ultra-high-purity demand from solid-state prototyping lines driving the most attractive margin pools.
For Market Incumbents: Hedge against carbonylation-route cost convergence by locking long-term methanol supply contracts and accelerating REACH SVHC documentation for European export channels. Backward integration into coal-to-chemicals corridors in Ningxia and Shandong secures feedstock cost positions against volatile spot markets. Certification investment in battery passport carbon accounting systems represents the critical defensive lever as OEM qualification timelines compress. For New Entrants and Emerging Players: Begin with sodium-ion hard-carbon electrolyte formulations where qualification barriers remain lower than lithium-ion supply chains and incumbent positions are less entrenched. Shandong province pilot production lines for Na-ion cells offer the most penetrable entry point. A go-to-market angle anchored on carbonylation-route carbon intensity disclosure aligns with dual carbon procurement mandates from Chinese integrators. For Investors and Strategic Acquirers: Battery OEMs with captive electrolyte formulation capabilities are the most active acquirer in this space, consolidating solvent refining assets to secure supply chain traceability. The five-to-ten year viability window favors targets with demonstrated sub-10 ppm distillation expertise and existing qualification relationships with Korean cell manufacturers. The signal to watch is accelerating direct contracting between DMC refiners and EV OEMs bypassing distributor intermediaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coal-to-Chemicals | CATL's Ningxia corridor demonstrates captive methanol sourcing that insulates margin from feedstock volatility. |
| Carbonylation Route Capacity Expansion | Korean retrofitting of coal-to-chemicals complexes displaces higher-carbon transesterification capacity. |
| Ultra-High-Purity Distillation Investment | Samsung SDI's solid-state prototyping lines require sub-10 ppm grades that exceed traditional solvent capabilities. |
| Direct OEM Electrolyte Contracting | LG Chem bypasses distributor networks by supplying specification-matched solvent blends directly to gigafactory clusters. |
| Battery Passport Carbon Certification | German automotive OEMs now require carbon intensity disclosure that reshapes sourcing from Asian suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrolyte formulation chemists, battery OEM procurement directors, carbonylation plant managers, and REACH regulatory consultants with secondary validation. Trade data from Chinese customs authorities, Korean petrochemical association reports, ECHA substance registration databases, and SEC filings from listed battery material suppliers anchored supply-side modeling. Bottom-up capacity assessments and top-down demand projections from EV production forecasts were triangulated to constrain estimate variance.
Segment-weighting approaches applied differential growth assumptions across lithium-ion, sodium-ion, and solid-state technology trajectories, with purity grade tiers and application thermal profiles as cross-cutting dimensions. CAGRs were derived from fitted growth curves across the projection horizon, with cell chemistry adoption rates and gigafactory commissioning schedules as primary demand inputs. Electrolyte salt compatibility requirements and VOC emission regulatory stringency served as industry-specific forecast modifiers.
Caveats apply where methanol price spikes, propylene oxide supply disruptions, or REACH SVHC listing expansions could materially shift the outlook. Forecasts reflect assumptions about carbonylation route adoption rates and solid-state commercialization timelines that carry execution risk. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Alkaline Battery Market
Batteries
Battery Binders Market
Batteries
India Rechargeable Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Yacht Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Dry Cell Battery Market
Batteries
Primary Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
Battery Separators Market
Batteries
Taiwan Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Molten Salt Battery Market
Batteries
Leisure Battery Market
Batteries
Europe Consumer Battery Market