
 Battery Separators Market | 2026-2036
Battery Separators Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Separators Market Analysis
China is rewriting competitive dynamics in battery separators through massive domestic capacity additions for wet-process polyethylene membranes. Asahi Kasei Corporation leverages its proprietary Hipore technology to sustain premium positioning in automotive-grade separators. SK IE Technology anchors Korean supply security through integrated polymer-to-membrane production. Entek International specializes in lead-acid and lithium-ion dry-process solutions, occupying a defensible niche in industrial battery applications.
Battery separators are microporous membranes, typically 10-40 microns thick, that physically isolate anode and cathode materials while permitting ionic transport through electrolyte-filled pores; they prevent internal short circuits and thermal runaway in electrochemical cells. Polyethylene dominates volume in wet-process automotive cells where puncture resistance and uniform pore distribution matter most, while ceramic-coated composites command margin premiums in high-nickel cathode systems prone to elevated operating temperatures. The below 20 microns thickness tier is gaining share in consumer electronics where energy density and pack volumetric efficiency drive procurement decisions.
FDA oversight of battery-containing medical devices, EPA hazardous waste rules for spent separator materials, and China's GB standards for lithium-ion safety collectively elevate compliance costs and technical barriers for new entrants. The EU Battery Regulation's carbon footprint declaration requirements will reshape sourcing patterns for European-bound supply chains. Stakeholders must monitor how solid-state battery timelines affect separator technology roadmaps and capital allocation priorities.
Market Dynamics
The battery separators market is experiencing acute supply-side compression as Chinese wet-process polyethylene capacity expansion outpaces demand absorption, forcing incumbent producers to defend technical differentiation through ceramic coating capabilities and automotive qualification timelines.
Growth Catalysts
- EU Battery Regulation traceability mandates:Material passport requirements for carbon footprint disclosure are accelerating separator requalification programs among European cell manufacturers seeking compliant supply sources.
- High-nickel cathode thermal management needs:NCM 811 and 9-series chemistries operating above 45°C are driving ceramic-coated separator adoption to prevent thermal runaway propagation.
- China's domestic cell maker procurement localization:CATL and BYD are executing multi-year offtake agreements with local membrane producers to secure wet-process polyethylene supply security.
Market Restraints
- Ultra-high molecular weight polyethylene feedstock concentration:Three Korean and Japanese petrochemical groups control over 70% of battery-grade UHMWPE resin supply, creating input cost volatility exposure for membrane producers.
- Dry-process technical ceiling:Polypropylene melt-stretch membranes face pore size distribution limitations below 25 microns, constraining energy density gains in automotive applications.
- GB standards compliance burden:China's lithium-ion safety certification requirements for separator puncture resistance and shutdown temperature are extending new entrant qualification cycles by 18-24 months.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Production-linked incentives for 50 GWh annual cell capacity are creating first-mover separator qualification windows for membrane suppliers establishing local technical service presence.
- Solid-state battery interface materials:Composite polymer-ceramic hybrid separators are emerging as bridge technologies for semi-solid cell architectures requiring dendrite suppression and mechanical flexibility.
- Direct OEM contracting models:Automotive cell makers are bypassing traditional distributor channels to negotiate volume-price agreements with separator producers for platform-specific membrane specifications.
Industry Challenges
- Electrolyte wetting optimization expertise:Separator surface energy matching with novel high-voltage electrolyte formulations requires specialized polymer chemistry talent scarce outside Japanese and Korean technical centers.
- Automotive PPAP timeline compression:Cell maker customers are demanding production part approval process completion within 12 months versus historical 24-month cycles, straining quality system resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Separators Market |
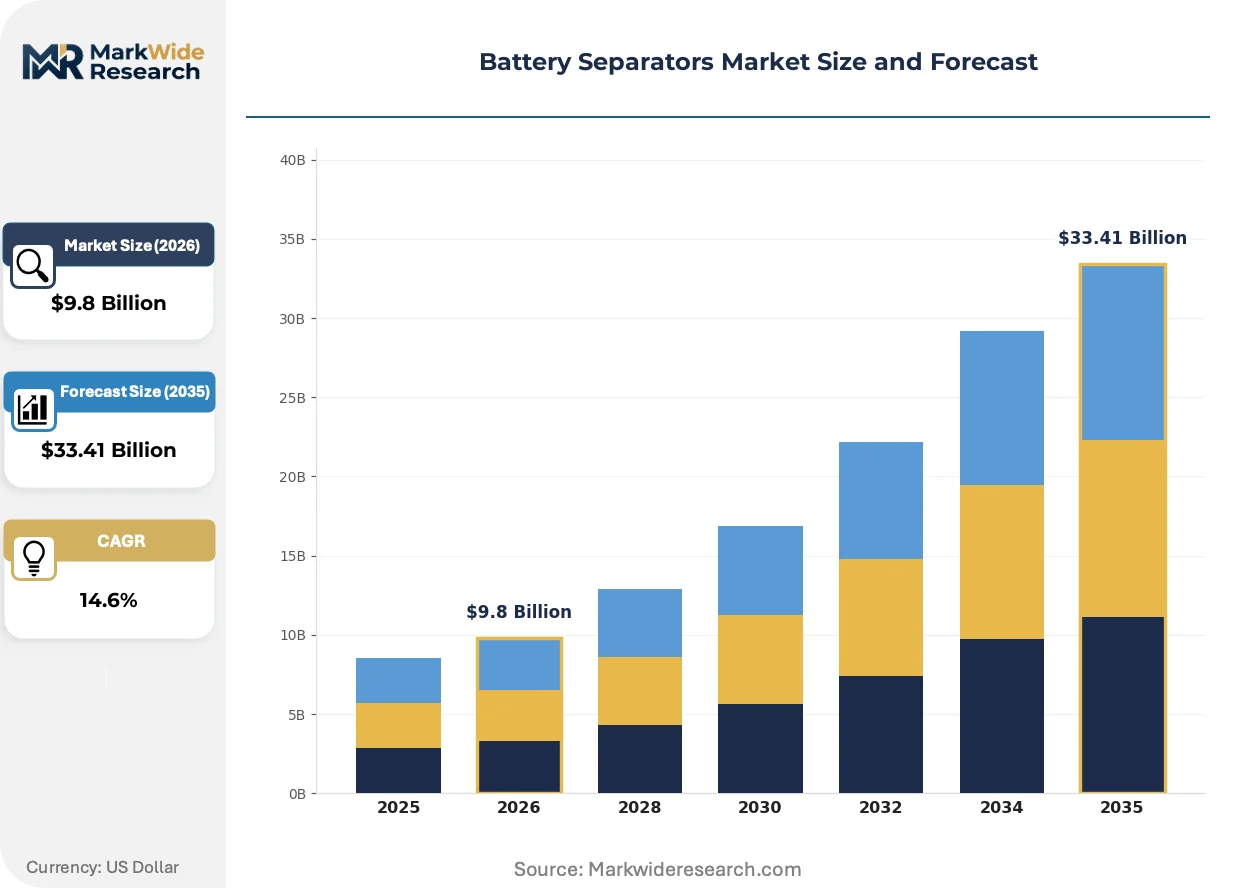
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ceramic, Composite End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Thickness: Below 20 Microns, 20-30 Microns, 30-40 Microns, Above 40 Microns Technology: Wet Process, Dry Process, Coextrusion, Nano-coating |
| Companies Covered | Entek International, Shanghai Energy New Materials Technology, Asahi Kasei Corporation, Evonik, UBE Corporation, SK IE Technology, Toray Industries, Celgard, Semcorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Separators Market Emerging Trajectories
Separator technology roadmaps are diverging between evolutionary wet-process polyethylene refinement and ceramic composite architectures, with digitization of quality systems emerging as a cross-cutting operational transformation.
Machine vision-based pore inspection is digitizing quality assurance protocols across wet-process production lines. Korean membrane producers are deploying real-time defect detection at 50+ meters per minute coating speeds. This digitizing of inspection workflows is compressing batch release cycles from 72 hours to 4 hours while reducing human inspection labor by 60%.
REACH restrictions on perfluorinated compounds are forcing reformulation of binder chemistries used in ceramic coating slurries. European separator producers are qualifying water-based acrylic alternatives ahead of 2025 authorization sunset dates. Automotive-grade coated membranes for German OEM supply chains face the most acute substitution timeline pressure.
Cell makers are consolidating supplier bases around dual-source strategies with technical audit rights. Tier-1 automotive battery divisions are reducing qualified separator vendors from 6-8 to 2-3 per plant while demanding quarterly cost reduction commitments. This concentration is most visible in Hungary and Poland, where European cell gigafactories are negotiating multi-year framework agreements with membrane producers holding localized technical service capabilities.
Battery Separators Market Segmentation
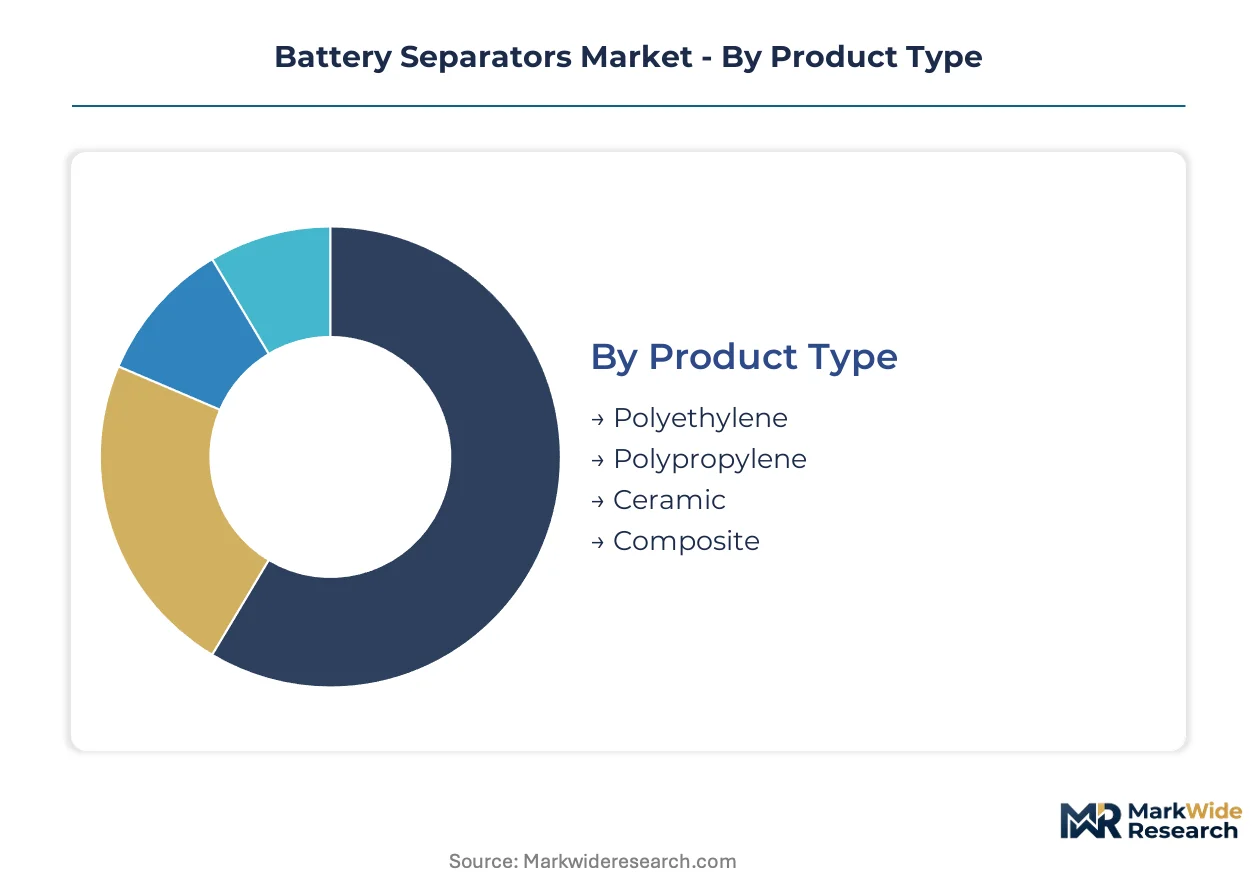
Separator procurement decisions hinge on matching electrochemical requirements to membrane architecture across four critical dimensions. Cell manufacturers optimize cost-performance tradeoffs by selecting thickness tiers and coating technologies aligned to specific cathode chemistries and thermal management protocols.
Product Type:
Mature commodity polymers dominate volume, while emerging ceramic composites capture margin premiums in safety-critical applications.
- Polyethylene:Ultra-high molecular weight polyethylene forms the backbone of wet-process automotive separators, delivering uniform sub-micron pore distribution and reliable shutdown behavior at elevated temperatures. CATL and BYD procurement contracts in China are concentrating demand for 12-25 micron PE membranes in extended-range EV platforms.
- Ceramic:Alumina and boehmite coatings deposited on polymer substrates create thermal barriers that prevent internal short propagation in NCM 811 cells. European cell makers bound by ECHA REACH compliance timelines are accelerating qualification of water-based ceramic slurries to replace perfluorinated binders ahead of authorization sunsets.
- Polypropylene:Melt-stretch dry-process membranes serve lead-acid and industrial lithium-ion applications where cost minimization outweighs energy density requirements.
- Composite:Multi-layer architectures combining polymer flexibility with ceramic thermal resistance target semi-solid battery architectures requiring dendrite suppression.
Polyethylene handles the majority of throughput; ceramic is expanding most quickly on share.
End User:
Customer archetypes span from price-sensitive industrial buyers to automotive OEMs demanding PPAP-qualified supply security.
- Automotive:Tier-1 battery divisions specify ceramic-coated separators with 150°C shutdown windows and puncture resistance exceeding 300 gf for NCM 811 packs. Hungarian and Polish gigafactories are consolidating supplier bases to 2-3 qualified membrane vendors per plant.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize sub-20 micron thickness tiers to maximize volumetric energy density in compact form factors.
- Industrial:Forklift and stationary storage applications tolerate thicker dry-process membranes where cycle life and capital cost matter more than gravimetric density.
- Renewable Energy:Grid-scale battery installations specify separators with extended calendar life for 20-year operational horizons in temperature-cycled environments.
Automotive commands the dominant revenue share; renewable energy is climbing fastest on deployment scale.
Thickness:
Thickness selection directly trades off ionic conductivity against mechanical integrity and manufacturing yield.
- Below 20 Microns:Ultra-thin membranes enable highest energy density in consumer electronics but require precision coating equipment to maintain pinhole-free coverage. Korean producers have achieved production yields above 85% at 16-micron specifications.
- 20-30 Microns:The standard automotive tier balances puncture resistance with ion transport efficiency for 800V fast-charging architectures.
- 30-40 Microns:Thicker wet-process films serve commercial vehicle and energy storage segments prioritizing abuse tolerance over pack density.
- Above 40 Microns:Legacy lead-acid and industrial lithium-ion applications tolerate coarse pore structures where electrolyte retention outweighs impedance minimization.
20-30 microns carries the largest volume position; below 20 microns is gaining share fastest on consumer electronics miniaturization.
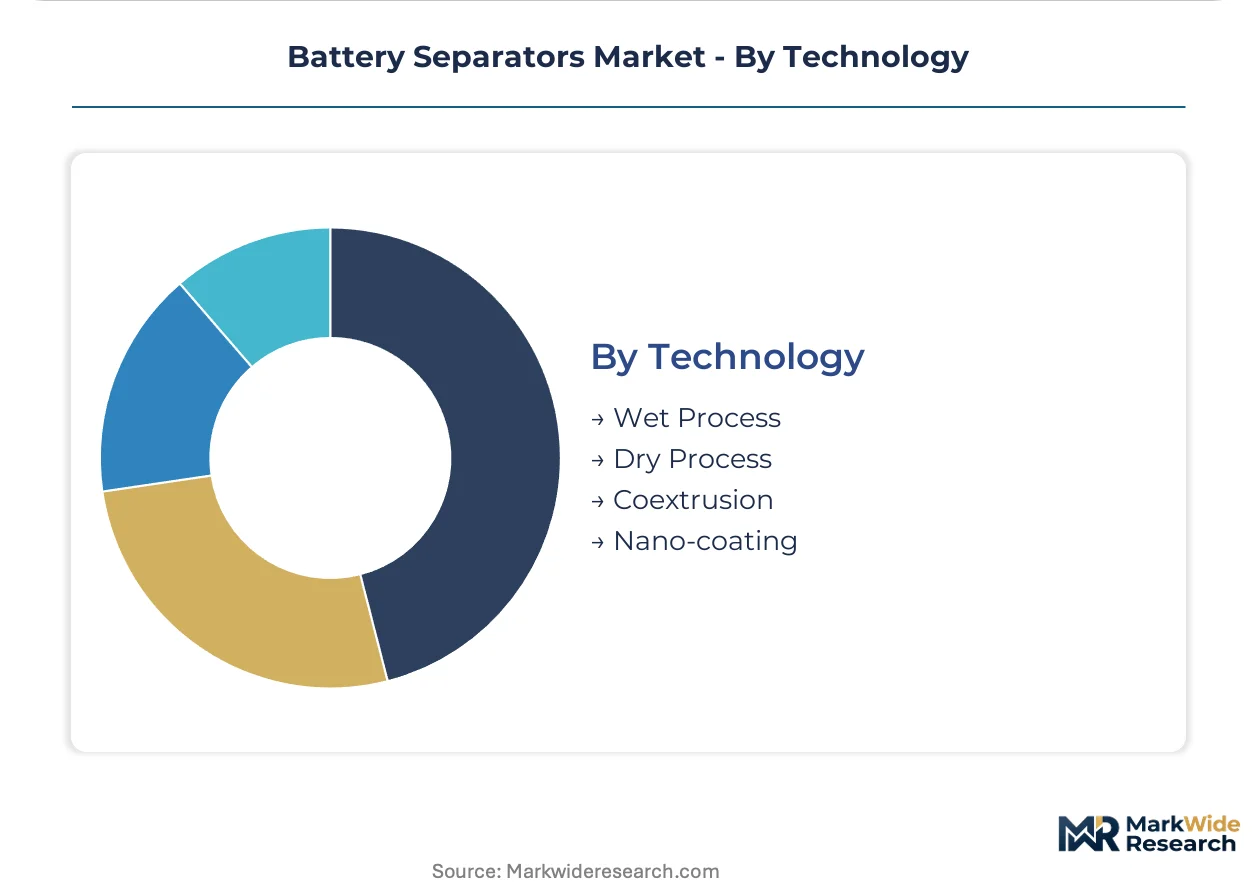
Technology:
Process selection determines pore morphology, production economics, and compatibility with ceramic coating workflows.
- Wet Process:Solvent-based extraction of plasticizers from UHMWPE creates interconnected pore networks with narrow size distributions ideal for automotive cells. Chinese capacity additions are compressing margins and forcing incumbents to defend through ceramic coating differentiation.
- Nano-coating:Atomic layer deposition and spray-based ceramic application enable sub-micron functional layers without substrate thickness penalties. Japanese technical centers retain scarce polymer-electrolyte interface optimization expertise.
- Dry Process:Melt-stretch polypropylene avoids solvent recovery costs but faces pore size limitations below 25 microns.
- Coextrusion:Multi-layer extrusion combines polymers with distinct thermal properties into single-membrane architectures.
Wet process dominates throughput; nano-coating shows the steepest expansion trajectory on high-nickel cathode thermal management needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese wet-process polyethylene capacity additions are compressing margins worldwide, forcing membrane producers to defend technical differentiation through ceramic coating capabilities and automotive qualification timelines.
China
CATL and BYD procurement localization is concentrating demand for 12-25 micron PE membranes in extended-range EV platforms. GB standards for lithium-ion safety certification extend new entrant qualification cycles by 18-24 months. The Yangtze River Delta hosts the densest cluster of domestic membrane producers securing multi-year offtake agreements.
Germany
ECHA REACH restrictions on perfluorinated compounds are accelerating water-based ceramic slurry qualifications ahead of 2025 authorization sunsets. The EU Battery Regulation's carbon footprint declaration requirements reshape sourcing patterns for European-bound supply chains. Bavarian automotive cell gigafactories are consolidating supplier bases to 2-3 qualified membrane vendors per plant.
South Korea
SK IE Technology anchors supply security through integrated polymer-to-membrane production for NCM 811 thermal management needs. Korean petrochemical groups control over 70% of battery-grade UHMWPE resin supply, creating input cost volatility exposure. The Busan-Ulsan corridor concentrates real-time defect detection deployment at 50+ meters per minute coating speeds.
Japan
Asahi Kasei Corporation leverages proprietary Hipore technology to sustain premium positioning in automotive-grade separators. METI oversight of battery-containing industrial equipment elevates compliance costs for membrane imports. The Kanto region retains scarce polymer-electrolyte interface optimization expertise for high-voltage electrolyte formulations.
United States
FDA oversight of battery-containing medical devices and EPA hazardous waste rules for spent separator materials elevate technical barriers for new entrants. Entek International specializes in lead-acid and lithium-ion dry-process solutions occupying defensible industrial niches. The Midwest battery manufacturing corridor is negotiating direct OEM contracting models bypassing traditional distributor channels.
Battery Separators Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream defending margin through ceramic coating differentiation and automotive qualification timelines. The vendor base clusters around three strategic archetypes: integrated petrochemical-to-membrane producers, specialty coating technology licensors, and dry-process industrial specialists. Dominant competitive moves include capacity expansion in Chinese wet-process polyethylene and strategic partnerships for solid-state bridge technology development.
Within the integrated production tier, Asahi Kasei Corporation and SK IE Technology exemplify the petrochemical-to-membrane archetype, while Entek International occupies a position among dry-process specialists serving industrial battery applications. Shanghai Energy New Materials Technology and Semcorp represent Chinese domestic membrane producers securing long-term offtake agreements through localized technical service presence. Toray Industries and UBE Corporation sit within the materials science tier, anchoring regional supply security through polymer chemistry expertise.
| Leading Market Players |
|---|
| Entek International |
| Shanghai Energy New Materials Technology |
| Asahi Kasei Corporation |
| Evonik |
| UBE Corporation |
| SK IE Technology |
| Toray Industries |
| Celgard |
| Semcorp |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta wet-process polyethylene capacity cluster compresses margin structures across automotive-grade membrane tiers, forcing Korean and Japanese incumbents to defend pricing power through ceramic coating differentiation and accelerated PPAP qualification timelines.
Pricing Analysis
The EU Battery Regulation's carbon footprint declaration mandates dictate the pricing tier structure across European-bound supply chains, separating PPAP-qualified automotive membranes from industrial-grade alternatives. Ceramic-coated separators for NCM 811 cells command premium positioning against commodity polyethylene due to thermal runaway suppression requirements. Cost compression in standard wet-process tiers is intensifying because Chinese domestic capacity additions outpace demand absorption. Industrial battery buyers exhibit highest price sensitivity, while Tier-1 automotive cell makers prioritize supply security over unit cost.
Supply Chain Analysis
Entek International and domestic Chinese membrane producers hold concentrated dry-process and wet-process manufacturing capacity respectively. Battery-grade UHMWPE resin supply draws from Korean and Japanese petrochemical groups, ceramic coating slurries rest on European water-based acrylic reformulations, and precision coating equipment sources from Japanese technical centers. Single-source vulnerability in ultra-high molecular weight polyethylene feedstock creates input cost volatility exposure. Distribution runs through direct OEM contracting models that bypass traditional distributor channels for platform-specific membrane specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer-electrolyte interface optimization expertise remains concentrated in Japanese and Korean technical centers, constraining new entrant qualification timelines and sustaining incumbent margin structures in high-voltage electrolyte matching applications.
For Market Incumbents: Harden automotive qualification defenses by accelerating PPAP completion cycles below 12 months and deepening captive supply of ceramic coating slurry formulations. Solid-state battery interface material development represents the critical R&D lever for platform relevance extension. SK IE Technology's integrated polymer-to-membrane production model demonstrates how upstream control over UHMWPE resin buffers feedstock volatility.
For New Entrants and Emerging Players: Pursue India's PLI scheme for cell manufacturing as the most penetrable geography, where 50 GWh annual capacity targets create first-mover separator qualification windows before incumbent technical service presence solidifies. Bridge technology positioning for semi-solid battery architectures offers lower competitive density than saturated wet-process automotive tiers. Establish local technical service capabilities as the essential go-to-market angle for multi-year offtake negotiations.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because ceramic coating capabilities and automotive qualification timelines create durable moats against commodity capacity additions. Acquisition targets should display integrated polymer-to-membrane production or proprietary nano-coating technology licensable across cell maker customers. Watch solid-state battery commercialization timelines as the critical inflection signal for separator technology roadmap relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Chinese wet-process polyethylene additions compress margins and force ceramic coating differentiation. |
| Backward Integration | Captive UHMWPE resin production buffers Korean and Japanese membrane makers against feedstock volatility. |
| Long-term Supply Agreement | CATL and BYD multi-year offtake contracts with domestic producers secure localized supply security. |
| Joint Venture | European cell gigafactories in Hungary and Poland consolidate supplier bases through framework agreements. |
| Technology Licensing | Proprietary nano-coating expertise from Japanese technical centers enables high-nickel cathode thermal management. |
Methodological Framework
A standing panel of cell maker procurement directors, separator plant operations managers, ceramic coating R&D leads, and automotive Tier-1 battery platform engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from customs trade data for UHMWPE resin flows, SEC filings of listed membrane producers, GB standards documentation for lithium-ion safety certification, and EU Battery Regulation implementation guidance. Bottom-up capacity modeling and top-down demand triangulation from EV production forecasts anchored volume estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon based on solid-state battery commercialization pace and Chinese capacity absorption rates. Segmentation dimensions spanned product type, end-use archetype, thickness tier, and coating technology intensity. CAGRs were derived from fitted growth curves against historical capacity deployment patterns. Industry-specific inputs included automotive cell maker qualification timeline compression and REACH authorization sunset schedules for perfluorinated binder chemistries.
Macroeconomic conditions sit as an overlay; deviation in EV adoption rates, lithium carbonate pricing, or semiconductor availability for coating equipment would shift the trajectory. Forecasts reflect documented assumptions on cathode chemistry evolution and regulatory enforcement timelines. Quarterly review of automotive PPAP completion rates and ceramic slurry qualification progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Wash System Market
Batteries
France Rechargeable Battery Market
Batteries
Wireless Power Bank Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Europe Rechargeable Battery Market
Batteries
Medical Batteries Market
Batteries
Marine Powerboat Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
SLI Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Liquid Metal Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
South America Battery Cell Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
North Africa Battery Market
Batteries
Flow Battery Market