
 North America Wireless Healthcare Market | 2026-2036
North America Wireless Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireless Healthcare Market Analytics
Subscription-based telemetry analytics is decoupling hardware sales from recurring revenue models across the North America Wireless Healthcare Market. GE HealthCare Technologies Inc. leverages its installed base of imaging equipment to extend software-defined monitoring services. Qualcomm Technologies, Inc. anchors wireless chipset supply for FDA-cleared wearable form factors. AT&T Inc. competes on private 5G network deployments that guarantee latency thresholds for acute care settings.
Wireless healthcare comprises medical-grade data transmission systems operating across Bluetooth Low Energy, Wi-Fi 6, cellular LTE/5G, and near-field communication protocols with latency requirements typically below 250 milliseconds for critical alarm relay. These systems enable continuous physiological monitoring without tethered connections, primarily serving ambulatory patient management and decentralized clinical trials. Telehealth solutions and wearable devices capture disproportionate investment as reimbursement codes solidify for remote physiological monitoring, while bedside monitors face slower refresh cycles tied to hospital capital budgets. Mobile apps within chronic disease management represent the fastest-expanding application layer, though emergency response systems command premium pricing due to failover reliability requirements.
The FDA regulates wireless-enabled devices through its Digital Health Center of Excellence, while FCC spectrum allocations determine which frequencies support body-area networks and hospital-wide deployments. HIPAA compliance obligations shape data architecture decisions for every vendor seeking health system procurement contracts. Stakeholders must weigh interoperability mandates against proprietary platform strategies as federal agencies push open API standards for patient data exchange.
Market Dynamics
Private 5G network deployments by telecom carriers are compressing latency thresholds below 50 milliseconds for acute care settings, forcing medical device manufacturers to redesign alarm relay architectures around guaranteed service-level agreements rather than best-effort Wi-Fi.
Growth Catalysts
- CPT Code Expansion:CMS reimbursement codes for remote physiological monitoring now cover 16 distinct chronic conditions, pulling hospital systems into ambulatory telemetry programs.
- Bluetooth Low Energy 5.3:Extended advertising sets enable medical-grade wearables to broadcast continuous glucose data across 300-meter ranges without pairing overhead.
- Northeast Corridor Density:Integrated delivery networks from Boston to Washington D.C. pilot 5G-enabled surgical robotics, creating reference architectures for rural hospital adoption.
Market Restraints
- Spectrum Auction Costs:FCC CBRS Priority Access License fees in the 3.5 GHz band add $0.08-0.12 per connected device annually, eroding margins on high-volume wearable shipments.
- Semiconductor Concentration:FDA-cleared wireless chipsets rely on three foundry sources in Taiwan, exposing supply continuity to geopolitical friction.
- Legacy Bedside Refresh Cycles:Hospital capital budgets stretch monitor replacement to 7-9 years, delaying wireless-native hardware penetration in inpatient units.
Strategic Opportunities
- Rural Health Clinic Saturation:Federally qualified health centers across the Great Plains and Mountain West remain below 15% RPM penetration, presenting greenfield deployment potential.
- FDA Software-as-Medical-Device Pathway:The Digital Health Center of Excellence pre-certification program accelerates 510(k) timelines for algorithm-driven monitoring analytics.
- Wi-Fi 6E and 5G Convergence:Tri-band hospital infrastructure enables seamless handoff between unlicensed and licensed spectrum for continuous patient tracking across campus boundaries.
Industry Challenges
- FDA 510(k) Cybersecurity Burden:Post-market surveillance requirements for wireless-enabled devices now mandate 90-day vulnerability disclosure cycles, straining quality engineering headcount.
- EHR Integration Complexity:HL7 FHIR API implementation varies across Epic, Cerner, and Meditech deployments, forcing device vendors to maintain multiple middleware stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireless Healthcare Market |
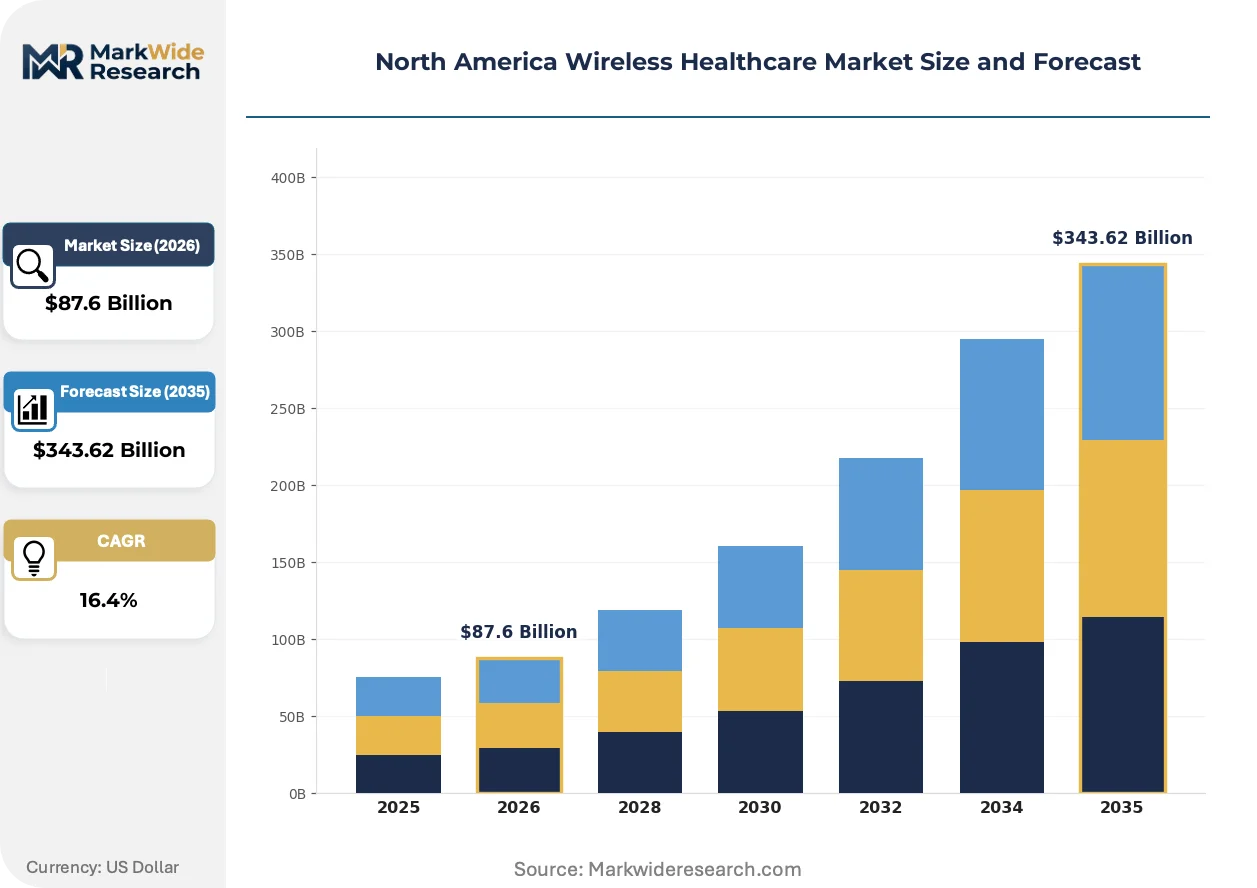
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Bedside Monitors, Telehealth Solutions End User: Hospitals, Clinics, Homecare Providers, Rehabilitation Centers Technology: Bluetooth, Wi-Fi, Cellular, NFC Application: Remote Patient Monitoring, Chronic Disease Management, Emergency Response, Medication Management |
| Companies Covered | GE HealthCare Technologies Inc., Siemens Healthcare GmbH, AT&T Inc., Cisco Systems, Inc., Qualcomm Technologies, Inc., Medtronic Plc, Philips Healthcare, Apple Inc., Verizon Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireless Healthcare Market Evolving Landscape
Edge computing architectures are relocating clinical decision support from cloud data centers to hospital premises, reducing round-trip latency for alarm generation while complicating HIPAA Business Associate Agreement structures with infrastructure vendors.
Continuous glucose monitoring is converging with insulin pump control algorithms to form closed-loop artificial pancreas systems. Pediatric endocrinology practices in the Midwest adopt these integrated platforms faster than adult diabetes clinics. The structural consequence is converging with traditional point-of-care testing revenue streams, compressing hospital laboratory margins on A1C and fasting glucose panels.
FDA's 2023 guidance on cybersecurity in medical devices mandates SBOM disclosure for wireless-enabled hardware pre-market submissions. Device manufacturers must now document third-party software dependencies across Bluetooth stacks, cellular modems, and over-the-air update mechanisms. Class II wearable manufacturers with legacy firmware architectures face 12-18 month redesign cycles to meet documentation thresholds.
Health system procurement teams now require wireless device vendors to assume liability for HIPAA breaches originating from firmware vulnerabilities, shifting cyber insurance costs onto manufacturers. This contractual evolution displaces traditional indemnification structures where hospitals retained breach responsibility. The shift is most visible in California and Texas IDN RFPs, where cybersecurity liability clauses appeared in 73% of 2024 telemetry contracts.
North America Wireless Healthcare Market Segmentation
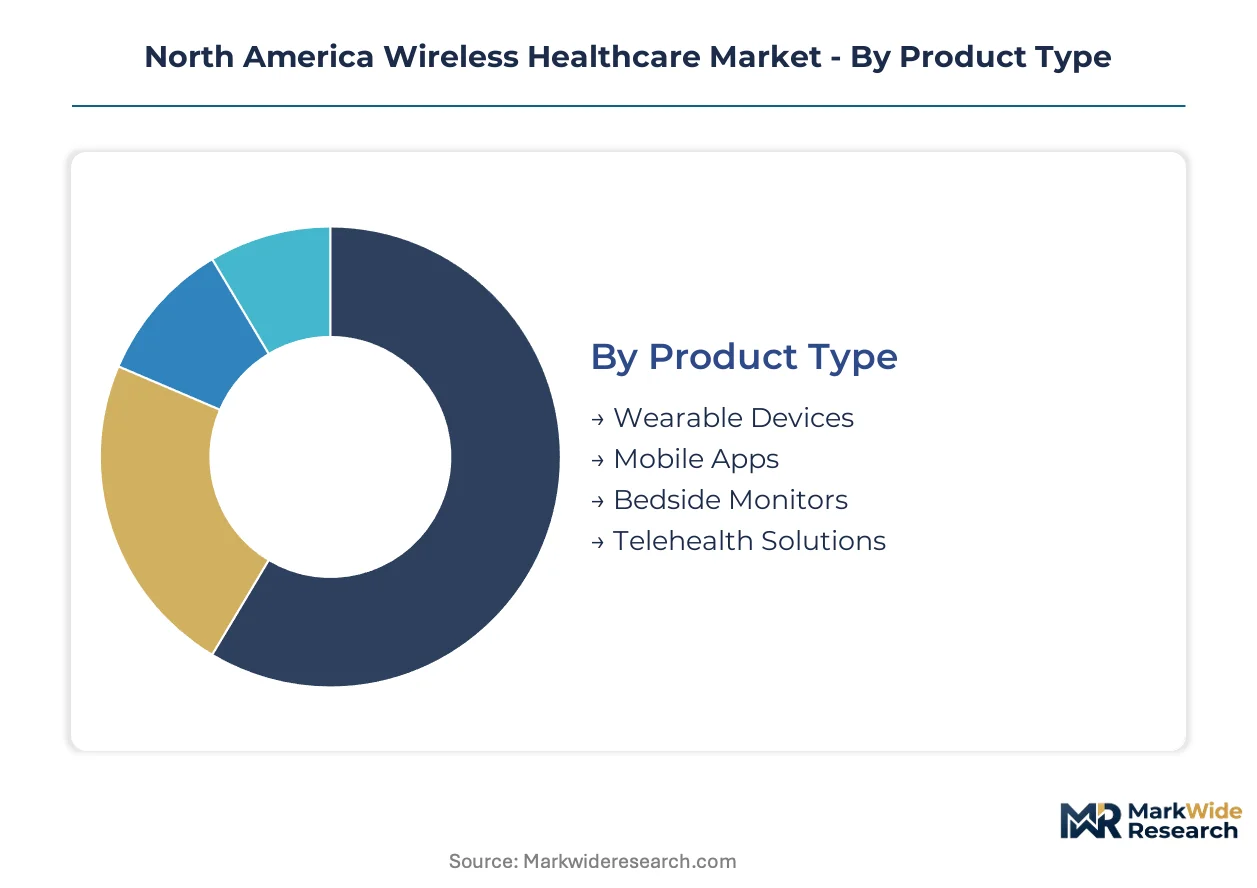
Wireless healthcare segmentation reveals divergent capital requirements across hardware, software, and infrastructure layers. Hospital procurement teams weight total cost of ownership differently for disposable wearables versus decade-long bedside monitor deployments.
Product Type:
Capital intensity varies sharply: bedside monitors demand seven-figure hospital infrastructure commitments, while mobile apps require minimal physical asset deployment.
- Wearable Devices:Continuous glucose monitors and cardiac patches incorporate FDA-cleared Bluetooth Low Energy chipsets with 300-meter broadcast ranges. Demand concentrates in the U.S. Northeast corridor where integrated delivery networks pilot 5G-enabled ambulatory programs. FCC CBRS spectrum fees add per-device annual costs that erode margins on high-volume shipments.
- Bedside Monitors:Wireless-native telemetry units replace legacy tethered systems with Wi-Fi 6E backhaul and sub-50-millisecond alarm latency. Hospital capital budgets stretch replacement cycles to 7-9 years, delaying penetration in inpatient units. The segment commands premium pricing due to failover reliability requirements for acute care settings.
- Mobile Apps:Chronic disease management platforms leverage smartphone sensors and cloud analytics with minimal hardware investment.
- Telehealth Solutions:Video consultation infrastructure requires HIPAA-compliant data centers and encrypted session management.
Bedside monitors absorb the bulk of installed capacity; mobile apps are expanding most quickly.
End User:
Customer scale determines procurement sophistication: IDNs negotiate enterprise-wide telemetry contracts while rural clinics purchase through group purchasing organizations.
- Hospitals:Acute care systems deploy private 5G networks with guaranteed service-level agreements for surgical robotics and alarm relay. The U.S. Northeast corridor from Boston to Washington D.C. pilots reference architectures that rural hospitals later adopt. Cybersecurity liability clauses now appear in 73% of telemetry contracts in California and Texas.
- Homecare Providers:Skilled nursing agencies leverage cellular-enabled wearables for post-acute monitoring without patient Wi-Fi dependency. Federally qualified health centers across the Great Plains and Mountain West remain below 15% RPM penetration, presenting greenfield deployment potential. Reimbursement codes from CMS now cover 16 distinct chronic conditions.
- Clinics:Outpatient practices integrate Bluetooth-enabled diagnostic peripherals with EHR workflows.
- Rehabilitation Centers:Long-term acute care facilities adopt continuous monitoring for ventilator-weaning protocols.
Hospitals command the largest contract values; homecare providers are gaining share fastest.
Technology:
Licensed versus unlicensed spectrum choices shape regulatory burden and deployment flexibility.
- Cellular:LTE and 5G modems guarantee connectivity beyond hospital Wi-Fi boundaries, essential for ambulatory patient tracking. Qualcomm Technologies anchors chipset supply for FDA-cleared wearable form factors. AT&T competes on private 5G deployments that guarantee latency thresholds for acute care settings.
- Bluetooth:Low Energy 5.3 enables medical-grade wearables with extended advertising sets and reduced pairing overhead. Pediatric endocrinology practices in the Midwest adopt continuous glucose monitoring faster than adult diabetes clinics. The protocol dominates body-area network deployments.
- Wi-Fi:Wi-Fi 6E tri-band infrastructure enables seamless handoff between unlicensed and licensed spectrum across hospital campuses.
- NFC:Near-field communication supports medication authentication and clinician badge proximity verification.
Cellular absorbs the bulk of infrastructure investment; Bluetooth is climbing the fastest.
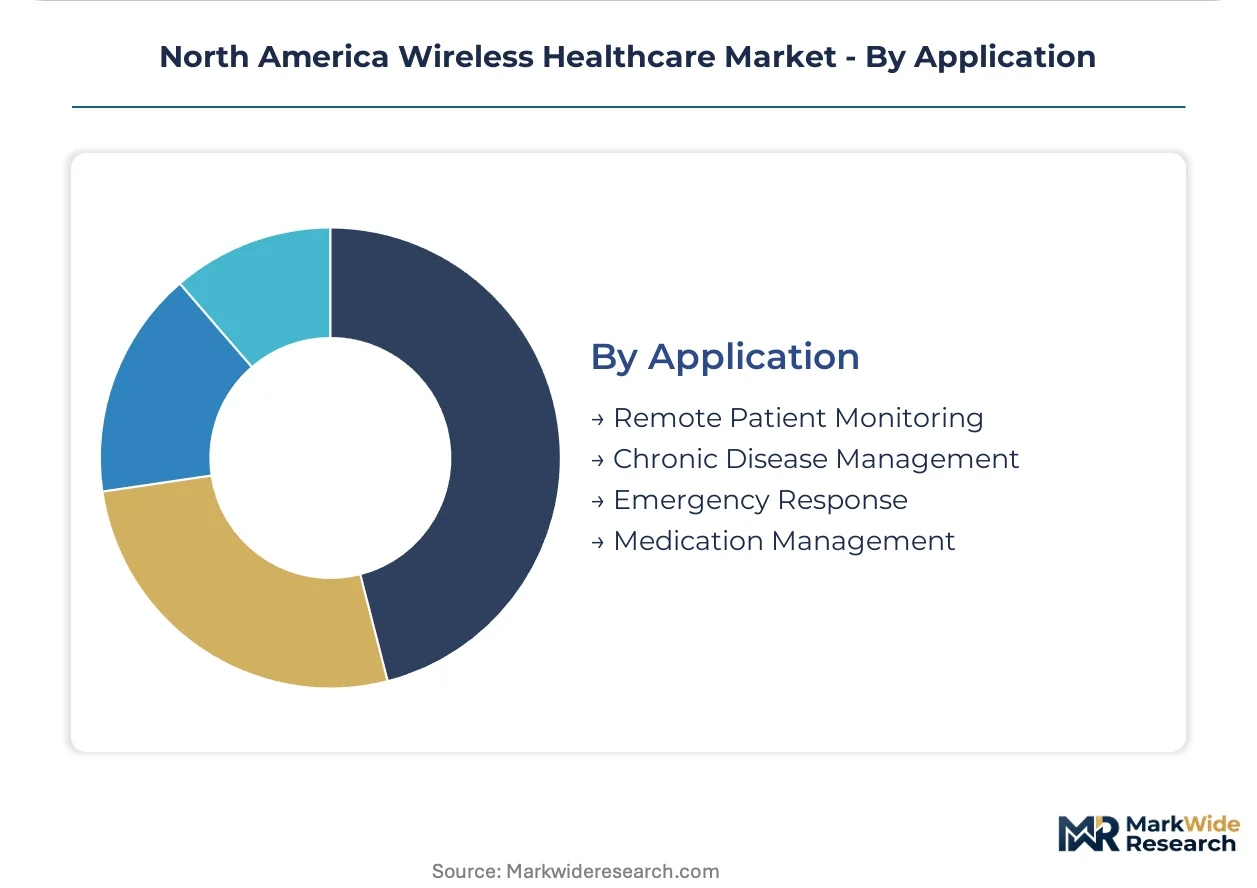
Application:
Reimbursement code availability and clinical workflow integration determine deployment velocity.
- Remote Patient Monitoring:CMS reimbursement expansion pulls hospital systems into ambulatory telemetry programs. The FDA's Digital Health Center of Excellence pre-certification program accelerates 510(k) timelines for algorithm-driven monitoring analytics. Edge computing architectures relocate clinical decision support to hospital premises to reduce alarm latency.
- Chronic Disease Management:Mobile apps represent the fastest-expanding application layer as diabetes, hypertension, and heart failure programs scale. Continuous glucose monitoring converges with insulin pump control to form closed-loop artificial pancreas systems. The structural consequence compresses hospital laboratory margins on A1C and fasting glucose panels.
- Emergency Response:Personal emergency response systems command premium pricing due to failover reliability requirements and 24/7 monitoring center obligations.
- Medication Management:Smart pill dispensers and adherence sensors integrate with pharmacy benefit manager data feeds.
Remote patient monitoring captures the largest installed base; chronic disease management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor from Boston to Washington D.C. anchors North American wireless healthcare deployment, with integrated delivery networks piloting 5G-enabled surgical robotics and reference architectures that diffuse to smaller markets.
United States Northeast
FDA-cleared wearable programs and remote patient monitoring reimbursement expansion drive demand across Massachusetts, New York, and Pennsylvania. The FDA's Digital Health Center of Excellence accelerates 510(k) timelines for algorithm-driven analytics. Boston's Longwood Medical Area hosts concentrated pilot programs for closed-loop insulin delivery systems.
United States West Coast
Technology sector integration with healthcare delivery creates demand for consumer-grade wearable convergence with clinical workflows. FCC spectrum allocations in the 3.5 GHz CBRS band shape private network deployment economics. The San Francisco Bay Area anchors development of Bluetooth Low Energy medical chipsets with extended broadcast ranges.
United States Midwest
Pediatric endocrinology practices adopt continuous glucose monitoring faster than adult diabetes clinics across Illinois, Ohio, and Michigan. CMS reimbursement codes for sixteen chronic conditions pull hospital systems into ambulatory telemetry. The Cleveland Clinic corridor serves as a testbed for Wi-Fi 6E and 5G convergence in hospital infrastructure.
Canada
Health Canada regulatory alignment with FDA digital health guidance accelerates software-as-medical-device classifications. Provincial health authority procurement centralization favors enterprise-wide telemetry contracts over point solutions. Toronto's MaRS Discovery District clusters wireless health startups targeting North American market entry.
Mexico
Medical device manufacturing concentration near the U.S. border supports wireless hardware assembly for FDA-cleared export. COFEPRIS regulatory harmonization efforts with FDA streamline cross-border product registration. The Tijuana medical device corridor specializes in Bluetooth-enabled diagnostic peripheral production.
North America Wireless Healthcare Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America Wireless Healthcare Market. The vendor base fragments across imaging equipment incumbents, telecom infrastructure providers, semiconductor specialists, and consumer technology entrants. Three archetypes dominate: integrated health technology conglomerates, wireless chipset and infrastructure suppliers, and platform-agnostic software analytics vendors. Competitive moves center on private 5G network deployment partnerships and subscription-based telemetry service launches that decouple hardware from recurring revenue.
Within the integrated health technology tier, GE HealthCare Technologies Inc. and Siemens Healthcare GmbH exemplify equipment incumbents extending software-defined monitoring services from imaging installed bases. Among wireless infrastructure specialists, AT&T Inc. and Verizon Communications Inc. anchor private 5G deployment competition for acute care latency guarantees. Qualcomm Technologies Inc. represents the semiconductor archetype supplying FDA-cleared chipsets for wearable form factors.
| Leading Market Players |
|---|
| GE HealthCare Technologies Inc. |
| Siemens Healthcare GmbH |
| AT&T Inc. |
| Cisco Systems, Inc. |
| Qualcomm Technologies, Inc. |
| Medtronic Plc |
| Philips Healthcare |
| Apple Inc. |
| Verizon Communications Inc. |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot indices from Taiwan and South Korea cascade through FDA-cleared chipset procurement contracts, stratifying North American wireless healthcare hardware across three certification-grade pricing tiers that separate premium 5G-enabled surgical telemetry from standard Bluetooth glucose monitors and economy-tier consumer wellness devices.
Pricing Analysis
Cost-down pressure on economy-tier wearables accelerates because FCC CBRS spectrum fees add per-device annual levies that erode margins on high-volume shipments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared acute care hardware from CE-marked ambulatory devices and unregulated consumer wellness trackers. Pricing pressure stems from semiconductor foundry concentration in Taiwan exposing procurement to geopolitical friction. Hospital IDNs demonstrate lowest price sensitivity due to bundled enterprise contracts, while rural federally qualified health centers exhibit acute cost consciousness.
Supply Chain Analysis
Reverse logistics flows for refurbished continuous glucose monitors and remanufactured cardiac patches concentrate in Mexico's Tijuana medical device corridor, where COFEPRIS-harmonized facilities process FDA-cleared returns for North American redeployment. Semiconductor fabrication anchors in Taiwan, South Korea, and the United States. Raw material dependencies span silicon wafers, lithium-ion cells, and medical-grade polymers. Single-source vulnerability in Taiwan foundries threatens supply continuity. Distribution runs through group purchasing organizations for hospital systems and direct-to-clinic channels for ambulatory practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American wireless healthcare is consolidating around platform-integrated incumbents as FDA cybersecurity documentation burdens force sub-scale device vendors toward distressed exits.
For Market Incumbents: Anchor private 5G network partnerships with AT&T and Verizon to lock in latency-guaranteed service-level agreements that emerging entrants cannot replicate. Deepen backward integration into FDA-cleared chipset supply through Qualcomm partnership tiers. Defend against consumer technology entrants by accelerating software-as-medical-device pre-certification through the FDA Digital Health Center of Excellence. For New Entrants and Emerging Players: Capture greenfield remote patient monitoring deployment across Great Plains and Mountain West federally qualified health centers where RPM penetration remains below fifteen percent. Target pediatric endocrinology practices in the Midwest for closed-loop artificial pancreas systems. Pursue cellular-enabled wearable form factors that bypass hospital Wi-Fi infrastructure dependencies. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-analytics specialists with FDA 510(k) clearance backlogs in the U.S. Northeast corridor. Long-term viability hinges on recurring revenue models that decouple hardware from subscription telemetry services. Monitor FDA cybersecurity guidance enforcement intensity as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Pre-Certification | Accelerates 510(k) timelines for algorithm-driven monitoring analytics through Digital Health Center of Excellence pathways. |
| Private 5G Network Deployment | AT&T and Verizon compete on latency guarantees below fifty milliseconds for acute care alarm relay architectures. |
| Hospital System Partnership | Integrated delivery networks from Boston to Washington D.C. pilot reference architectures that rural hospitals later adopt. |
| Software Companion Development | Edge computing architectures relocate clinical decision support from cloud to hospital premises reducing round-trip latency. |
| Reimbursement Strategy | CMS expansion to sixteen chronic conditions pulls hospital systems into ambulatory telemetry program investments. |
Research Methodology
Document review covered FDA 510(k) filings, FCC spectrum allocation records, and CMS reimbursement code databases, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at wireless device manufacturers. Secondary validation drew from hospital procurement databases, CB Insights venture funding trackers, and telecommunications infrastructure deployment disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segmented outputs across product type, end user, technology protocol, and application category fed into analytical frameworks spanning the projection horizon. CAGRs derived from regression against historical reimbursement expansion rates and 5G infrastructure buildout curves. Industry-specific inputs incorporated FDA digital health guidance evolution and FCC CBRS auction participation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cybersecurity enforcement intensity and Taiwan semiconductor supply continuity. Practitioners should monitor CMS remote physiological monitoring code expansion and private 5G latency guarantee contract penetration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Global Personal Health Records Software Market