
 Practice Management System (PMS) Market | 2026-2036
Practice Management System (PMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Practice Management System (PMS) Market Analytics
The gap between premium enterprise suites and commodity point solutions is rebalancing as mid-market buyers demand configurable workflows without full custom implementation. Athenahealth, Inc. leverages cloud-native architecture to sustain recurring revenue from ambulatory networks. Epic Systems Corporation anchors academic medical center deployments with deep EHR integration. Cerner Corporation competes aggressively on federal health system contracts where interoperability mandates create switching costs.
A practice management system orchestrates administrative workflows including patient scheduling, registration, billing, claims processing, and reporting for healthcare delivery organizations, typically operating through HL7 FHIR-compliant data exchange with modular API architecture. Cloud-based deployment leads segment momentum as health systems prioritize remote accessibility and reduced IT overhead, while on-premise installations retain dominance in security-sensitive settings with strict data residency requirements. Artificial intelligence integration within the technology segment is reshaping revenue cycle automation, though machine learning tools for predictive scheduling currently capture the fastest expansion in new implementations.
FDA oversight of clinical decision support modules, HIPAA security rule enforcement by the Office for Civil Rights, and ONC Cures Act Final Rule interoperability deadlines collectively raise compliance barriers for new entrants while accelerating replacement demand among legacy system users. Stakeholders must monitor how state-level Medicaid expansion timelines and Medicare reimbursement rule changes alter the addressable base of billable-claim volumes that directly determine PMS pricing power and contract renewal rates.
Market Dynamics
Cloud-native architecture is compressing replacement cycles for legacy on-premise installations as multi-location practices demand unified patient data access across state lines. HIPAA interoperability mandates and ONC certification deadlines are forcing upgrade decisions faster than typical software depreciation schedules would otherwise allow.
Growth Catalysts
- ONC Cures Act Final Rule:Interoperability deadlines accelerate replacement demand among legacy system users who cannot meet API exchange requirements without full platform migration.
- Artificial intelligence integration:Revenue cycle automation and predictive scheduling tools are capturing fastest expansion in new implementations across ambulatory networks.
- Specialty clinic consolidation:United States multi-location private practices seek unified billing and scheduling platforms that standardize operations across dispersed sites.
Market Restraints
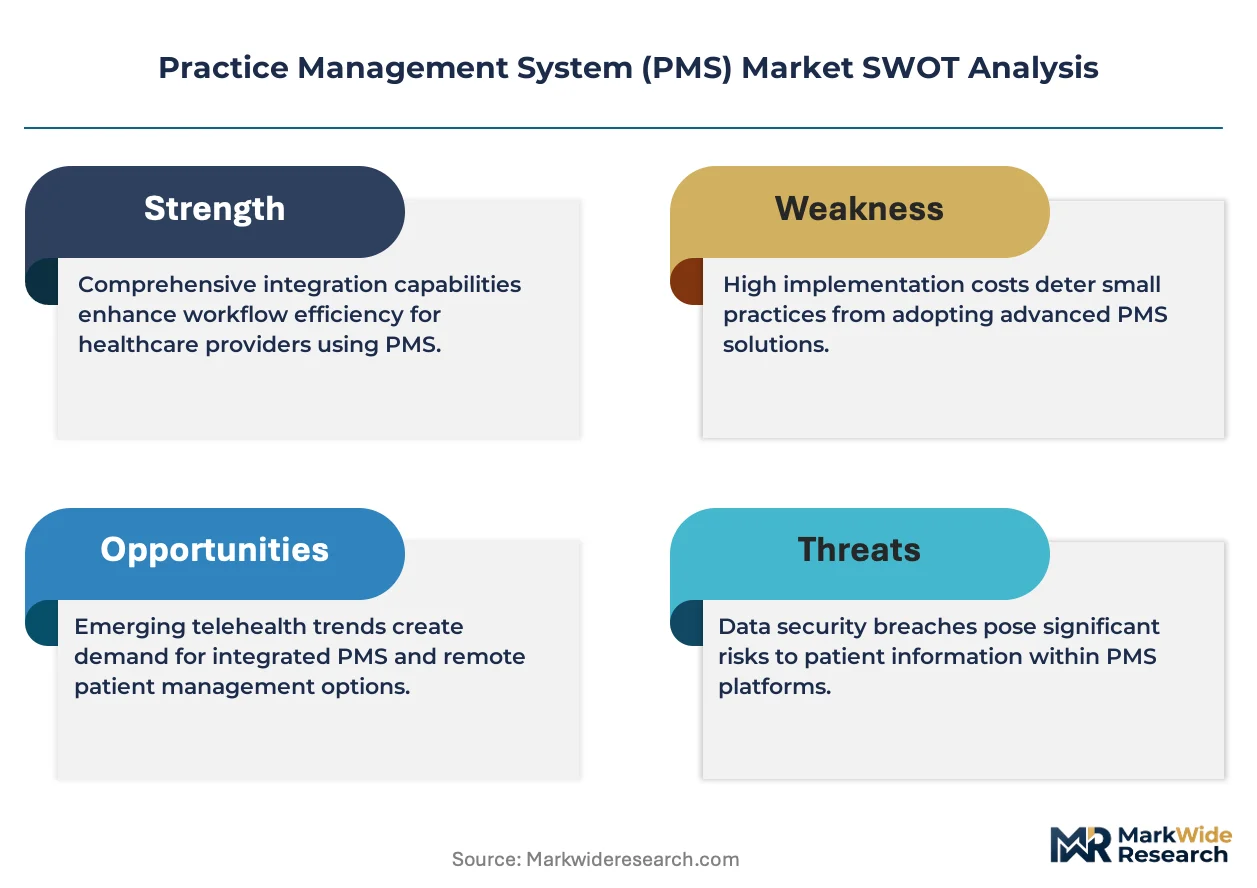
- Compliance cost escalation:FDA oversight of clinical decision support modules and HIPAA security rule enforcement raise capital barriers for new entrants without established legal infrastructure.
- Technical debt accumulation:Legacy HL7 v2 interfaces in installed base systems create integration friction that slows cloud migration timelines and extends parallel operation costs.
- Data residency requirements:Security-sensitive settings maintain on-premise dominance despite higher IT overhead, fragmenting vendor addressable market between deployment models.
Strategic Opportunities
- Medicaid expansion timelines:State-level program rollouts alter the addressable base of billable-claim volumes that directly determine PMS pricing power and contract renewal rates.
- Machine learning convergence:Predictive analytics for no-show reduction and revenue forecasting create upsell paths within existing customer accounts.
- API-first modular architecture:Configurable workflows without full custom implementation address mid-market buyer demands currently underserved by enterprise suites.
Industry Challenges
- Interoperability implementation complexity:HL7 FHIR compliance requires specialized health IT engineering talent that concentrates in established vendor ecosystems and academic medical centers.
- Medicare reimbursement rule volatility:Annual fee schedule adjustments and quality payment program changes force continuous software updates that strain smaller vendor development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Practice Management System (PMS) Market |
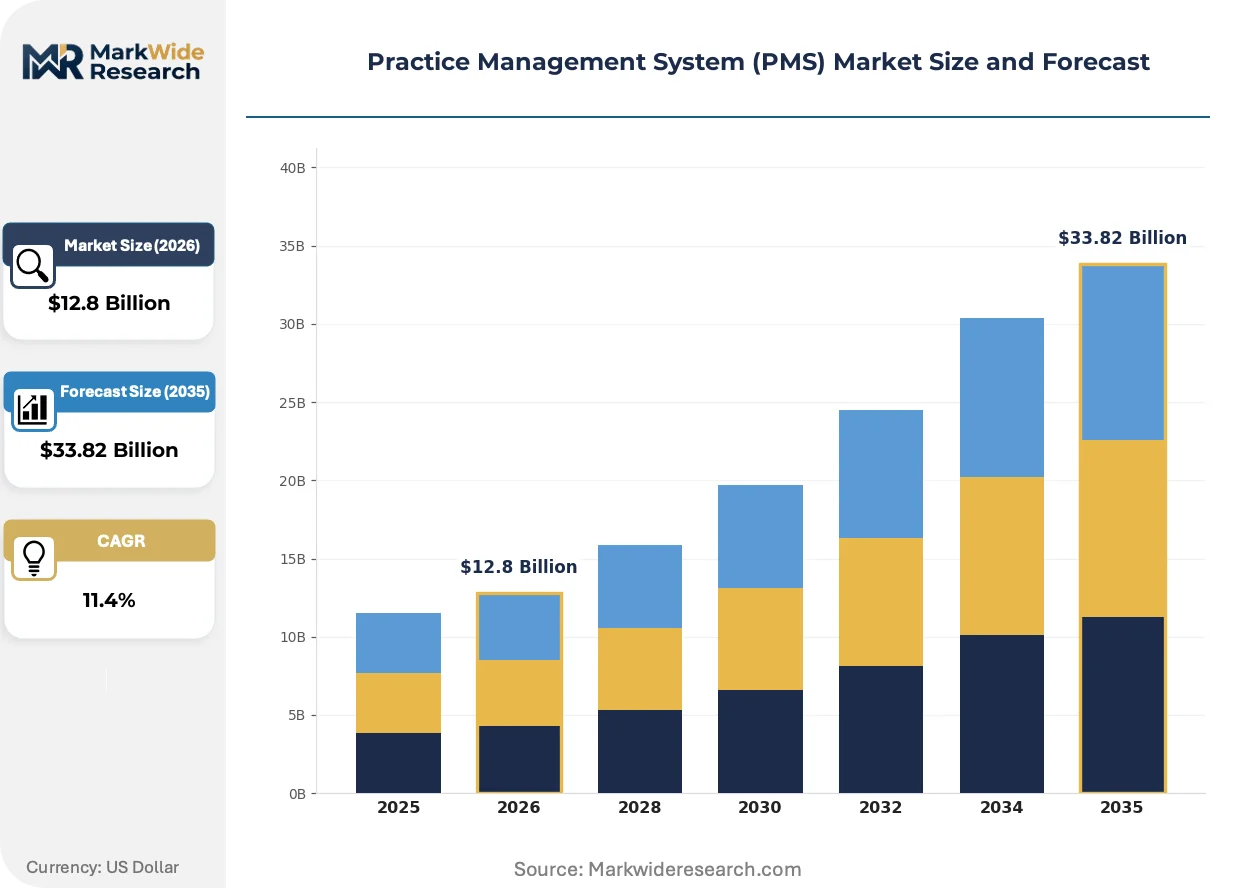
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
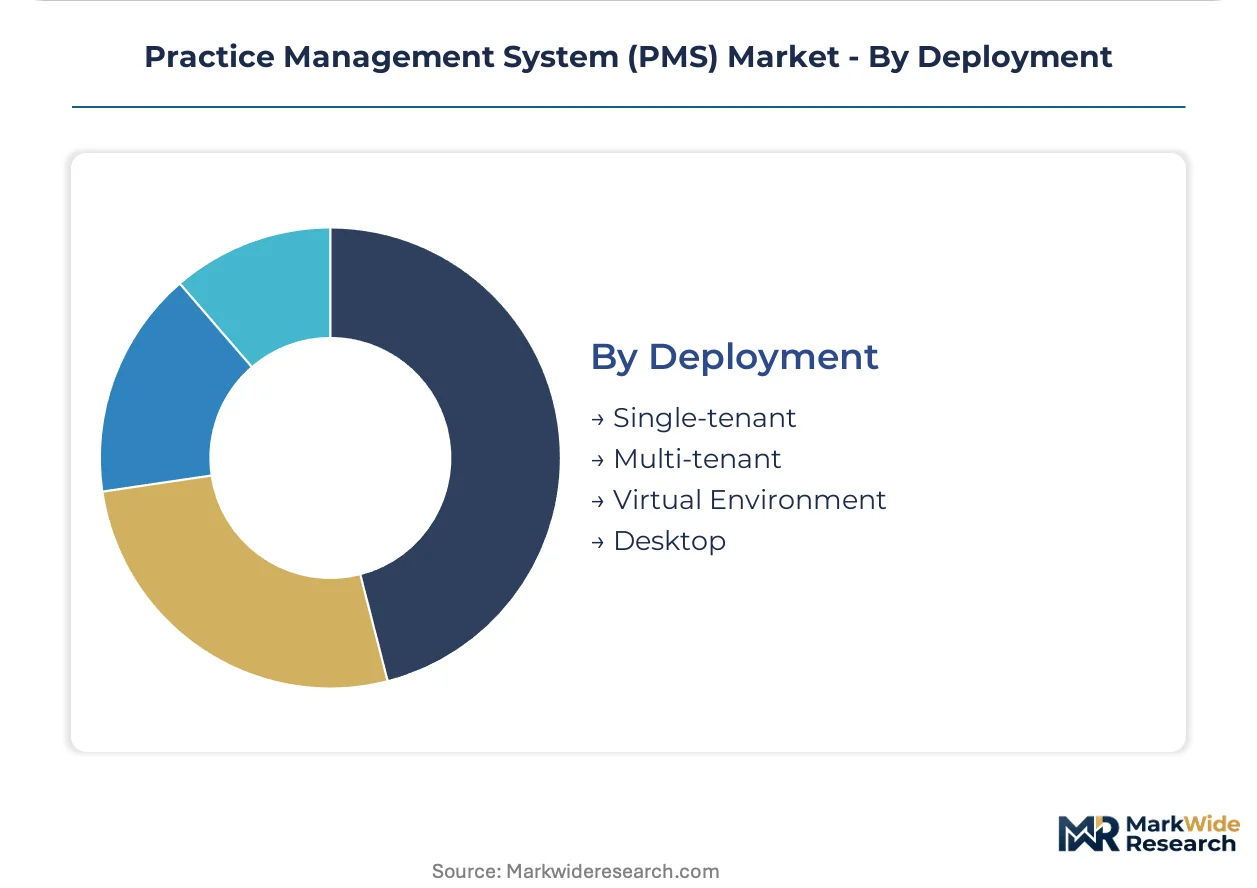
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Mobile End User: Hospitals, Clinics, Private Practices, Telehealth Providers Technology: Artificial Intelligence, Blockchain, Machine Learning, Data Analytics Deployment: Single-tenant, Multi-tenant, Virtual Environment, Desktop |
| Companies Covered | Henry Schein, Inc., Athenahealth, Inc., Veradigm LLC, Epic Systems Corporation, Cerner Corporation, eClinicalWorks, CareCloud, Inc., GE Healthcare, NextGen Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Practice Management System (PMS) Market Evolving Landscape
Artificial intelligence capabilities are migrating from peripheral automation tools to core scheduling and billing workflows, reshaping how vendors differentiate beyond basic EHR integration. The competitive frontier is shifting toward predictive operational intelligence rather than administrative digitization alone.
Machine learning for predictive scheduling is converging with natural language processing for clinical documentation, creating unified platforms that anticipate patient flow patterns while automating prior authorization workflows. Ambulatory networks with fifty-plus providers are adopting these converged suites fastest, compressing the addressable market for standalone point solutions. Specialty clinics in dermatology and orthopedics report measurable reductions in no-show rates and revenue leakage within six months of implementation.
The Office for Civil Rights has intensified HIPAA security rule enforcement through targeted audits of business associate agreements, elevating vendor liability exposure for data breaches in cloud-hosted environments. PMS providers must now maintain separate compliance infrastructure for each covered entity's specific risk profile. Small and mid-size practices lacking dedicated compliance officers are consolidating vendor relationships to reduce audit surface area, favoring platforms with embedded security monitoring.
Subscription pricing for software-as-a-service deployments is displacing perpetual license models that dominated on-premise installations, compressing upfront revenue recognition and extending customer lifetime value calculations. Value-based care organizations in Medicare Advantage networks are driving this shift, demanding outcome-aligned pricing that ties fees to measurable operational improvements. United States private equity-backed practice management companies are negotiating enterprise-wide SaaS contracts that bundle implementation, training, and ongoing optimization services into single recurring fees.
Practice Management System (PMS) Market Segmentation
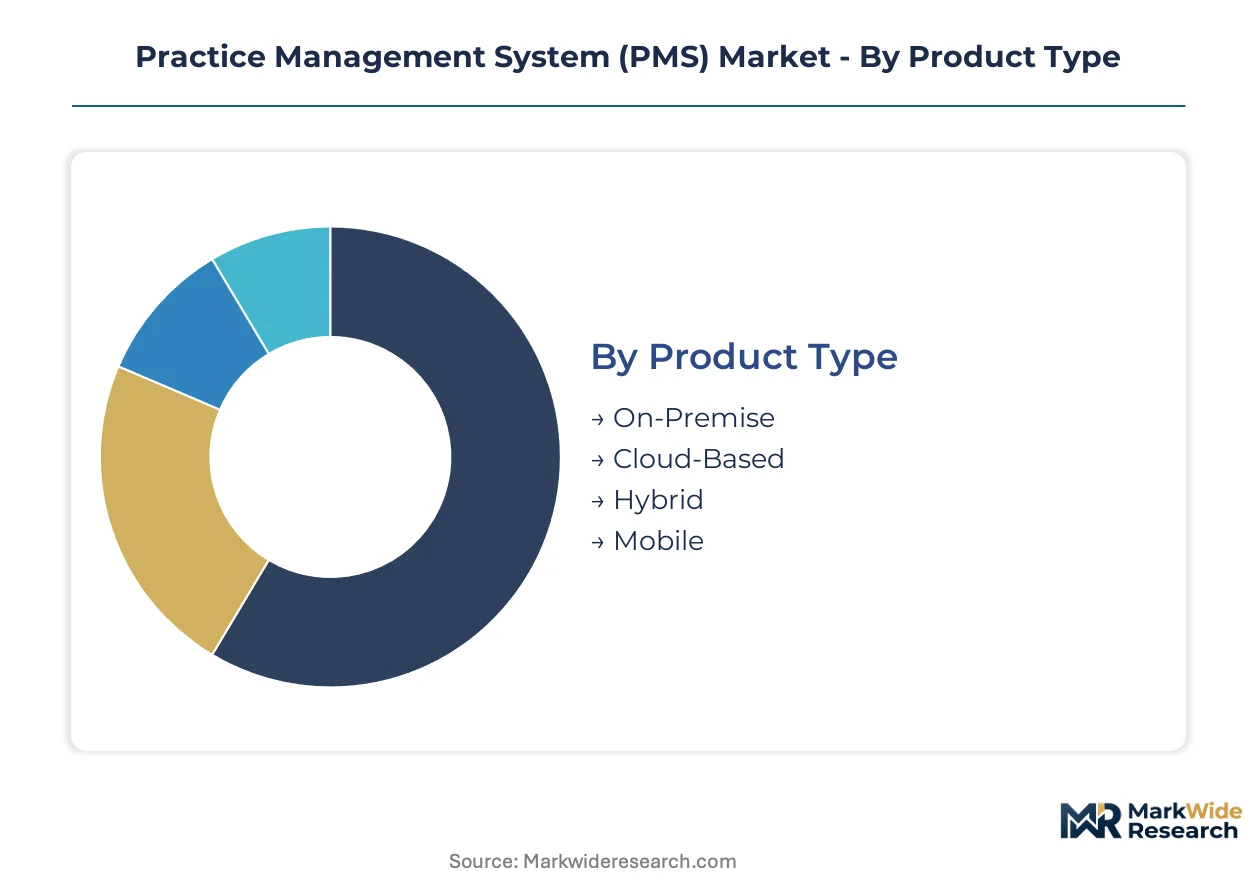
Segmentation in the Practice Management System market reveals how procurement priorities diverge across buyer types. Deployment preferences and technology readiness separate health systems seeking comprehensive platforms from specialty clinics prioritizing modular point solutions.
Product Type:
Buyers differentiate by infrastructure ownership tolerance and IT staffing levels rather than feature requirements alone.
- Cloud-Based:Fully hosted infrastructure eliminates server maintenance overhead while enabling remote access across distributed care sites. Demand concentrates among United States multi-location private practices where HIPAA-compliant data synchronization across state lines drives procurement decisions.
- On-Premise:Local server installations maintain physical data custody with dedicated hardware residing within facility premises. Security-sensitive settings in government-contracted health systems favor this model despite higher capital expenditure and internal IT burden.
- Hybrid:Split architectures retain sensitive billing data on local servers while routing scheduling through cloud interfaces.
- Mobile:Native applications optimized for tablet and smartphone workflows support point-of-care documentation.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations bridging legacy infrastructure with interoperability mandates.
End User:
Scale of administrative complexity and reimbursement mix determines platform sophistication requirements across buyer categories.
- Private Practices:Independent physician groups typically under fifty providers require streamlined billing and scheduling without enterprise overhead. United States specialty clinic consolidation is accelerating unified platform adoption across dermatology, orthopedics, and cardiology networks seeking standardized operations.
- Hospitals:Acute care systems demand deep EHR integration with inpatient revenue cycle modules and complex claims management. Academic medical centers anchor the highest-complexity deployments where research billing and graduate medical education funding streams require specialized workflow support.
- Clinics:Ambulatory facilities balance patient throughput optimization with limited IT resources.
- Telehealth Providers:Virtual-first delivery models prioritize automated eligibility verification and digital front-door patient intake.
Private Practices generate the highest transaction velocity; Hospitals command the largest per-contract value.
Technology:
Integration depth with clinical workflows separates commodity automation from differentiated intelligence offerings.
- Machine Learning:Predictive algorithms analyze historical appointment patterns to forecast no-show probability and optimize scheduling density. Ambulatory networks report measurable revenue leakage reduction within six months of implementation.
- Artificial Intelligence:Natural language processing automates prior authorization documentation and clinical coding suggestions. Medicare Advantage networks in value-based care arrangements drive fastest expansion for outcome-aligned operational intelligence.
- Data Analytics:Business intelligence dashboards aggregate claims denial patterns and payer performance metrics.
- Blockchain:Distributed ledger applications address credential verification and supply chain transparency in pilot deployments.
Data Analytics dominates current installed base; Machine Learning is climbing the fastest among new implementations.
Deployment:
Multi-tenancy architecture choices reflect vendor strategy and customer isolation requirements.
- Multi-tenant:Shared infrastructure instances partition customer data logically while pooling compute resources for cost efficiency. SaaS-native vendors leverage this model to compress implementation timelines and standardize update delivery across customer bases.
- Single-tenant:Dedicated environment deployments isolate customer instances for customized configurations and audit separation. Large health systems with specific risk profiles mandate this architecture for business associate agreement compliance.
- Virtual Environment:Containerized deployments bridge cloud flexibility with controlled infrastructure parameters.
- Desktop:Local application installations persist in rural settings with unreliable connectivity.
Multi-tenant configurations capture the broadest addressable market; Single-tenant deployments command premium pricing for compliance-sensitive buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nashville anchors North American PMS deployment activity, hosting dense clusters of health system headquarters and vendor operations centers that shape procurement patterns across the United States.
United States
Multi-location specialty clinics in dermatology and orthopedics drive unified platform adoption across state lines. HIPAA interoperability mandates and ONC Cures Act deadlines force accelerated replacement cycles for legacy installations. The Nashville-Dallas corridor concentrates vendor implementation teams serving ambulatory networks.
Germany
Academic medical centers in Baden-Württemberg and Bavaria demand deep EHR integration with research billing modules. The EU AI Act and MDR compliance requirements raise certification barriers for cloud-hosted clinical decision support. Berlin-Brandenburg hosts pilot deployments of FHIR-compliant scheduling platforms for cross-border patient data exchange.
United Kingdom
NHS England's digital transformation programs consolidate procurement around interoperable cloud solutions for primary care networks. GDPR and NHS data residency requirements create friction for multi-tenant SaaS architectures. London's Harley Street clinic cluster drives demand for premium-tier patient engagement modules.
Japan
Metropolitan Tokyo hospitals prioritize HL7 FHIR compliance ahead of the 2025 national health data exchange deadline. METI guidelines on medical AI create approval pathways for predictive scheduling algorithms. The Osaka-Kobe corridor concentrates mid-size clinic chains seeking modular billing platforms.
Australia
State-level Medicaid expansion timelines in Victoria and New South Wales alter billable-claim volumes for practice management vendors. The TGA's software as a medical device framework regulates clinical decision support modules. Sydney's private hospital networks anchor enterprise SaaS contract negotiations.
Practice Management System (PMS) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the configuration flexibility spectrum, with enterprise suites commanding sustained pricing power while point solutions face compression from converged platforms. The vendor base organizes into three strategic archetypes: cloud-native SaaS specialists, legacy EHR-integrated incumbents, and modular API-first challengers. Consolidation pressure intensifies as mid-market buyers reject custom implementation timelines. M&A activity targets workflow automation capabilities, while strategic partnerships bridge interoperability gaps between installed base systems and emerging standards.
Within the cloud-native tier, Athenahealth, Inc. and CareCloud, Inc. exemplify subscription-model architectures built for ambulatory network scale. Epic Systems Corporation anchors the EHR-integrated incumbent position, representing the academic medical center deployment pattern where deep clinical system integration creates switching costs. Cerner Corporation occupies the federal health system specialization, reflecting procurement concentration where interoperability mandates align with large-scale contract structures.
| Leading Market Players |
|---|
| Henry Schein, Inc. |
| Athenahealth, Inc. |
| Veradigm LLC |
| Epic Systems Corporation |
| Cerner Corporation |
| eClinicalWorks |
| CareCloud, Inc. |
| GE Healthcare |
| NextGen Healthcare |
| Others |
Value Network & Pricing Analysis
Health IT engineering talent concentration in Nashville and Bangalore generates labor-cost differentials that widen pricing-tier spreads between enterprise suites and mid-market configurations. Cloud-native vendors leverage lower-cost development centers to compress SaaS subscription rates while maintaining margin.
Pricing Analysis
Value-based pricing anchored to operational outcome metrics dominates Medicare Advantage network contracts, tying fees to measurable no-show reduction and revenue leakage improvement. Three-tier pricing structure across premium, standard, and economy levels separates single-tenant dedicated deployments from multi-tenant shared instances and basic scheduling-only modules. Cost compression in the economy tier is intensifying because API-first challengers commoditize core administrative functionality. Small and mid-size practices lacking dedicated compliance officers exhibit highest price sensitivity, while academic medical centers prioritize integration depth over subscription cost.
Supply Chain Analysis
Freight costs for on-premise server hardware and networking equipment concentrate procurement leverage with distributors serving United States government-contracted health systems and German academic medical centers. Software development draws from engineering talent pools in India, Poland, and the United States, with cloud infrastructure sourcing from hyperscaler data centers in Virginia, Frankfurt, and Singapore. Single-source vulnerability in HL7 FHIR compliance tooling creates bottleneck risk for vendors accelerating interoperability migrations. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers for private practice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as ONC Cures Act interoperability deadlines force smaller vendors without established legal infrastructure toward exit or acquisition.
For Market Incumbents: Extend platform integration depth into revenue cycle automation and predictive scheduling to raise switching costs against API-first challengers. Invest in backward integration into specialized health IT engineering talent pipelines to secure FHIR compliance capabilities that concentrate in Nashville and academic medical centers. Certify clinical decision support modules proactively under FDA oversight to accelerate replacement demand among legacy system users. For New Entrants and Emerging Players: The mid-market price-point gap between Athenahealth subscription tiers and economy scheduling point solutions creates white-space opportunity for configurable workflow platforms without full custom implementation. Target United States multi-location specialty clinics in dermatology and orthopedics seeking unified billing across state lines. Pursue channel partnerships with GPOs and private equity-backed practice management companies to compress customer acquisition costs. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native SaaS specialists given Medicaid expansion timelines altering addressable billable-claim volumes. Long-term viability favors vendors with embedded AI capabilities converging predictive scheduling with natural language processing for prior authorization automation. Monitor state-level Medicaid procurement announcements as inflection indicators for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep EHR connectivity with Epic and Cerner anchors academic medical center retention. |
| Acquisition of Specialist Firm | Machine learning startups for no-show prediction compress R&D timelines for ambulatory networks. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure HIPAA-compliant cloud infrastructure scale. |
| Geographic Expansion | Implementation teams in the Nashville-Dallas corridor capture multi-location specialty clinic consolidation. |
| Product Launch | FHIR-compliant API modules address ONC Cures Act deadlines forcing legacy migration decisions. |
Research Methodology
Multi-period observation of ONC certification timelines, HIPAA audit enforcement patterns, and vendor contract renewal rates anchored the trend analysis, supplemented by interviews with practice management executives, health system CIOs, GPO contracts managers, and revenue cycle directors. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, SEC 10-K filings of publicly traded vendors, and ONC interoperability dashboard metrics. Bottom-up modeling of billable-claim volumes across state Medicaid programs triangulated against top-down market sizing from vendor reported subscription metrics.
Segment-weighting across deployment models, end-user scale tiers, and technology integration depths shaped the analytical framework across the analysis window. CAGRs were derived from fitted growth curves applied to procurement pipeline data and replacement cycle acceleration patterns. Forecast inputs incorporated state-level Medicaid expansion announcements, Medicare Advantage network penetration rates, and AI module adoption velocity in ambulatory settings.
Inputs from vendor implementation teams and health system purchasing committees were available through the study window; gaps in private practice churn rates and undisclosed contract values introduce uncertainty bands around mid-market share estimates. Forecasts reflect documented assumptions regarding interoperability deadline adherence and reimbursement rule stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Global Pharmacy Management System Market