
 Non-Clinical Homecare Software Market | 2026-2036
Non-Clinical Homecare Software Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Clinical Homecare Software Market Analysis
Subscription-based software-defined feature layers is shifting how vendors monetize non-clinical homecare platforms, moving perpetual licenses toward recurring revenue architectures. WellSky leverages cloud-native infrastructure to anchor its position across scheduling and compliance modules. Netsmart Technologies competes through specialized EHR-to-homecare interoperability, while Axxess differentiates via mobile-first field clinician tools.
Non-clinical homecare software encompasses digital platforms that manage administrative, scheduling, billing, and care-coordination workflows without direct clinical documentation or diagnostic functions; core specifications include API-based interoperability with payer systems, real-time GPS-enabled caregiver tracking, and automated visit verification compliant with electronic visit verification mandates. Patient Management solutions dominate current revenue pools due to mandatory state-level EVV integration, while Cloud-Based deployment represents the fastest-expanding structural category as agencies abandon on-premises server maintenance. Billing Software segments sustain above-average margin capture where automated claims scrubbing reduces denial rates.
FDA oversight of software-as-medical-device boundaries, HIPAA security rule enforcement by HHS, and state-level Medicaid EVV mandates collectively shape product certification requirements and market access conditions for vendors serving US homecare operators. Stakeholders must monitor evolving CMS guidance on remote patient monitoring reimbursement adjacent to non-clinical platforms, as policy convergence will determine whether scheduling and communication tools absorb RPM-adjacent features or remain administratively siloed.
Market Dynamics
The US homecare software market is restructuring around electronic visit verification mandates, which force agencies to replace paper-based scheduling with GPS-enabled, timestamp-authenticated digital workflows. This regulatory pressure compresses procurement cycles and elevates interoperability requirements above standalone feature depth.
Growth Catalysts
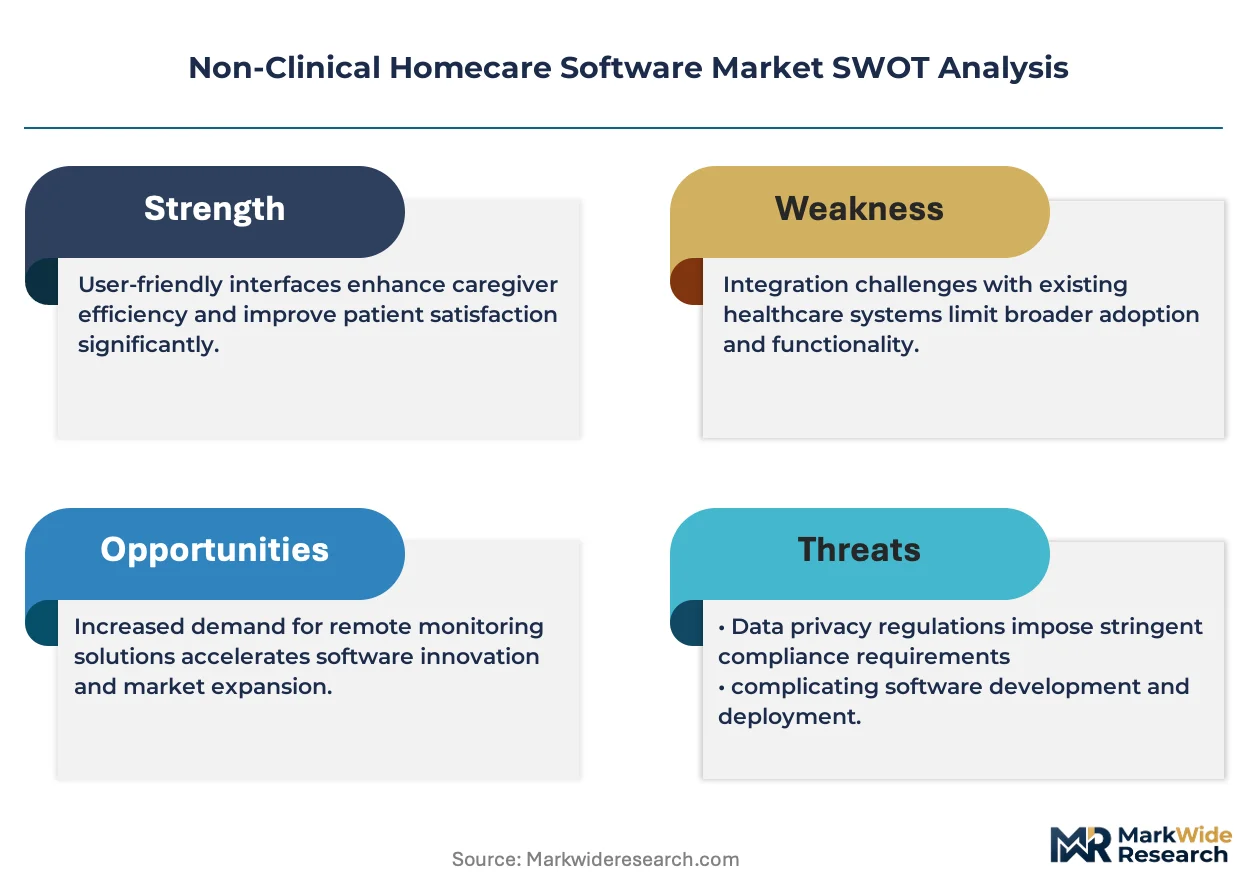
- Medicaid EVV Mandates:State-level compliance deadlines under the 21st Century Cures Act compel homecare agencies to deploy automated visit verification systems, creating immediate procurement pull for integrated scheduling platforms.
- Aging-in-Place Policy Alignment:Medicare Advantage expansion and state waiver programs redirect long-term care dollars toward home-based services, expanding the addressable agency base for software vendors.
- Cloud Migration:Multi-tenant SaaS architectures eliminate server maintenance burdens for small and mid-sized agencies, lowering adoption barriers previously sustained by capital-constrained operators.
Market Restraints
- Interoperability Fragmentation:Proprietary data formats between legacy EHR systems and modern homecare platforms force expensive custom integration work, inflating total cost of ownership for multi-vendor environments.
- Cybersecurity Compliance Burden:HIPAA Security Rule enforcement by HHS Office for Civil Rights imposes audit and encryption standards that strain engineering resources at smaller software vendors.
- Caregiver Technology Resistance:Field workforce demographics skew toward limited digital literacy, creating adoption friction that slows feature rollout and increases training costs.
Strategic Opportunities
- Remote Patient Monitoring Convergence:CMS guidance on RPM reimbursement creates white space for scheduling platforms to absorb passive monitoring alerts, blurring administrative-clinical software boundaries.
- Family Caregiver Engagement Channels:Mobile portals connecting informal caregivers to agency workflows represent an underpenetrated segment with direct-to-consumer pricing potential.
- Voice-Enabled Field Documentation:Natural language processing integration allows caregivers to complete visit notes hands-free during patient interactions, reducing documentation time and improving data quality.
Industry Challenges
- API Standardization Delays:Absence of universal data exchange protocols between payer systems and agency software forces redundant development cycles and delays revenue cycle automation.
- Workforce Management Complexity:High caregiver turnover rates and variable shift patterns demand real-time optimization algorithms that most current platforms execute poorly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Clinical Homecare Software Market |
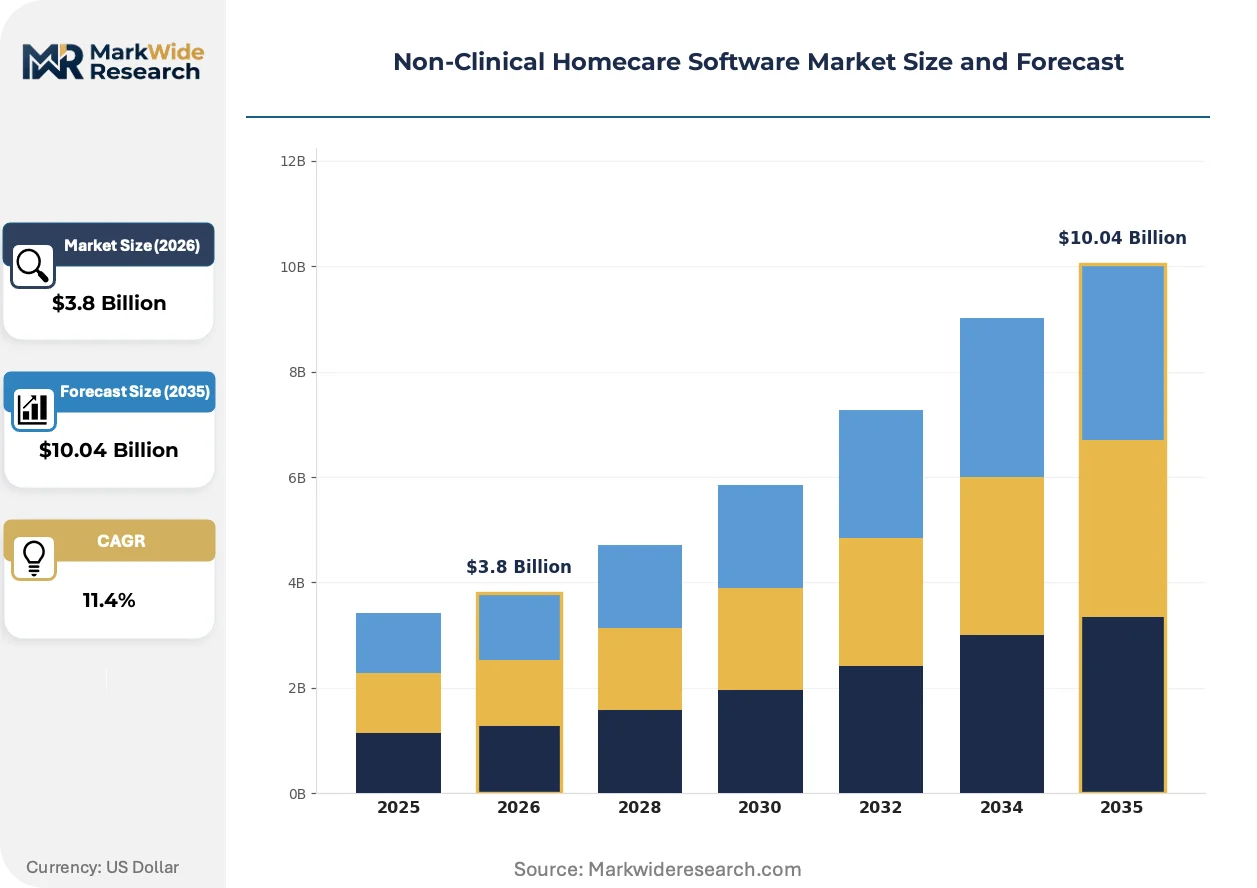
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Billing Software, Reporting Tools, Patient Management End User: Homecare Agencies, Independent Care Providers, Family Caregivers, Non-Profit Organizations Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Applications Solution: Care Coordination, Administrative Management, Communication Tools, Compliance Tracking |
| Companies Covered | Homecare Homebase, WellSky, Netsmart Technologies, Axxess, Kinnser Software, Cerner Corporation, Allscripts Healthcare, MatrixCare, CareVoyant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Clinical Homecare Software Market Emerging Trajectories
Artificial intelligence and machine learning capabilities are penetrating non-clinical homecare platforms, transforming scheduling from static calendar tools into predictive workforce optimization engines. This shift elevates software from cost center to revenue protection mechanism.
Machine learning-driven demand forecasting is rewriting how agencies staff their caregiver pools. The technology ingests historical visit patterns, seasonal acuity fluctuations, and real-time cancellation data to predict staffing needs. Large multi-site agencies in California and Texas are piloting these systems aggressively. The structural consequence is compression of overtime labor costs and reduction in missed visit penalties.
HHS Office for Civil Rights has intensified HIPAA Security Rule audit frequency for business associates handling protected health information. Homecare software vendors now face mandatory third-party penetration testing and documented incident response protocols. Small and mid-sized agencies in the Southeast are consolidating vendor relationships to reduce compliance surface area, favoring platforms with pre-built audit documentation.
Subscription pricing with usage-based tiers is displacing perpetual license models across buyer segments. Agencies prefer OpEx-aligned payments that scale with active patient census rather than upfront CapEx commitments. This shift is most visible among venture-backed homecare startups in urban markets, which prioritize cash flow preservation over long-term cost optimization.
Non-Clinical Homecare Software Market Segmentation
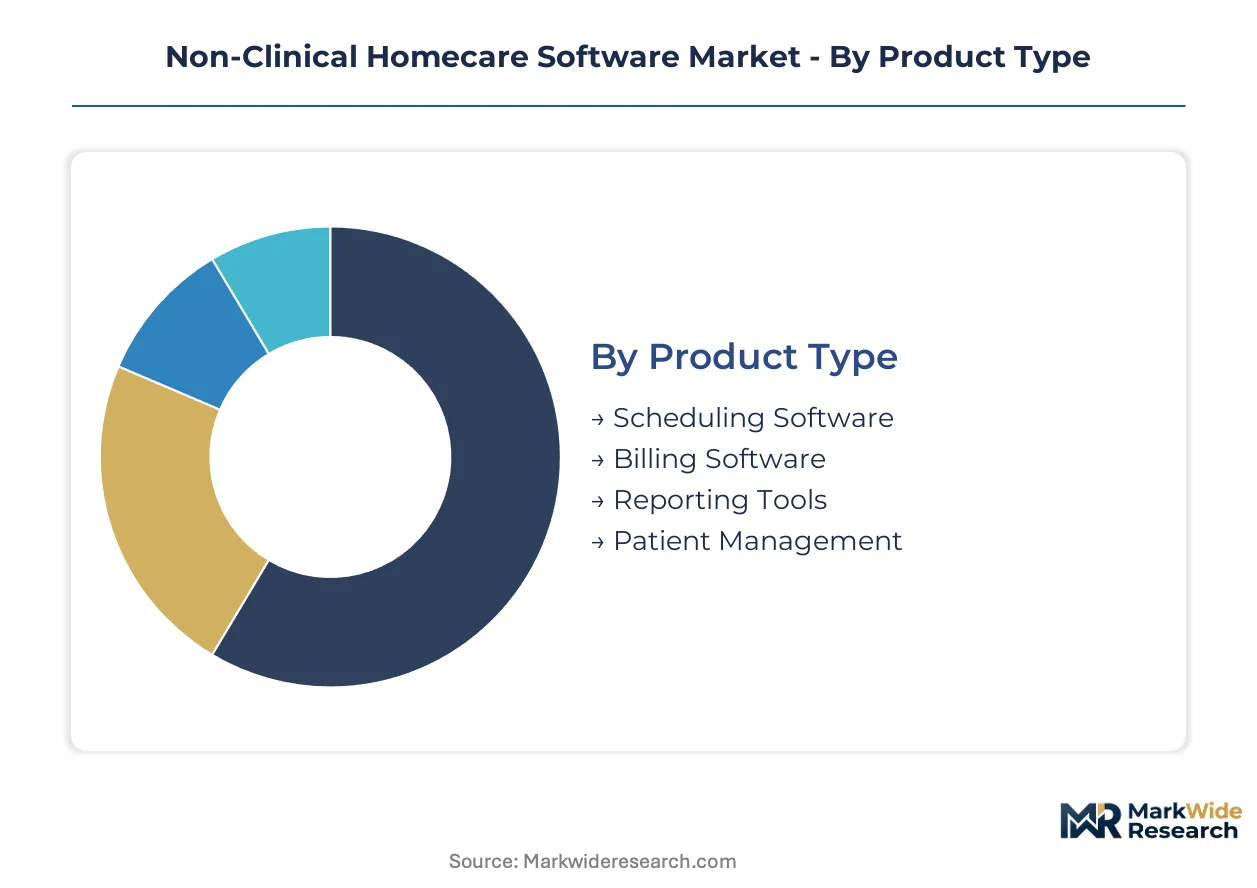
Non-clinical homecare software procurement follows distinct decision hierarchies across buyer types and operational scales. Segment boundaries determine integration complexity, pricing tolerance, and regulatory exposure for vendors competing in this $3.8 billion market.
Product Type:
Agency procurement committees prioritize workflow integration depth over standalone feature breadth when evaluating software categories.
- Patient Management:Core platforms integrate electronic visit verification, care plan documentation, and caregiver matching algorithms into unified dashboards. State Medicaid agencies in Texas and Florida mandate EVV-compliant patient management modules, forcing accelerated replacement cycles among legacy operators.
- Scheduling Software:Real-time optimization engines ingest cancellation patterns, travel distances, and caregiver skill matrices to auto-populate shift calendars. California's In-Home Supportive Services program and New York's Consumer Directed Personal Assistance Program drive concentrated demand for multi-payer scheduling flexibility.
- Billing Software:Automated claims scrubbing reduces denial rates through payer-specific rule engines.
- Reporting Tools:Analytics modules aggregate operational metrics for state compliance filings and quality improvement initiatives.
Volume sits with Patient Management; growth tilts toward Scheduling Software.
End User:
Technology sophistication and procurement authority diverge sharply across user categories, shaping vendor sales motion design.
- Homecare Agencies:Licensed operators with 50+ caregivers require enterprise-grade platforms spanning scheduling, billing, and compliance. Medicare Advantage plan contracts in Arizona and Ohio pressure these buyers toward outcomes-documentation capabilities beyond core administrative functions.
- Independent Care Providers:Solo practitioners and micro-agencies with under 10 caregivers prioritize mobile-first, low-cost solutions with minimal training overhead. Georgia and North Carolina Medicaid personal care programs expanded reimbursement eligibility for independent providers, enlarging this addressable base.
- Family Caregivers:Informal care networks access agency-branded portals for visit visibility and care plan coordination.
- Non-Profit Organizations:Community-based service providers operate on restricted funding cycles with extended procurement timelines.
Revenue concentrates among Homecare Agencies; expansion accelerates fastest for Independent Care Providers.
Deployment:
Capital availability and IT staffing levels determine architecture preferences across the buyer spectrum.
- Cloud-Based:Multi-tenant SaaS platforms eliminate server maintenance burdens and enable automatic regulatory updates. Venture-backed homecare startups in Boston and Seattle exclusively specify cloud-native procurement to preserve operating cash flow.
- Mobile Applications:Native iOS and Android tools support GPS-enabled visit verification and offline documentation for field caregivers. Rural agencies across Montana and Wyoming depend on mobile resilience where cellular coverage remains intermittent.
- Hybrid Solutions:Split architectures retain sensitive data on local servers while leveraging cloud connectivity for non-PHI functions.
- On-Premises:Legacy server installations persist among agencies with sunk infrastructure investments and specialized security requirements.
Installed base remains concentrated in On-Premises legacy systems; Cloud-Based deployment climbs the fastest.
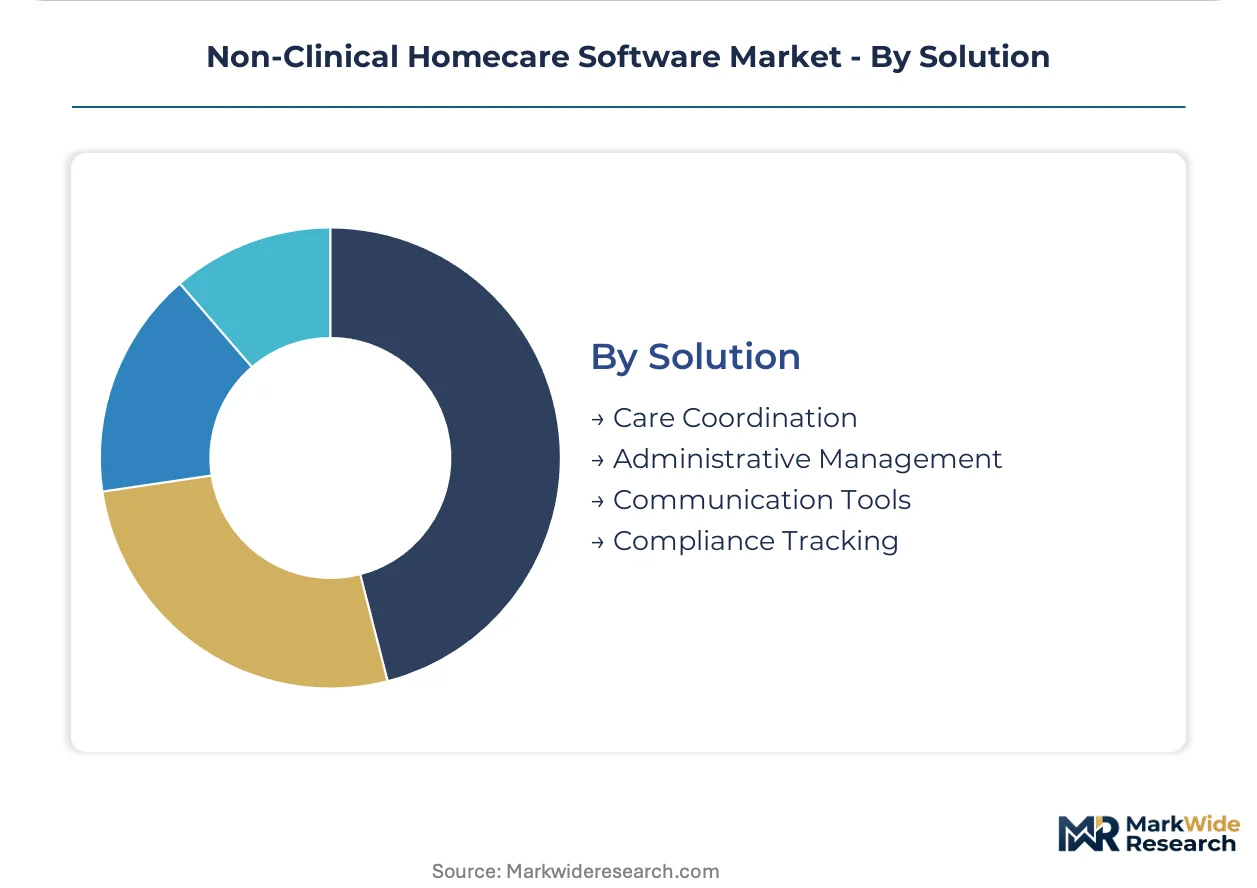
Solution:
Feature bundling strategies reflect varying buyer willingness to consolidate vendor relationships versus maintain best-of-breed stacks.
- Care Coordination:Platforms synchronize schedules, care plans, and communication across informal caregivers, formal agencies, and medical providers. Pennsylvania's Community HealthChoices program and Washington's Medicaid managed care expansion created procurement pull for multi-stakeholder coordination tools.
- Compliance Tracking:Automated audit trails, training documentation, and incident reporting satisfy state survey requirements and HIPAA Security Rule obligations. HHS Office for Civil Rights enforcement actions against business associates elevated buyer priority for pre-built compliance documentation.
- Administrative Management:Back-office modules handle payroll, accounts receivable, and human resource functions.
- Communication Tools:Secure messaging and telephony integration connect field staff with dispatch and clinical oversight.
Adoption clusters around Care Coordination; Compliance Tracking gains share fastest amid regulatory intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors software development for non-clinical homecare platforms, hosting venture-backed startups that prioritize cloud-native architectures and HIPAA-compliant data infrastructure for aging-in-place service delivery.
United States
Medicaid EVV mandates and Medicare Advantage expansion drive procurement across Texas and Florida state programs. HHS Office for Civil Rights enforces HIPAA Security Rule compliance through intensified business associate audits. Boston-area agencies pilot AI-driven scheduling optimization for multi-payer environments.
United Kingdom
NHS Long Term Plan commitments to community-based care redirect funding toward digital coordination platforms. GDPR and UK Data Protection Act requirements shape vendor encryption and breach notification protocols. London healthtech clusters develop API interoperability standards for social care scheduling systems.
Germany
Pflegeversicherung reforms expand home-based care eligibility, enlarging the addressable agency base. BSI technical guidelines and EU MDR adjacent compliance frameworks govern software certification for care coordination tools. Munich and Berlin host established EHR vendors extending into homecare administrative modules.
Japan
Super-aged society demographics accelerate demand for caregiver matching platforms under the Long-Term Care Insurance system. PMDA guidance on software-as-medical-device boundaries influences product classification for monitoring-adjacent scheduling tools. Tokyo metropolitan agencies deploy mobile-first solutions for dispersed rural caregiver networks.
Australia
Consumer Directed Care reforms under the Aged Care Act empower recipients to select digital coordination platforms. TGA oversight of health software and Privacy Act obligations structure vendor market access requirements. Sydney and Melbourne homecare providers consolidate vendor relationships to reduce compliance complexity.
Non-Clinical Homecare Software Market Vendor Landscape
Capital-heavy infrastructure providers compete with asset-light SaaS developers across deployment architectures, creating tiered competitive dynamics where server-dependent legacy systems face margin pressure from multi-tenant cloud platforms. The vendor base separates into three strategic archetypes: established healthcare IT conglomerates extending EHR footprints, pure-play homecare specialists with deep workflow integration, and mobile-native entrants targeting independent caregiver segments. Dominant competitive moves include vertical consolidation through EHR-to-homecare interoperability acquisitions and geographic expansion via state-level Medicaid contract captures.
Within the pure-play specialist tier, WellSky and Axxess occupy positions representing divergent architectural philosophies, while Netsmart Technologies exemplifies the EHR-extension archetype bridging acute and post-acute care coordination. These anchors demonstrate how vendor origin—whether rooted in legacy healthcare infrastructure or purpose-built field operations—determines feature prioritization and regulatory response velocity across state Medicaid programs.
| Leading Market Players |
|---|
| Homecare Homebase |
| WellSky |
| Netsmart Technologies |
| Axxess |
| Kinnser Software |
| Cerner Corporation |
| Allscripts Healthcare |
| MatrixCare |
| CareVoyant |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure costs cascade through SaaS pricing tiers as AWS and Azure compute rates anchor vendor cost bases before downstream subscription models reach homecare agencies. HIPAA-compliant data center investments in Northern Virginia and Dallas-Fort Worth concentrate supplier leverage among certified hosting providers, compressing margin flexibility for mid-sized software vendors competing against WellSky and Netsmart scale economies.
Pricing Analysis
Value-based pricing anchored to patient census throughput dominates vendor monetization, with per-seat subscription tiers scaling from independent caregiver solo practitioners to multi-site agency enterprise deployments. Price differentiation separates cloud-native platforms with pre-built EVV compliance from legacy on-premises systems requiring costly customization. Pricing pressure stems from Medicaid reimbursement rate compression in Texas and Florida state programs, squeezing agency software budgets. Independent care providers with under ten caregivers exhibit highest price sensitivity, while Medicare Advantage contracted agencies absorb premium pricing for outcomes-documentation capabilities.
Supply Chain Analysis
API middleware supply rests on California-based interoperability specialists and Bangalore offshore development centers, creating geographic concentration risk for real-time scheduling integration. Cloud infrastructure draws from AWS US-East, Azure Central US, and Google Cloud Iowa data centers, with mobile application development tethered to iOS and Android ecosystem updates. Single-source vulnerability concentrates in GPS-enabled visit verification chipsets sourced from Taiwan semiconductor fabricators. Distribution runs through direct enterprise sales teams for large agencies and channel partner networks serving independent provider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over EHR-to-homecare data pipelines determines pricing power and customer retention velocity.
For Market Incumbents: Deploy acquisition-led interoperability expansion to neutralize API fragmentation threats from emerging scheduling specialists. Consolidate state Medicaid EVV contract captures in Texas and Florida before compliance deadlines lock in switching costs. Channel control through certified implementation partner networks defends against mobile-native entrants targeting independent caregivers. For New Entrants and Emerging Players: Independent caregiver cooperatives in Georgia and North Carolina represent the most penetrable white-space segment following Medicaid personal care program expansions. Family caregiver engagement portals for informal care networks offer direct-to-consumer pricing potential absent agency procurement committee friction. Voice-enabled field documentation partnerships with natural language processing providers unlock differentiation against established scheduling incumbents. For Investors and Strategic Acquirers: CMS guidance convergence on remote patient monitoring reimbursement is the leading indicator that administrative-clinical software boundaries will dissolve, creating platform consolidation opportunities. Acquisition targets should display pre-built HIPAA audit documentation and multi-payer scheduling flexibility across Medicare Advantage and Medicaid managed care contracts. Watch for AI-driven workforce optimization pilot results from California and Texas multi-site agencies as inflection signals for predictive scheduling adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | EVV-compliant scheduling merger with billing modules reduces vendor fragmentation for Texas Medicaid agencies. |
| Acquisition of Specialist Firm | Voice-enabled documentation targets caregiver technology resistance in rural Montana and Wyoming markets. |
| Strategic Partnership | EHR interoperability alliances with Netsmart extend acute-to-post-acute care coordination for Medicare Advantage plans. |
| Geographic Expansion | State-level Medicaid contract captures in Florida and Ohio lock in switching costs before compliance deadlines. |
| Product Launch | Family caregiver mobile portals open direct-to-consumer revenue channels outside agency procurement cycles. |
Methodological Framework
Multi-period observation of EVV mandate compliance timelines and cloud migration patterns anchored the trend analysis, supplemented by interviews with homecare agency operations directors, state Medicaid program administrators, HIPAA compliance officers, and software vendor product managers. Secondary validation drew from CMS Medicare reimbursement guidance, HHS Office for Civil Rights enforcement actions, state Medicaid EVV implementation reports, and SEC filings of publicly traded healthcare IT conglomerates. Bottom-up agency census data triangulated against top-down software vendor revenue disclosures.
Input-output matrices modeled deployment architecture shifts, organization size stratification, vertical integration depth, and regional regulatory intensity across the projection horizon. Segmentation dimensions included product type, end-user category, cloud versus on-premises deployment, and solution bundling strategy. CAGRs derived from fitted growth curves applied to historical procurement velocity and payer policy trajectories. Forecast inputs incorporated caregiver workforce turnover rates and state-level Medicaid reimbursement rate trajectories.
Caveats apply where CMS remote patient monitoring guidance revisions or HHS HIPAA Security Rule enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions about EVV mandate deadline adherence and cloud infrastructure cost trajectories. A small set of named triggers—CMS reimbursement convergence, state Medicaid program consolidation, and cybersecurity incident frequency—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Neurosurgery Software Market