
 North America 3D Printing in Healthcare Market | 2026-2036
North America 3D Printing in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
North America 3D Printing in Healthcare Market Insights
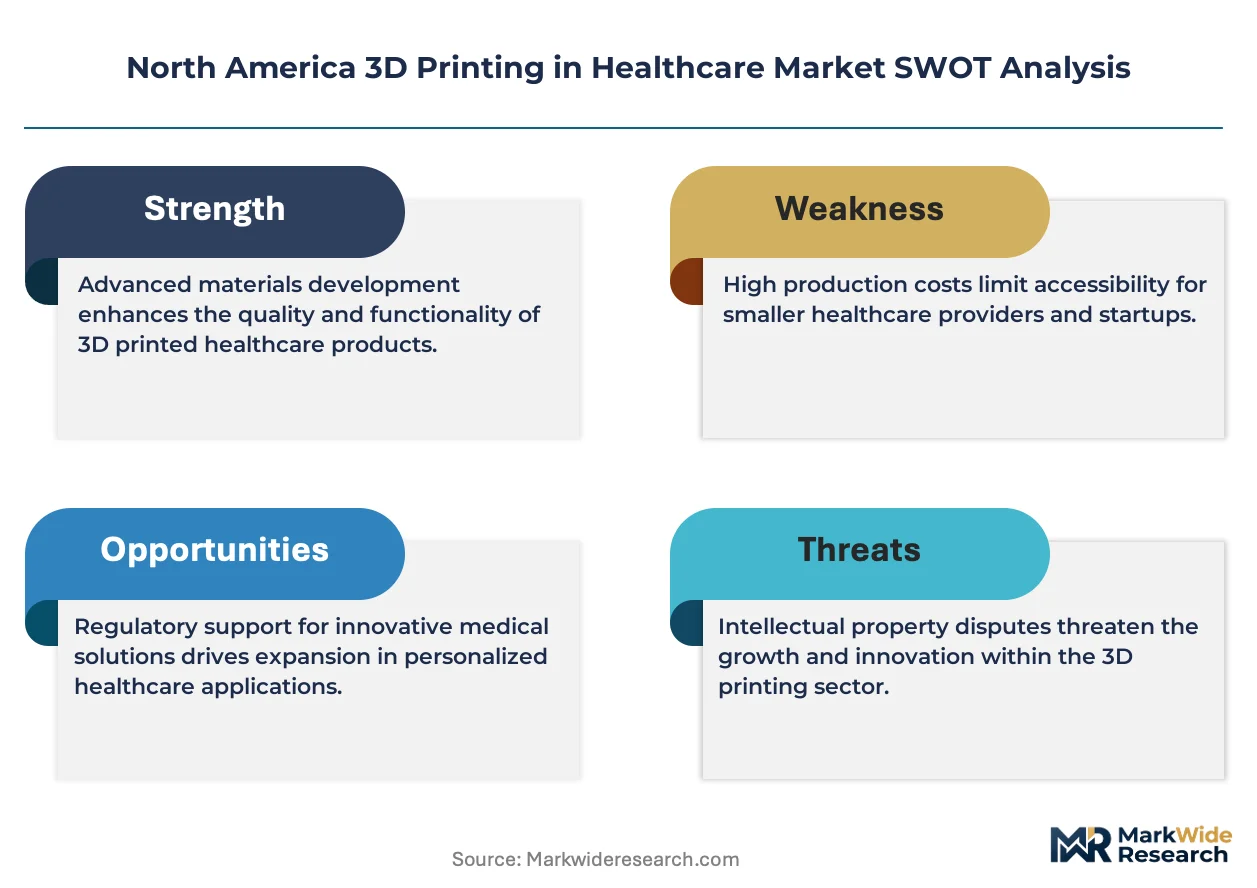
Biomedical engineering talent scarcity is bifurcating the North America 3D Printing in Healthcare Market into organizations that cultivate in-house additive manufacturing expertise and those dependent on external service bureaus. Materialise leverages decades of surgical planning software integration to dominate patient-specific workflow platforms across the continent. GE Healthcare anchors industrial-scale metal printing capacity for orthopedic implant production, while Stratasys Ltd. competes through polymer system specialization targeting dental and anatomical modeling applications.
North America 3D Printing in Healthcare encompasses additive fabrication of patient-matched devices, surgical instruments, and biological scaffolds using layer-by-layer deposition of polymers, metals, ceramics, or bioinks with resolution tolerances typically ranging from 50 to 250 micrometers. The technology serves clinical purposes spanning preoperative visualization, custom implant osseointegration, and regenerative matrix architectures. Surgical instruments and implants constitute the most mature product segments with established reimbursement pathways, whereas bioprinted tissues represent the frontier where margin pools remain speculative but R&D intensity concentrates. Selective laser sintering and digital light processing technologies lead production throughput for end-use medical devices, while fused deposition modeling dominates low-cost anatomical modeling in teaching hospitals.
FDA's Additive Manufacturing Working Group and the agency's Technical Considerations for Additive Manufactured Medical Devices guidance shape device clearance requirements, material qualification protocols, and post-market surveillance obligations across the United States. Health Canada and the FDA both mandate biocompatibility testing aligned with ISO 10993 standards for patient-contacting components, creating cross-border regulatory convergence that simplifies multi-jurisdictional product registrations. Stakeholders must monitor evolving software-as-medical-device classifications for AI-generated print parameters and real-time quality control algorithms that regulators are actively reassessing.
Market Dynamics
Patient-specific orthopedic implants are displacing off-the-shelf inventory across North American health systems, compressing surgical revision rates while forcing hospitals to choose between capital-intensive point-of-care fabrication and outsourced production partnerships.
Growth Catalysts
- FDA Additive Manufacturing Working Group:Streamlined premarket submission pathways for polymer and metal implant producers reduce regulatory friction and accelerate device clearance timelines.
- Hospital-based 3D printing labs:Academic medical centers in Boston, Cleveland, and Houston now produce surgical guides and anatomical models at the point of care, embedding additive manufacturing into clinical workflows.
- Selective laser sintering:This metal deposition technology enables osseointegration-optimized lattice structures that improve patient outcomes in load-bearing orthopedic applications.
Market Restraints
- Titanium powder supply concentration:Feedstock for orthopedic metal printing concentrates among a limited supplier base, creating input cost volatility and quality consistency risks.
- Biocompatibility testing requirements:ISO 10993-aligned validation protocols for patient-contacting components extend development timelines and elevate qualification costs for new material entrants.
- Off-the-shelf implant substitution:Mass-produced devices retain cost advantages for standard anatomies, limiting addressable market penetration in price-sensitive patient populations.
Strategic Opportunities
- Canadian regulatory convergence:Health Canada's alignment with FDA biocompatibility standards simplifies multi-jurisdictional registrations, opening cross-border commercialization pathways for US device developers.
- Bioprinted tissue matrices:Regenerative scaffold architectures represent an underdeveloped frontier where R&D investment concentrates ahead of speculative margin pool formation.
- AI-generated print parameters:Software-as-medical-device classifications for real-time quality control algorithms are actively under regulatory reassessment, creating first-mover positioning potential.
Industry Challenges
- Biomedical engineering talent scarcity:Organizations lacking in-house additive manufacturing expertise remain dependent on external service bureaus, constraining workflow integration and IP control.
- Post-market surveillance obligations:FDA mandates for long-term implant performance tracking impose data infrastructure requirements that strain mid-cap manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America 3D Printing in Healthcare Market |
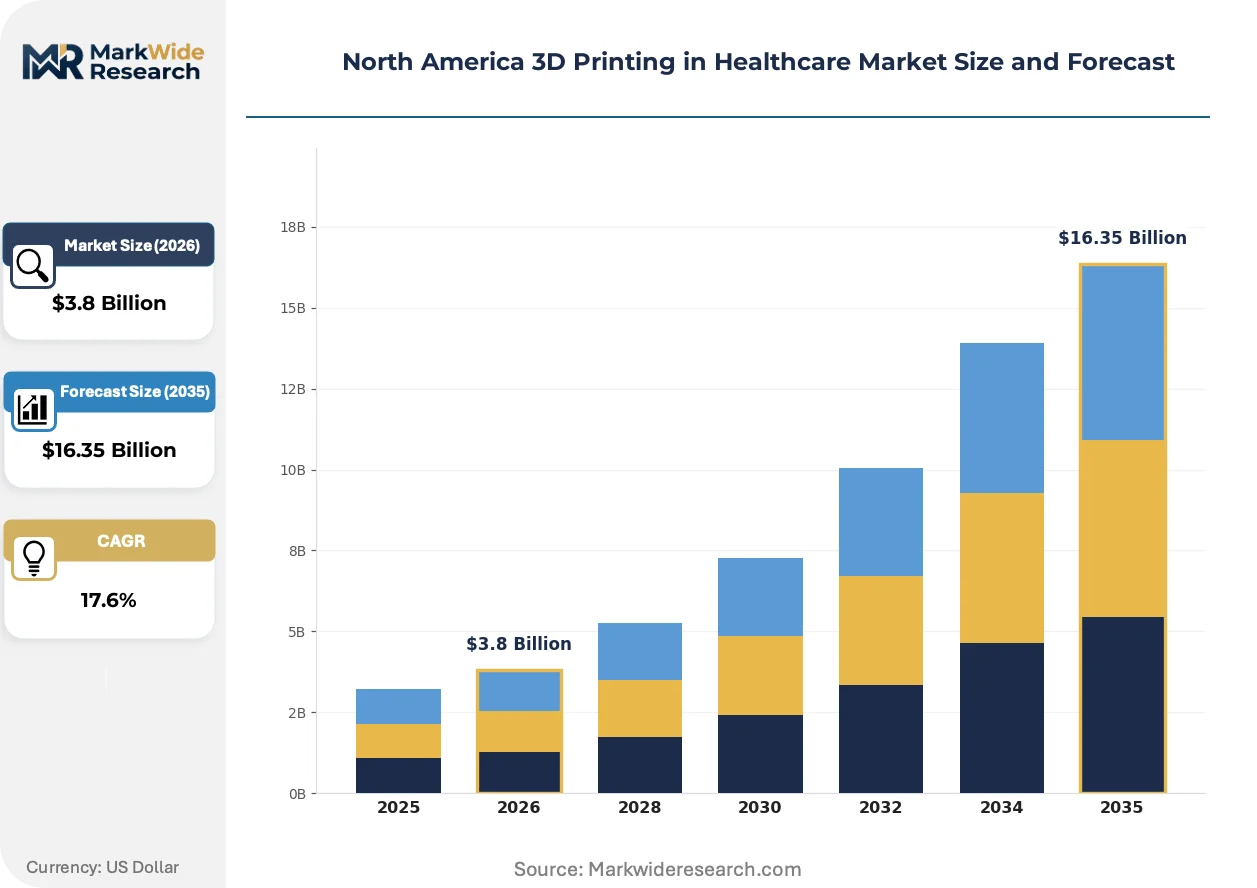
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping Models, Surgical Instruments, Implants, Bioprinted Tissues Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User: Hospitals, Clinics, Research Institutions, Medical Device Manufacturers Application: Orthopedics, Dentistry, Prosthetics, Tissue Engineering |
| Companies Covered | 3D Systems, Inc., Stratasys Ltd., Carbon, Inc., ENVISIONTEC, Inc., Materialise, EOS GmbH, GE Healthcare, Organovo Holdings, Inc., regenHU, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America 3D Printing in Healthcare Market Trends and Innovations
Digital light processing systems are compressing production timelines for dental and anatomical modeling applications, while regulatory frameworks evolve to address algorithmic quality control and software-defined device parameters.
Micro-stereolithography systems are miniaturizing feature resolution for vascular scaffold and micro-needle array fabrication. Ocular device manufacturers in California and Minnesota adopt these platforms to produce patient-matched glaucoma drainage implants with 25-micrometer channel tolerances. The technology is miniaturizing anatomical complexity thresholds previously unreachable with conventional subtractive methods, opening micro-implant categories to additive production.
FDA's Technical Considerations for Additive Manufactured Medical Devices guidance establishes material qualification protocols that harmonize with Health Canada requirements. Device developers now navigate unified biocompatibility testing frameworks across the United States and Canada, reducing redundant validation expenditure. Polymer implant segments respond fastest, with PEEK cranial plate submissions leveraging cross-border regulatory convergence.
Hospital procurement committees now evaluate total cost-of-ownership models that incorporate sterilization logistics, revision surgery probability, and inventory carrying costs alongside unit device pricing. Orthopedic departments in Texas and Ohio health systems increasingly source patient-specific implants through consignment arrangements rather than capital purchase. This behavioral shift concentrates purchasing influence within supply chain and value analysis committees, displacing individual surgeon preference as the dominant selection criterion.
North America 3D Printing in Healthcare Market Segmentation
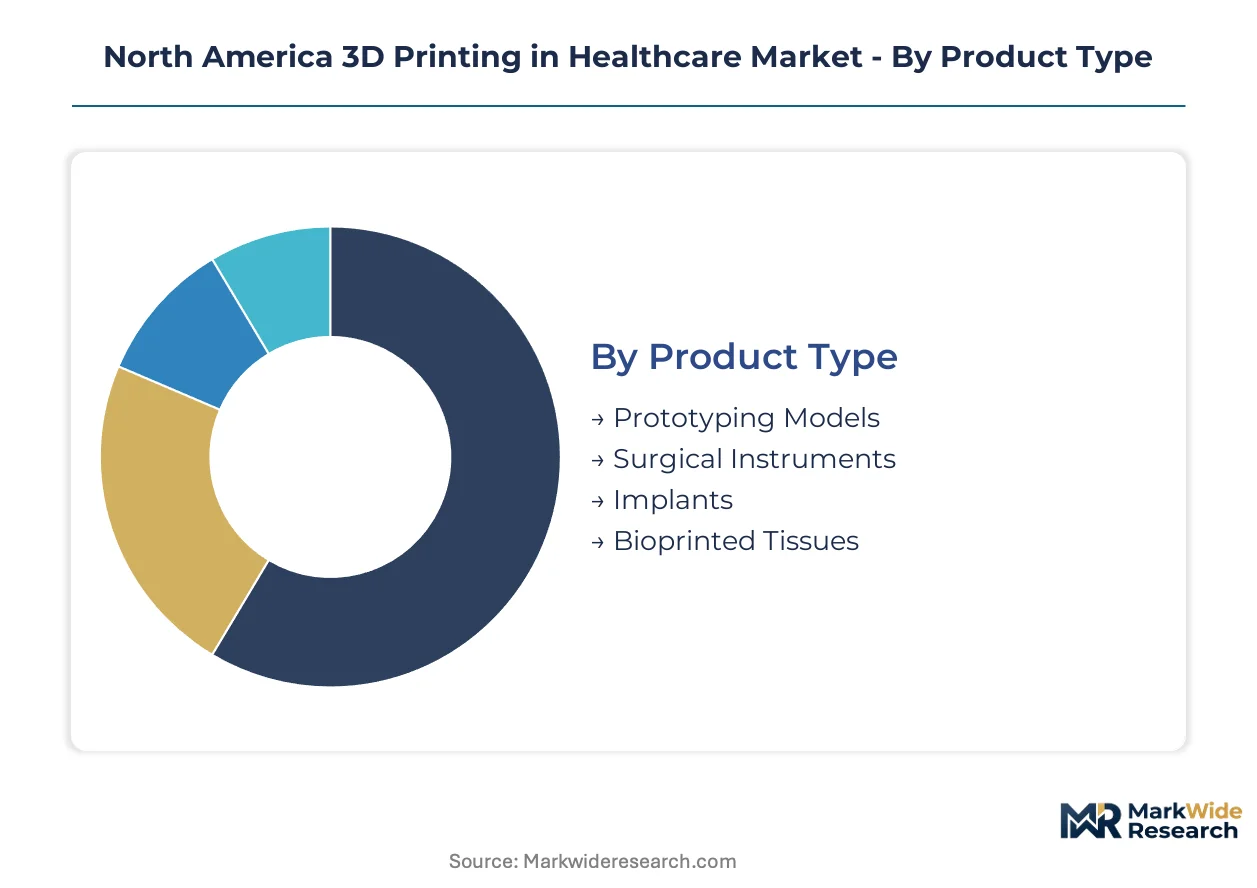
Segmentation reveals where additive manufacturing displaces conventional fabrication versus where it merely supplements existing workflows. Each dimension exposes different substitution pressures, technology readiness levels, and margin structures across the North American healthcare ecosystem.
Product Type:
Implants face the most acute substitution threat from patient-matched geometries, while bioprinted tissues remain protected by biological complexity barriers that conventional manufacturing cannot replicate.
- Implants:Patient-specific orthopedic and cranial devices fabricated from titanium alloys and PEEK polymers achieve superior osseointegration through lattice architectures. Cleveland Clinic and Houston Methodist now source these through consignment models rather than capital purchase, embedding additive manufacturing into supply chain workflows.
- Surgical Instruments:Custom retractors, guides, and cutting jigs match individual patient anatomy from preoperative imaging data. Boston academic medical centers operate point-of-care fabrication labs that compress sterilization logistics and revision probability into total cost-of-ownership evaluations.
- Prototyping Models:Anatomical replicas for surgical planning dominate teaching hospital procurement in Texas and Ohio health systems.
- Bioprinted Tissues:Regenerative scaffolds remain pre-commercial with speculative margin pools concentrated in R&D-intensive California and Minnesota clusters.
Implants retain volume leadership; bioprinted tissues hold the steepest expansion curve.
Technology:
Cost tier stratification separates production-grade metal systems from accessible polymer platforms, with mid-range investments concentrating in dental and anatomical modeling applications.
- Selective Laser Sintering:Metal powder bed fusion produces load-bearing orthopedic implants with 50-100 micrometer feature resolution. FDA's Additive Manufacturing Working Group has streamlined premarket submissions for these devices, accelerating clearance timelines for titanium lattice structures.
- Fused Deposition Modeling:Thermoplastic extrusion systems dominate low-cost anatomical modeling in teaching hospitals where capital constraints limit equipment acquisition. ABS and PLA filaments serve visualization purposes without biocompatibility requirements for patient contact.
- Stereolithography:Photopolymer resin curing achieves finest surface finish for dental crown and bridge production in Minnesota and California manufacturing clusters.
- Digital Light Processing:Projection-based photopolymerization compresses batch production timelines for surgical guide fabrication across mid-Atlantic health systems.
Selective laser sintering commands premium pricing; digital light processing is gaining share fastest among new installations.
End User:
Customer type determines whether additive manufacturing operates as captive in-house capability or outsourced service bureau dependency, with workflow integration depth varying accordingly.
- Hospitals:Academic medical centers in Boston, Cleveland, and Houston maintain dedicated 3D printing labs producing surgical guides and anatomical models at point of care. These facilities face biomedical engineering talent scarcity that constrains IP control and workflow autonomy.
- Medical Device Manufacturers:Industrial-scale producers leverage GE Healthcare's metal printing capacity and Stratasys polymer systems for regulatory-cleared implant production at volume.
- Research Institutions:University-affiliated laboratories in Texas and Ohio concentrate bioprinting R&D ahead of commercial margin formation.
- Clinics:Outpatient surgical centers rely on external service bureaus for patient-specific instrument procurement without capital equipment investment.
Hospitals anchor installed base expansion; medical device manufacturers capture value-added production margins.
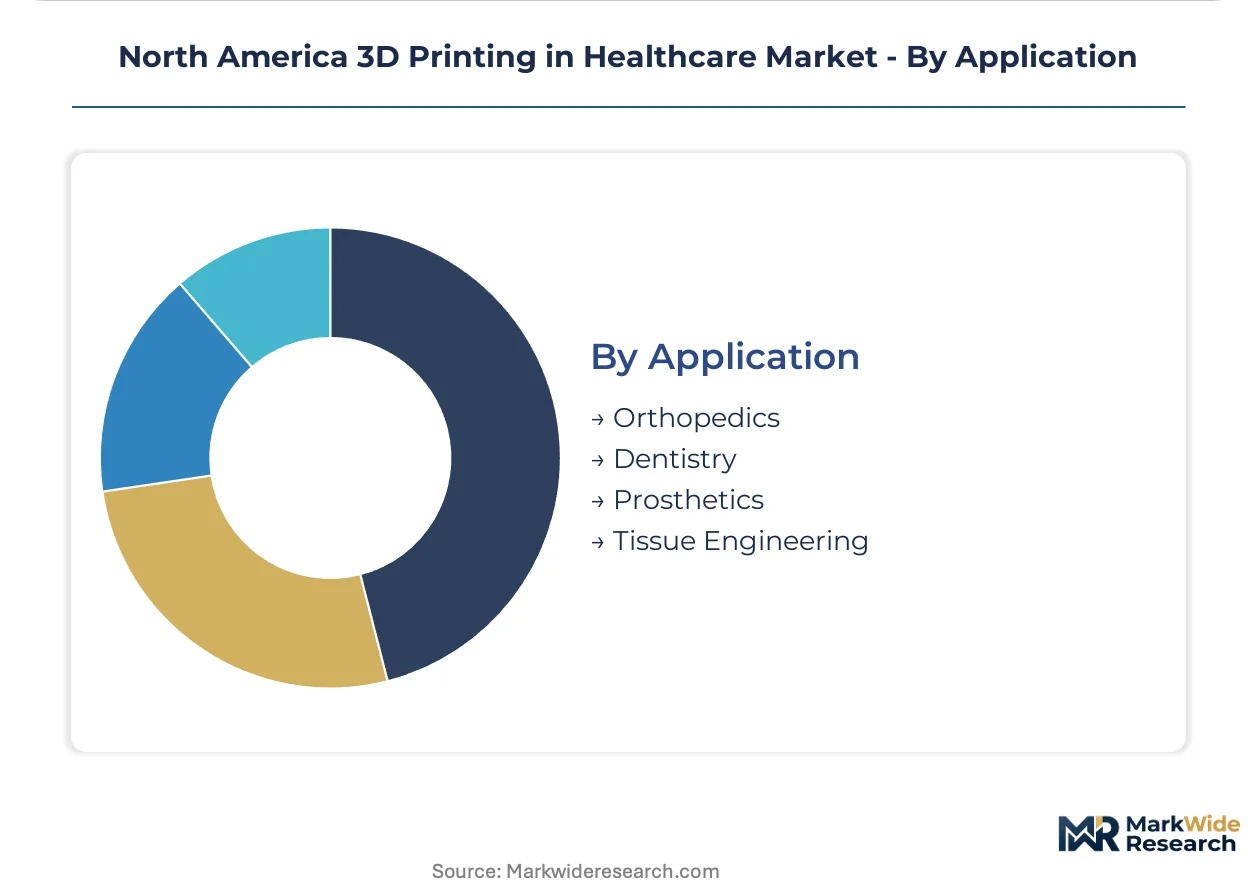
Application:
Maturity gradients separate established reimbursement pathways from frontier segments where regulatory and clinical validation remain incomplete.
- Orthopedics:Patient-specific implants for hip, knee, and spinal applications achieve established CMS reimbursement codes and documented revision rate reductions. Health Canada and FDA biocompatibility convergence under ISO 10993 simplifies cross-border commercialization for PEEK cranial plate submissions.
- Dentistry:Crown, bridge, and aligner production represents the most penetrated additive application with clear regulatory pathways and repeat purchase economics.
- Prosthetics:Limb socket and cosmetic cover fabrication serves veterans affairs hospitals and pediatric centers with individualized geometry requirements.
- Tissue Engineering:Vascular scaffolds and organoid matrices remain experimental with micro-stereolithography systems achieving 25-micrometer resolution for ocular drainage implants.
Dentistry maintains revenue concentration; tissue engineering shows the most aggressive R&D investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare additive manufacturing across North America varies sharply by jurisdiction, with United States hospitals embedding point-of-care fabrication while Canadian institutions favor centralized production models and Mexican facilities concentrate on export-oriented medical device assembly.
United States
Academic medical centers in Boston, Cleveland, and Houston operate dedicated hospital-based 3D printing labs producing surgical guides and anatomical models at point of care. FDA's Additive Manufacturing Working Group streamlines premarket submission pathways for polymer and metal implant producers, accelerating device clearance timelines. Texas and Ohio health systems increasingly source patient-specific implants through consignment arrangements rather than capital purchase.
Canada
Health Canada mandates biocompatibility testing aligned with ISO 10993 standards for patient-contacting components, creating cross-border regulatory convergence with FDA requirements. Canadian health systems favor centralized production partnerships over capital-intensive point-of-care fabrication, embedding additive manufacturing into supply chain workflows rather than clinical facilities. Ontario and Quebec manufacturing clusters concentrate on regulatory-cleared implant production for export markets.
Mexico
Medical device assembly operations in Baja California and Chihuahua leverage proximity to United States distribution channels for orthopedic implant components. Mexican regulators align with FDA technical considerations for additive manufactured devices, facilitating cross-border commercialization for contract manufacturers. Guadalajara and Mexico City metro areas concentrate dental prosthetic fabrication serving North American dental laboratory networks.
North America 3D Printing in Healthcare Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with industrial-scale metal printing capacity holders and polymer system specialists occupying distinct competitive positions. The market structure stratifies between organizations cultivating in-house additive manufacturing expertise and those dependent on external service bureaus. Three archetypes dominate: surgical planning software integrators, industrial-scale metal printing capacity operators, and polymer system specialists targeting dental and anatomical modeling. Competitive moves concentrate on strategic partnerships embedding workflow platforms into hospital procurement committees and technology licensing agreements spanning regulatory-cleared material qualification protocols.
Among United States-based fabricators, 3D Systems, Inc. and Carbon, Inc. occupy positions within the polymer specialization tier, while Materialise represents the surgical planning software integration archetype across the continent. These companies exemplify divergent strategic postures: hardware-centric platform development versus workflow software dominance. Belgian-originated Materialise anchors patient-specific workflow platforms through decades of surgical planning integration, while Carbon, Inc. exemplifies the venture-backed digital light processing specialist segment.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| Stratasys Ltd. |
| Carbon, Inc. |
| ENVISIONTEC, Inc. |
| Materialise |
| EOS GmbH |
| GE Healthcare |
| Organovo Holdings, Inc. |
| regenHU |
| Others |
Pricing and Supply Chain Analysis
Industrial-scale metal printing capacity utilization in the United States anchors price floors for titanium orthopedic implants, concentrating supply leverage among operators with FDA-cleared material qualification protocols while compressing margins for mid-cap polymer system specialists lacking consignment arrangement access.
Pricing Analysis
Consignment arrangements now dominate procurement for patient-specific implants across Texas and Ohio health systems, displacing capital purchase models. Price differentiation hinges on FDA clearance tier and sterilization logistics bundling, with premium tiers capturing surgical revision rate guarantees. Cost compression in polymer anatomical modeling intensifies as FDM system commoditization accelerates. Academic medical centers exhibit lowest price sensitivity due to bundled total cost-of-ownership evaluations, while outpatient clinics face acute budget constraints driving service bureau dependency.
Supply Chain Analysis
Titanium powder supply concentration among limited United States and European suppliers creates single-source vulnerability for orthopedic metal printing feedstock. The North American ecosystem draws from German and Belgian surgical planning software providers, Canadian regulatory-cleared implant producers, and Mexican contract assembly operations. Logistics chokepoints in cross-border sterilization certification impose inventory carrying cost penalties. Distribution runs through hospital value analysis committees and GPO contracts rather than individual surgeon preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-based 3D printing labs are shifting from capital equipment purchases to workflow platform subscriptions, creating platform-economics inflection where surgical planning software interoperability determines vendor lock-in depth across Boston, Cleveland, and Houston academic medical centers.
For Market Incumbents: Secure FDA Additive Manufacturing Working Group premarket submission pathways for titanium lattice implants before polymer system specialists achieve metal deposition capability parity. Deepen backward integration into titanium powder supply through long-term offtake arrangements with German and United States feedstock producers. Anchor hospital procurement influence through consignment model expansion in Texas and Ohio health systems. For New Entrants and Emerging Players: Differentiate on bioprinted tissue matrix R&D concentration ahead of commercial margin formation, targeting California and Minnesota research institution partnerships. Exploit Canadian regulatory convergence with FDA biocompatibility standards for cross-border PEEK cranial plate submissions. Pursue AI-generated print parameter software-as-medical-device classifications as first-mover positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors surgical planning software integrators with decades of hospital workflow embedding over hardware-centric platform developers facing commoditization pressure. Long-term viability concentrates in patient-specific orthopedic implant producers with established CMS reimbursement codes and documented revision rate reductions. Monitor FDA Technical Considerations guidance evolution for algorithmic quality control classification as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Embedding consignment models into Texas and Ohio value analysis committees displaces capital purchase preference. |
| FDA Submission Pathway | Streamlined Additive Manufacturing Working Group clearance accelerates titanium implant market access timelines. |
| Software Companion Development | AI-generated print parameter platforms trigger software-as-medical-device regulatory reassessment opening first-mover positioning. |
| Backward Integration | Captive titanium powder supply secures input cost stability against limited supplier base concentration risk. |
| Reimbursement Strategy | CMS code establishment for patient-specific orthopedic implants locks in revision rate reduction value capture. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and FDA regulatory affairs specialists provided ongoing calibration across primary interview rounds, with secondary validation drawing from FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and ISO 10993 biocompatibility test registries. Bottom-up implant volume modeling and top-down healthcare additive manufacturing expenditure estimates were triangulated against cross-referenced sources.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeling spanning product type, technology platform, end user archetype, and application maturity tier. CAGRs were derived from installed base expansion trajectories and procedure volume elasticity to patient-specific adoption rates, incorporating titanium powder pricing volatility and regulatory clearance timeline distributions as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA Additive Manufacturing Working Group streamlining, stable titanium feedstock supply, and continued CMS reimbursement code coverage would require recalibration. Forecasts reflect documented assumptions regarding hospital capital expenditure cycles and biomedical engineering talent pipeline expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Struts Implants Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Micro Syringes Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Neurovascular Devices Market