
 Healthcare Claims Management Software Market | 2026-2036
Healthcare Claims Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Claims Management Software Market Outlook
The healthcare claims management software landscape is restructuring around a sharp split between premium enterprise suites with deep EHR integration and commodity cloud tools competing on price. Waystar leverages its dominance in revenue cycle analytics to anchor relationships with large hospital networks. athenahealth competes through vertical control over billing workflows and practice management. Optum sustains its position by extending payer-provider data linkages across integrated delivery systems.
Healthcare claims management software encompasses platforms that automate the submission, adjudication, and payment of medical claims through rule engines, electronic data interchange protocols, and real-time eligibility verification. These systems process ANSI X12 837 claim formats and interface with clearinghouses to reduce denial rates and accelerate reimbursement cycles. Cloud-based solutions are capturing the fastest expansion as hospitals migrate from legacy on-premise installations to multi-tenant architectures with API-driven interoperability. By end user, insurers and third-party administrators represent concentrated margin pools due to their volume scale and complexity of cross-payer coordination requirements.
In the United States, HIPAA and the CMS Interoperability and Prior Authorization Final Rule shape product standards by mandating standardized APIs and real-time patient access to claims data. The FDA does not directly regulate claims software, but ONC certification requirements for health IT create de facto market access barriers for uncertified platforms. Stakeholders must monitor how state-level Medicaid management information system modernization programs reshape procurement criteria and vendor eligibility.
Market Dynamics
Hospital consolidation into mega-systems is forcing vendors to rebuild platforms for multi-entity revenue cycle orchestration rather than single-facility deployment.
Growth Catalysts
- CMS Interoperability Mandates:Real-time API requirements under the Prior Authorization Final Rule are compelling payers to modernize legacy adjudication stacks.
- Cloud Migration:Multi-tenant SaaS architectures are displacing on-premise installations as hospitals seek elastic capacity for seasonal claim volume spikes.
- United States:Large health system consolidation into integrated delivery networks creates concentrated procurement power demanding end-to-end platform unification.
Market Restraints
- Clearinghouse Concentration:Three national clearinghouses process over 80% of electronic claims, creating single-point-of-failure risk for downstream software vendors.
- HIPAA Compliance Burden:State-by-state breach notification variations impose redundant audit and legal costs on multi-state deployments.
- Legacy EHR Lock-in:Proprietary data formats from dominant hospital information systems raise switching costs and delay interoperability timelines.
Strategic Opportunities
- Medicaid MMIS Modernization:State-level management information system overhauls create procurement windows for modular claims processing components.
- AI-Powered Denial Prediction:Machine learning models trained on historical denial patterns are converging with real-time eligibility verification to preempt claim rejections.
- Self-Insured Employers:Large employers building captive health plans represent an underpenetrated channel bypassing traditional payer-vendor relationships.
Industry Challenges
- ANSI X12 Version Migration:Upgrading from 5010 to 6020 transaction standards requires multi-year coordination across thousands of trading partners.
- Revenue Cycle Talent Scarcity:Shortage of certified medical coders and claims adjudication specialists constrains customer implementation velocity.
- Prior Authorization Complexity:Proliferation of payer-specific clinical documentation requirements fragments workflow automation efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Claims Management Software Market |
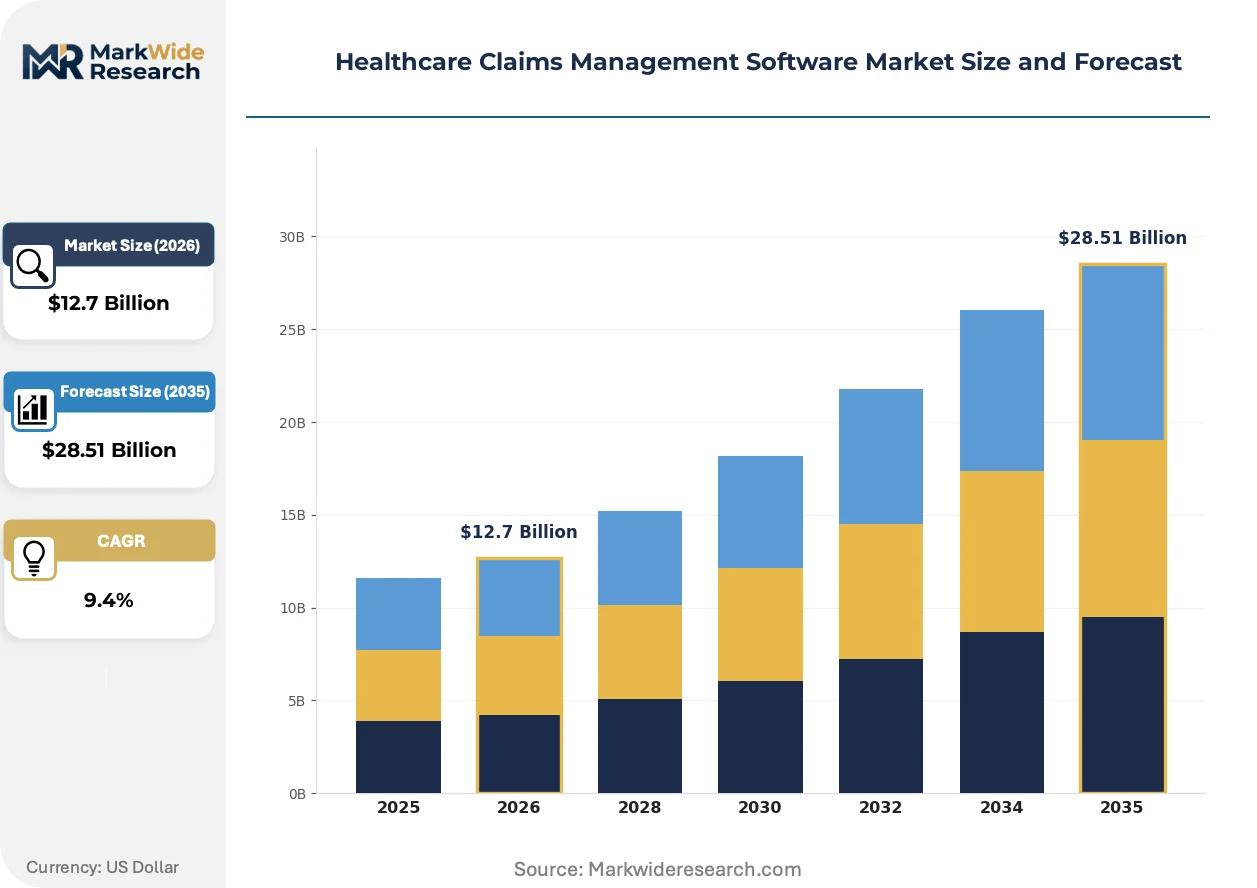
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise Solutions, Cloud-Based Solutions, Hybrid Solutions, Software as a Service End User: Hospitals, Clinics, Insurers, Third-Party Administrators Deployment Model: Public Cloud, Private Cloud, Dedicated Server, Multi-Tenant Architecture Integration Level: APIs, EHR Integration, Billing System Integration, Health Information Exchange |
| Companies Covered | CareCloud, Experian Health, Waystar, Ensemble Health Partners, FinThrive, athenahealth, Optum, AdvancedMD, NextGen Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Claims Management Software Market Strategic Shifts
Artificial intelligence and regulatory mandates are compressing the gap between claim submission and payment, eliminating batch-processing delays that defined legacy revenue cycles.
Real-time adjudication engines are unifying eligibility verification, prior authorization, and payment estimation into single-transaction workflows. Large hospital networks in the United States are deploying these systems across outpatient and emergency departments to reduce point-of-service collection friction. This unification is compressing revenue cycle timelines from weeks to minutes while shifting vendor competition toward API response latency benchmarks.
The CMS Interoperability and Prior Authorization Final Rule mandates standardized FHIR-based APIs for patient access and provider data exchange by 2026. Payers must expose claims data and decision rationale through these interfaces, exposing historical opacity in denial justifications. Medicare Advantage plans and Medicaid managed care organizations face the steepest compliance curves, driving consolidation of vendor relationships to reduce integration fragmentation.
Subscription-based pricing for claims management modules is displacing perpetual license models in mid-market hospital segments. Chief financial officers now demand consumption-aligned contracts tied to claim volume or denial reduction outcomes rather than fixed fees. This shift is most pronounced among community hospitals and critical access facilities in the United States seeking to reduce upfront capital commitment during margin compression.
Healthcare Claims Management Software Market Segmentation
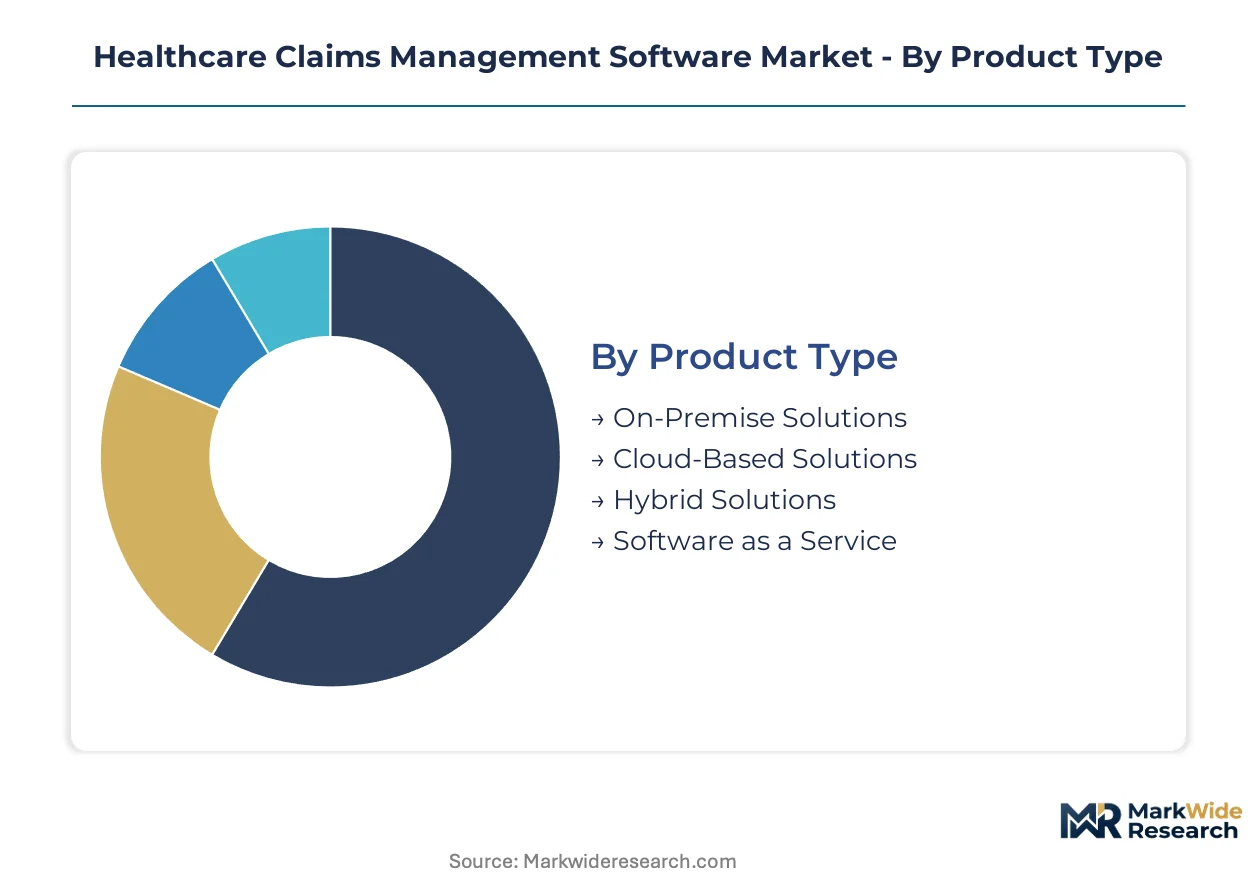
Segmentation in healthcare claims management software reveals how vendor strategies diverge across infrastructure maturity and buyer sophistication. Procurement patterns differ sharply between legacy-dependent hospital systems and cloud-native payers seeking modular interoperability.
Product Type:
Customization dominates at the enterprise tier while standardization accelerates in mid-market segments, creating divergent R&D investment patterns across vendors.
- On-Premise Solutions:Perpetual-license platforms deployed within hospital data centers with dedicated hardware stacks. Demand concentrates among integrated delivery networks in the United States with sunk capital in Cerner and Epic installations, constrained by multi-year amortization cycles that delay cloud migration decisions.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with elastic compute provisioning for seasonal claim volume spikes. Large health systems in Texas and California are consolidating onto these platforms to unify revenue cycles across acquired community hospitals, driven by CFO mandates to shift capital expenditure to operational expenditure.
- Hybrid Solutions:Split architectures retaining sensitive adjudication logic on-premise while offloading analytics to cloud instances.
- Software as a Service:Subscription models with API-first delivery and continuous feature deployment.
Leading the category by volume: Cloud-Based Solutions. Expanding most quickly: Software as a Service.
End User:
Margin capture varies dramatically across buyer types, with payers extracting pricing power through volume guarantees while providers struggle with implementation complexity.
- Hospitals:Large academic medical centers and community hospital networks requiring end-to-end revenue cycle orchestration. Procurement in the United States is consolidating toward mega-system contracts spanning 50+ facilities, forcing vendors to rebuild platforms for multi-entity deployment rather than single-facility installation.
- Insurers:Commercial payers and Medicare Advantage plans with complex cross-payer coordination requirements. These buyers command concentrated margin pools through adjudication volume scale and drive vendor roadmaps toward real-time API compliance under CMS mandates.
- Clinics:Independent physician practices and ambulatory surgery centers with lighter IT infrastructure.
- Third-Party Administrators:Benefits administrators serving self-insured employers with specialized claim routing needs.
Commanding the highest contract values: Insurers. Gaining share fastest: Third-Party Administrators.
Deployment Model:
Security classification and latency requirements segment this category, with public cloud adoption gated by state-level Medicaid data residency rules.
- Public Cloud:Shared infrastructure with FedRAMP or HITRUST certification for healthcare workloads. State Medicaid agencies in New York and Illinois are piloting these deployments for non-PHI analytics layers, constrained by federal matching fund requirements for data sovereignty.
- Private Cloud:Single-tenant environments with dedicated virtual infrastructure. Large Blue Cross Blue Shield plans in the United States favor this model for core adjudication engines, balancing elasticity needs against legacy security audit frameworks.
- Dedicated Server:Bare-metal provisioning for maximum workload isolation.
- Multi-Tenant Architecture:Shared codebases with tenant-specific data partitioning and configuration isolation.
Dominating current procurement: Private Cloud. Climbing the fastest: Multi-Tenant Architecture.
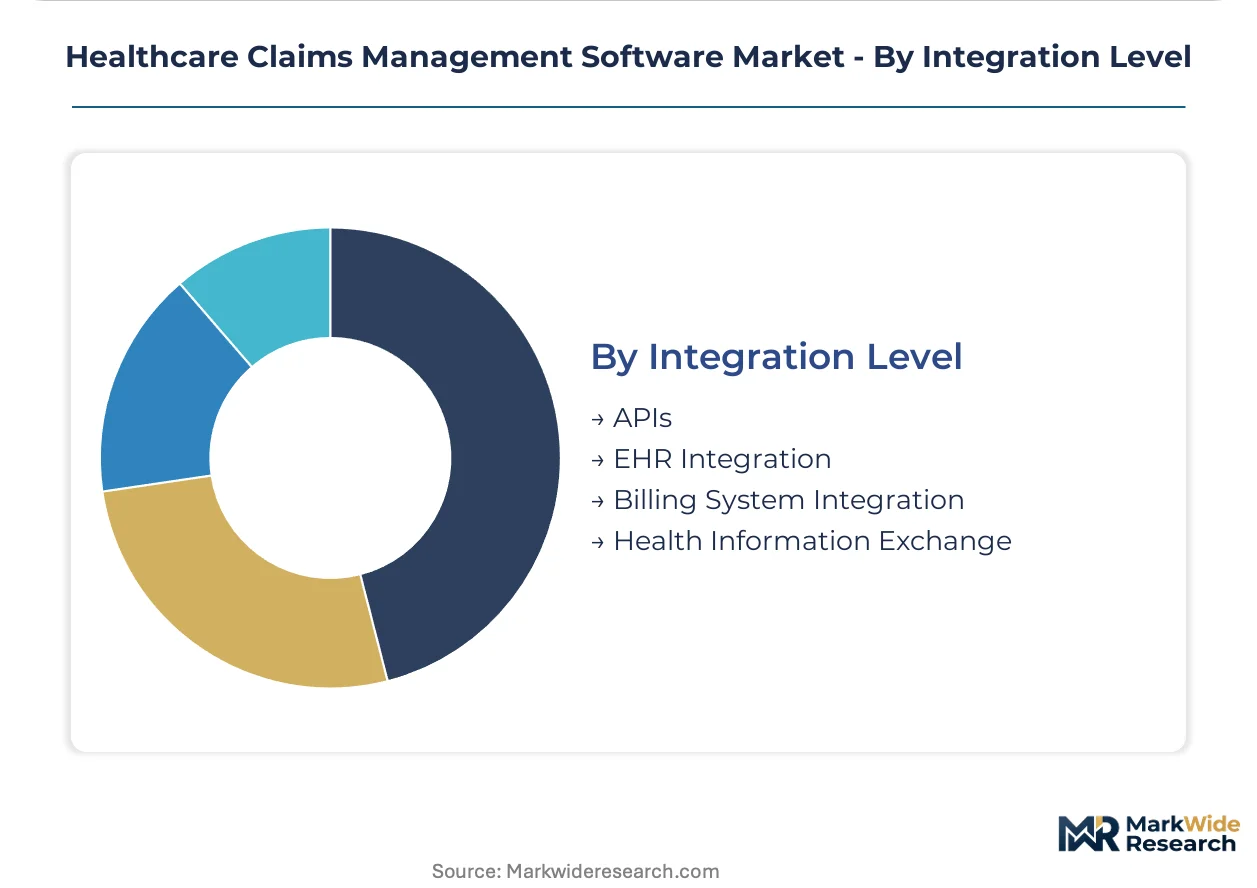
Integration Level:
Interoperability depth determines switching costs, with EHR-native integration creating the stickiest vendor relationships in hospital segments.
- APIs:FHIR-based and REST interfaces enabling real-time data exchange between disparate systems. Payers under the CMS Interoperability and Prior Authorization Final Rule must expose these endpoints by 2026, forcing wholesale stack modernization at Medicare Advantage organizations.
- EHR Integration:Deep workflow embedding within Epic, Cerner, and MEDITECH environments. Hospital CIOs in the United States prioritize these connections to eliminate dual data entry, though proprietary formats from dominant EHR vendors raise switching costs and delay third-party interoperability timelines.
- Billing System Integration:Point-to-point connections with practice management and patient accounting platforms.
- Health Information Exchange:Query-based and push-based data sharing across regional networks.
Generating the longest sales cycles: EHR Integration. Showing steepest adoption curve: APIs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nashville anchors the highest concentration of healthcare claims management software headquarters and revenue cycle operations in the United States, with the metropolitan area hosting multiple vendor development centers and payer technology subsidiaries.
United States
Hospital consolidation into mega-systems across Texas and California drives demand for multi-entity revenue cycle orchestration platforms. HIPAA and the CMS Interoperability and Prior Authorization Final Rule mandate standardized FHIR-based APIs by 2026, forcing payer stack modernization. The Nashville-Dallas corridor concentrates vendor engineering and implementation resources serving national health plan networks.
Germany
Statutory health insurance funds (Gesetzliche Krankenversicherung) require automated claims processing to manage 70 million insured lives under DRG reimbursement systems. The GDPR and Germany's national healthcare interoperability framework impose strict data residency requirements on cloud deployments. Berlin hosts emerging InsurTech clusters developing API-first claims platforms for regional sickness funds.
United Kingdom
NHS England's Federated Data Platform procurement creates demand for claims analytics integrating primary and secondary care reimbursement. NHS Digital interoperability standards and UK GDPR compliance shape vendor certification requirements. London's health technology corridor concentrates software development for NHS trusts and private medical insurers.
India
Expanding health insurance penetration under Ayushman Bharat drives claims automation for government-sponsored schemes covering 500 million beneficiaries. The Digital Information Security in Healthcare Act (DISHA) and IRDAI data protection guidelines regulate health data exchange. Bangalore and Hyderabad host development centers building SaaS claims platforms for domestic insurers and export markets.
Canada
Provincial health authority modernization programs in Ontario and British Columbia replace legacy Medicaid Management Information System infrastructure with modular claims components. Health Canada and provincial privacy commissioners enforce PHIPA and PIPEDA compliance on cross-border data flows. Toronto's health technology cluster concentrates vendors serving provincial single-payer administration systems.
Healthcare Claims Management Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across EHR integration depth, with the market consolidating around three structural tiers. Enterprise suites with native Epic and Cerner connectivity command pricing power from large integrated delivery networks. Mid-market SaaS vendors compete on implementation velocity for community hospitals. API-first specialists capture emerging opportunities in real-time adjudication and prior authorization automation. Competitive dynamics center on strategic acquisitions to fill interoperability gaps and cloud migration partnerships to accelerate legacy displacement.
Within the enterprise tier, Waystar and athenahealth exemplify divergent platform strategies—one anchored in revenue cycle analytics scale, the other in vertical workflow control. Optum occupies a distinct position extending payer-provider data linkages across integrated delivery systems. These three structures illustrate how vendor archetypes map to buyer consolidation patterns: analytics-scale platforms, vertical workflow specialists, and payer-affiliated integrators each capture different segments of hospital procurement concentration.
| Leading Market Players |
|---|
| CareCloud |
| Experian Health |
| Waystar |
| Ensemble Health Partners |
| FinThrive |
| athenahealth |
| Optum |
| AdvancedMD |
| NextGen Healthcare |
| Others |
Value Chain & Pricing Dynamics
Certified medical coder labor costs cascade through claims management software pricing tiers, with revenue cycle specialist scarcity in the United States inflating implementation fees for enterprise deployments while compressing margins on mid-market SaaS subscriptions.
Pricing Analysis
Outcome-based contracts anchored to denial rate reduction percentages dominate hospital procurement, displacing perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels separates EHR-native enterprise suites from API-first mid-market tools and commodity clearinghouse connectors. Pricing pressure stems from CFO mandates to shift capital expenditure to operational expenditure, intensifying consumption-aligned contract negotiations. Community hospitals and critical access facilities exhibit highest price sensitivity, while large integrated delivery networks prioritize interoperability depth over unit cost.
Supply Chain Analysis
Direct-to-hospital sales channels handle mega-system procurement, while partner networks serve independent clinics and third-party administrators. Engineering talent concentrates in the United States, India, and Germany, with development centers in Nashville, Bangalore, and Berlin feeding platform innovation. Cloud infrastructure draws from hyperscale providers, while specialized clearinghouse connectivity rests on three national networks processing electronic claims. Single-source vulnerability in clearinghouse concentration creates downstream failure risk for software vendors. Distribution runs through value-added resellers and direct implementation teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
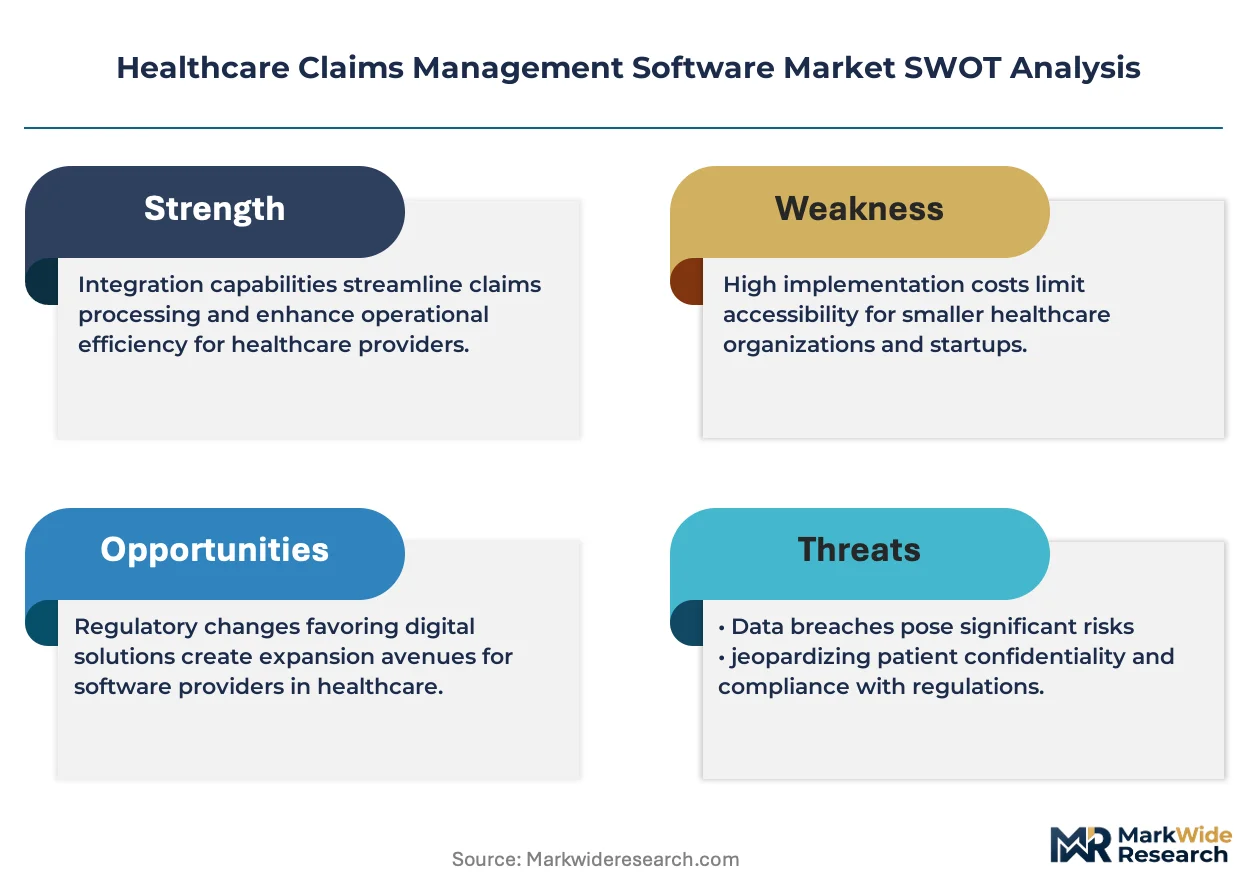
The healthcare claims management software market operates as a cost-of-compliance arena where HIPAA and CMS Interoperability mandates erect formidable barriers to entry, rewarding vendors with ONC certification and established payer-provider data linkages.
For Market Incumbents: Acquire FHIR-based API specialist firms to close interoperability gaps before the CMS Prior Authorization Final Rule deadline. Consolidate vendor relationships with Medicare Advantage plans facing steepest compliance curves. Cloud migration partnerships with community hospital networks defend against mid-market SaaS erosion. Certification investment in state Medicaid MMIS modernization programs locks out unqualified competitors. For New Entrants and Emerging Players: Self-insured employers building captive health plans represent the most penetrable buyer archetype, bypassing entrenched payer-vendor relationships. Prior authorization automation for specialty pharmaceuticals offers white-space targeting with fragmented clinical documentation requirements. Geographic expansion into Canadian provincial health authority modernization programs exploits procurement windows in Ontario and British Columbia. API-first positioning with consumption-based pricing lowers customer acquisition friction. For Investors and Strategic Acquirers: State Medicaid agency RFP releases for MMIS modular components signal inflection points for vendor consolidation opportunities. Long-term viability favors platforms with native Epic and Cerner integration depth, multi-tenant SaaS architectures, and established clearinghouse relationships. Acquisition target archetype: mid-market revenue cycle analytics firms with denial prediction algorithms and hospital network referenceability. Monitor ANSI X12 6020 migration readiness as technical debt differentiator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native EHR connectivity with Epic and Cerner reduces implementation friction for large hospital networks. |
| Acquisition of Specialist Firm | API-first prior authorization vendors fill interoperability gaps under CMS mandate deadlines. |
| Strategic Partnership | Clearinghouse alliances secure claim routing capacity for seasonal volume spikes. |
| Product Launch | Real-time adjudication engines compress revenue cycle timelines from weeks to minutes. |
| Geographic Expansion | Canadian provincial MMIS modernization opens procurement windows in Ontario and British Columbia. |
Study Parameters
SEC filings, CMS Medicare cost reports, and hospital procurement databases formed the secondary backbone, cross-referenced with primary interviews with revenue cycle executives, health system CIOs, payer technology officers, and clearinghouse operations directors. Bottom-up triangulation across claim volume data and top-down validation through vendor revenue disclosures anchored market sizing. Primary fieldwork with GPO contracts managers and state Medicaid IT directors supplied implementation velocity benchmarks.
Historical trendline analysis of cloud migration patterns and EHR consolidation trajectories informed projection frameworks across the analysis window. Segmentation modeling captured deployment model, organization size, integration complexity, and regional adoption pattern dimensions. CAGRs derived from weighted average of vendor revenue growth rates and customer expansion metrics. Forecast inputs incorporated ANSI X12 version migration timelines and state Medicaid MMIS procurement schedules.
Revisions become necessary when CMS interoperability rule enforcement delays, clearinghouse consolidation events, or hospital merger waves materialize outside modeled assumptions. Practitioners should monitor state Medicaid RFP releases and Medicare Advantage plan vendor consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Patient Access Solutions Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market