
 Global Back-End Revenue Cycle Management Market | 2026-2036
Global Back-End Revenue Cycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Back-End Revenue Cycle Management Market Foresight
Hospital buyer concentration is collapsing as physician practices and ambulatory surgical centers accelerate back-end RCM outsourcing. Optum, Inc. leverages its payer-provider integration to control denial management workflows at scale. Epic Systems Corporation anchors hospital-centric revenue cycle operations through embedded EHR billing modules. McKesson Corporation competes across the hybrid delivery model with pharmacy-revenue synergies.
Back-end revenue cycle management encompasses the post-claim financial processes—including payment posting, denial management, and collections—that reconcile provider services with payer remittances, typically operating through HL7 FHIR-compliant data exchanges and automated clearinghouse integrations. Cloud-based solutions lead technology deployment due to lower capital burden and faster EHR interoperability, while AI-enabled platforms represent the fastest-expanding segment as machine learning reduces denial rates and accelerates cash conversion. Claims management remains the most mature service type with compressed margins, whereas denial management captures expanding margin pools from complex payer contract variability.
US HIPAA transaction standards and the CMS interoperability mandates shape product requirements for electronic remittance and patient access APIs, while India's CDSCO digital health guidelines and Germany's BfArM medical device software classifications create divergent compliance thresholds for platform vendors. The EU AI Act's risk-tiering framework will constrain automated decision-making in payment algorithms. Stakeholders must monitor how jurisdictional fragmentation in health data governance reshapes vendor certification roadmaps and client retention economics.
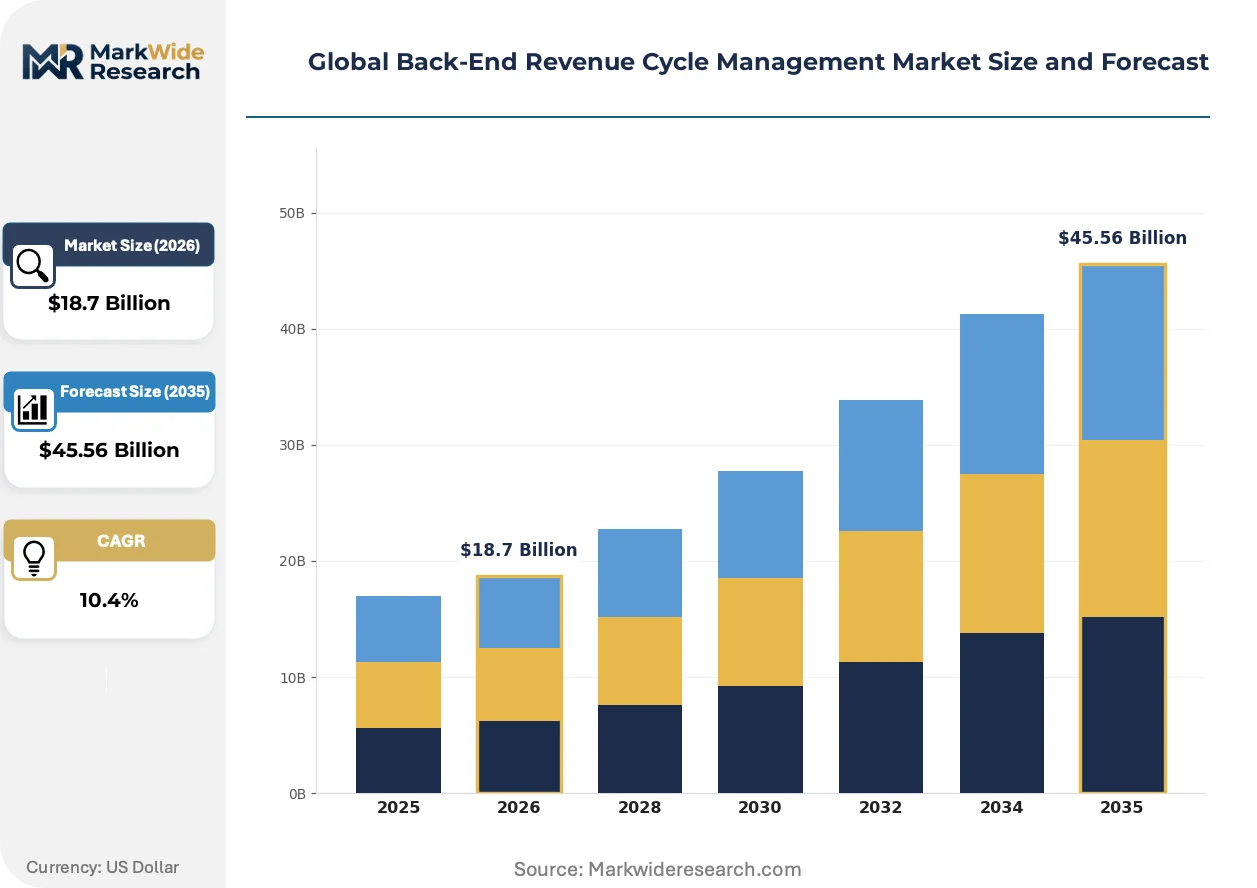
Market Dynamics
Cloud-native platforms are compressing deployment cycles from months to weeks while HIPAA transaction standards force real-time interoperability investments across US health systems. This dual pressure is redrawing competitive boundaries between embedded EHR billing modules and standalone denial management specialists.
Growth Catalysts
- CMS Interoperability Mandates:The US Centers for Medicare & Medicaid Services requires electronic remittance and patient access APIs, compelling providers to replace legacy batch-processing systems with real-time data exchanges.
- Machine Learning in Denial Prediction:Natural language processing models trained on historical payer responses now flag claim defects pre-submission, reducing administrative rework for physician practices.
- Germany's BfArM Software Classification:Medical device revenue cycle platforms face streamlined certification pathways, accelerating vendor entry into hospital procurement pipelines.
Market Restraints
- Legacy System Technical Debt:HL7 v2 interfaces in decades-old hospital information systems resist FHIR-native integration, forcing expensive middleware layers.
- Cloud Concentration Risk:AWS, Azure, and Google Cloud dominate health data hosting, creating single-point-of-failure exposure for multi-tenant RCM platforms.
- EU AI Act Risk Tiering:Automated payment algorithms fall under high-risk classification, requiring human-in-the-loop overrides that dilute automation ROI.
Strategic Opportunities
- India's CDSCO Digital Health Guidelines:Emerging compliance frameworks for software-as-medical-device create first-mover advantage for cloud-native vendors establishing local data residency.
- Value-Based Reimbursement Convergence:Bundled payment models demand new analytics layers that reconcile clinical outcomes with financial performance, opening greenfield product categories.
- Direct-to-Employer Contracting:Self-insured employers bypass traditional payers, requiring RCM platforms to support alternative payment methodologies outside standard clearinghouse rails.
Industry Challenges
- FHIR Implementation Expertise Scarcity:Health systems lack sufficient informaticists to configure standardized APIs, stalling interoperability timelines despite regulatory deadlines.
- Multi-Payer Contract Variability:Each commercial insurer maintains distinct prior authorization rules and appeal windows, preventing scalable denial management automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Back-End Revenue Cycle Management Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $45.56 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing Services, Claims Management, Payment Posting, Denial Management Technology: Cloud-Based Solutions, On-Premise Solutions, RPA, AI-Enabled Platforms End User: Hospitals, Physician Practices, Ambulatory Surgical Centers, Health Systems Delivery Model: Outsourced, In-House, Hybrid, Third-Party |
| Companies Covered | Optum, Inc., Epic Systems Corporation, Oracle, McKesson Corporation, Solventum, athenahealth, Inc., R1 RCM, Inc., Conifer Health Solutions, LLC, Cognizant Technology Solutions Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Back-End Revenue Cycle Management Market Shifts & Advancements
Artificial intelligence is migrating from retrospective reporting to real-time claim editing, while regulatory fragmentation forces vendors to maintain parallel compliance architectures across jurisdictions.
Embedded analytics engines are miniaturizing denial management workflows into point-of-care decision support. Ambulatory surgical centers deploy these modules at patient check-in to catch eligibility gaps before service delivery. The technology is miniaturizing traditional back-office functions into front-desk operations, collapsing the historical separation between clinical and financial workflows.
The EU AI Act's risk-tiering framework constrains automated decision-making in payment algorithms. Vendors must now engineer human override mechanisms and audit trails into machine learning models. European hospital buyers are prioritizing explainable AI certifications over raw accuracy metrics in procurement evaluations.
Physician practice buyers are consolidating vendor relationships around single-platform solutions that span scheduling, documentation, and revenue cycle functions. Standalone RCM specialists face displacement unless they embed deeply into EHR ecosystems or demonstrate superior denial recovery rates. This consolidation is most visible in US metropolitan markets where private equity-backed practice rollouts demand standardized financial operations across dozens of sites.
Global Back-End Revenue Cycle Management Market Segmentation
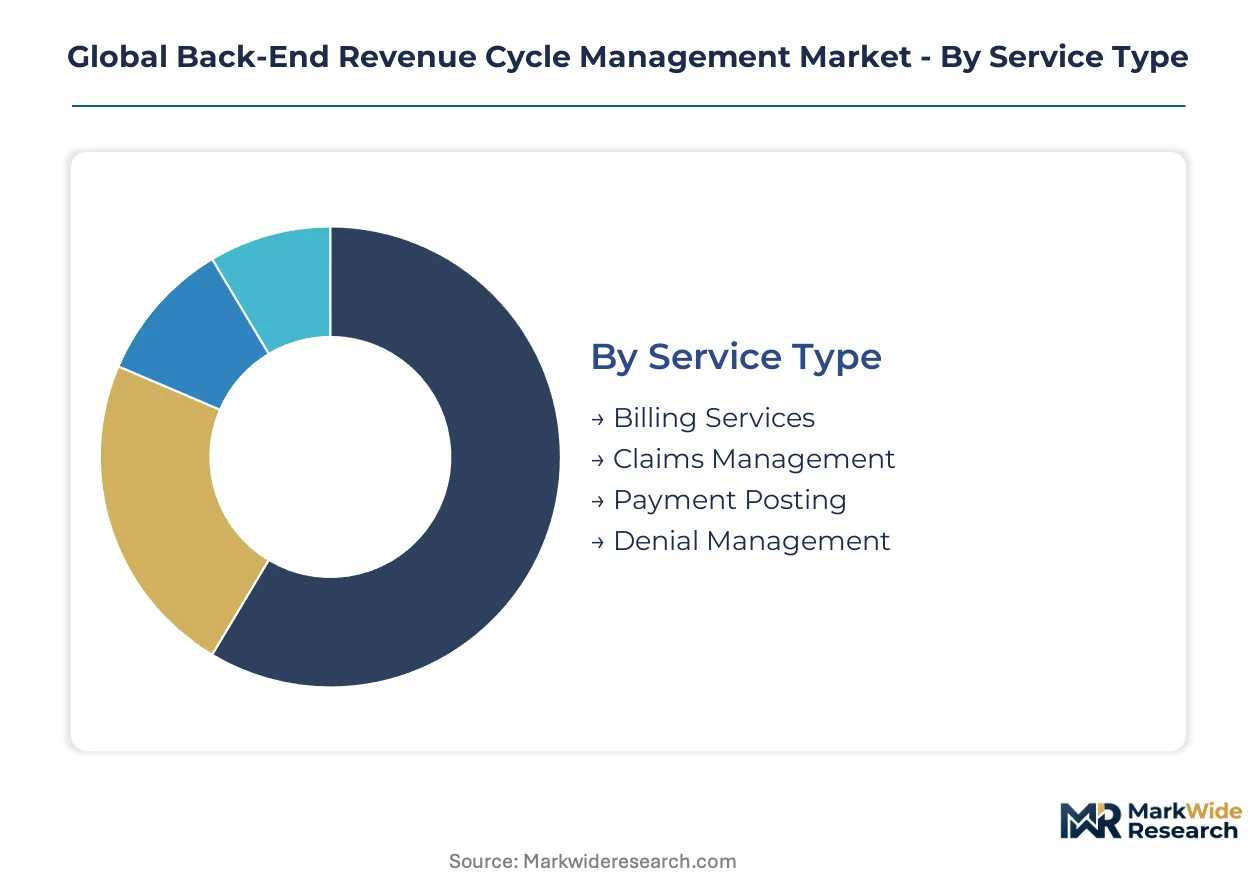
Back-end revenue cycle management segments reflect divergent margin structures across service maturity, technology deployment costs, and buyer consolidation patterns. Understanding where value concentrates within each dimension enables vendors to prioritize capability investments and channel strategies.
Service Type:
Denial management commands expanding margin pools as payer contract complexity multiplies administrative rework, while claims management confronts commoditization from automated clearinghouse standardization.
- Denial Management:Appeals workflows and root-cause analytics address the costliest friction point in revenue cycle operations. Physician practices in US metropolitan markets deploy pre-submission NLP models to intercept eligibility gaps and coding errors before payer rejection. Complex prior authorization variability across commercial insurers sustains premium pricing for specialized vendors.
- Claims Management:Electronic submission and scrubbing functions operate through mature clearinghouse integrations with compressed differentiation. Health systems in Germany leverage BfArM-certified platforms to streamline hospital procurement pipelines, though margin pressure intensifies as real-time adjudication becomes table stakes.
- Billing Services:Charge capture and code optimization services anchor outsourced relationships for mid-size physician groups lacking internal certified coders.
- Payment Posting:Automated remittance reconciliation reduces manual matching of ERAs to patient accounts, with demand concentrating among ambulatory surgical centers managing high-volume, low-dollar transactions.
Claims management holds installed capacity. Denial management is rotating up the share rankings.
Technology:
Capital deployment intensity separates cloud-native architectures from legacy infrastructure, with AI platforms capturing disproportionate R&D investment despite smaller current revenue bases.
- AI-Enabled Platforms:Machine learning models trained on historical payer responses now predict denial probability at the point of claim generation. US health systems facing CMS interoperability mandates prioritize these capabilities to reduce administrative rework and accelerate cash conversion cycles.
- Cloud-Based Solutions:Multi-tenant architectures eliminate on-premise hardware burdens and compress deployment timelines from months to weeks. India's CDSCO digital health guidelines create compliance pathways for vendors establishing local data residency, opening first-mover advantages in emerging markets.
- RPA:Robotic process automation handles repetitive eligibility verification and payment posting tasks with deterministic rule sets.
- On-Premise Solutions:Legacy installations persist in hospital systems with stringent data sovereignty requirements or technical debt in HL7 v2 interfaces.
Cloud-based solutions anchor current deployment volumes. AI-enabled platforms are climbing the fastest.
End User:
Buyer scale determines procurement sophistication, with health systems and hospitals demanding enterprise integration while smaller sites prioritize speed-to-implement.
- Physician Practices:Consolidation under private equity rollouts drives standardization demands across dozens of sites. These buyers increasingly favor single-platform solutions spanning scheduling, documentation, and revenue cycle functions, pressuring standalone RCM specialists to embed deeply into EHR ecosystems.
- Hospitals:Epic Systems Corporation anchors hospital-centric operations through embedded EHR billing modules, creating high switching costs for competing standalone offerings. US HIPAA transaction standards and CMS interoperability mandates shape product requirements for electronic remittance and patient access APIs.
- Ambulatory Surgical Centers:High-volume, specialized service profiles require rapid eligibility verification and point-of-care financial clearance.
- Health Systems:Multi-facety networks pursue centralized revenue cycle operations with standardized analytics across diverse care settings.
Hospitals retain the deepest incumbent relationships. Physician practices are gaining procurement influence fastest.
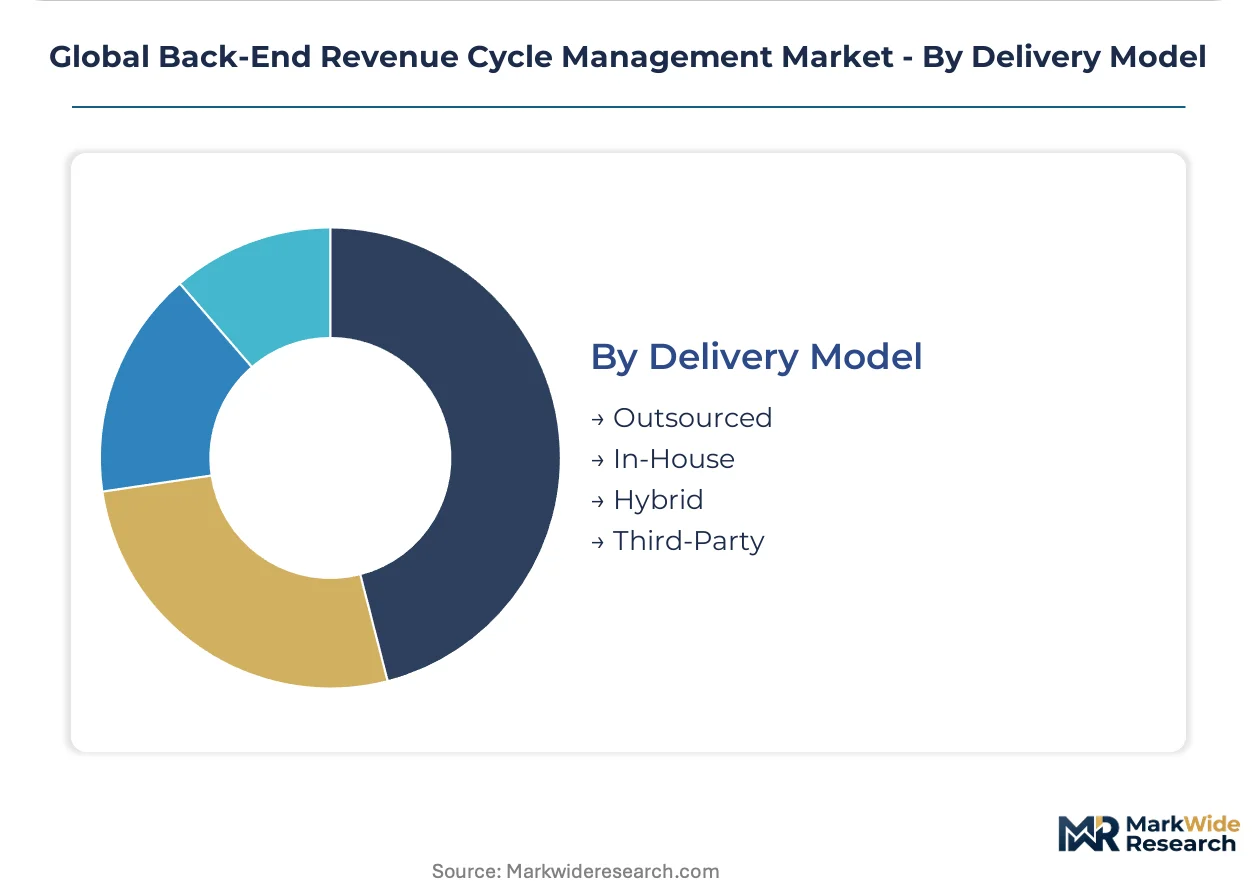
Delivery Model:
Control preferences and internal capability depth segment buyers across outsourcing appetite, with hybrid models capturing ambivalent organizations.
- Outsourced:Third-party specialists assume full responsibility for denial management and collections, appealing to physician practices and ambulatory surgical centers lacking scale for internal operations. Optum, Inc. leverages payer-provider integration to control workflows at scale in this segment.
- Hybrid:Organizations retain strategic functions in-house while outsourcing transactional processing. McKesson Corporation competes across this model with pharmacy-revenue synergies that span clinical and financial operations.
- In-House:Large health systems with dedicated revenue cycle teams maintain captive capabilities for competitive differentiation.
- Third-Party:Distinct from pure outsourcing, this model involves technology licensing with implementation support rather than full business process delegation.
Outsourced delivery holds relationship density. Hybrid arrangements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cloud-native vendors export real-time denial management platforms to US physician practices facing CMS interoperability deadlines. German BfArM-certified systems flow into hospital procurement pipelines across Central Europe. This trade corridor pattern reflects how regulatory certification in one jurisdiction creates exportable competitive advantage.
United States
Health systems accelerate denial management automation as value-based reimbursement models expand. HIPAA transaction standards and CMS mandates for electronic remittance APIs force replacement of legacy batch-processing systems. The Dallas-Fort Worth metroplex hosts concentrated RCM platform development targeting ambulatory surgical centers.
Germany
Hospital procurement pipelines prioritize BfArM-certified medical device software for revenue cycle platforms. The EU AI Act's risk-tiering framework constrains automated payment algorithms, requiring human-in-the-loop overrides. Bavaria's Munich-Stuttgart corridor anchors vendor development of explainable AI certifications for European hospital buyers.
India
CDSCO digital health guidelines create compliance pathways for software-as-medical-device platforms. Cloud-native vendors establish local data residency to capture first-mover advantage in emerging markets. Bangalore and Hyderabad clusters specialize in FHIR-native development for export to US health systems.
United Kingdom
NHS procurement frameworks drive demand for integrated revenue cycle solutions across hospital trusts. GDPR compliance requirements shape vendor data governance architectures for European deployment. London's health tech corridor concentrates AI-enabled denial prediction development for private healthcare providers.
Japan
METI digital health initiatives accelerate cloud migration away from legacy on-premise hospital information systems. JIS standards for medical software create certification barriers for foreign platform vendors. The Tokyo-Osaka corridor hosts domestic development of embedded EHR billing modules for hospital-centric operations.
Global Back-End Revenue Cycle Management Market Competitive Landscape
Player mix skews toward payer-provider integrated conglomerates and embedded EHR specialists. The vendor base concentrates around three strategic archetypes: vertically integrated health services conglomerates with captive payer relationships, EHR-native platform developers with high hospital switching costs, and standalone RCM specialists competing on denial recovery rates. Dominant competitive moves include payer-provider vertical integration and EHR ecosystem embedding through API partnerships.
Among US-based integrated health services conglomerates, Optum, Inc. and McKesson Corporation exemplify the payer-provider convergence archetype. Epic Systems Corporation anchors the embedded EHR specialist tier with hospital-centric revenue cycle operations. These three entities represent distinct competitive positioning vectors: payer control over denial workflows, pharmacy-revenue synergies across hybrid delivery models, and EHR-native billing module dominance.
| Leading Market Players |
|---|
| Optum, Inc. |
| Epic Systems Corporation |
| Oracle |
| McKesson Corporation |
| Solventum |
| athenahealth, Inc. |
| R1 RCM, Inc. |
| Conifer Health Solutions, LLC |
| Cognizant Technology Solutions Corporation |
| Others |
Supply & Pricing Matrix
HIPAA transaction standards and BfArM medical device software classifications simultaneously gate vendor qualification and stratify price tiers across the Global Back-End Revenue Cycle Management Market. Certification investment creates supply-side barriers that protect premium pricing for compliant platforms while excluding uncertified competitors from hospital procurement pipelines.
Pricing Analysis
Legacy on-premise installations command residual premiums from risk-averse health systems with stringent data sovereignty requirements, while cloud-native SaaS tiers undercut them by sixty percent or more on annual contract value. Pricing stratifies across FHIR-native AI platforms, standard cloud-based workflows, and residual on-premise licenses, with differentiation anchored in certification grade and integration complexity. Cost compression in claims management is intensifying because automated clearinghouse standardization has commoditized electronic submission functions. Ambulatory surgical centers exhibit the highest price sensitivity due to thin operating margins, whereas integrated health systems prioritize total cost of ownership over license fees.
Supply Chain Analysis
Implementation timelines for cloud-native platforms have compressed from sixteen-week averages to under four weeks, eliminating inventory buffers and shifting vendor capacity constraints to engineering talent pools. Platform development concentrates in the United States, Germany, and India, with engineering talent drawn from Bangalore's FHIR-specialist clusters and Munich's medical device software corridors. Raw material dependencies center on cloud compute capacity from AWS, Azure, and Google Cloud, proprietary NLP training datasets, and HL7 FHIR-compliant middleware libraries. Single-source vulnerability in hyperscaler hosting creates concentration exposure for multi-tenant architectures. Distribution runs through direct enterprise sales teams for health systems and channel partnerships with EHR vendors for physician practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
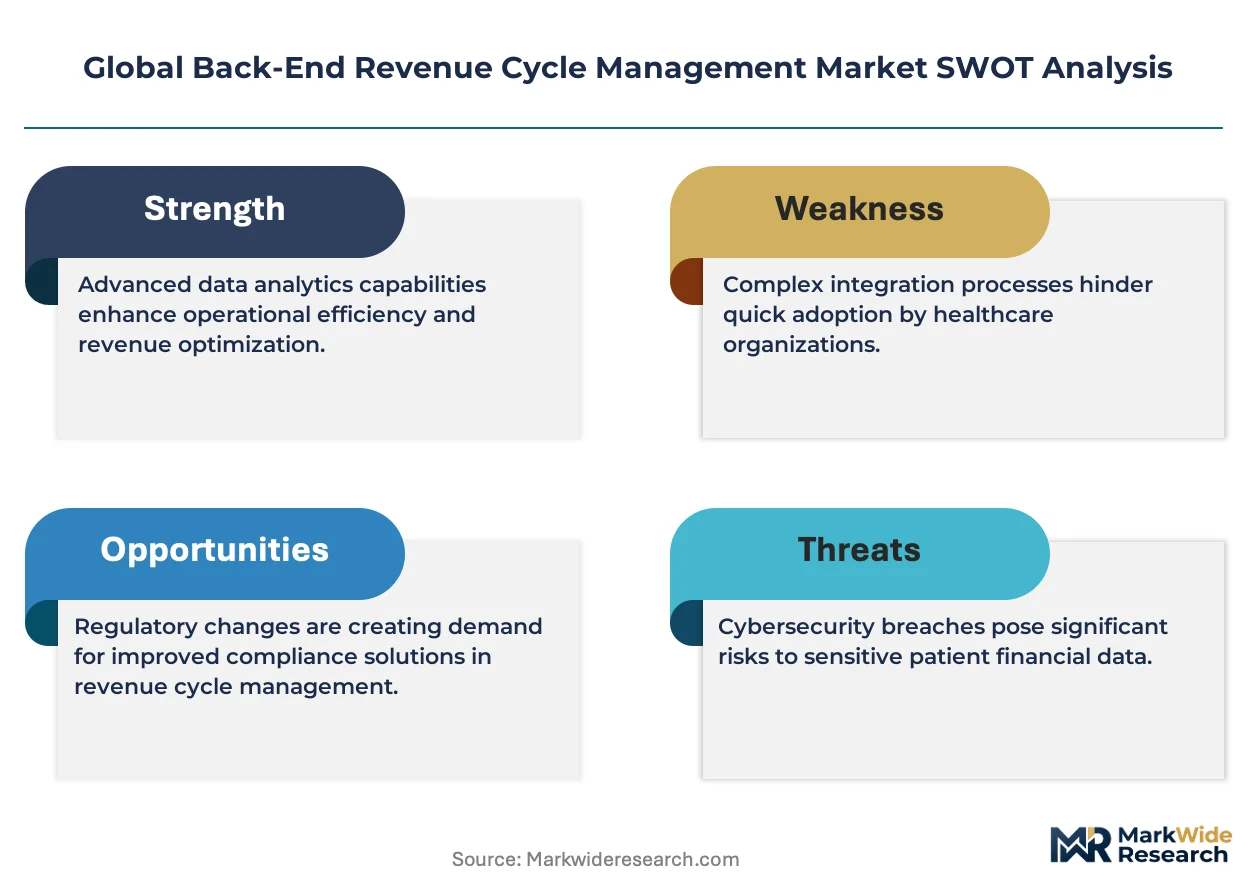
Vendor success in this market hinges on scarce FHIR implementation expertise and explainable AI engineering capabilities that health systems cannot rapidly internalize. The gap between regulatory mandate deadlines and available informaticist supply creates asymmetric advantage for platforms with pre-certified, deployment-ready architectures.
For Market Incumbents: Consolidate denial management specialist acquisitions to capture premium margin pools from complex payer contract variability. Deepen API embedding partnerships with Epic Systems Corporation to defend against displacement by standalone RCM vendors. Invest in BfArM and CDSCO certification pathways ahead of competitor entry into European and Indian hospital procurement pipelines.
For New Entrants and Emerging Players: Lead with pre-submission NLP models targeting US metropolitan physician practices under private equity consolidation pressure. India's ambulatory surgical centers present the most penetrable geography given CDSCO guideline alignment and local data residency requirements. Position through channel partnerships with regional EHR distributors rather than direct enterprise sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native AI platforms as R&D leverage improves with scaled training data. Long-term viability favors vendors with payer-provider integration depth or EHR-native switching cost moats. Acquisition target archetype: standalone denial management specialists with proven recovery rate superiority in specific therapeutic categories. Monitor CMS interoperability mandate enforcement intensity as inflection indicator for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems Corporation's embedded billing modules create hospital switching costs that lock out standalone competitors. |
| Regulatory Certification Pathway | BfArM medical device software classification accelerates vendor entry into German hospital procurement pipelines. |
| Strategic Partnership | Payer-provider integration at Optum, Inc. controls denial management workflows at scale across outsourced delivery. |
| Acquisition of Specialist Firm | Denial management specialists with NLP-trained models capture premium pricing from complex prior authorization variability. |
| Geographic Expansion | CDSCO-compliant data residency in India opens first-mover advantage for cloud-native vendors in emerging markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, CMS Medicare data, GPO contracts, and BfArM certification registries. Interviews with revenue cycle executives, hospital purchasing committees, biomedical informaticists, and payer operations directors informed demand-side validation. Supply-side triangulation incorporated SEC filings from publicly traded vendors, hyperscaler healthcare vertical disclosures, and CDSCO digital health guideline documentation. Bottom-up sizing of installed platform counts across end-user segments was cross-checked against top-down expenditure estimates from national health accounts.
Segmentation dimensions modeled include service type, technology deployment architecture, end-user scale category, and delivery model preference across the projection horizon. CAGRs were derived from logistic adoption curves fitted to historical cloud migration patterns and regulatory deadline impacts. Industry-specific forecast inputs incorporated CMS interoperability mandate compliance timelines and BfArM certification throughput capacity. Value outputs reflect annual contract value aggregation rather than license revenue alone.
Forecasts assume regulatory continuity in HIPAA transaction standards, CMS interoperability mandates, BfArM software classifications, and CDSCO digital health guidelines; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Global Emergency Department Information System Market