
 North America Waterborne Adhesives Market | 2026-2036
North America Waterborne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Waterborne Adhesives Market Analytics
Multi-source procurement for resin intermediates is hardening across the value chain as formulators seek supply security. Dow leverages captive acrylic emulsion capacity to sustain margin stability across packaging grades. Henkel AG & Co. KGaA anchors its position through specialized automotive bonding solutions that navigate OEM qualification timelines. H.B. Fuller competes aggressively in wood bonding applications where it controls distribution through direct mill relationships.
Waterborne adhesives are aqueous polymer dispersions, typically 40-60% solids content, that form bonds through evaporation-driven coalescence of acrylic, polyurethane, or vinyl acetate particles. These systems serve as the primary bonding medium in applications where solvent emission control, worker safety, or flammability restrictions disqualify conventional solvent-based alternatives. Acrylic formulations dominate volume in packaging and construction applications where fast tack and clarity command premium positioning. Polyurethanes represent the fastest-expanding technology segment, driven by automotive interior assembly and flexible lamination demands that require heat resistance and bond flexibility. Vinyl acetate-ethylene copolymers occupy mature, cost-sensitive niches in wood bonding and general assembly where performance thresholds remain modest.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based adhesive use in manufacturing facilities across the United States. California Air Resources Board SCM 2007 limits and evolving LEED v4.1 material ingredient reporting requirements shape product formulation decisions and market access conditions. Stakeholders must monitor state-level green procurement mandates and bio-based content verification protocols as these frameworks increasingly determine specification eligibility in public and private construction projects.
Market Dynamics
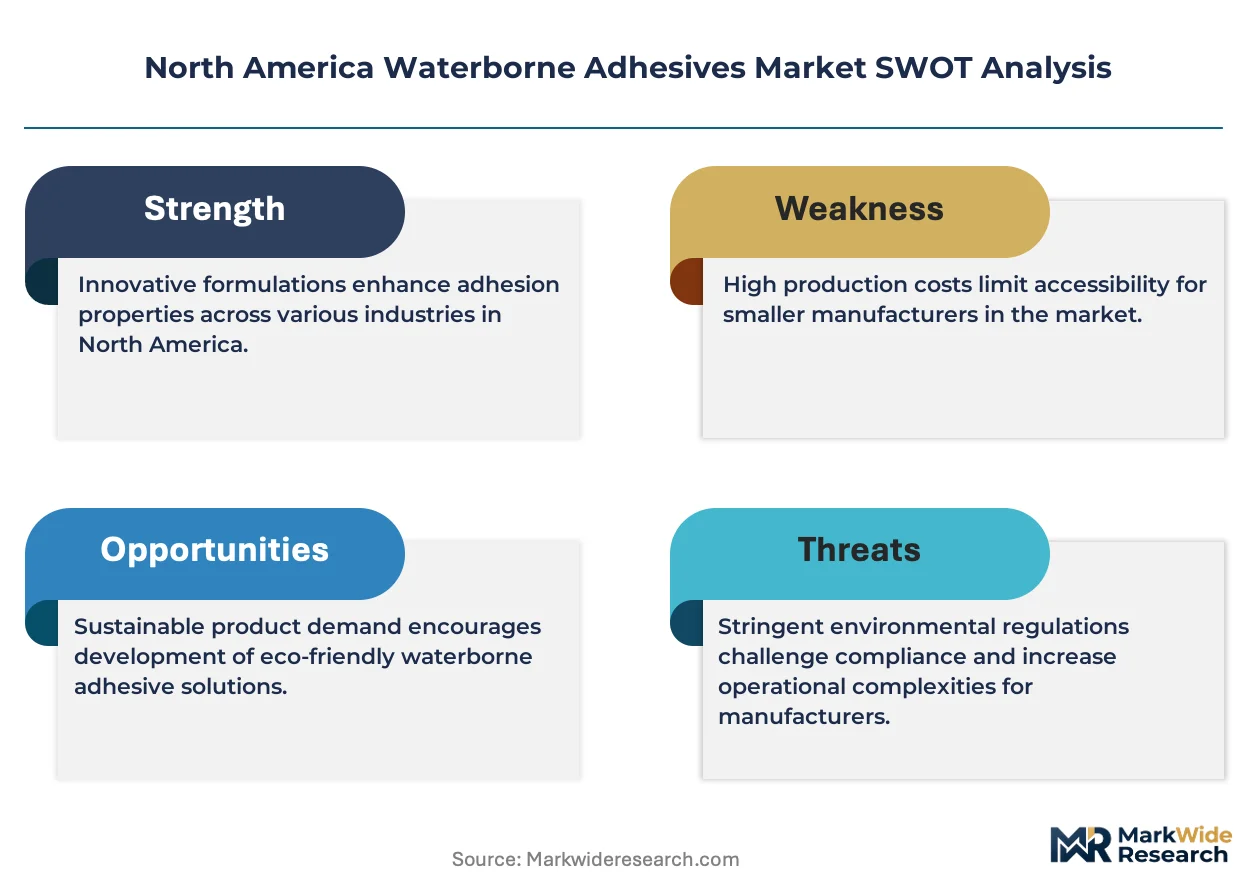
EPA VOC emission limits under the National Emission Standards for Hazardous Air Pollutants are compressing solvent-based adhesive capacity across United States manufacturing facilities, forcing formulators to reconfigure production lines for waterborne acrylic and polyurethane systems.
Growth Catalysts
- California SCM 2007 limits:State-level mandates in California and New York accelerate solvent-to-waterborne conversion in packaging and furniture applications.
- Automotive interior assembly:Heat-resistant polyurethane dispersions capture specification share from solvent-based alternatives in flexible lamination and trim bonding.
- US Southeast manufacturing clusters:Furniture mills and automotive assembly plants in Georgia, North Carolina, and Tennessee anchor regional offtake expansion.
Market Restraints
- Acrylic monomer cost volatility:Crude-linked propylene derivatives expose formulators to margin compression during energy price spikes.
- Water sensitivity in cured films:Performance gaps versus solvent-based systems limit specification in exterior construction and marine applications.
- Extended drying cycles:Evaporation-driven coalescence requires longer open times, constraining high-speed packaging line throughput.
Strategic Opportunities
- Mexico automotive supplier base:Underpenetrated Tier-2 and Tier-3 component manufacturers present conversion potential for polyurethane bonding systems.
- LEED v4.1 material ingredient reporting:Green building certification pathways create specification pull for low-VOC adhesives in commercial construction.
- Bio-based content verification protocols:Emerging USDA BioPreferred and state procurement mandates open premium positioning for partially renewable formulations.
Industry Challenges
- OEM qualification timelines:Automotive and aerospace bonding specifications require 18-36 month validation cycles, locking out new entrants.
- Formulation chemist scarcity:Specialized expertise in emulsion polymerization and rheology control concentrates at established suppliers, constraining talent mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Waterborne Adhesives Market |
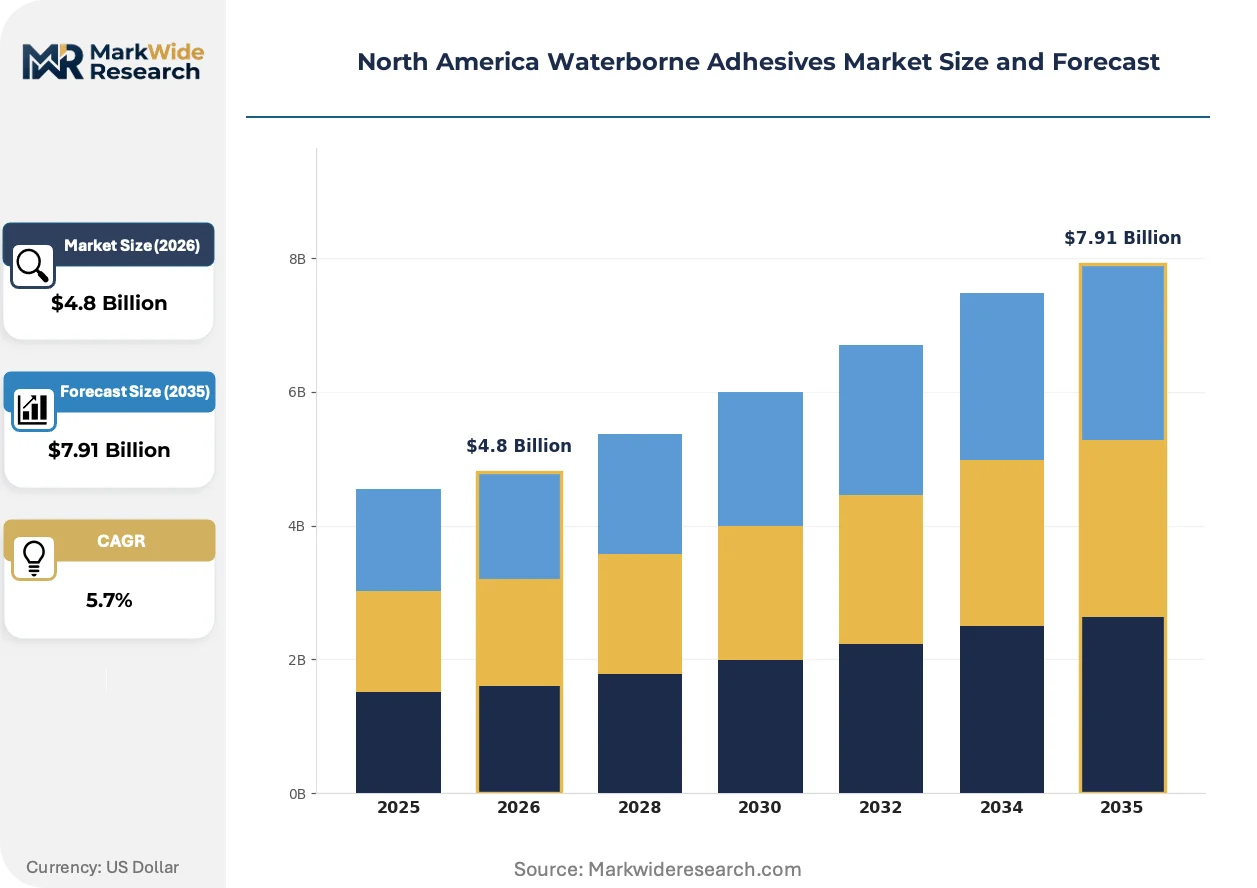
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
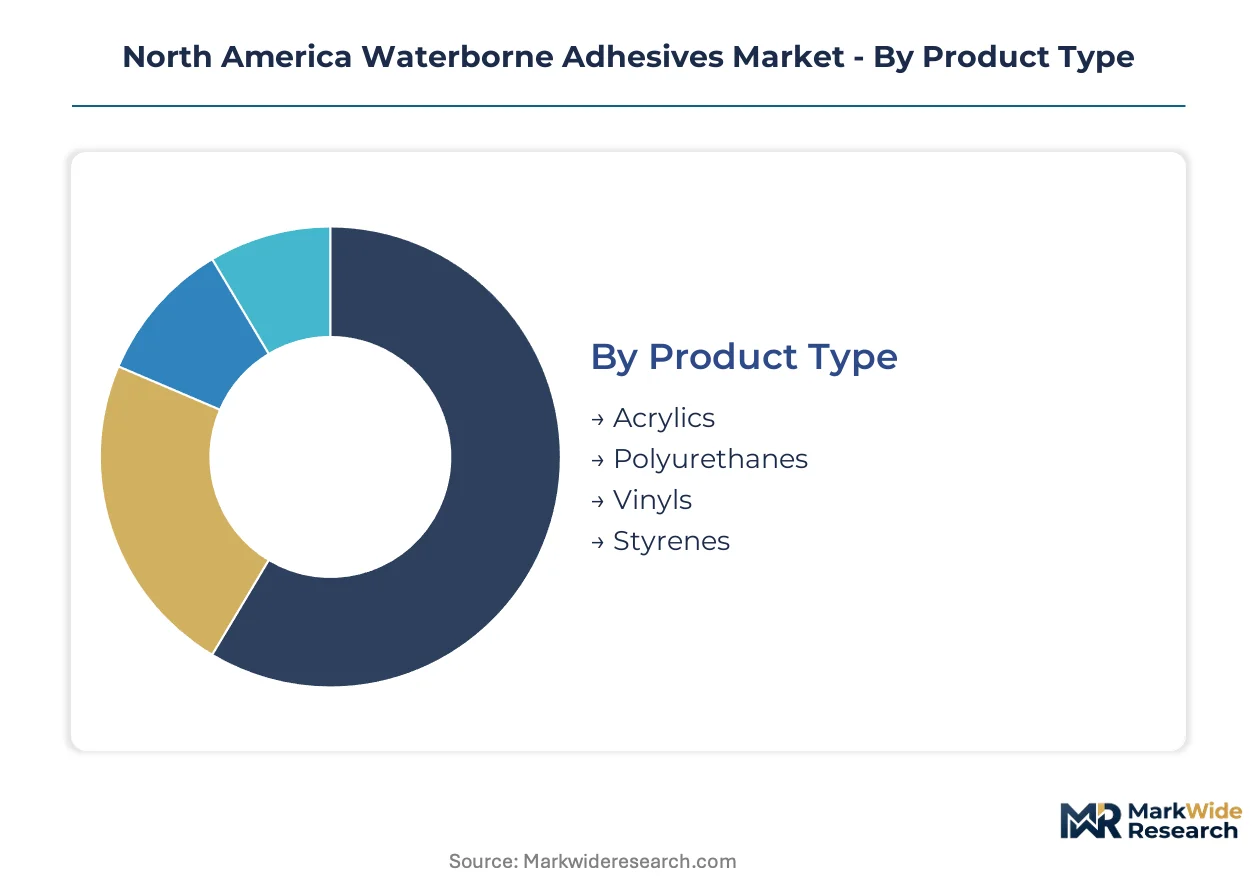
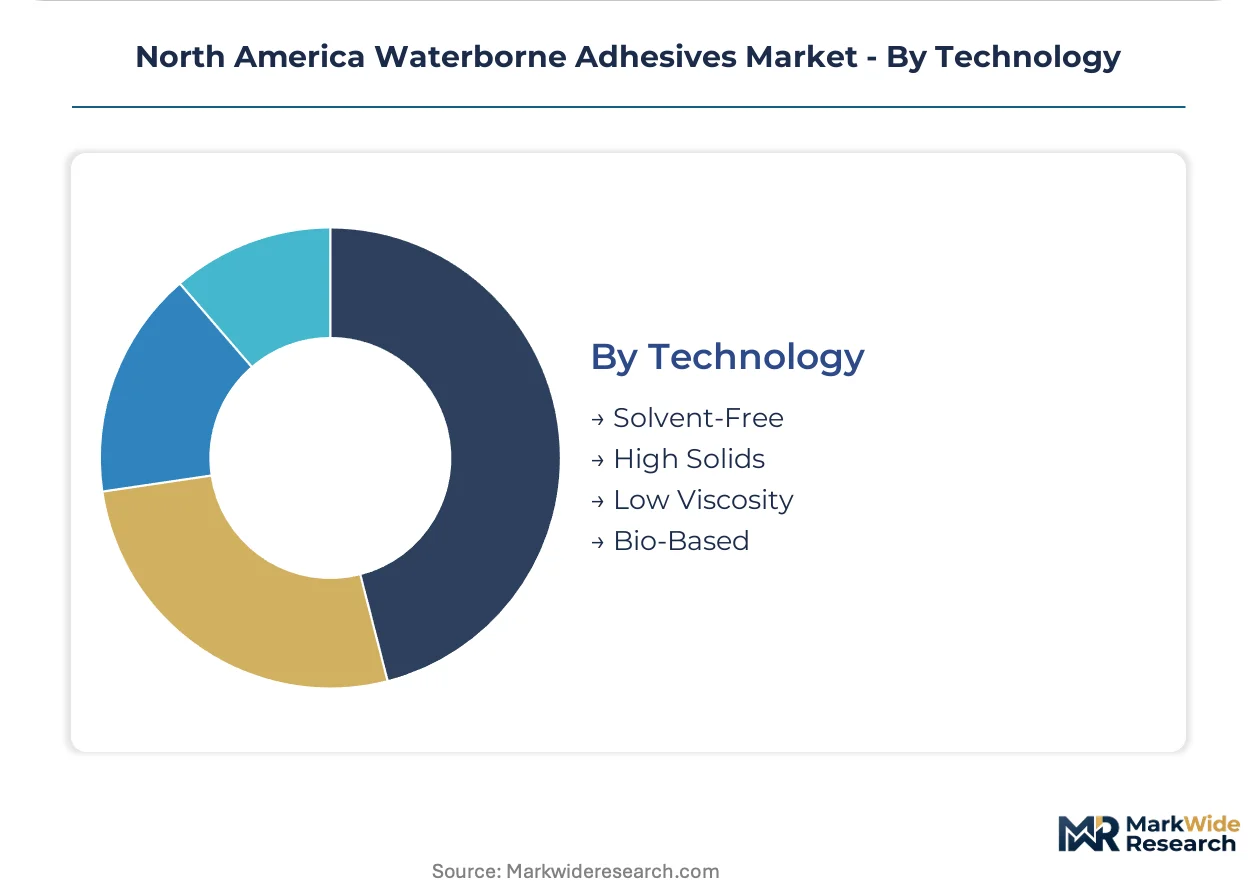
| Segmentation | Product Type: Acrylics, Polyurethanes, Vinyls, Styrenes Application: Packaging, Wood Bonding, Automotive, Textiles End User: Furniture, Construction, Electronics, Footwear Technology: Solvent-Free, High Solids, Low Viscosity, Bio-Based |
| Companies Covered | 3M, Arkema Group, Dow, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller, Ashland, Franklin Adhesives & Polymers, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Waterborne Adhesives Market Evolving Landscape
Formulation chemistry is advancing through hybridization of acrylic and polyurethane backbones, while regulatory pressure and buyer specification requirements compress adoption cycles for next-generation waterborne systems.
Hybrid acrylic-polyurethane dispersions are electrifying performance expectations in flexible packaging lamination. These systems combine the fast tack of acrylics with the heat and chemical resistance of polyurethanes. Major food packaging converters in the US Midwest and Southeast are qualifying these formulations for retort pouch and lidding applications. The technology is electrifying specification standards that previously required solvent-based or two-component systems.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening ambient air monitoring at adhesive manufacturing facilities. Compliance costs are accelerating capital deployment toward closed-loop waterborne production equipment. Small and mid-size formulators in Texas and Ohio face the steepest reconfiguration burdens as they retrofit legacy solvent-capable assets.
Mill-direct specification relationships are consolidating procurement influence among large wood products manufacturers. These buyers now mandate technical service integration and just-in-time delivery as table stakes for adhesive supply contracts. The pattern is most pronounced in North Carolina and Virginia furniture manufacturing corridors, where three-to-five year sole-source agreements are replacing spot purchasing.
North America Waterborne Adhesives Market Segmentation
Waterborne adhesive procurement decisions in North America increasingly pivot on reformulation timelines driven by EPA VOC enforcement and state-level green chemistry mandates. Buyers segment suppliers by their capacity to deliver compliant systems without disrupting existing production line speeds.
Product Type:
Upgrade cycles from solvent-based to waterborne systems concentrate procurement attention on formulations that minimize equipment retrofit requirements while meeting emission thresholds.
- Acrylics:Aqueous polymer dispersions with 40-60% solids content deliver fast tack and optical clarity for flexible packaging applications. Demand clusters among Southeast US food packaging converters navigating California Air Resources Board SCM 2007 limits for lidding and label stock.
- Polyurethanes:Heat-resistant dispersions form flexible, durable bonds through coalescence of segmented polymer chains. Automotive interior assembly plants in Tennessee and Michigan specify these systems for trim bonding and flexible lamination where solvent-based alternatives face EPA National Emission Standards for Hazardous Air Pollutants constraints.
- Vinyls:Vinyl acetate-ethylene copolymers serve cost-sensitive wood bonding and general assembly applications with modest performance requirements.
- Styrenes:Styrene-butadiene emulsions anchor pressure-sensitive adhesive formulations for tape and label markets.
Acrylics sit at the top of the volume ranking, with polyurethanes climbing the fastest.
Application:
Cost tier differentiation separates specification-grade formulations from commodity alternatives across end-use verticals.
- Packaging:FDA-compliant acrylic and polyurethane systems bond flexible films, paperboard, and aluminum substrates in food-contact applications. Midwest and Southeast converters prioritize formulations qualifying for retort pouch and lidding specifications.
- Wood Bonding:Vinyl acetate-ethylene copolymers dominate furniture and millwork assembly where bond line appearance and cold-creep resistance determine specification. North Carolina and Virginia manufacturing corridors drive regional offtake through mill-direct procurement relationships.
- Automotive:Heat-resistant polyurethane dispersions capture specification share in interior trim, headliner, and seat assembly applications requiring fogging resistance and bond durability.
- Textiles:Low-viscosity acrylic emulsions serve fabric lamination and technical textile bonding where hand feel and wash durability command premium positioning.
Packaging commands the largest volume position, while automotive applications expand most quickly.
End User:
Customer type segmentation reveals divergent procurement patterns between specification-driven OEMs and price-sensitive contract manufacturers.
- Furniture:Solid wood and engineered panel manufacturers in the US Southeast specify waterborne systems for casegoods and upholstery frame assembly. Three-to-five year sole-source agreements are replacing spot purchasing among large manufacturers.
- Construction:Commercial builders and flooring installers select low-VOC adhesives to meet LEED v4.1 material ingredient reporting requirements and state green procurement mandates.
- Electronics:Device assembly operations require precision-dispensed formulations with controlled rheology for component bonding and display lamination.
- Footwear:Upper-to-sole bonding and material lamination applications favor polyurethane dispersions offering flexibility and abrasion resistance.
Furniture anchors current demand volumes, with construction end-use gaining share fastest.
Technology:
Supply concentration among emulsion polymerization specialists shapes availability of advanced technology tiers.
- Solvent-Free:Pure aqueous systems eliminate co-solvent content entirely, maximizing compliance with EPA National Emission Standards for Hazardous Air Pollutants. Formulators with captive acrylic emulsion capacity leverage these systems for margin stability.
- High Solids:Concentrated dispersions above 55% solids reduce drying energy and line footprint for high-throughput packaging converters.
- Low Viscosity:Shear-thinning formulations enable spray and roll coating application methods in textile and automotive assembly operations.
- Bio-Based:Partially renewable formulations incorporating bio-derived monomers or starch-modified backbones target USDA BioPreferred verification and state-level bio-content procurement mandates.
Solvent-free technology holds the dominant volume position, with bio-based formulations expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns within North America reflect divergent cost-of-compliance trajectories, with manufacturers repositioning capacity to exploit regulatory arbitrage between US federal EPA mandates and Mexico's evolving environmental enforcement framework.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforcement compresses solvent-based adhesive capacity across Ohio and Texas manufacturing corridors. California Air Resources Board SCM 2007 limits and New York state green chemistry mandates accelerate formulation conversion in packaging and furniture applications. Georgia, North Carolina, and Tennessee anchor regional offtake expansion through furniture manufacturing clusters and automotive assembly plants.
Canada
Health Canada and Environment and Climate Change Canada coordinate VOC emission guidelines that align with US EPA thresholds while maintaining provincial flexibility. Ontario and Quebec house the dominant adhesive formulation capacity, serving cross-border automotive and packaging supply chains. Toronto-Windsor corridor manufacturers qualify products for LEED v4.1 material ingredient reporting requirements in commercial construction specifications.
Mexico
Automotive supplier base expansion in Nuevo León and Bajío Region creates conversion potential for polyurethane bonding systems in Tier-2 and Tier-3 component manufacturing. PROFEPA environmental enforcement remains less stringent than US EPA standards, attracting solvent-capable production from cost-pressured formulators. Mexico City Metro and Guadalajara industrial zones concentrate packaging converter demand for acrylic emulsion systems.
Southeast US Manufacturing Belt
Furniture mills in Virginia and North Carolina drive mill-direct procurement relationships with three-to-five year sole-source agreements replacing spot purchasing. Automotive interior assembly plants in Tennessee and South Carolina specify heat-resistant polyurethane dispersions for trim bonding applications. Regional formulators leverage proximity to anchor OEM qualification programs and just-in-time delivery mandates.
North America Waterborne Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and specialty automotive qualifications. The vendor base concentrates among integrated chemical conglomerates with captive resin capacity and regional specialists with mill-direct distribution control. Three archetypes dominate: diversified materials conglomerates with backward integration into acrylic emulsion production, adhesive specialists with automotive OEM qualification expertise, and regional formulators with furniture industry relationships. Competitive moves center on hybrid formulation development and geographic expansion into underpenetrated Mexican automotive supply tiers.
Among diversified chemical conglomerates, Dow and BASF SE exemplify integrated producers with captive acrylic emulsion capacity sustaining margin stability across packaging grades. Henkel AG & Co. KGaA and H.B. Fuller occupy positions within the specialty adhesive tier, with the former representing automotive bonding qualification expertise and the latter anchoring wood bonding distribution through direct mill relationships. These four entities collectively illustrate the competitive structure's bifurcation between scale-driven raw material control and relationship-driven specification access.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller |
| Ashland |
| Franklin Adhesives & Polymers |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Hybrid acrylic-polyurethane dispersion production is concentrating capacity among integrated resin producers while simultaneously compressing cost economics for mid-tier formulators lacking captive emulsion assets. This technology shift rewards suppliers with backward integration into propylene derivatives while exposing non-integrated competitors to margin volatility from crude-linked feedstock costs.
Pricing Analysis
Distributor margins in the Southeast furniture corridor absorb 12-18% of landed adhesive costs before mill-direct relationships capture volume discounts. Pricing stratifies across automotive qualification-grade, packaging-compliant, and general assembly tiers, with certification investment separating premium positioning from commodity alternatives. Cost compression in standard acrylic grades is intensifying because propylene derivative volatility exposes non-integrated formulators during energy price spikes. Contract manufacturers in Mexico represent the most price-sensitive segment, while OEM-qualified automotive suppliers accept premium positioning for validated polyurethane systems.
Supply Chain Analysis
Freight costs from Texas and Ohio formulation hubs to Southeast manufacturing clusters add 8-12% to delivered adhesive economics, favoring regional producers with just-in-time capabilities. Supply concentrates in the United States, Canada, and Mexico, with captive acrylic emulsion capacity anchoring margin stability for Dow and BASF SE. The chain draws from crude-linked propylene derivatives, isocyanate precursors, and specialty surfactants, with single-source vulnerability in automotive-qualified polyurethane intermediates. Distribution runs through direct mill relationships in furniture, Tier 1 supplier integration in automotive, and packaging converter networks in the Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Waterborne Adhesives Market functions as a stable compounder, with EPA VOC enforcement and state-level green chemistry mandates creating durable conversion tailwinds from solvent-based alternatives.
For Market Incumbents: Deepen captive emulsion capacity to defend margin stability against propylene derivative volatility while accelerating hybrid formulation R&D to capture automotive interior assembly specifications. Threats concentrate in emerging bio-based entrants pursuing USDA BioPreferred verification and Mexican automotive supplier conversion. Prioritize sole-source contract renewal in North Carolina and Virginia furniture corridors before spot purchasing relationships erode. For New Entrants and Emerging Players: Begin with underpenetrated Tier-2 and Tier-3 automotive component manufacturers in Nuevo León and Bajío Region, where polyurethane bonding system conversion lags OEM assembly plant adoption. The most penetrable segment sits in Mexico packaging converters seeking California CARB SCM 2007 compliance without equipment retrofit burden. Pursue technical service integration as the primary go-to-market angle, positioning formulation chemist expertise as the differentiator against commodity acrylic suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with furniture industry relationships but lacking automotive qualification expertise, creating roll-up opportunity before OEM validation timelines extend. Long-term viability centers on exposure to regulatory conversion rather than cyclical construction demand. The signal to watch is California Air Resources Board enforcement intensity, which accelerates solvent-to-waterborne conversion velocity and expands addressable market for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Captive acrylic emulsion additions in Texas and Ohio secure margin stability against propylene volatility. |
| Backward Integration | Upstream control over resin intermediates reduces exposure to crude-linked feedstock cost spikes. |
| Green Manufacturing Transition | Bio-based content verification opens premium positioning under USDA BioPreferred and state procurement mandates. |
| Long-term Supply Agreement | Three-to-five year sole-source contracts in Southeast furniture corridors lock out spot purchasing competitors. |
| Joint Venture | Partnerships with Mexican automotive Tier 2 suppliers accelerate polyurethane system qualification timelines. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market triangulated against cross-border supply chain dynamics. The analysis combines primary interviews with adhesive formulation chemists, procurement leads at packaging converters, automotive Tier 1 supplier quality engineers, and furniture manufacturing operations directors with secondary validation from EPA enforcement records, California Air Resources Board regulatory filings, customs trade data, and SEC 10-K disclosures from integrated chemical producers. Bottom-up demand modeling across end-use verticals and top-down supply capacity assessment ensure triangulation integrity.
Rate-of-change decomposition separates volume expansion from mix-shift effects across the projection horizon. The analytical framework models segmentation dimensions including product chemistry, application vertical, end-user industry, technology tier, and regional production hub. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and OEM qualification cycle timelines. Industry-specific forecast inputs incorporate EPA National Emission Standards enforcement intensity and LEED v4.1 adoption velocity in commercial construction specifications.
Several conditions sit outside the modeled scope, including abrupt shifts in crude oil pricing affecting propylene derivative economics, unforeseen delays in automotive OEM validation programs, and potential relaxation of PROFEPA enforcement in Mexico attracting solvent-capacity migration. Forecasts reflect assumptions about regulatory continuity and conversion timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane Adhesives Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Industrial Wood Adhesives Market