
 France Adhesives Market | 2026-2036
France Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
France Adhesives Market Foresight
Specialty formulation services is rewriting margin allocation across the France adhesives value chain. Arkema Group leverages its upstream acrylic monomer position to capture premium pricing in high-performance segments. Henkel AG & Co. KGaA sustains dominance in automotive OEM bonding through dedicated technical centers near Paris and Lyon. Sika AG anchors construction-sector demand with mortar-adhesive hybrid systems engineered for French building codes.
Adhesives are non-metallic substances applied to surfaces that develop structural or semi-structural bonds through chemical curing, physical setting, or pressure-sensitive tack, with formulations typically comprising resins, tackifiers, plasticizers, and curing agents in viscosities ranging from water-thin liquids to paste consistencies. Their primary industrial purpose is to join dissimilar materials—metals to composites, glass to plastics, textiles to foams—while distributing stress across bonded areas rather than concentrating it at mechanical fastening points. Acrylic and polyurethane formulations lead volume consumption in France, with acrylics commanding margin pools in electronics assembly and transparent bonding applications where optical clarity and UV resistance prove critical. Hot melt adhesives represent the fastest-expanding product category, displacing solvent-based systems in packaging solutions and bookbinding as converters retrofit lines to eliminate drying stages and reduce energy intensity.
REACH registration requirements and the EU F-Gas Regulation constrain fluorinated chemistry use in adhesive formulations, pushing manufacturers toward bio-based polyols and renewable tackifier feedstocks. ANSM oversight of workplace chemical exposure and France's national low-carbon strategy further tighten VOC emission thresholds in industrial adhesive applications. Stakeholders must monitor bio-based raw material certification schemes and anticipate tightening carbon border adjustment impacts on imported adhesive intermediates.
Market Dynamics
Automotive lightweighting mandates and REACH-driven VOC restrictions are forcing formulation pivots toward bio-based polyols and structural bonding systems across French industrial corridors.
Growth Catalysts
- Automotive lightweighting programs:OEMs in the Rhône-Alpes manufacturing belt are expanding structural adhesive bonding to replace mechanical fasteners in multi-material vehicle architectures.
- REACH compliance deadlines:ECHA registration requirements are accelerating R&D investment in low-VOC acrylic and polyurethane formulations for electronics and packaging applications.
- Packaging line retrofits:Hot melt systems are capturing share from solvent-based alternatives as converters in Île-de-France eliminate drying stages and reduce energy intensity.
Market Restraints
- Bio-based feedstock cost volatility:Renewable tackifier and polyol prices fluctuate with agricultural commodity cycles, compressing margin pools for mid-tier formulators.
- Fluorinated chemistry constraints:The EU F-Gas Regulation limits high-performance fluoropolymer adhesive availability for extreme-temperature aerospace and electronics bonding.
- Specialized curing equipment capex:UV and moisture-cure systems require significant capital outlay, slowing adoption among small-scale French packaging converters.
Strategic Opportunities
- Underpenetrated medical device bonding:ANSM oversight of biocompatibility standards creates first-mover advantage for cyanoacrylate and silicone adhesive suppliers to surgical instrument manufacturers.
- Construction renovation wave:France's national low-carbon strategy and building energy retrofit mandates are expanding demand for mortar-adhesive hybrid systems in façade and flooring applications.
- Circular economy certification:Cradle-to-Cradle and EU Ecolabel schemes offer premium positioning for adhesive suppliers demonstrating closed-loop feedstock traceability.
Industry Challenges
- Formulation chemist shortage:France's specialized polymer chemistry talent pipeline struggles to match demand from automotive and electronics OEM technical centers near Paris and Lyon.
- REACH registration timeline compression:ECHA dossier preparation and substance evaluation periods extend product launch cycles by 18-36 months for novel bio-based chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Adhesives Market |
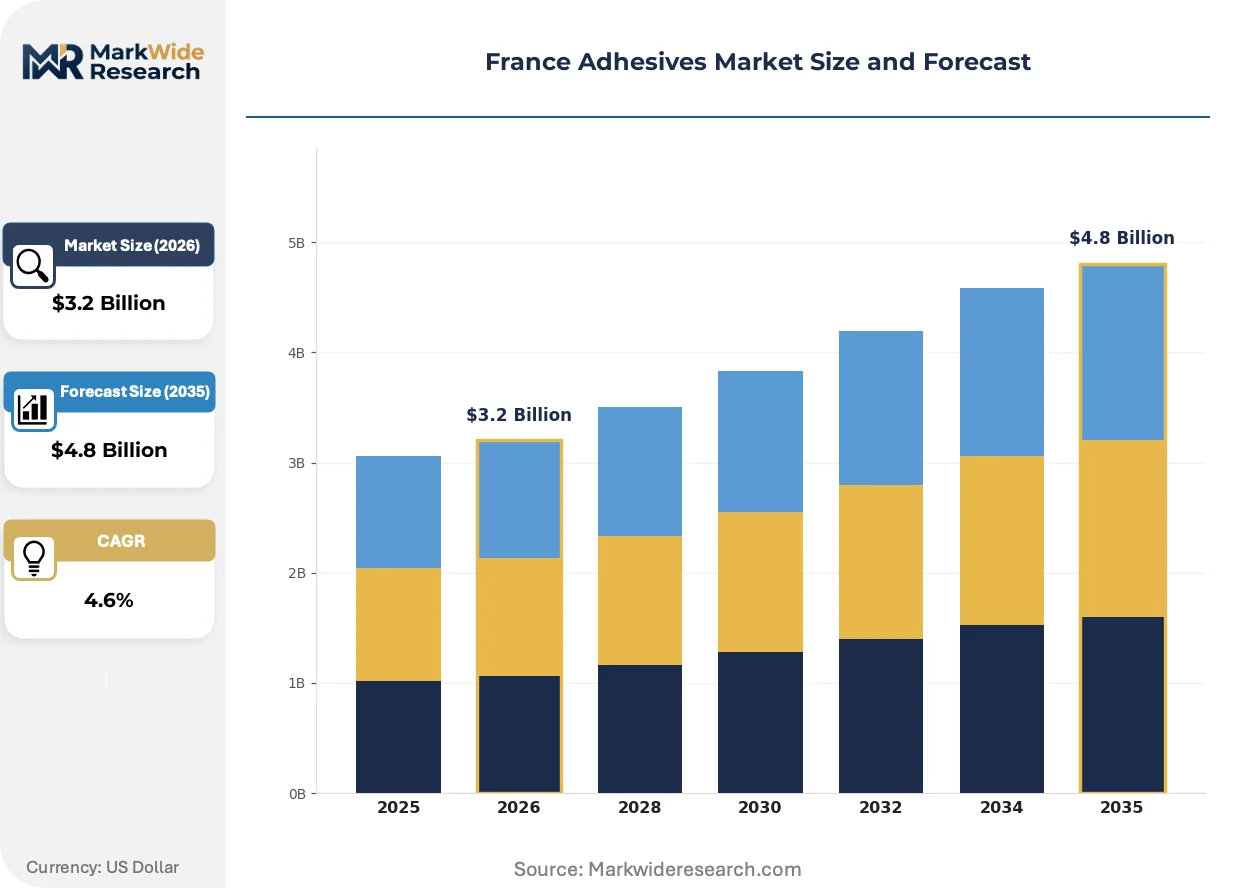
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.8 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone, Hot Melt, Rubber-Based Application: Construction, Electronics Assembly, Bookbinding, Footwear Manufacturing, Packaging Solutions, Textile Lamination End User Industry: Consumer Goods, Aerospace, Marine, Furniture Manufacturing, Electrical Devices, Sports Equipment Packaging Type: Tubes, Cartridges, Bulk Drums, Sachets, Bottles, Cans |
| Companies Covered | H.B. Fuller Company, Avery Dennison Corporation, Arkema Group, Huntsman International LLC, Dow, Henkel AG & Co. KGaA, 3M, Bolton Adhesives, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Adhesives Market Shifts & Advancements
Reactive hot melt and UV-cure platforms are compressing process steps and energy loads across French packaging and assembly operations. Formulation houses are racing to synchronize adhesive performance with automated dispensing robotics and inline quality verification systems.
Reactive polyurethane hot melt adhesives are collapsing the distinction between initial tack and final structural strength in automotive interior assembly. Tier-1 suppliers around Saint-Étienne and Grenoble are adopting these systems for dashboard and trim bonding to eliminate clamping fixtures and accelerate line speeds. The technology is collapsing capital requirements for multi-material joining while expanding design freedom for composite-intensive vehicle platforms.
France's national low-carbon strategy and the EU CSRD are mandating Scope 3 emissions disclosure across industrial supply chains. Adhesive formulators must now document cradle-to-gate carbon intensity for bio-based and petroleum-derived feedstocks alike. Construction and automotive OEMs in the Île-de-France corridor are prioritizing suppliers with certified product carbon footprints, redirecting procurement toward domestic bio-polyol producers.
Buyers are consolidating adhesive supplier panels and demanding integrated bonding system packages rather than standalone products. Automotive OEM technical centers near Lyon now specify adhesive-dispensing-robot combinations as single procurement units, displacing independent equipment and chemical vendors. This pattern concentrates most visibly in electric vehicle battery pack assembly, where bondline integrity directly impacts thermal management performance and warranty exposure.
France Adhesives Market Segmentation
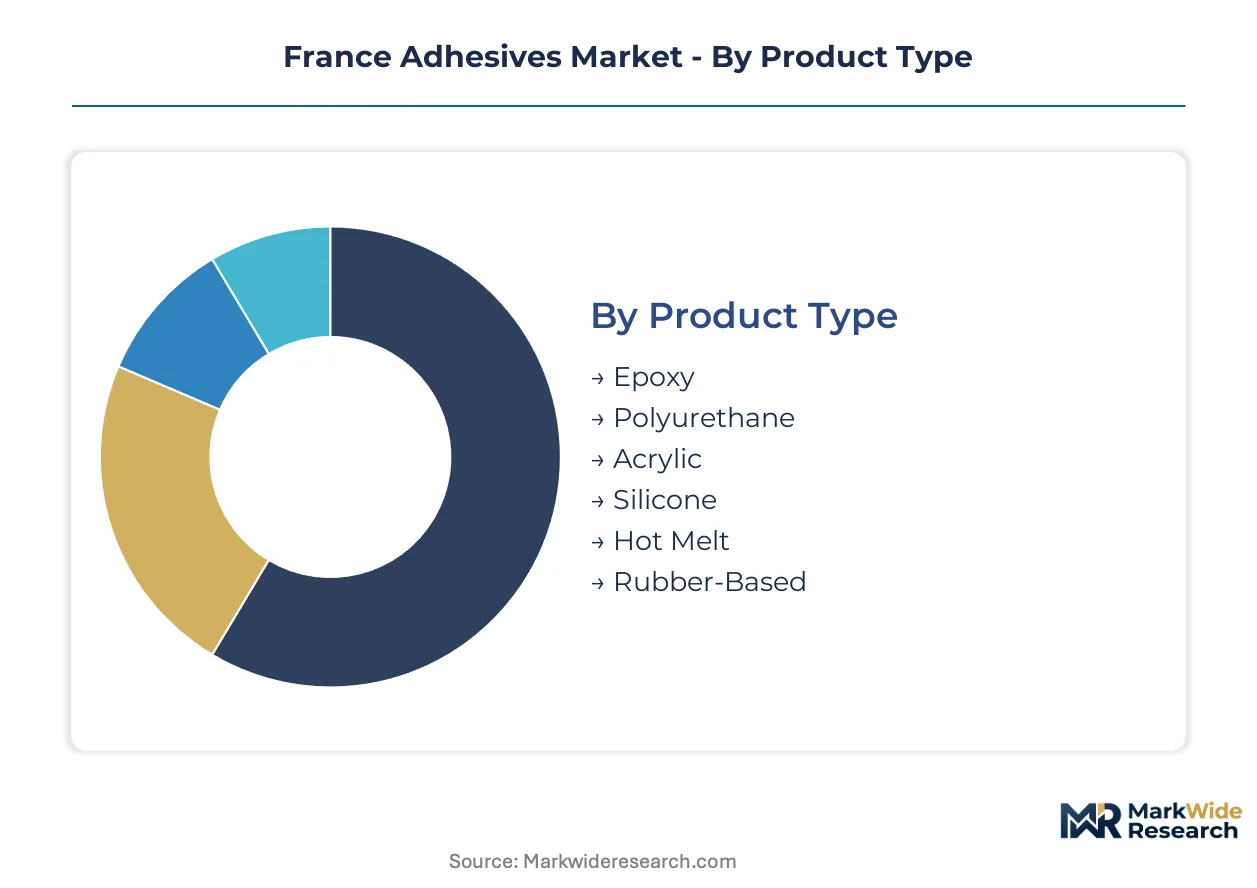
Segmentation in the France adhesives market reveals how formulation chemistry, application requirements, and packaging logistics create distinct margin pools. Technical service intensity varies dramatically across segments, with automotive and aerospace applications demanding dedicated application engineering while commodity packaging adhesives compete on throughput economics.
Product Type:
After-sales service intensity separates specialty formulations from commodity adhesives, with structural bonding systems requiring on-site technical support and curing optimization that standard hot melts rarely need.
- Epoxy:Two-part thermosetting systems delivering exceptional shear strength and chemical resistance for load-bearing applications. Demand concentrates in aerospace composite bonding around Toulouse and Nantes clusters, where ANSM-regulated biocompatibility standards govern medical device variants.
- Polyurethane:Reactive polymers offering flexibility across temperature extremes and substrate combinations. Automotive OEMs in the Rhône-Alpes belt specify moisture-cure polyurethanes for windshield bonding, with REACH registration requirements extending reformulation cycles for bio-based polyol variants.
- Acrylic:Rapid-cure formulations dominate electronics assembly with optical clarity and UV stability.
- Silicone:Extreme-temperature performance serves aerospace engine seals and medical device encapsulation.
- Hot Melt:Thermoplastic systems eliminate solvent drying in packaging and bookbinding operations.
- Rubber-Based:Pressure-sensitive tack drives tape and label applications with lower capital barriers.
Polyurethane holds the largest share; momentum sits with hot melt systems displacing solvent chemistries.
Application:
Cost tier stratification runs through application segments, with construction and electronics commanding premium pricing against commoditized bookbinding and packaging volumes.
- Construction:Structural and non-structural bonding for concrete, masonry, and insulation systems. Façade retrofit mandates under France's national low-carbon strategy are expanding mortar-adhesive hybrid demand in the Île-de-France corridor.
- Electronics Assembly:Precision dispensing of thermally conductive and electrically insulating formulations. Miniaturization trends in Grenoble semiconductor clusters are driving ultra-low outgassing specifications for display bonding.
- Bookbinding:EVA and PUR hot melts serve high-speed binding lines with minimal waste.
- Footwear Manufacturing:Polyurethane and rubber cements bond leather, synthetic, and textile uppers.
- Packaging Solutions:Case sealing and carton closing applications prioritize line speed over bond strength.
- Textile Lamination:Hot melt and reactive systems bond technical fabrics for automotive interiors and sportswear.
Construction commands the greatest value pool; electronics assembly offers the steepest expansion trajectory.
End User Industry:
Customer type diversity spans from specification-driven OEMs to price-sensitive contract manufacturers, with aerospace and marine segments demanding lot traceability that consumer goods buyers rarely require.
- Consumer Goods:High-volume packaging and assembly applications for household products and personal care. Major formulators maintain dedicated technical service teams near Paris to support just-in-line adhesive delivery for high-speed filling operations.
- Aerospace:Structural bonding for composite airframes and interior assemblies. Toulouse and Nantes manufacturing clusters specify certified materials with full batch documentation under EASA oversight.
- Marine:Hull bonding and deck sealing systems resistant to saltwater and UV degradation.
- Furniture Manufacturing:Edgebanding and panel lamination in mass production and custom craft segments.
- Electrical Devices:Potting and encapsulation for motor and transformer insulation.
- Sports Equipment:Ski, bicycle, and footwear bonding with impact and fatigue resistance requirements.
Aerospace dominates premium positioning; consumer goods generates the highest absolute volume.
Packaging Type:
Supply concentration in bulk logistics versus distributed retail channels shapes packaging format selection, with drum and tanker deliveries serving integrated manufacturers against cartridge formats for maintenance and repair operations.
- Tubes:Collapsible aluminum and plastic containers for manual dispensing in maintenance and small-batch assembly. Automotive repair shops across Lyon and Saint-Étienne favor 310ml tubes for windshield urethane replacement.
- Cartridges:Rigid cylinders for caulk-gun application in construction and industrial settings. Building contractors in the Rhône-Alpes region specify dual-component cartridges for structural anchoring adhesives.
- Bulk Drums:Returnable and disposable containers for continuous production lines.
- Sachets:Single-use pouches for field repair and consumer DIY applications.
- Bottles:Brush-applied contact cements and specialty formulations for craft and industrial use.
- Cans:Aerosol and brushable systems for sprayable contact adhesives and primers.
Bulk drums capture the greatest tonnage; cartridges offer the most favorable value-to-weight ratio.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France and Rhône-Alpes consume adhesives through divergent industrial lenses—automotive structural bonding in the southeast versus packaging and electronics assembly around Paris—creating distinct formulation requirements across French sub-regions.
Île-de-France
Packaging converters and electronics assemblers drive demand for hot melt and low-VOC acrylic systems. ANSM workplace exposure standards tighten emission thresholds for industrial adhesive applications in the Paris industrial belt. Technical service teams from major formulators cluster in Saint-Denis and Gennevilliers to support just-in-line adhesive delivery for high-speed filling operations.
Auvergne-Rhône-Alpes
Automotive OEMs and Tier-1 suppliers specify moisture-cure polyurethanes for windshield bonding and structural applications. REACH registration requirements extend reformulation cycles for bio-based polyol variants sourced from regional chemical producers. Saint-Étienne and Grenoble manufacturing clusters adopt reactive polyurethane hot melts for dashboard and interior trim assembly to eliminate clamping fixtures.
Provence-Alpes-Côte d'Azur
Aerospace composite bonding and marine sealing applications demand epoxy and silicone formulations with extreme-temperature performance. EASA oversight of certified materials governs structural adhesive specifications for Toulouse airframe manufacturing. Sophia Antipolis technology park attracts specialty formulators serving satellite and defense electronics assembly.
Hauts-de-France
Construction renovation and façade retrofit activity expands demand for mortar-adhesive hybrid systems under France's national low-carbon strategy. Building energy efficiency mandates drive specification of thermally insulating adhesive tapes for window and insulation panel installation. Lille metropolitan area contractors prioritize dual-component cartridge systems for structural anchoring in concrete and masonry substrates.
Nouvelle-Aquitaine
Furniture manufacturing and woodworking clusters consume edgebanding and panel lamination adhesives across mass production and craft segments. Bordeaux and Limoges industrial zones favor EVA and PUR hot melts for high-speed binding and veneer applications. Regional sawmills and panel processors specify low-formaldehyde formulations to meet indoor air quality certification schemes.
France Adhesives Market Competitive Landscape
Capability concentration sits with integrated chemical producers commanding resin and monomer supply; scale advantage sits with diversified industrial conglomerates distributing through established logistics networks. The market structures around three tiers: multinational formulation houses with dedicated French technical centers, mid-sized European specialists with niche application expertise, and regional distributors serving maintenance and repair channels. Consolidation pressure runs through M&A activity targeting bio-based formulation capabilities and strategic partnerships aligning adhesive suppliers with automated dispensing equipment vendors.
Within the integrated chemical tier, Arkema Group anchors upstream acrylic positioning, while Henkel AG & Co. KGaA and Sika AG exemplify divergent specialization vectors—consumer and industrial assembly versus construction and infrastructure bonding. These three entities occupy positions that span formulation depth, geographic coverage, and end-market diversification, representing the competitive archetypes against which mid-tier specialists and regional distributors benchmark capability investments.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Avery Dennison Corporation |
| Arkema Group |
| Huntsman International LLC |
| Dow |
| Henkel AG & Co. KGaA |
| 3M |
| Bolton Adhesives |
| Sika AG |
| Others |
Supply & Pricing Matrix
German and Belgian petrochemical producers control acrylic monomer and polyol feedstock supply into French formulation houses, concentrating margin capture upstream while downstream formulators compete on technical service bundling and REACH compliance speed.
Pricing Analysis
Long-term offtake contracts dominate raw material procurement, with spot purchases limited to agricultural-derived tackifiers subject to harvest volatility. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified epoxies from construction-grade polyurethanes and commodity hot melts. Cost compression in standard-tier packaging adhesives is intensifying because converters consolidate supplier panels and demand integrated dispensing-equipment packages. Consumer goods packaging buyers exhibit highest price sensitivity; aerospace OEMs prioritize batch documentation and technical support over unit cost.
Supply Chain Analysis
Extended payment terms from automotive OEMs strain working capital across Tier-1 adhesive distributors, prompting supply-chain finance facilities from regional banks. Feedstock supply draws from Germany, Belgium, and the Netherlands for petrochemical inputs; Spain and Italy for citrus-derived tackifiers. Propylene oxide and MDI availability rests on Antwerp-Rotterdam pipeline infrastructure; bio-based polyol output hinges on rapeseed and sunflower harvests in southwestern France. Single-source vulnerability runs through specialized curing-agent producers in the Rhine corridor. Distribution runs through bulk tanker deliveries to integrated manufacturers alongside drum and cartridge formats for maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France adhesives market sits in a cyclical recovery phase as automotive production normalization and construction renovation waves restore volume growth after prior-period destocking.
For Market Incumbents: Pre-empt margin erosion in commodity hot melts by securing captive bio-polyol supply through backward integration into regional oleochemical processors or long-term offtake with Provence-based producers. Accelerate REACH dossier preparation for novel low-VOC chemistries to compress the 18-36 month registration timeline that delays product launches. Threat substitution from mechanical fastening in lightweight vehicle platforms demands structural bonding performance guarantees backed by dedicated technical centers near Lyon and Paris. For New Entrants and Emerging Players: Pursue the underpenetrated medical device bonding segment where ANSM biocompatibility standards create qualification barriers that favor specialized cyanoacrylate and silicone formulators. Target surgical instrument manufacturers in the Île-de-France corridor with rapid-cure platforms engineered for automated assembly lines. Go-to-market angle: partner with existing distribution networks serving hospital procurement rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier European specialists possessing niche aerospace or electronics expertise but lacking scale for integrated dispensing-system offerings. Long-term viability across the analysis window favors formulators with documented Scope 3 carbon footprints and Cradle-to-Cradle certification traction among construction and automotive OEMs. Signal to watch: consolidation of adhesive supplier panels by major French automotive OEMs into single-source bonding-system contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyol Production | Captures margin pools shifting from petroleum feedstocks under France's national low-carbon strategy. |
| REACH Registration Acceleration | Compresses product launch cycles for novel chemistries ahead of ECHA compliance deadlines. |
| Integrated Bonding System Partnerships | Aligns adhesive formulators with automated dispensing robotics vendors for electric vehicle battery assembly. |
| Medical Device Certification Investment | Positions suppliers for ANSM-regulated surgical instrument bonding as OEMs consolidate supplier panels. |
| Construction Renovation Channel Expansion | Captures mortar-adhesive hybrid demand from France's building energy retrofit mandates. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulator R&D directors, automotive OEM procurement managers, packaging converter operations heads, and construction contractor purchasing leads and refined through secondary validation. Sources included customs trade data for acrylic monomer and polyol imports, ECHA REACH registration databases, SEC filings from listed chemical conglomerates, and Cefic sector reports. Bottom-up volume estimates from end-use industry consumption patterns were triangulated against top-down market sizing from supplier revenue analysis.
Demand-supply balance modeling anchored forecast construction, with segmentation across product chemistry, application requirement, packaging format, and regional industrial cluster. CAGRs were derived from trend extrapolation of automotive lightweighting penetration rates, packaging line retrofit cycles, and construction renovation spend patterns. Key inputs included electric vehicle production forecasts for the Rhône-Alpes belt, ANSM regulatory timeline projections, and bio-based feedstock cost curves.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, agricultural commodity prices, or eurozone industrial confidence indices would shift the trajectory. Forecasts reflect documented assumptions regarding REACH implementation timelines and carbon border adjustment mechanisms. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
Brazil Adhesives Market