
 Mexico Sealants Market | 2026-2036
Mexico Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Sealants Market Outlook
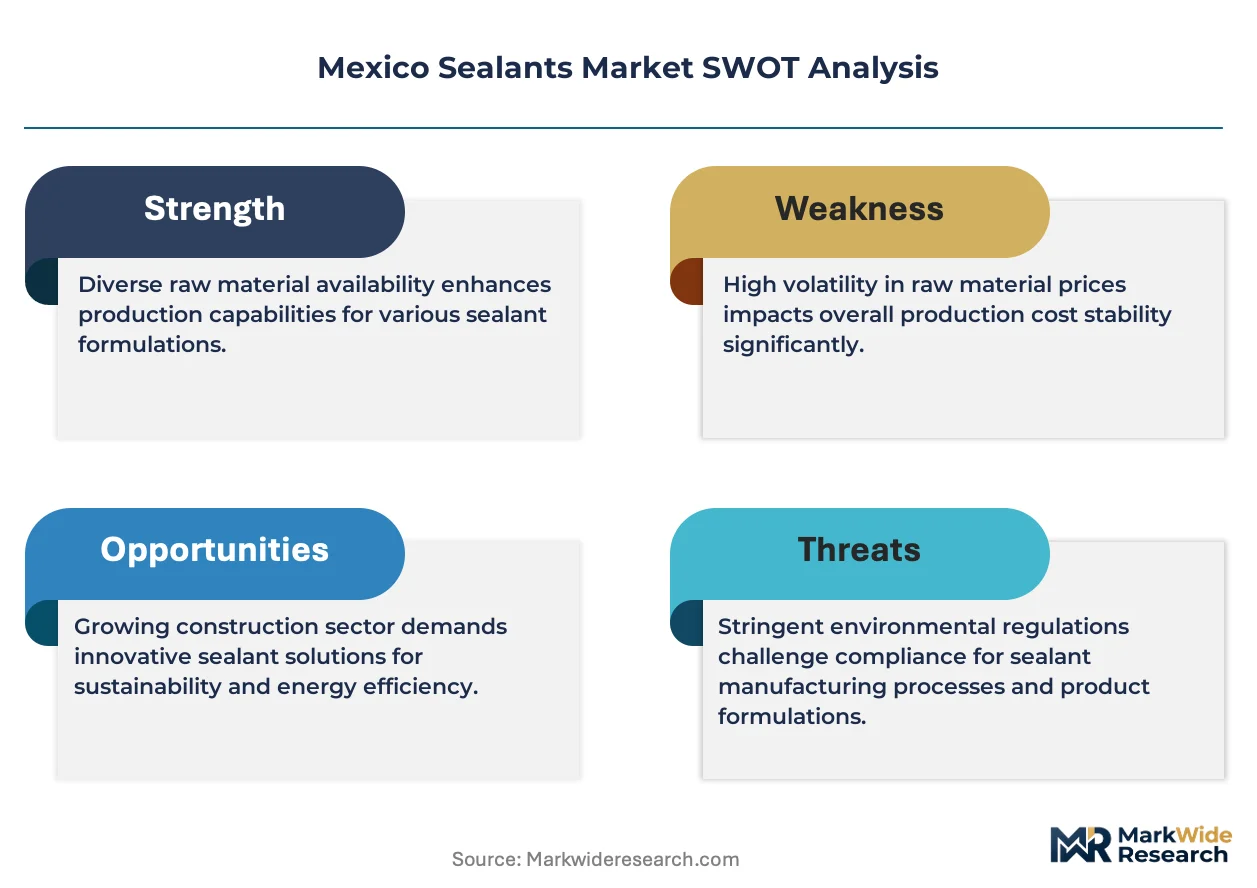
The Mexico sealants market is restructuring around a widening performance gap between specification-grade architectural systems and bulk construction commodities. Henkel AG & Co. KGaA leverages its adhesive-sealant technology portfolio to dominate premium facade and glazing applications. Sika AG anchors its position through localized manufacturing and strong specification relationships with Mexican engineering firms.
Sealants are elastomeric compounds formulated from silicone, polyurethane, acrylic, or polysulfide polymers that cure to form flexible, impermeable barriers; they typically achieve Shore A hardness of 15-50 and elongation at break exceeding 200% to accommodate joint movement in building envelopes and transportation assemblies. Silicone formulations lead commercial architecture due to superior UV resistance and 20-plus-year service life, while polyurethane competes aggressively in automotive underbody and marine sealing where paint compatibility and abrasion resistance command priority. Acrylic segments occupy the cost-driven residential waterproofing tier with thinner margin pools and shorter replacement cycles.
CONUEE energy efficiency standards and Mexico's NOM building codes shape product certification requirements for air infiltration and thermal bridging control. The Secretariat of Economy's metrology enforcement and PROFECO consumer protection oversight constrain informal sealant imports and substandard labeling practices. Stakeholders must monitor regulatory harmonization with USMCA technical barriers to trade provisions as North American supply chain integration deepens.
Market Dynamics
CONUEE energy efficiency standards and NOM building code updates are compressing specification windows, forcing formulators to recertify portfolios around thermal bridging metrics and air infiltration thresholds that now govern envelope assembly approvals.
Growth Catalysts
- CONUEE Efficiency Mandates:Updated building energy codes require continuous air barriers in commercial envelopes, expanding specification-grade silicone volumes for curtain wall and window-wall systems.
- Automotive Reshoring:OEM assembly expansion in Aguascalientes and Guanajuato generates demand for NVH-rated polyurethane sealants in underbody and seam-sealing applications.
- Silicone Technology Migration:20-plus-year service life expectations in high-rise glazing are displacing acrylic alternatives in Mexico City and Monterrey commercial towers.
Market Restraints
- Siloxane Feedstock Concentration:Specialty silicone precursor supply concentrates in Asian merchant markets, exposing Mexican formulators to freight and duty volatility on imported intermediates.
- Acrylic Substitution Ceiling:Cost-driven residential waterproofing segments resist specification upgrades, capping margin expansion in the largest volume tier by polymer type.
- PROFECO Enforcement Friction:Metrology and labeling compliance timelines delay product launches by 8-14 months for reformulated systems seeking NOM certification.
Strategic Opportunities
- Baja California Industrial Corridor:Medical device and aerospace manufacturing clusters near Tijuana create demand for cleanroom-rated sealants with low-VOC and ionic purity specifications.
- USMCA Technical Barrier Harmonization:Regulatory alignment with North American testing protocols reduces dual-certification costs for exporters serving integrated supply chains.
- Hybrid MS-Polymer Convergence:Silyl-modified polymer systems combining silicone durability with polyurethane paint compatibility are opening automotive refinish and marine maintenance segments.
Industry Challenges
- Formulation Chemistry Talent Gap:Mexican universities produce limited polymer science graduates with elastomer compounding expertise, forcing reliance on expatriate technical staff or foreign R&D support.
- Climate Chamber Certification Bottlenecks:Accelerated weathering validation for UV-resistant facade sealants requires outsourced testing to US or European facilities, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Sealants Market |
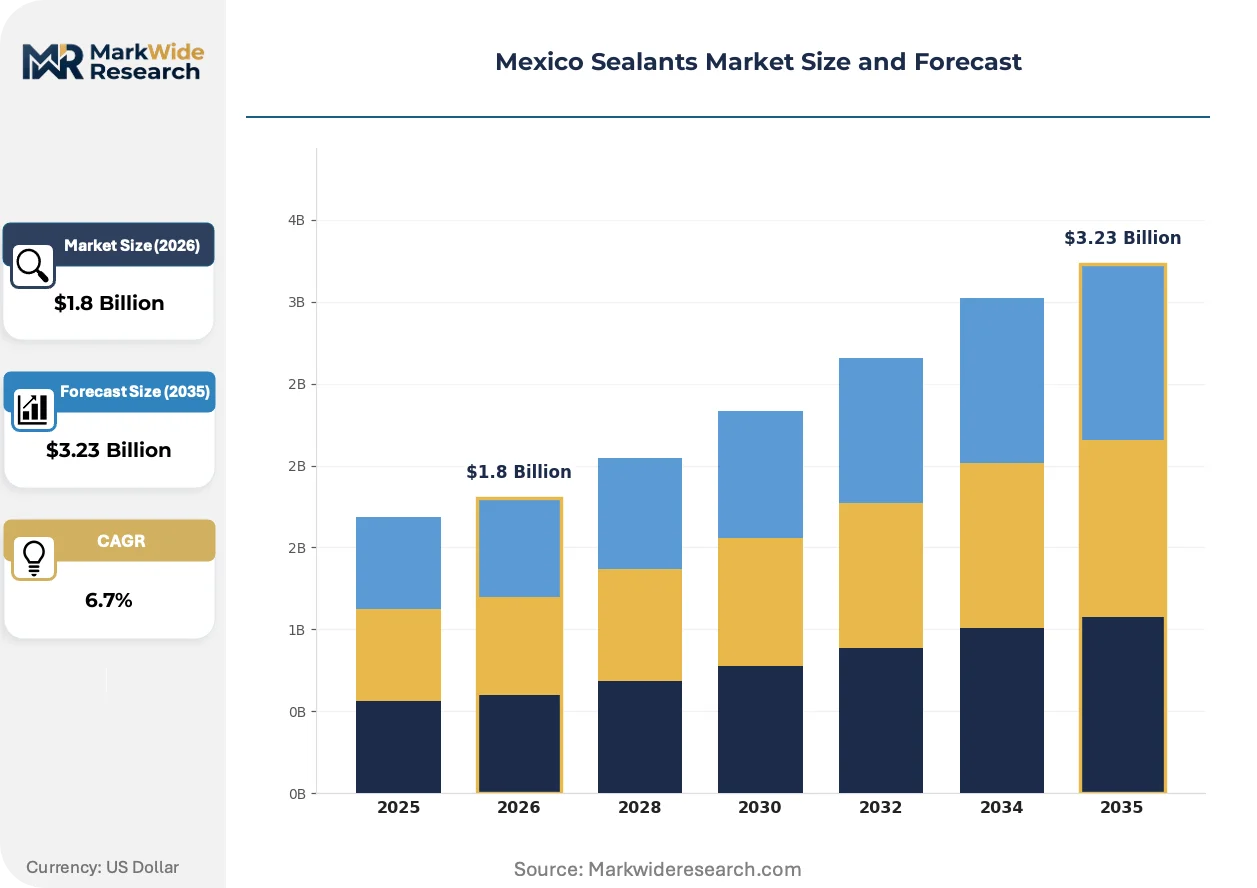
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Polysulfide End User: Construction, Automotive, Aerospace, Marine Application: Sealing, Bonding, Insulation, Coating Distribution Channel: Direct Sales, Distributors, Retail, E-commerce |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, RPM International Inc., Dow, Illinois Tool Works Inc., Arkema Group, Wacker Chemie AG, Soudal Holding N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Sealants Market Strategic Shifts
Formulation platforms are fragmenting around performance-specialized architectures that sacrifice economies of scale for specification compliance in regulated envelope and transportation applications.
Hybrid silyl-terminated polyether systems are modularizing traditional silicone-polyurethane boundaries by delivering paintable surfaces with 25-year durability guarantees. Tier-one automotive suppliers in Queretaro and Puebla are adopting these platforms for visible seam sealing where color match and weathering resistance coexist as requirements. The technology is modularizing procurement categories that previously forced buyers to choose between incompatible performance attributes.
CONUEE's updated Norma Oficial Mexicana for envelope thermal performance now mandates blower-door testing on commercial assemblies above four stories, creating de facto certification barriers for uncertified sealant brands. The Secretariat of Economy has aligned PROFECO enforcement with these standards, removing substandard imports from distribution channels. High-rise developers in Mexico City now require manufacturer-signed compliance letters as a condition of specification.
Buyer concentration among national construction conglomerates is compressing distributor margins and shifting technical support burdens upstream to formulators. Direct specification relationships with engineering firms are displacing traditional hardware channel influence in commercial envelope procurement. This pattern concentrates most intensely in Monterrey, where Grupo Cementos de Chihuahua and Cemex procurement offices maintain centralized sealant qualification lists.
Mexico Sealants Market Segmentation
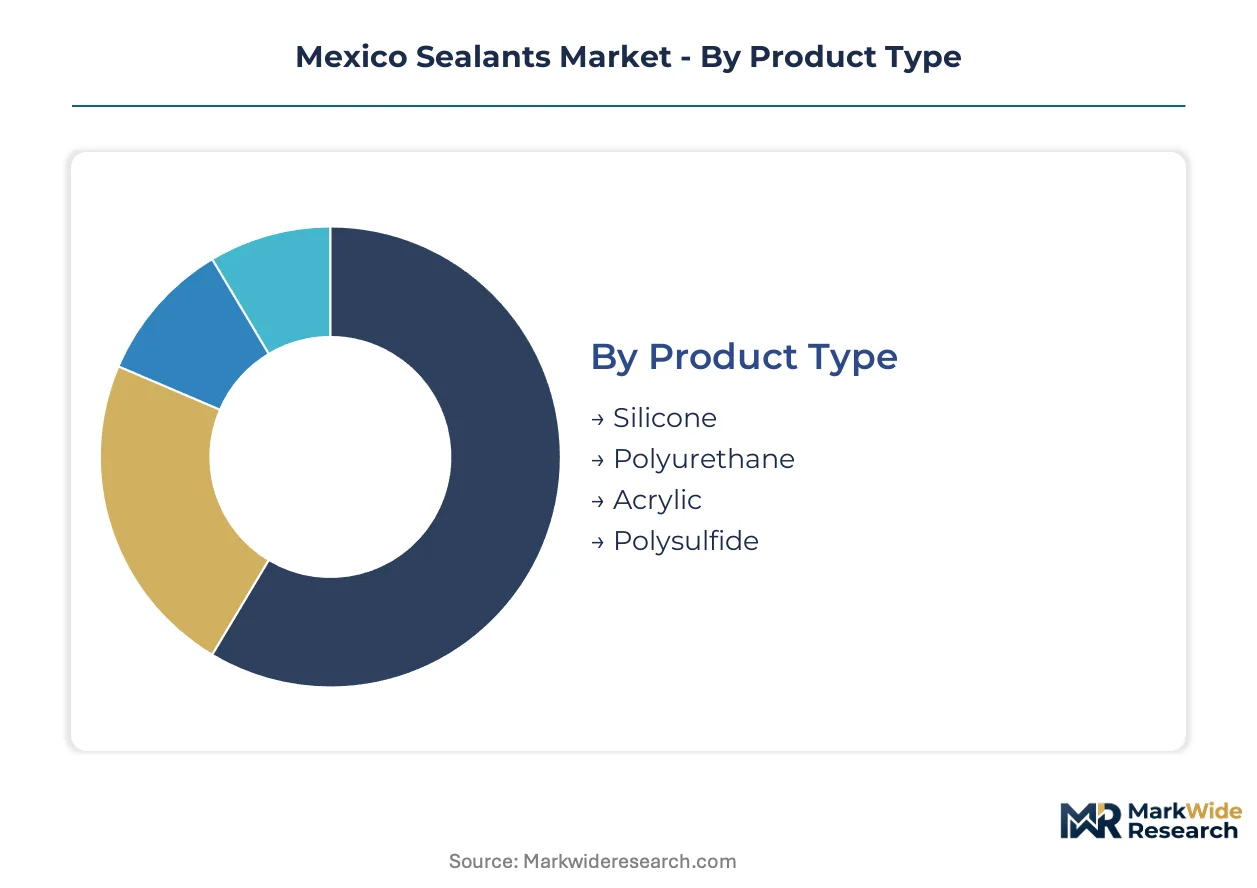
Sealant procurement in Mexico stratifies sharply across performance tiers, with specification-grade architectural systems commanding multiples over bulk construction commodities. Polymer chemistry and certification grade determine margin pools more than volume scale.
Product Type:
Silicone formulations demand the heaviest capital investment in precursor synthesis and cleanroom compounding infrastructure.
- Silicone:Formulated from siloxane polymers with UV-stable crosslinking chemistry, these systems achieve Shore A hardness of 20-40 and elongation exceeding 300%. Demand concentrates in Mexico City high-rise glazing where CONUEE thermal performance mandates require 20-plus-year service life guarantees.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture reaction to form paint-compatible elastomers with superior abrasion resistance. Automotive assembly plants in Aguascalientes and Guanajuato specify these for underbody seam sealing where NVH damping and corrosion protection converge.
- Acrylic:Water-based emulsions serve cost-sensitive residential waterproofing with shorter replacement cycles and thinner margin structures.
- Polysulfide:Liquid polymer systems deliver fuel resistance and low-temperature flexibility for specialized transportation and industrial gasketing applications.
Most installed capacity flows through silicone. Expansion is steepest in polyurethane.
End User:
Customer type determines technical support intensity and specification channel strategy.
- Construction:Envelope assemblies in commercial towers and infrastructure projects drive specification-grade volumes. Monterrey and Mexico City developers now require manufacturer-signed NOM compliance letters as a condition of procurement.
- Automotive:OEM assembly expansion generates demand for NVH-rated systems in body-in-white and final trim applications. Tier-one suppliers in Queretaro and Puebla dominate procurement.
- Aerospace:Baja California clusters near Tijuana require cleanroom-rated sealants with ionic purity specifications for fuel tank and pressure boundary sealing.
- Marine:Coastal maintenance yards in Veracruz and Mazatlan specify polysulfide and hybrid systems for hull sealing and deck waterproofing.
Construction absorbs the largest volume share. Aerospace is climbing the fastest on a percentage basis.
Application:
Functional use case dictates cure chemistry, application equipment, and labor skill requirements.
- Sealing:Joint-filling applications in curtain wall and window-wall systems demand movement accommodation exceeding 25% of joint width. CONUEE blower-door testing mandates now govern commercial envelope approvals above four stories.
- Bonding:Structural glazing and panel attachment require tensile lap shear strengths above 1.0 MPa with modulus matched to substrate thermal expansion coefficients.
- Insulation:Thermal and acoustic barrier applications in building envelopes and transportation assemblies prioritize low thermal conductivity and closed-cell morphology.
- Coating:Protective film-forming applications in industrial maintenance deliver chemical resistance through build thickness and crosslink density control.
Sealing commands the greatest polymer volume. Bonding is gaining share fastest as structural glazing adoption accelerates.
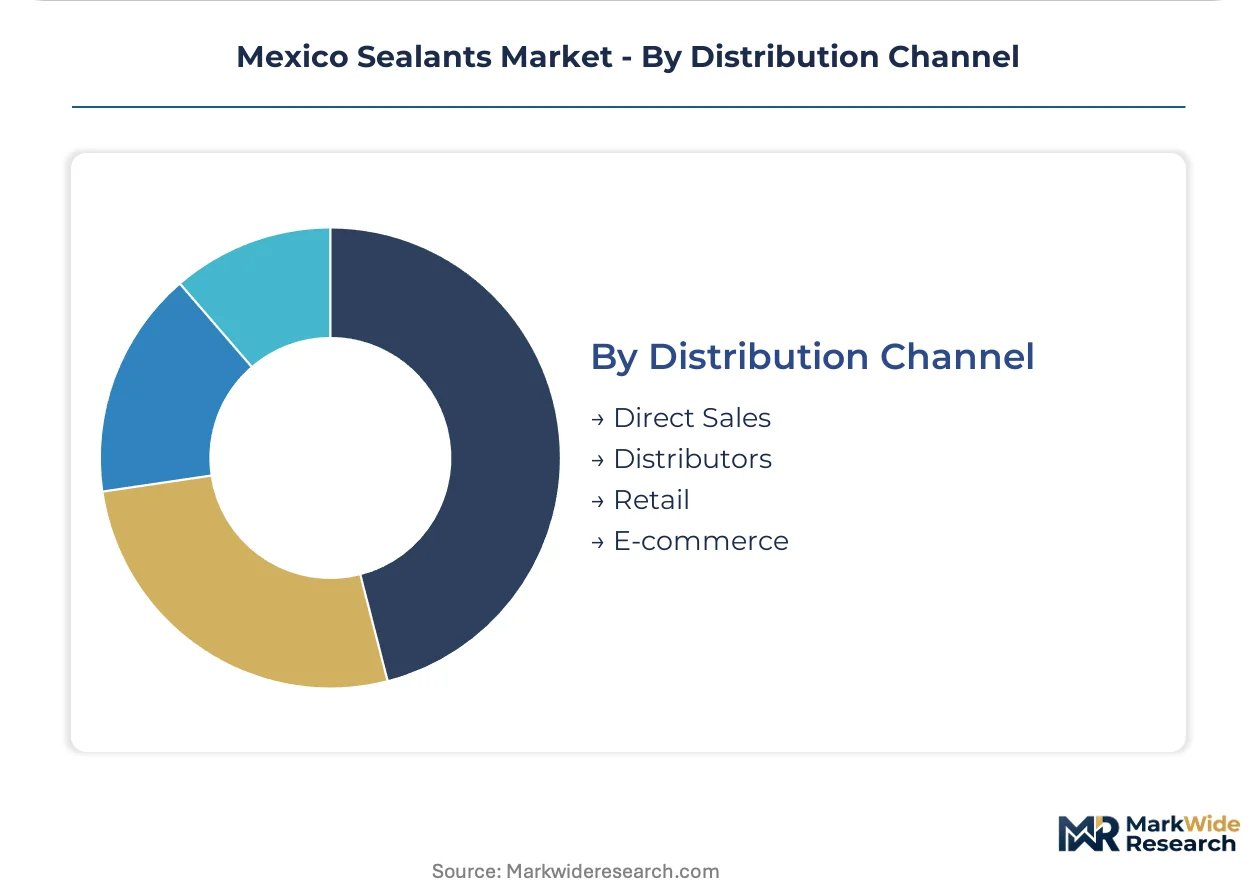
Distribution Channel:
Channel structure reflects buyer concentration and technical service requirements.
- Direct Sales:National construction conglomerates and automotive OEMs negotiate frame contracts with formulators for specification-grade volumes. Grupo Cementos de Chihuahua and Cemex maintain centralized sealant qualification lists.
- Distributors:Regional construction supply houses serve mid-tier contractors with inventoried commodity grades and basic technical support.
- Retail:Home improvement chains and hardware stores reach residential waterproofing and DIY maintenance segments with acrylic and economy silicone offerings.
- E-commerce:Digital procurement channels are emerging for standardized SKU replenishment in industrial maintenance and small-contractor segments.
Distributors handle the greatest transaction volume. Direct sales is expanding most quickly as buyer concentration intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Mexico's sealant demand concentrates in high-rise commercial corridors, Brazil's construction chemicals sector distributes more evenly across residential and industrial applications. This structural difference shapes procurement patterns throughout Latin America.
Mexico City Metro
High-rise glazing and curtain wall installations drive specification-grade silicone volumes as CONUEE energy codes mandate continuous air barriers. The Secretariat of Economy enforces NOM building standards through PROFECO oversight, removing non-compliant imports from distribution channels. Polanco and Santa Fe business districts anchor demand for 20-plus-year service life guarantees in envelope assemblies.
Nuevo León
Monterrey's cement conglomerates centralize sealant procurement through qualified vendor lists that privilege direct manufacturer relationships. Grupo Cementos de Chihuahua and Cemex procurement offices require signed NOM compliance letters before specification approval. The metropolitan area's commercial tower pipeline exceeds other northern Mexican states combined.
Jalisco
Automotive tier-one suppliers in Guadalajara generate demand for NVH-rated polyurethane systems in body-in-white applications. The state's industrial parks attract OEM assembly expansion from Aguascalientes spillover. Jalisco's technical workforce supports localized compounding operations for paint-compatible sealant formulations.
Bajío Region
Queretaro and Guanajuato automotive clusters specify hybrid silyl-modified polymers for visible seam sealing where color match and weathering resistance converge. The region's aerospace maintenance facilities add demand for fuel-resistant polysulfide systems. Industrial corridor development outpaces envelope construction in sealant consumption growth rates.
Northern Border States
Baja California's medical device and aerospace manufacturing near Tijuana requires cleanroom-rated sealants with low-VOC and ionic purity specifications. USMCA technical barrier harmonization reduces dual-certification costs for suppliers serving integrated North American supply chains. Tijuana and Mexicali assembly plants prioritize regulatory alignment with California environmental standards.
Mexico Sealants Market Competitive Environment
Top-tier vendors anchor specification-grade architectural systems, while commodity-grade residential suppliers compete on price and distribution reach. The market structure stratifies sharply around certification grade rather than volume scale. Three archetypes dominate: multinational chemical conglomerates with adhesive-sealant portfolios, specialized construction chemical formulators with localized manufacturing, and regional distributors with technical service capabilities. Competitive moves concentrate on direct specification relationships with engineering firms and backward integration into siloxane precursor supply.
Within the multinational tier, Henkel AG & Co. KGaA and Sika AG exemplify divergent approaches to market position. The Düsseldorf-based conglomerate leverages cross-technology portfolios spanning adhesives and sealants, while the Swiss specialist anchors through manufacturing proximity and engineering firm relationships. Dow represents the integrated chemical producer archetype with upstream control over siloxane feedstocks. These three occupy positions that span premium facade applications through automotive assembly supply, with each representing a distinct competitive vector in procurement channel strategy.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| RPM International Inc. |
| Dow |
| Illinois Tool Works Inc. |
| Arkema Group |
| Wacker Chemie AG |
| Soudal Holding N.V. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap formulators in Mexico's construction chemicals sector anchor supply discipline through long-held distributor relationships and conservative working capital practices that buffer pricing volatility. Their embedded position in regional hardware channels constrains multinational pricing power while insulating them from raw material cost spikes through informal hedging arrangements.
Pricing Analysis
Bundled technical certification services now separate specification-grade silicone procurement from unbundled commodity acrylic transactions. Three-tier pricing structure across premium, standard, and economy levels reflects NOM certification grade and manufacturer-signed compliance letter availability. Price differentiation hinges on CONUEE thermal performance validation and direct engineering firm relationships. Cost compression in the acrylic residential tier is intensifying because informal imports circumvent PROFECO metrology enforcement. National construction conglomerates exhibit lowest price sensitivity; DIY retail channels show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Monterrey and Mexico City operate hub-and-spoke patterns that consolidate inventory risk for specification-grade portfolios. Siloxane precursor supply concentrates in China, South Korea, and Germany, exposing Mexican formulators to freight volatility on imported intermediates. Raw material dependencies center on siloxane polymers, isocyanate prepolymers, and acrylic emulsions. Single-source vulnerability in Asian merchant siloxane markets threatens formulation continuity. Distribution runs through direct sales to national conglomerates, with distributor networks serving mid-tier contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Mexico's sealants sector rests on specification-grade silicone displacement of acrylic alternatives and CONUEE-driven certification barriers that compress price competition in premium tiers.
For Market Incumbents: Cement specification relationships with engineering firms through NOM compliance letter programs and localized climate chamber investments. Defend against hybrid silyl-modified polymer substitution by accelerating paint-compatible silicone R&D. Prioritize backward integration into siloxane precursor supply to reduce Asian merchant market exposure. For New Entrants and Emerging Players: The premium-economy price-point gap in automotive NVH-rated polyurethane creates white-space opportunity. Target the Baja California medical device corridor with cleanroom-rated low-VOC formulations. Enter through USMCA-aligned certification pathways that reduce dual-compliance costs for North American supply chain integration. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with technical service capabilities but limited direct specification access. Long-term viability favors formulators with captive siloxane supply or hybrid polymer patent positions. Monitor CONUEE enforcement intensity as inflection signal for specification-grade margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Precursors | Captive supply from Dow or Wacker Chemie AG reduces Asian merchant market freight exposure. |
| NOM Certification Acceleration | PROFECO-aligned compliance timelines compress competitive windows for imported alternatives. |
| Hybrid MS-Polymer Capacity Addition | Silyl-modified systems open automotive refinish and marine maintenance specification channels. |
| Direct Sales Force Expansion | Grupo Cementos de Chihuahua and Cemex procurement offices require manufacturer relationships. |
| Cleanroom Compounding Investment | Baja California aerospace clusters demand ionic purity specifications for fuel tank sealing. |
Study Parameters
Direct dialogue with plant managers at Queretaro automotive tier-one suppliers, procurement leads at Cemex and Grupo Cementos de Chihuahua, distribution channel partners in Monterrey, and technical R&D directors at hybrid polymer formulators grounded qualitative findings. Secondary validation drew from Mexican customs trade data, CONUEE energy efficiency filings, PROFECO enforcement releases, and SEC 10-K disclosures from multinational chemical conglomerates. Bottom-up volume estimates triangulated against top-down construction spending projections.
Bottom-up modeling segmented demand by polymer chemistry, certification grade, end-use industry, and regional production hub across the analysis window. CAGRs derived from regression against construction permit data, automotive production forecasts, and energy code adoption curves. Forecast inputs incorporated CONUEE blower-door testing mandate phase-ins and USMCA technical barrier harmonization timelines.
Caveats apply where PROFECO enforcement intensity, siloxane precursor tariff shifts, or automotive reshoring velocity could materially shift the outlook. Forecasts reflect documented assumptions around regulatory adoption and supply chain integration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
US Adhesives and Sealants Market