
 Industrial Wood Adhesives Market | 2026-2036
Industrial Wood Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wood Adhesives Market Insights
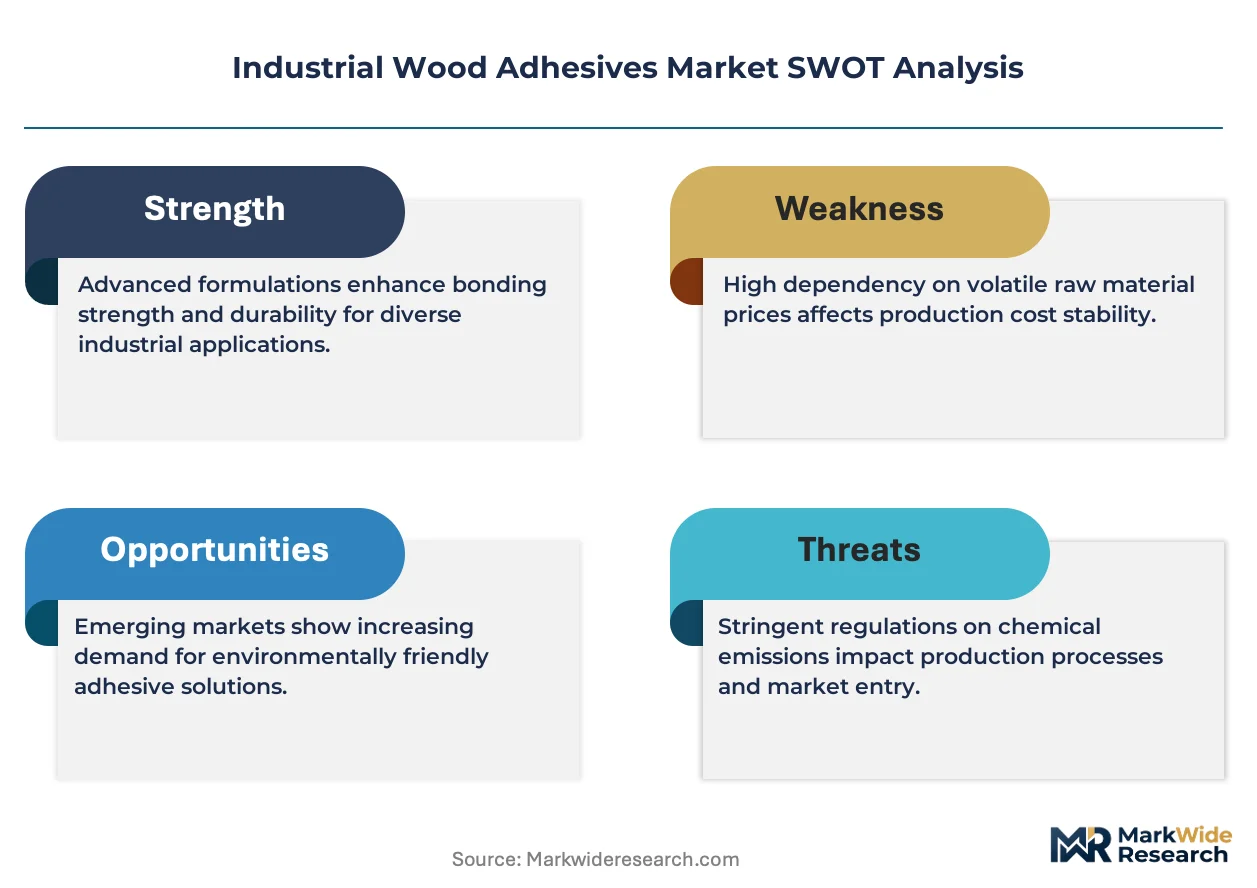
A shift from single-source petrochemical supply toward multi-source bio-feedstock procurement is hardening across the adhesive value chain. Henkel leverages its European resin compounding network to secure tall-oil derivatives from Nordic pulp mills. BASF sustains backward integration into methanol-to-formaldehyde pathways at its Ludwigshafen complex. Jowat competes through specialized hot-melt formulations for edgebanding applications in German furniture manufacturing.
Industrial wood adhesives are synthetic or bio-based bonding agents formulated from polyvinyl acetate emulsions, polyurethane prepolymers, epoxy resins, or ethylene-vinyl acetate hot melts, typically cured through moisture activation, thermal energy, or chemical hardeners to create load-bearing joints in engineered wood products. Their primary purpose is to transfer structural stresses across bonded interfaces in plywood, oriented strand board, laminated veneer lumber, and cross-laminated timber assemblies. PVA dominates volume in furniture and cabinetry assembly due to cost efficiency and ease of application, while polyurethane captures margin in structural mass timber where moisture resistance and gap-filling strength justify premium positioning. Epoxy remains a niche but high-value segment in specialty flooring and architectural millwork requiring exceptional durability and chemical resistance.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood products in the United States, compelling adhesive suppliers to certify no-added-formaldehyde formulations or ultra-low-emitting resins. ECHA REACH restrictions on isocyanates and GB standards in China for indoor air quality collectively shape product development roadmaps and market access conditions across major manufacturing geographies. Stakeholders must monitor evolving bio-based feedstock certification schemes and building code approvals for mass timber construction as these frameworks increasingly determine which adhesive chemistries qualify for green building credits and structural engineering specifications.
Market Dynamics
Mass timber construction codes are rewriting specification requirements across commercial building segments, forcing adhesive formulators to requalify products for structural load-bearing certifications while simultaneously retooling supply chains for bio-based feedstock security.
Growth Catalysts
- EPA TSCA Title VI enforcement:Composite wood product regulations in the United States mandate ultra-low formaldehyde emissions, accelerating no-added-formaldehyde adhesive adoption in plywood and oriented strand board manufacturing.
- Cross-laminated timber engineering:Commercial architects specify structural polyurethane systems for high-rise mass timber projects requiring moisture resistance and gap-filling strength under cyclic loading conditions.
- Stuttgart-Munich manufacturing corridor:German CLT production clusters concentrate demand for specialized hot-melt and polyurethane formulations serving engineered wood fabricators.
Market Restraints
- Tall-oil fatty acid supply concentration:Nordic pulp mill dependency creates feedstock vulnerability for European bio-based adhesive producers seeking alternatives to petrochemical resins.
- Isocyanate handling restrictions:ECHA REACH workplace exposure limits on methylene diphenyl diisocyanate increase compliance costs and operational complexity for polyurethane adhesive manufacturing.
- Legacy urea-formaldehyde substitution economics:Cost-sensitive furniture manufacturers in emerging markets retain low-emission conventional systems despite performance limitations in humid environments.
Strategic Opportunities
- GB standard indoor air quality alignment:Chinese building code evolution toward stricter formaldehyde limits creates qualification pathways for certified low-emission adhesive technologies in domestic engineered wood production.
- Hot-melt reactive polyurethane advancement:Furniture edgebanding and assembly applications adopt moisture-curing PUR systems delivering superior heat resistance compared to conventional ethylene-vinyl acetate alternatives.
- Architectural millwork specification premium:Specialty flooring and high-end interior installations seek epoxy-based formulations offering exceptional chemical resistance and durability for commercial hospitality environments.
Industry Challenges
- Mass timber structural certification timelines:Building code approval processes for new adhesive systems in cross-laminated timber and glued laminated timber applications extend 18-36 months, delaying market entry.
- Bio-feedstock quality standardization:Variable lignin and tannin content in regional biomass sources complicates adhesive performance consistency and batch-to-batch reliability for formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wood Adhesives Market |
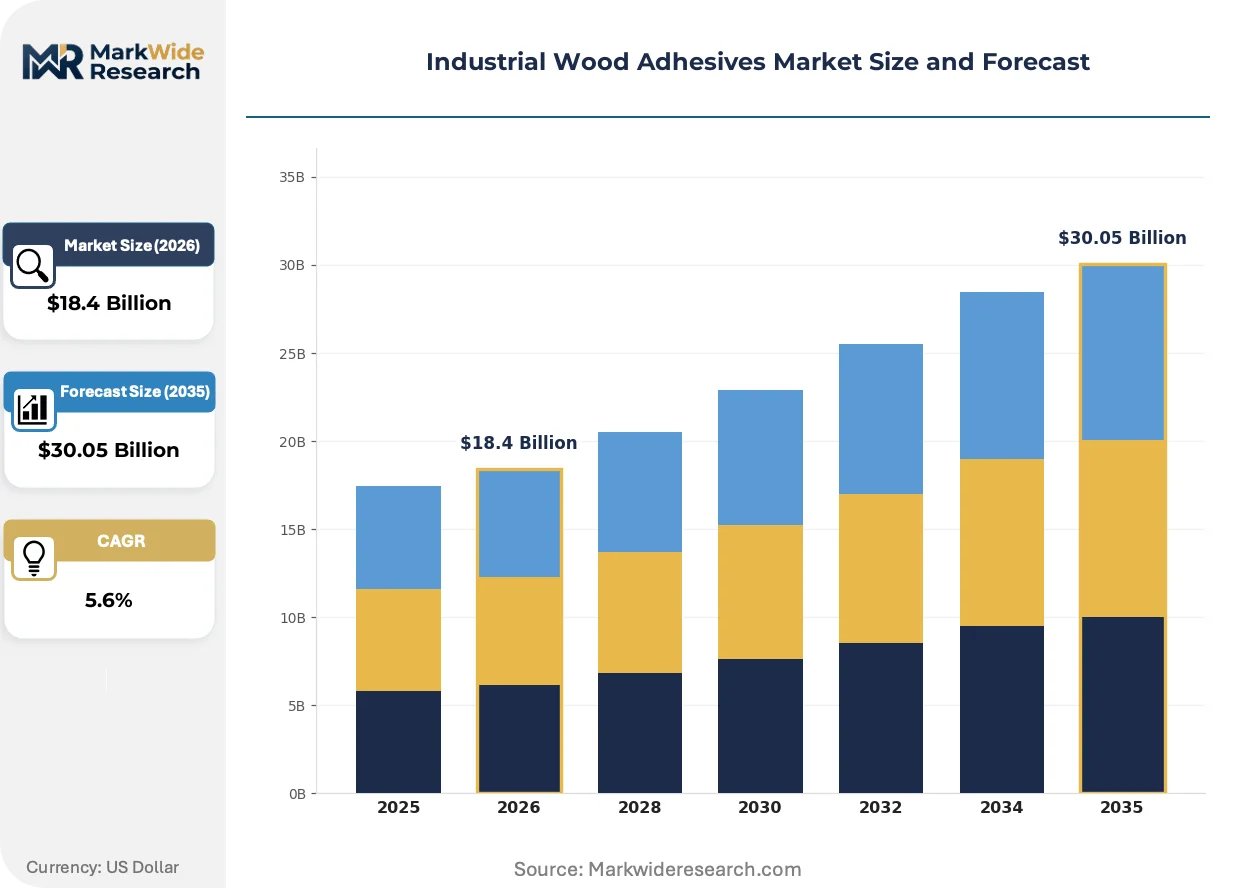
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.05 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVA, Polyurethane, Epoxy, Hot Melt Application: Furniture, Flooring, Cabinetry, Packaging End User: Manufacturers, Carpentry, Construction, Retail Form: Liquid, Granular, Paste, Powder |
| Companies Covered | 3M, Arkema, H.B. Fuller, BASF, Ashland, Henkel, Jowat, Pidilite Industries, Sika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wood Adhesives Market Trends and Innovations
Digital manufacturing integration and feedstock traceability systems are reconfiguring how adhesive specifications travel from formulation labs to fabrication floors, compressing qualification cycles while hardening sustainability credentials.
Decentralized bio-refining technology is decentralizing lignin extraction and modification capabilities, enabling regional adhesive compounders to process locally sourced forestry residues into binding agents without centralized petrochemical infrastructure. Mid-sized engineered wood producers in Scandinavia and the Pacific Northwest adopt containerized pyrolysis units to generate tailored bio-oil fractions. This distributed model reduces transportation costs for bulky raw materials while allowing customization of adhesive properties for specific climate and end-use requirements.
REACH authorization procedures for diisocyanate substances are compelling polyurethane adhesive manufacturers to invest in closed-loop application systems and worker exposure monitoring technologies. Industrial hygiene compliance costs are restructuring competitive economics, favoring formulators with integrated safety engineering capabilities over commodity suppliers. German and French fabrication facilities lead implementation of automated dispensing and curing equipment to satisfy ECHA-mandated industrial user training protocols.
Specification-driven procurement now dominates mass timber project development, with architects and structural engineers demanding third-party certified environmental product declarations before adhesive approval. This behavioral shift displaces traditional price-first purchasing in commercial construction verticals. Nordic and North American project pipelines exhibit the strongest certification adherence, where green building rating systems mandate full supply chain disclosure for structural bonding agents.
Industrial Wood Adhesives Market Segmentation
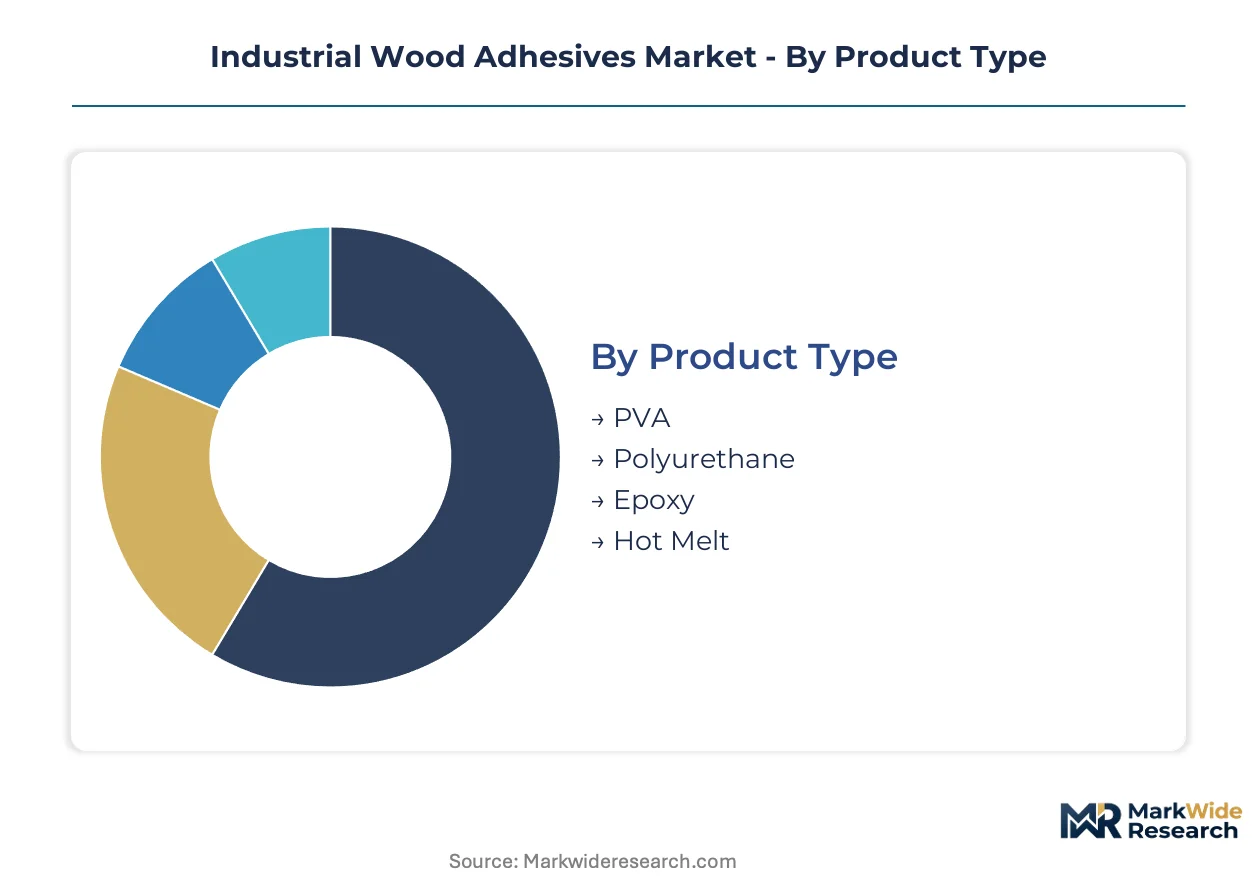
Adhesive selection in engineered wood manufacturing hinges on balancing performance specifications against application economics. Each segment category reveals distinct procurement patterns where cost-sensitive volume applications diverge sharply from premium structural requirements.
Product Type:
Polyvinyl acetate dominates total volume while polyurethane commands structural premium positioning.
- PVA:Water-based emulsion systems formulated from vinyl acetate monomer polymerization deliver rapid set times and easy cleanup for non-structural bonding. Furniture manufacturers in Germany and China specify PVA for flat lamination and edge gluing where humidity exposure remains limited. Cost efficiency and sprayable application methods sustain its grip on high-volume cabinetry assembly.
- Polyurethane:Moisture-curing prepolymer systems with isocyanate-terminated backbones penetrate wood fibers to create gap-filling bonds with exceptional creep resistance. Mass timber fabricators around Stuttgart and Munich specify structural polyurethane for cross-laminated timber panels requiring cyclic load certification. Premium pricing reflects ECHA REACH compliance investments and specialized dispensing equipment.
- Epoxy:Two-part thermosetting systems combining bisphenol-A resins with amine hardeners achieve chemical resistance for specialty flooring installations.
- Hot Melt:Thermoplastic ethylene-vinyl acetate or reactive polyurethane formulations enable rapid automated edgebanding on German furniture production lines.
Mature deployment sits with PVA in conventional furniture manufacturing. Newer deployment is concentrated in polyurethane systems for engineered structural timber.
Application:
Specification intensity varies dramatically between decorative interior finishes and load-bearing structural assemblies.
- Furniture:Assembly operations demand adhesives balancing open assembly time with clamp-free handling strength. German mid-market manufacturers prioritize hot-melt systems for frame construction while premium producers specify PVA variants with enhanced moisture resistance for kitchen and bathroom cabinetry. EPA TSCA Title VI certification requirements now filter adhesive selection across export-oriented production.
- Flooring:Engineered hardwood and laminate installations require adhesives with exceptional dimensional stability under seasonal humidity cycling. Reactive polyurethane systems penetrate oak and maple substrates to prevent telegraphing through wear layers. Commercial hospitality specifications in Nordic markets increasingly mandate epoxy-based formulations for chemical resistance in healthcare and food service environments.
- Cabinetry:Face-frame and box construction favors PVA emulsions with fast tack development for high-speed assembly lines.
- Packaging:Corrugated pallet and crate manufacturing utilizes low-cost dextrin and starch-based alternatives for non-structural containment.
Specification complexity clusters in flooring. Volume concentration remains heaviest in furniture assembly operations.
End User:
Procurement sophistication separates integrated manufacturing operations from fragmented installation trades.
- Manufacturers:Engineered wood producers operate centralized adhesive procurement with technical qualification protocols. Cross-laminated timber fabricators in the Stuttgart-Munich corridor demand batch-to-batch consistency certificates and environmental product declarations. Integrated safety engineering capabilities influence supplier selection as ECHA industrial user training mandates reshape purchasing criteria.
- Carpentry:Custom millwork shops prioritize shelf-stable formulations with extended open times for complex glue-ups. German architectural millwork specialists specify epoxy systems for heritage restoration requiring reversible bonding and chemical compatibility with historic substrates.
- Construction:On-site mass timber erection crews specify single-component moisture-curing systems compatible with weather-exposed installation conditions.
- Retail:Consumer-grade wood glues emphasize convenience packaging and simplified application instructions for DIY furniture repair.
Technical qualification depth distinguishes manufacturer procurement. Operational flexibility dominates carpentry purchasing decisions.
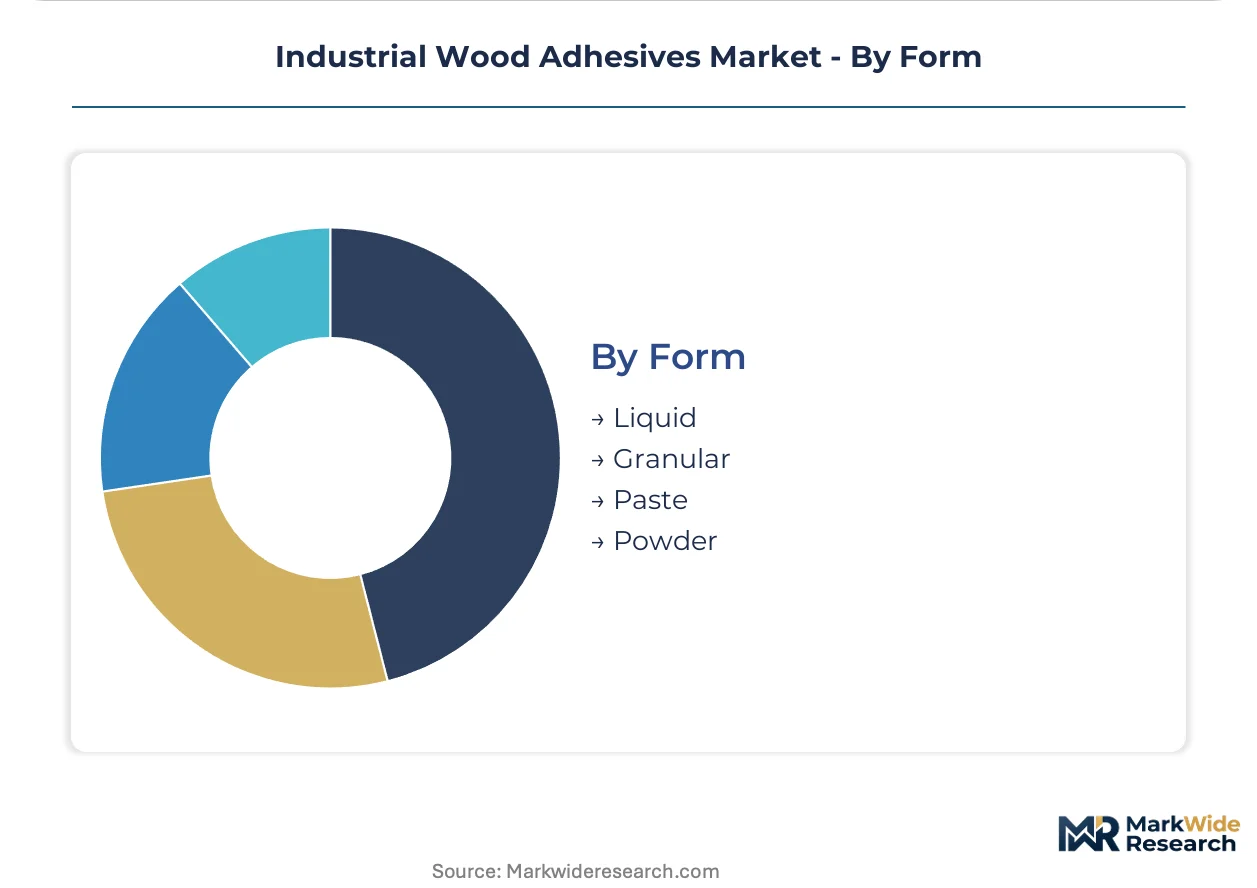
Form:
Physical state determines application equipment requirements and supply chain logistics configurations.
- Liquid:Pumpable emulsions and solvent-based systems enable spray, roll, and bead application across automated production lines. German plywood manufacturers utilize high-solids PVA liquids to minimize drying energy consumption. Bulk tanker deliveries reduce packaging waste for high-volume consumers with dedicated storage infrastructure.
- Granular:Urea-formaldehyde and phenol-formaldehyde resins in prilled form dissolve in heated water for particleboard and medium-density fiberboard manufacturing. Nordic producers favor granular delivery for centralized resin kitchen operations with precise formulation control.
- Paste:Thixotropic formulations resist sag on vertical surfaces during assembly clamping.
- Powder:Dry-mix polyvinyl alcohol and dextrin derivatives enable just-in-time reconstitution for remote construction sites with limited storage.
Liquid systems anchor continuous manufacturing operations. Powder and paste forms serve distributed construction and repair applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tall-oil fatty acid availability from Nordic pulp mills anchors European bio-based adhesive production, while methanol-to-formaldehyde infrastructure in Ludwigshafen sustains German petrochemical resin supply. Mass timber construction codes and formaldehyde emission regulations are reshaping procurement patterns across four distinct national markets.
Germany
Cross-laminated timber fabrication around Stuttgart and Munich concentrates demand for structural polyurethane and specialized hot-melt formulations. ECHA REACH restrictions on isocyanate workplace exposure compel adhesive manufacturers to invest in closed-loop dispensing systems and industrial hygiene compliance. The Stuttgart-Munich corridor hosts Europe's densest cluster of engineered wood producers, with fabricators demanding batch-to-batch consistency certificates and environmental product declarations for mass timber projects.
United States
Commercial architects specify structural polyurethane systems for high-rise mass timber developments requiring moisture resistance and cyclic load certification. EPA TSCA Title VI enforcement mandates ultra-low formaldehyde emissions in composite wood products, accelerating no-added-formaldehyde adhesive adoption across plywood and oriented strand board manufacturing. Pacific Northwest producers deploy containerized pyrolysis units to process locally sourced forestry residues into tailored bio-oil adhesive fractions.
China
GB standard evolution toward stricter indoor air quality limits creates qualification pathways for certified low-emission adhesive technologies in domestic engineered wood production. Furniture manufacturers in emerging markets retain cost-sensitive conventional systems despite performance limitations, though coastal provinces increasingly specify certified formulations for export-oriented production. Yangtze River Delta fabricators face mounting pressure to align with European and North American emission standards for cross-border supply chains.
Sweden
Nordic pulp mills supply tall-oil derivatives to European adhesive compounders seeking alternatives to petrochemical resins, though feedstock concentration creates supply vulnerability. Mid-sized engineered wood producers adopt decentralized bio-refining technology to extract and modify lignin from regional forestry residues. Scandinavian project pipelines exhibit the strongest environmental product declaration adherence, where green building rating systems mandate full supply chain disclosure for structural bonding agents.
Industrial Wood Adhesives Market Competitive Landscape
Global majors compete with regional champions across formulation specialization and feedstock security, producing a tiered structure where integrated chemical conglomerates face agile national compounders. Market concentration clusters around adhesive categories rather than geographic boundaries, with structural polyurethane and bio-based segments attracting divergent competitive sets. Three archetypes dominate: petrochemical-integrated resin producers, bio-feedstock specialists leveraging Nordic pulp partnerships, and application-focused formulators serving furniture edgebanding niches. Capacity expansion in mass timber-certified systems and strategic partnerships for tall-oil supply security represent the dominant competitive moves.
Among diversified chemical conglomerates, BASF anchors the petrochemical-integrated tier with captive methanol-to-formaldehyde pathways at its Ludwigshafen complex. Henkel occupies a position bridging global scale and regional bio-feedstock integration, leveraging European resin compounding networks to secure tall-oil derivatives. Jowat exemplifies the specialization archetype, with its Jowat SE structure reflecting concentrated focus on adhesive systems rather than diversified materials portfolios. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| 3M |
| Arkema |
| H.B. Fuller |
| BASF |
| Ashland |
| Henkel |
| Jowat |
| Pidilite Industries |
| Sika |
| Others |
Pricing and Supply Chain Analysis
Mass timber fabricators in the Stuttgart-Munich corridor command project-based contract pricing with environmental product declaration bundling, while furniture manufacturers negotiate spot-market PVA volumes with unbundled technical service. This buyer-archetype concentration splits the market between specification-driven premium anchoring and cost-sensitive commodity procurement.
Pricing Analysis
Warranty-backed performance guarantees and certified emission compliance are bundled into structural polyurethane contracts for CLT applications, whereas standard furniture-grade PVA sells unbundled with minimal technical support. Three-tier pricing structure across premium structural certification, standard industrial grade, and economy furniture assembly separates adhesive tiers by REACH compliance investment and batch testing rigor. Pricing pressure stems from tall-oil feedstock volatility as Nordic pulp mill supply tightens. Furniture exporters in China exhibit highest price sensitivity, while German mass timber engineers prioritize certification reliability over unit cost.
Supply Chain Analysis
Reverse-logistics for spent adhesive containers and curing equipment refurbishment flows through Henkel's European service network, creating circularity obligations that commodity suppliers avoid. Raw material supply concentrates in Germany for methanol-to-formaldehyde pathways, Sweden for tall-oil fatty acid derivatives, and China for vinyl acetate monomer feedstocks. Manufacturing draws from petrochemical naphtha streams, bio-refined lignin fractions, and isocyanate precursor chemicals. Single-source vulnerability sits with Nordic pulp mill tall-oil dependency for European bio-based formulations. Distribution runs through bulk tanker networks for liquid emulsions and regional compounding facilities for customized hot-melt systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as adhesive formulators pursue backward integration into bio-feedstock refining to secure tall-oil and lignin supply security against petrochemical volatility.
For Market Incumbents: Hedge against bio-feedstock concentration risk by securing long-term tall-oil offtake agreements with Nordic pulp mills or investing in decentralized pyrolysis capabilities. Defend structural polyurethane margins through closed-loop dispensing system integration that satisfies ECHA industrial user training mandates. Capacity expansion in mass timber-certified systems should prioritize the Stuttgart-Munich corridor where specification intensity is highest. For New Entrants and Emerging Players: Launch via specialty epoxy formulations targeting architectural millwork restoration and commercial hospitality flooring where certification barriers are lower than structural timber. White-space exists in containerized bio-refining equipment for mid-sized Scandinavian producers seeking localized lignin extraction. Target Chinese coastal provinces with EPA TSCA Title VI-compliant PVA systems for export-oriented furniture manufacturing. For Investors and Strategic Acquirers: The window for entry favors bio-feedstock specialists with secured Nordic pulp partnerships and established environmental product declaration portfolios. Long-term viability over the next decade hinges on mass timber building code expansion and REACH authorization timelines for diisocyanate substances. Monitor ECHA regulatory proceedings and CLT fabrication capacity announcements in Germany and the Pacific Northwest as inflection indicators for structural adhesive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstock | Secures tall-oil and lignin supply from Nordic pulp mills against petrochemical price volatility. |
| Mass Timber Certification Investment | Enables qualification for Stuttgart-Munich CLT fabricators demanding environmental product declarations. |
| Closed-Loop Dispensing Systems | Satisfies ECHA REACH industrial user training mandates for isocyanate handling compliance. |
| Long-Term Supply Agreement | Locks in vinyl acetate monomer streams from Chinese petrochemical producers for PVA cost stability. |
| Joint Venture | Combines German formulation expertise with Swedish bio-refining technology for regional lignin extraction. |
Research Methodology
Trade databases, chemical industry association filings, and customs import-export records formed the secondary backbone for supply chain mapping and feedstock flow analysis. Primary interviews with adhesive formulators, engineered wood procurement managers, and ECHA regulatory compliance officers were triangulated against secondary sources. Bottom-up volume estimates from CLT fabrication capacity and top-down value projections from chemical producer revenue disclosures were cross-validated to establish market sizing.
Historical trendline analysis of adhesive consumption per cubic meter of engineered wood output informed the projection framework across the analysis window. Segmentation modeling incorporated product chemistry, application intensity, end-user procurement sophistication, and physical form requirements. CAGRs were derived from elasticity-adjusted demand curves reflecting building code adoption rates and formaldehyde regulation enforcement timelines. Forecast inputs included mass timber construction permit data and REACH authorization status for diisocyanate substances.
Feedstock supply disruption, regulatory timeline acceleration, and building code revision delays are the dominant revision risks to forecast assumptions. Practitioners should monitor Nordic pulp mill capacity utilization, ECHA substance evaluation proceedings, and German CLT project pipeline announcements for early signals of demand inflection or supply constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Global Medical Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
United States Sealants Market