
 Active Metal Brazing (AMB) Paste Market | 2026-2036
Active Metal Brazing (AMB) Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Active Metal Brazing (AMB) Paste Market Insights
Multi-source procurement among ceramic substrate fabricators is restructuring supply relationships across the AMB paste value chain. Morgan Advanced Materials leverages its in-house metallization capabilities to secure long-term supply agreements with Japanese substrate producers. TANAKA Precious Metals anchors regional procurement networks through its precious metals refining and paste formulation integration in East Asia. Lucas-Milhaupt competes on North American proximity, sustaining just-in-time delivery contracts with power module assemblers.
Active metal brazing paste consists of a metal powder matrix—typically silver, copper, or nickel—combined with an active element such as titanium or zirconium that chemically reacts with ceramic surfaces to enable direct wetting and bonding without pre-metallization, achieving joint strengths exceeding 150 MPa in alumina and silicon nitride assemblies. Silver-based formulations dominate current procurement volumes due to established reliability in high-temperature power cycling, while copper-based variants represent the fastest-growing category as manufacturers seek cost reduction for automotive-scale SiC module production. Furnace brazing technology occupies the largest installed equipment base, though induction heating captures expanding share where throughput and energy efficiency drive capital replacement decisions.
Japan's METI enforces JIS standards for electronic component reliability that directly specify brazed joint performance under thermal shock testing, while REACH and RoHS frameworks in Europe restrict certain alloying additives and mandate material disclosure throughout the supply chain. China's GB standards under SAMR oversight increasingly align AMB paste composition requirements with domestic semiconductor packaging localization targets. Stakeholders must monitor evolving alloy composition restrictions and regional certification reciprocity agreements that will determine which formulation portfolios retain cross-border market access.
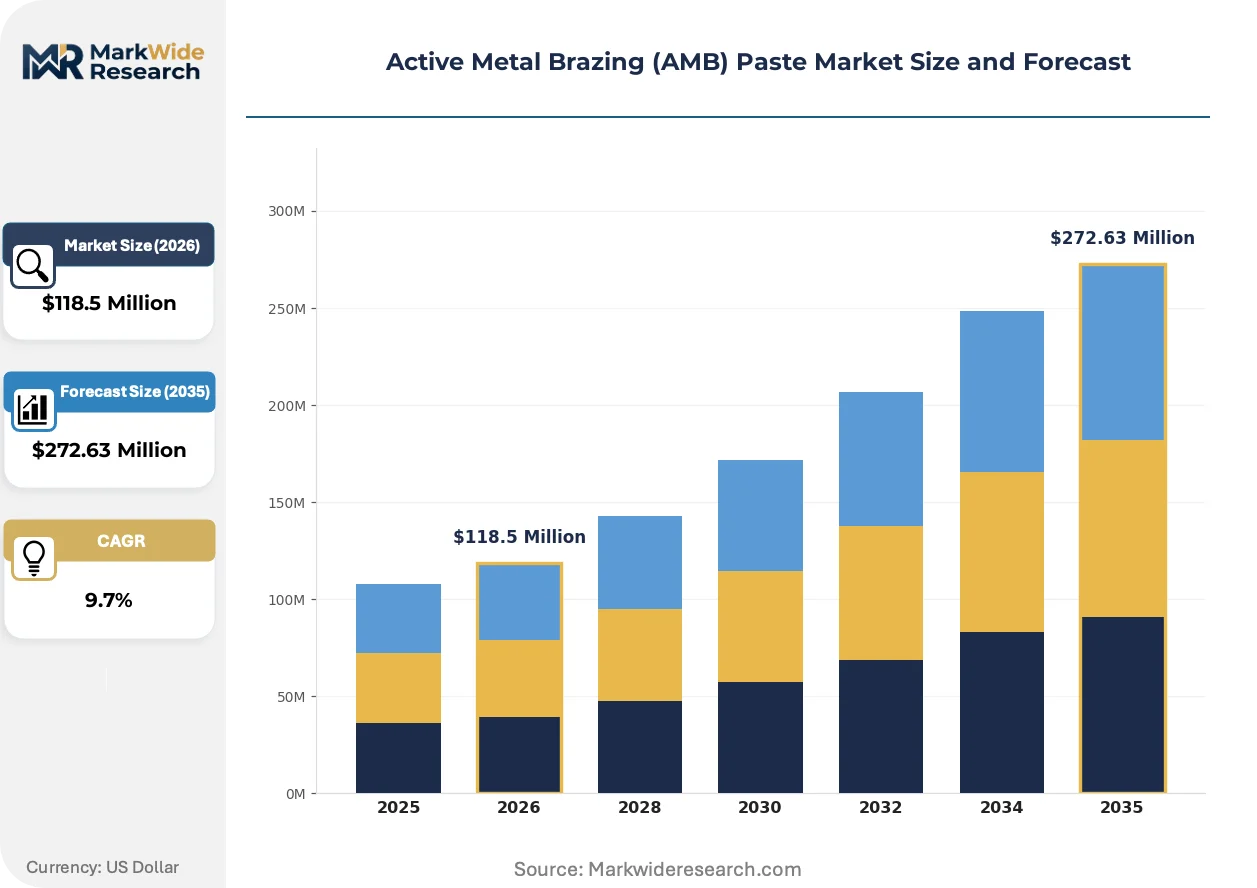
Market Dynamics
Silicon carbide module packaging is restructuring procurement priorities across the AMB paste value chain, as automotive power electronics manufacturers demand ceramic substrates capable of withstanding higher thermal cycling loads than traditional IGBT assemblies.
Growth Catalysts
- China's MIIT dual carbon goals:Stricter efficiency mandates for electric vehicle powertrains are accelerating semiconductor packaging localization. Domestic substrate fabricators are qualifying AMB pastes for high-volume SiC module production.
- Automotive SiC adoption:Power module assemblers in Japan and South Korea are expanding furnace brazing capacity to meet 800V platform ramp schedules from tier-one suppliers.
- Renewable energy inverter demand:Utility-scale solar and wind installations require ceramic-to-metal joints with thermal shock resistance exceeding 150 MPa, driving specification upgrades in East Asian manufacturing clusters.
Market Restraints
- Silver price volatility:Precious metals refining constraints in primary producing regions create input cost instability for silver-based formulations that dominate current procurement volumes.
- East Asian supply concentration:Substrate fabrication for IGBT and SiC modules concentrates procurement decisions among Japanese and South Korean producers, limiting buyer negotiating leverage.
- REACH alloying restrictions:ECHA frameworks restrict certain titanium and zirconium compound additives, forcing reformulation cycles that extend qualification timelines for European market access.
Strategic Opportunities
- Copper-based formulation expansion:Cost reduction imperatives for automotive-scale production are opening procurement windows for non-silver active metal brazing pastes in power module assembly lines.
- Induction heating equipment replacement:Energy efficiency mandates and throughput requirements are displacing legacy furnace brazing installations in North American power electronics manufacturing.
- India's PLI scheme for semiconductors:Domestic packaging localization incentives under CEA oversight are creating qualification pathways for AMB paste suppliers in emerging substrate fabrication facilities.
Industry Challenges
- Brazing technician scarcity:Furnace atmosphere control and joint inspection expertise remains concentrated among aging workforces in Japanese and German equipment supplier networks.
- Cross-border certification reciprocity gaps:Divergent JIS, GB, and REACH testing protocols force redundant qualification runs, extending time-to-revenue for formulation portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Metal Brazing (AMB) Paste Market |
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $272.63 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Based, Copper-Based, Nickel-Based, Aluminum-Based Application: Heat Exchangers, Semiconductor Devices, Vacuum Equipment, Power Electronics Technology: Induction Heating, Resistance Heating, Infrared Heating, Furnace Brazing End User: Electronics Manufacturers, HVAC Equipment Makers, Aerospace Components, Energy Systems |
| Companies Covered | Tokyo Braze, BrazeTec, Morgan Advanced Materials, LOT-TEK GmbH, VBC Group, TANAKA Precious Metals, Prince & Izant, Lucas-Milhaupt, Aimtek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Metal Brazing (AMB) Paste Market Trends and Innovations
Active metal brazing paste formulation is converging with advanced ceramic substrate architectures, as power module reliability requirements outpace the performance envelopes of legacy joining technologies. Three developments are compressing competitive timelines across the value chain.
Copper-based active metal brazing pastes are integrating titanium hydride activation systems to achieve wetting performance comparable to silver formulations at reduced material cost. Automotive power module assemblers in Germany and the United States are piloting these alternatives for 800V traction inverter programs. The technology is integrating cost-down roadmaps without sacrificing thermal cycling reliability in silicon nitride substrate assemblies.
Japan's METI is enforcing updated JIS standards for electronic component reliability that expand thermal shock testing protocols for brazed ceramic-to-metal joints. Substrate fabricators must demonstrate performance across expanded temperature ranges to maintain supply relationships with tier-one automotive module suppliers. South Korean producers are responding by upgrading furnace atmosphere control systems to meet the stricter qualification thresholds.
Multi-source qualification requirements from ceramic substrate fabricators are fragmenting long-term supply agreements into shorter validation cycles with performance guarantees. Power module assemblers in China and Japan are unbundling paste procurement from equipment service contracts, creating direct supplier relationships that bypass traditional distributor channels. This pattern is most visible in East Asian manufacturing clusters where substrate fabrication capacity is expanding fastest.
Active Metal Brazing (AMB) Paste Market Segmentation
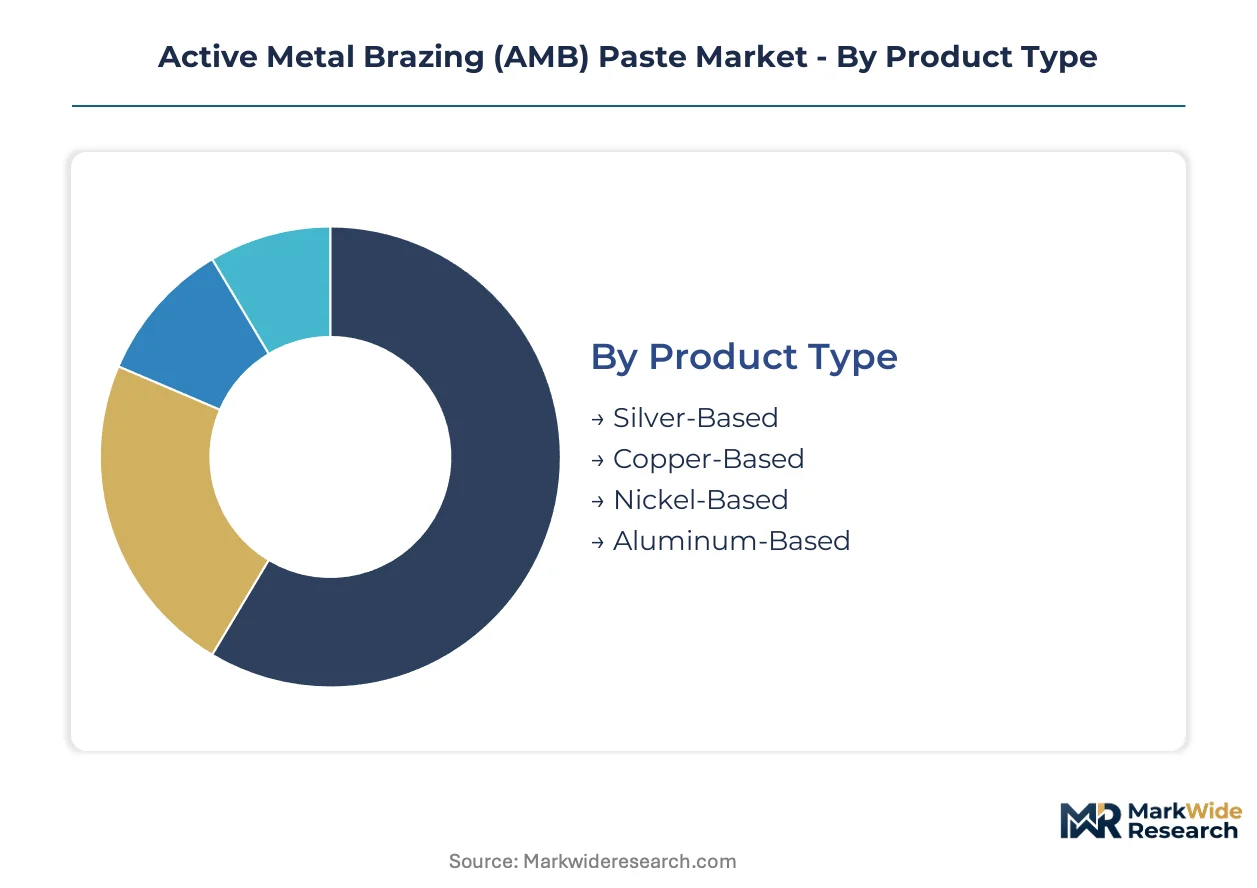
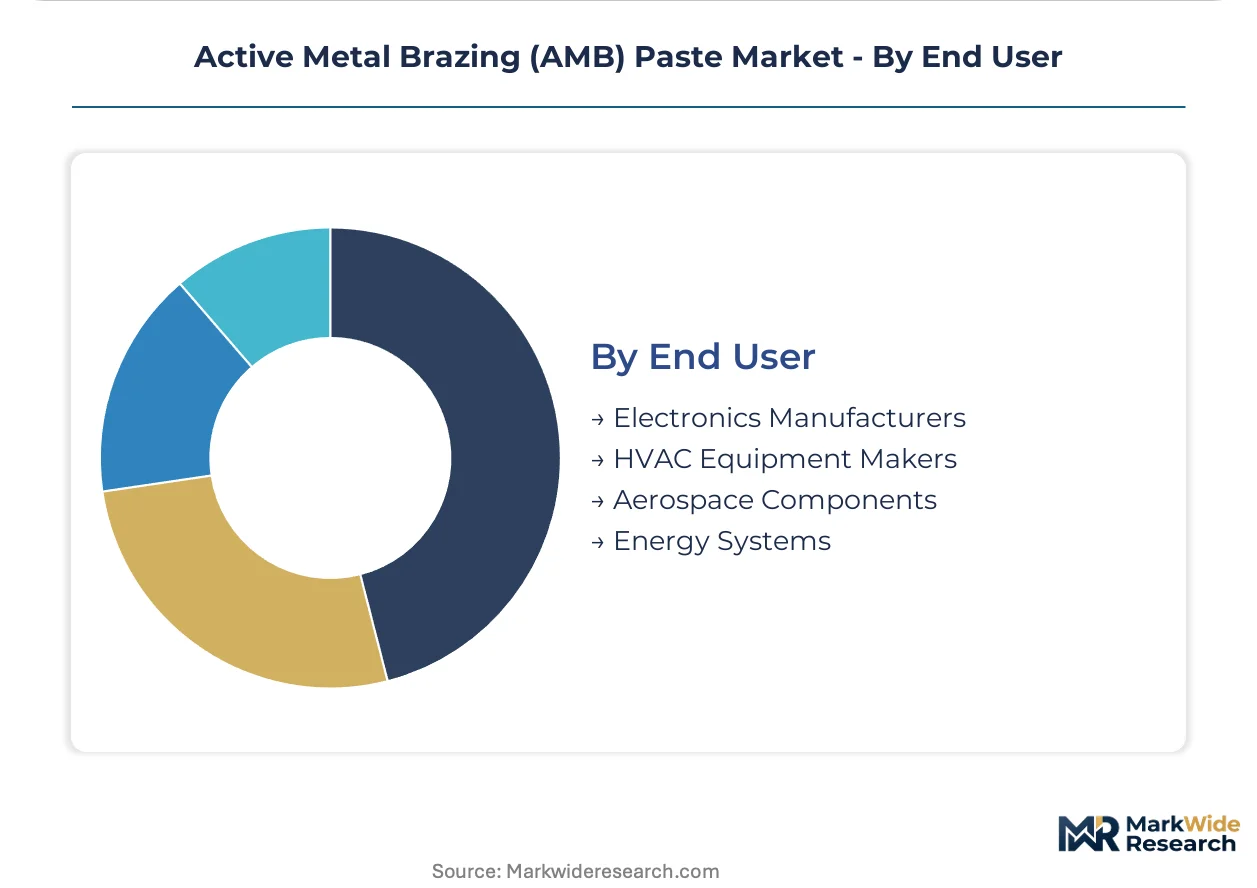
AMB paste procurement varies sharply by integration depth, with standalone brazing operations demanding different formulation portfolios than embedded manufacturing systems. Substrate fabricators and power module assemblers prioritize distinct technical specifications, reshaping supplier relationships across each segment boundary.
Product Type:
Silver-based formulations operate as standalone high-reliability solutions, while copper and nickel variants embed more deeply into cost-sensitive automotive production systems.
- Silver-Based:These formulations combine silver powder matrices with titanium or zirconium activators to achieve joint strengths exceeding 150 MPa in alumina and silicon nitride assemblies. Demand concentrates in Japanese and South Korean substrate fabrication facilities serving IGBT and SiC module producers, driven by METI-enforced JIS reliability standards that specify brazed joint performance under thermal shock testing.
- Copper-Based:Titanium hydride activation systems enable wetting performance comparable to silver at reduced material input cost. German and US automotive power module assemblers are piloting these alternatives for 800V traction inverter programs, responding to cost reduction imperatives for automotive-scale SiC module production.
- Nickel-Based:These pastes serve high-temperature vacuum applications where oxidation resistance outweighs thermal conductivity requirements.
- Aluminum-Based:Lightweight formulations target aerospace component joining where mass reduction drives specification selection.
Silver-based pastes lead volumes today; copper-based alternatives are gaining share fastest.
Application:
Application segmentation tracks thermal cycling intensity, with power electronics and semiconductor devices imposing the most demanding joint reliability requirements.
- Power Electronics:Ceramic-to-metal joints in IGBT and SiC modules must withstand thermal shock resistance exceeding 150 MPa, driving specification upgrades across East Asian manufacturing clusters in Japan, South Korea, and China.
- Semiconductor Devices:China's MIIT dual carbon goals and stricter efficiency mandates are pushing domestic packaging localization, with substrate fabricators qualifying AMB pastes for high-volume production lines.
- Heat Exchangers:Moderate thermal cycling loads enable broader formulation flexibility in HVAC and industrial equipment.
- Vacuum Equipment:Ultra-high purity requirements restrict viable activator chemistries in scientific and semiconductor process equipment.
Power electronics commands the largest procurement volumes; semiconductor device applications show the steepest expansion trajectory.
Technology:
Technology selection hinges on throughput requirements and energy efficiency mandates, with furnace systems dominating installed base and induction capturing replacement cycles.
- Furnace Brazing:This technology occupies the largest installed equipment base across Japanese and South Korean substrate fabrication facilities, though aging workforces concentrated in German and Japanese equipment supplier networks constrain capacity expansion.
- Induction Heating:Energy efficiency mandates and throughput requirements are displacing legacy furnace installations in North American power electronics manufacturing, with automotive module assemblers prioritizing capital replacement decisions.
- Resistance Heating:Localized heating suits repair operations and small-batch prototype fabrication.
- Infrared Heating:Rapid thermal ramp capabilities serve specialized ceramic substrate architectures with temperature-sensitive metallization layers.
Furnace brazing retains the dominant installed base; induction heating is climbing the fastest among new capital deployments.
End User:
End user segmentation reflects divergent qualification timelines, with electronics manufacturers facing the most stringent certification reciprocity requirements.
- Electronics Manufacturers:Power module assemblers in China and Japan are unbundling paste procurement from equipment service contracts, creating direct supplier relationships that bypass traditional distributor channels. REACH alloying restrictions from ECHA force reformulation cycles that extend qualification timelines for European market access.
- Energy Systems:Utility-scale solar and wind inverter producers in East Asia require ceramic-to-metal joints with expanded temperature range performance, responding to renewable energy installation growth.
- HVAC Equipment Makers:Standardized thermal cycling profiles enable multi-source procurement strategies with shorter validation cycles.
- Aerospace Components:Traceability requirements and flight-critical reliability standards limit qualified supplier pools.
Electronics manufacturers dominate procurement volumes; energy systems end users are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters concentrate substrate fabrication capacity for power electronics, with ceramic-to-metal joining expertise concentrated in Japan, South Korea, and China. Procurement decisions across these markets respond to divergent regulatory frameworks and localization imperatives.
Japan
IGBT and SiC module substrate fabricators in Nagoya and Osaka industrial corridors drive silver-based paste procurement volumes. METI enforces updated JIS standards expanding thermal shock testing protocols for brazed joints. Kansai region producers are upgrading furnace atmosphere control systems to meet stricter qualification thresholds for tier-one automotive suppliers.
China
Domestic packaging localization accelerates under MIIT dual carbon goals and stricter EV powertrain efficiency mandates. SAMR oversees GB standards alignment with semiconductor fabrication targets. Yangtze River Delta substrate fabricators in Shanghai and Suzhou are qualifying AMB pastes for high-volume SiC module production lines.
South Korea
Power module assemblers are expanding furnace brazing capacity to meet 800V platform ramp schedules from tier-one automotive suppliers. The country's national industrial regulator enforces electronic component reliability standards converging with METI frameworks. Busan-Ulsan manufacturing complexes concentrate procurement decisions for automotive and renewable energy inverter applications.
Germany
Automotive power module assemblers pilot copper-based alternatives with titanium hydride activation for 800V traction inverter programs. ECHA REACH frameworks restrict certain alloying additives and mandate material disclosure throughout supply chains. Bavaria and Baden-Württemberg industrial regions host equipment supplier networks where brazing technician expertise concentrates.
United States
North American power electronics manufacturers prioritize induction heating capital replacement for energy efficiency and throughput gains. EPA industrial emissions frameworks influence equipment upgrade decisions. Midwest manufacturing corridors and Pacific Northwest aerospace clusters sustain just-in-time delivery contracts with specialized paste distributors.
Active Metal Brazing (AMB) Paste Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue copper-based formulation development and induction heating compatibility. The market structure reflects moderate consolidation among precious metals refiners with integrated paste formulation capabilities, alongside specialized regional distributors serving proximity-sensitive procurement. Three archetypes dominate: vertically integrated metallization specialists, precious metals refiners with downstream formulation integration, and regional proximity-based distributors. Competitive moves concentrate on multi-source qualification unbundling and direct supplier relationship formation bypassing traditional channels.
Among East Asian precious metals refiners, TANAKA Precious Metals anchors regional procurement networks through metallization and formulation integration. Morgan Advanced Materials exemplifies the vertically integrated archetype, leveraging in-house capabilities to secure substrate fabricator agreements. Lucas-Milhaupt occupies the North American proximity-based position, sustaining delivery relationships with power module assemblers.
| Leading Market Players |
|---|
| Tokyo Braze |
| BrazeTec |
| Morgan Advanced Materials |
| LOT-TEK GmbH |
| VBC Group |
| TANAKA Precious Metals |
| Prince & Izant |
| Lucas-Milhaupt |
| Aimtek |
| Others |
Pricing and Supply Chain Analysis
China's MIIT dual carbon goals gate qualified supply and premium-tier pricing access, as substrate fabricators must demonstrate compliance with domestic semiconductor packaging localization targets to secure procurement relationships with tier-one automotive module suppliers. Silver price volatility from precious metals refining constraints creates input cost instability that propagates through formulation portfolios, compressing margins for non-integrated producers while vertically integrated refiners capture pricing power through captive supply.
Pricing Analysis
Input-cost pass-through from silver powder matrices dominates pricing dynamics, with precious metals volatility propagating directly to silver-based formulation contracts. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified high-reliability grades from automotive-volume copper-based alternatives and industrial-grade nickel formulations. Pricing pressure stems from automotive cost-down roadmaps for 800V SiC module production. Power module assemblers in Germany and the United States exhibit highest price sensitivity, while Japanese substrate fabricators prioritize reliability certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Osaka, Nagoya, and Busan anchor hub-and-spoke patterns for East Asian substrate fabrication clusters. Supply concentrates in Japan, South Korea, and China, with raw material dependencies spanning silver and copper powder feedstocks, titanium hydride activators, and ceramic substrate blanks. Single-source vulnerability from precious metals refining concentration in primary producing regions threatens formulation continuity. Distribution runs through direct supplier relationships that bypass traditional distributor channels, particularly in Yangtze River Delta and Kansai industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
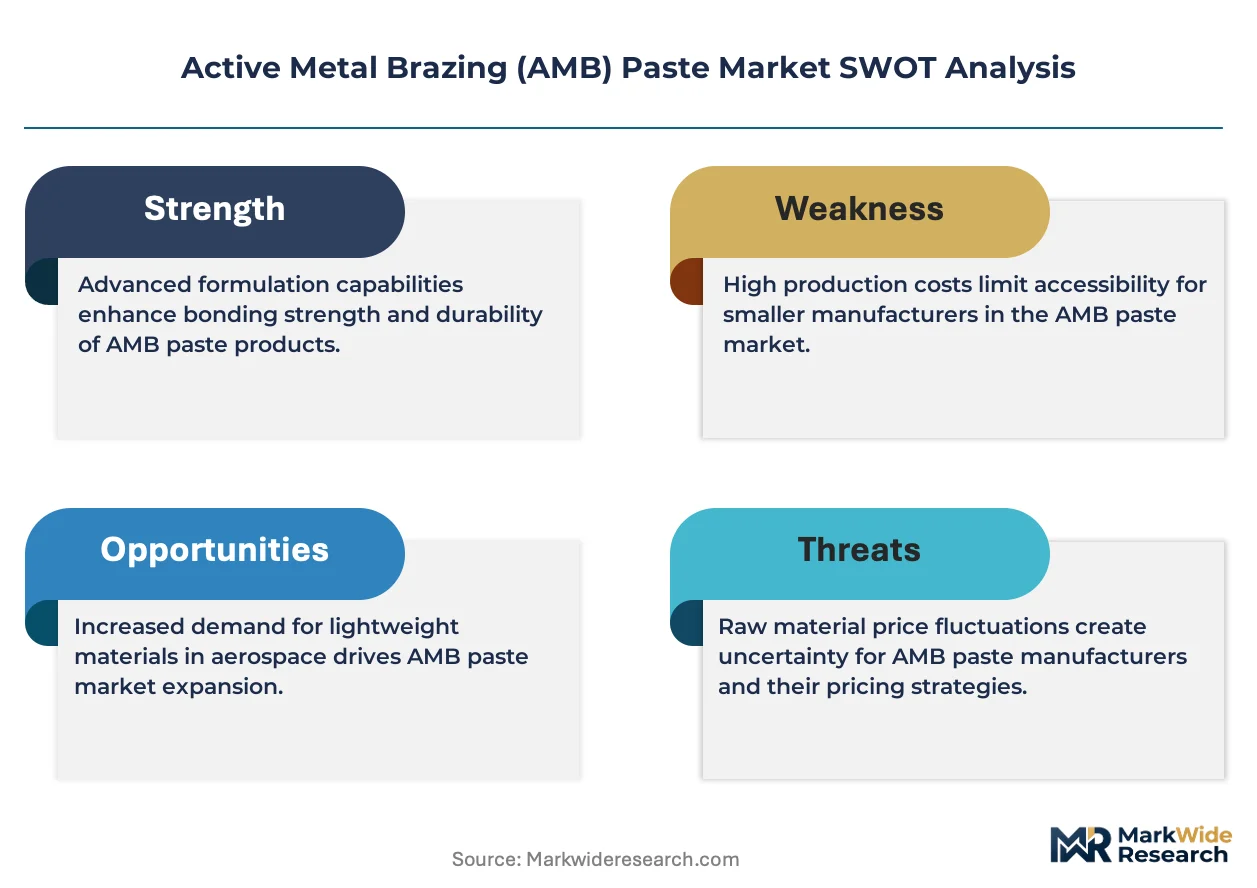
This market functions as a geographic-arbitrage play between East Asian manufacturing clusters and emerging Indian substrate fabrication, exploiting cost differentials in brazing technician labor and regulatory qualification timelines under divergent JIS and PLI scheme frameworks.
For Market Incumbents: Hedge silver price exposure through backward integration into precious metals refining or long-term offtake agreements with primary producers. Defend against copper-based formulation entrants by accelerating JIS certification investments for next-generation titanium hydride activation systems. Channel control through unbundled paste procurement relationships protects margin position as substrate fabricators fragment supply agreements.
For New Entrants and Emerging Players: Begin with copper-based formulation qualification for automotive 800V traction inverter programs, where cost reduction imperatives outrank incumbent brand loyalty. India's PLI scheme for semiconductors under CEA oversight offers the most penetrable geography, with domestic packaging localization incentives creating qualification pathways absent entrenched supplier relationships. Go-to-market through direct equipment compatibility partnerships accelerates furnace brazing line integration.
For Investors and Strategic Acquirers: Roll-up economics work for precious metals refiners with downstream paste formulation integration because substrate fabricators are consolidating procurement decisions among multi-capability suppliers. Long-term viability centers on automotive SiC module volume ramps and renewable energy inverter deployment. Watch for induction heating equipment replacement cycles in North American manufacturing as the inflection signal for copper-based formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Based Formulation Scale-Up | Titanium hydride activation development captures automotive cost-down roadmaps for 800V SiC modules. |
| Induction Heating Equipment Partnership | Energy efficiency mandates in North American power electronics drive furnace replacement demand. |
| JIS Certification Investment | METI thermal shock testing protocols gate supply relationships with tier-one Japanese automotive suppliers. |
| India PLI Scheme Localization | CEA semiconductor packaging incentives create qualification pathways in emerging substrate fabrication. |
| Precious Metals Refining Integration | Captive silver and copper supply hedges input cost volatility for formulation portfolios. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with substrate fabrication procurement directors, power module assembler engineering leads, precious metals refinery technical directors, furnace equipment OEM sales managers, and ceramic substrate R&D specialists with secondary validation from SEC filings, customs trade data, METI JIS standard documentation, and ECHA REACH regulatory frameworks. Bottom-up paste volume estimates from substrate fabrication capacity triangulated against top-down power electronics module production forecasts.
Segment-weighting across product type, application, technology, and end user dimensions anchored the analytical framework across the projection horizon. Silver-based, copper-based, nickel-based, and aluminum-based formulation categories combined with power electronics, semiconductor device, heat exchanger, and vacuum equipment applications. CAGRs derived from regression analysis against SiC module adoption curves and renewable energy inverter deployment trajectories, with furnace brazing and induction heating technology splits calibrated to capital equipment replacement cycles.
Caveats apply where silver price volatility, REACH alloying restriction expansions, or cross-border certification reciprocity failures could materially shift the outlook. Forecasts reflect documented assumptions about automotive 800V platform ramps and domestic packaging localization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Asia-Pacific Sealants Market