
 Middle-East and Africa Hot-Melt Adhesives Market | 2026-2036
Middle-East and Africa Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Hot-Melt Adhesives Market Foresight
Packaging is shifting toward higher-performance hot-melt systems across the Middle-East and Africa as e-commerce fulfillment expands. H.B. Fuller Company leverages its regional distribution network to supply packaging-grade ethylene vinyl acetate adhesives. Henkel AG & Co. KGaA anchors its position through automotive assembly applications in Moroccan and South African plants. Arkema Group differentiates via reactive hot melt technology for moisture-sensitive electronics bonding.
Hot-melt adhesives are thermoplastic polymer systems applied in molten state that solidify upon cooling to form mechanical bonds, typically formulated from ethylene vinyl acetate copolymers with melt viscosities between 2,000 and 50,000 mPa·s and softening points of 80°C to 120°C. These adhesives serve primary industrial functions in high-speed packaging lines, furniture edge-banding, and automotive interior trim attachment where solvent-free bonding and rapid set times are essential. Ethylene vinyl acetate formulations dominate volume flows due to their cost position and broad substrate compatibility, while reactive hot melt technology captures margin pools in electronics and automotive applications demanding elevated heat resistance. Styrenic block copolymers occupy a specialized niche in pressure-sensitive labeling across pharmaceutical and consumer goods packaging in the Gulf states.
Saudi Food and Drug Authority and Gulf Standardization Organization frameworks govern adhesive contact safety in food packaging and consumer goods across Gulf Cooperation Council member states. South Africa's National Regulator for Compulsory Specifications enforces VOC emission thresholds for interior building materials, directly affecting construction adhesive specifications. Environmental Health and Safety departments in UAE free zones monitor workplace exposure limits during hot-melt application processes. Stakeholders must track evolving polymer feedstock availability and regional converter capacity expansion to align product portfolios with formulation shifts.
Market Dynamics
E-commerce fulfillment acceleration across Gulf Cooperation Council states is restructuring adhesive procurement patterns, with packaging converters demanding faster-setting ethylene vinyl acetate formulations and tighter VOC compliance under Gulf Standardization Organization technical regulations.
Growth Catalysts
- Corrugated Packaging Surge:Saudi Arabia's Jeddah and Riyadh industrial clusters are expanding automated board sealing lines, pulling volume-grade hot-melt adhesives into high-throughput operations.
- GSO Technical Regulations:The UAE's adoption of stricter adhesive emission standards is forcing formulation upgrades that favor suppliers with certified low-VOC product portfolios.
- Reactive Hot Melt Penetration:Moisture-curing polyurethane technology is capturing share in Moroccan automotive assembly plants seeking elevated heat resistance for interior trim bonding.
Market Restraints
- Ethylene Vinyl Acetate Feedstock Volatility:Crude oil price swings directly compress margins on volume-grade formulations, exposing regional blenders to naphtha derivative cost pressure.
- Converter Capacity Concentration:Saudi Arabia hosts over half of regional hot-melt compounding infrastructure, creating geographic supply risk for East African markets.
- Water-Based Adhesive Substitution:South African construction applications are pivoting toward aqueous systems under National Regulator for Compulsory Specifications VOC thresholds, eroding hot-melt share in building materials.
Strategic Opportunities
- Nigerian Pharmaceutical Labeling:Pressure-sensitive adhesive demand for track-and-trace packaging remains underdeveloped, offering first-mover positioning for styrenic block copolymer suppliers.
- Reactive Technology Convergence:Hybrid systems combining polyurethane reactivity with hot-melt application speed are opening electronics bonding applications in UAE free zone assembly operations.
- Direct Converter Relationships:Bypassing traditional distributor networks through technical service partnerships with Saudi packaging clusters is compressing channel costs and accelerating specification wins.
Industry Challenges
- Formulation Chemistry Expertise Gap:Regional compounders lack sufficient polymer science capacity to execute rapid VOC-compliant reformulations under tightening Gulf Standardization Organization deadlines.
- Application Equipment Retrofit Costs:Existing packaging lines require heated tank and hose upgrades to handle next-generation reactive hot melt viscosities, stretching converter capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Hot-Melt Adhesives Market |
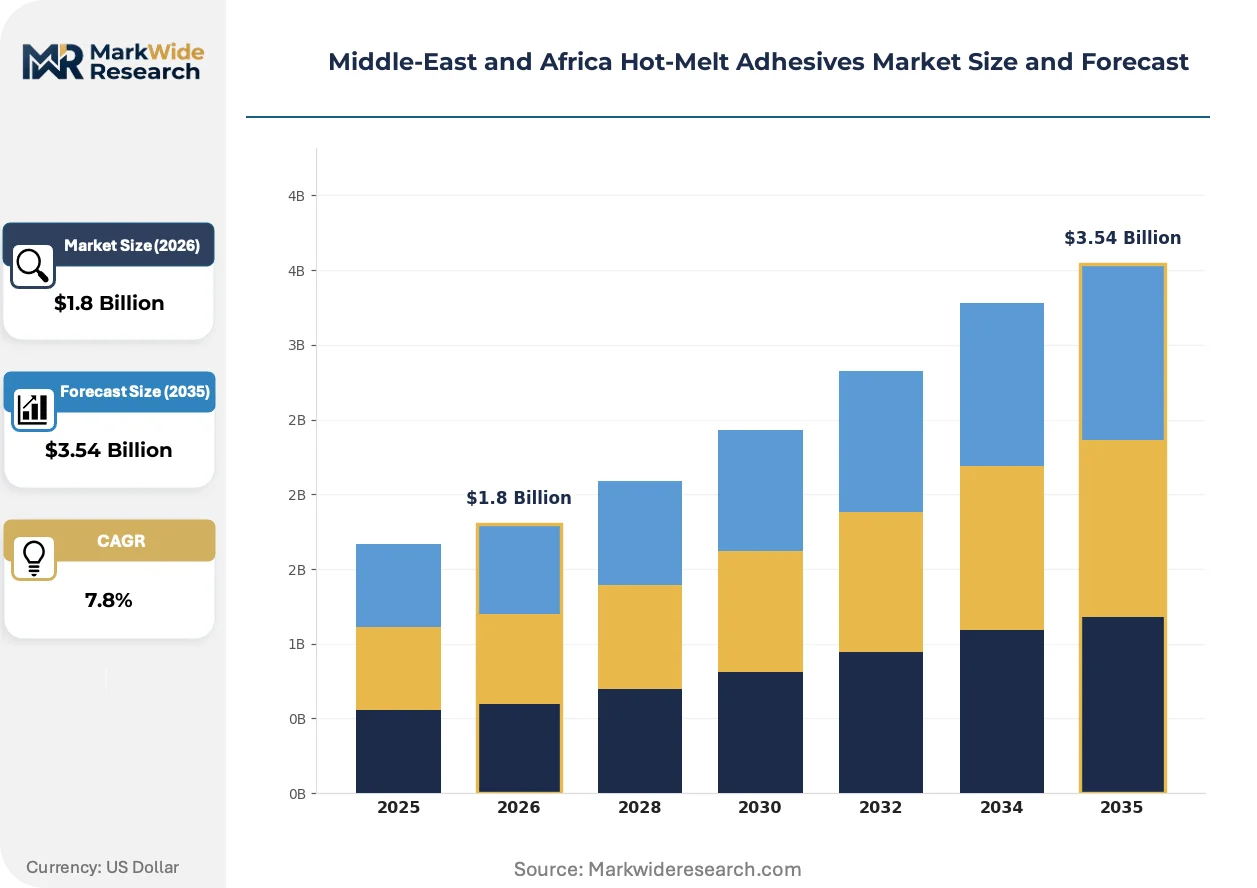
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Ethylene Vinyl Acetate, Styrenic Block Copolymers, Polyamide End User: Packaging, Automotive, Furniture, Electronics Technology: Hot Melt Coating, Hot Melt Extrusion, Reactive Hot Melt, Pressure-Sensitive Hot Melt Application: Bookbinding, Labeling, Assembly, Construction |
| Companies Covered | H.B. Fuller Company, Henkel AG & Co. KGaA, Arkema Group, Sika AG, Jowat, 3M, The Dow Chemical Company, Beardow Adams, Avery Dennison Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Hot-Melt Adhesives Market Shifts & Advancements
Formulation chemistry and application technology are converging to redefine performance benchmarks across Middle-East and Africa adhesive markets, with regulatory pressure and end-use specialization driving divergence between commodity and specialty segments.
Reactive polyurethane hot-melt technology is electrifying moisture-curing bonding applications. Automotive assemblers in Moroccan and South African plants are adopting these systems at accelerating pace to meet elevated temperature resistance requirements for interior trim attachment. This chemistry is electrifying margin pools previously captured by solvent-based alternatives while compressing set-time expectations across the specification chain.
Gulf Standardization Organization emission protocols are tightening adhesive contact safety requirements for food packaging across GCC member states. Industrial consequence includes mandatory third-party testing for migration limits and volatile organic compound thresholds, raising compliance costs for regional blenders. Food-contact packaging converters in the UAE and Saudi Arabia are responding by consolidating supplier relationships toward certified formulation houses with established GSO documentation.
Specification-driven procurement is consolidating buyer power among Saudi packaging clusters. Large corrugated converters are unbundling technical service from material supply, replacing traditional distributor relationships with direct polymer supplier partnerships. This pattern is most visible in Jeddah industrial zone operations, where volume commitments now hinge on application engineering support rather than price alone.
Middle-East and Africa Hot-Melt Adhesives Market Segmentation
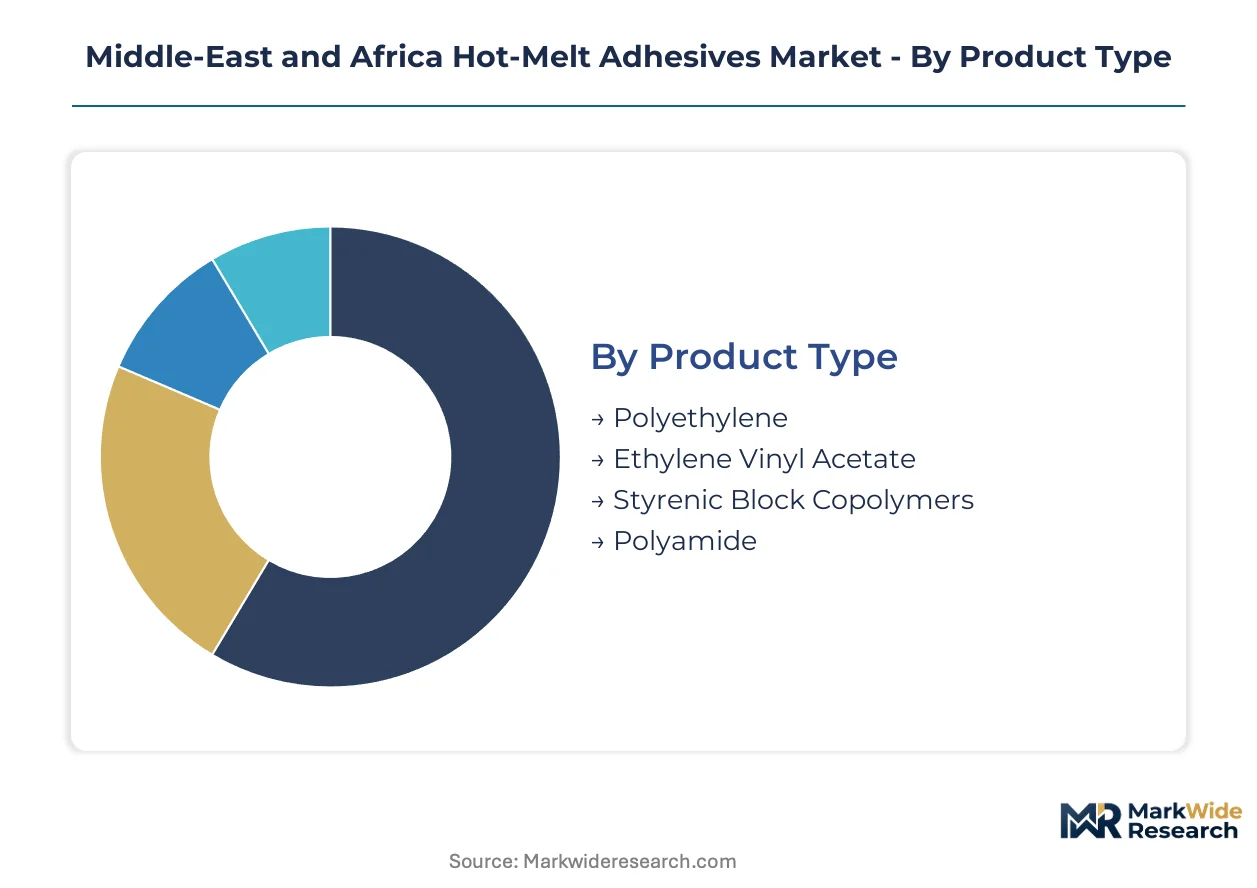
Hot-melt adhesive formulation chemistry and application technology diverge sharply across the Middle-East and Africa, with capital requirements varying tenfold between commodity ethylene vinyl acetate compounding and reactive polyurethane systems requiring precision moisture-cure control.
Product Type:
Capital intensity peaks with polyamide synthesis requiring high-pressure polymerization reactors, while ethylene vinyl acetate blending demands comparatively modest heated mixing vessels.
- Ethylene Vinyl Acetate:Copolymer formulations with 18-40% vinyl acetate content dominate volume flows through Saudi corrugated packaging clusters. Jeddah and Riyadh industrial zones pull steady demand for cost-optimized sealing grades under Gulf Standardization Organization emission protocols.
- Styrenic Block Copolymers:Hydrogenated SEBS and SIS structures enable pressure-sensitive adhesive performance for pharmaceutical track-and-trace labeling. Nigerian and South African demand remains underdeveloped relative to Gulf states, creating first-mover positioning for technical suppliers.
- Polyethylene:Metallocene-catalyzed grades serve cost-sensitive wood-furniture edge-banding across Moroccan manufacturing.
- Polyamide:Dimer-acid based hot melts command premium positioning for high-temperature automotive filter assembly in South African plants.
Most installed capacity flows through ethylene vinyl acetate. Expansion is steepest in styrenic block copolymers.
End User:
Application environments range from ambient-temperature packaging halls to 120°C automotive underhood conditions, dictating formulation investment thresholds.
- Packaging:Corrugated board sealing and case closing absorb the majority of regional volume, with e-commerce fulfillment acceleration across Gulf Cooperation Council states restructuring procurement toward faster-setting grades.
- Automotive:Interior trim bonding and filter assembly in Moroccan and South African plants are capturing moisture-curing reactive technology for elevated heat resistance requirements.
- Furniture:Edge-banding and veneer lamination concentrate in Turkish-influenced manufacturing clusters across North Africa.
- Electronics:Moisture-sensitive component bonding in UAE free zone assembly operations is opening hybrid reactive system adoption.
Packaging commands the largest absolute volume position. Electronics is gaining share fastest.
Technology:
Process equipment requirements separate simple tank-and-hose systems from precision extrusion lines demanding temperature control within ±2°C.
- Hot Melt Coating:Roll-applied systems serve continuous web converting in label stock manufacturing, with melt viscosity control critical for uniform coat weights.
- Reactive Hot Melt:Moisture-curing polyurethane technology is electrifying margin pools in automotive and electronics applications previously served by solvent-based alternatives.
- Hot Melt Extrusion:Profile coating for construction sealants faces substitution pressure from water-based systems under South African VOC regulations.
- Pressure-Sensitive Hot Melt:Permanent and removable tack formulations for pharmaceutical labeling remain technically demanding relative to commodity packaging grades.
Hot melt coating holds the broadest installed base. Reactive hot melt is climbing the fastest.
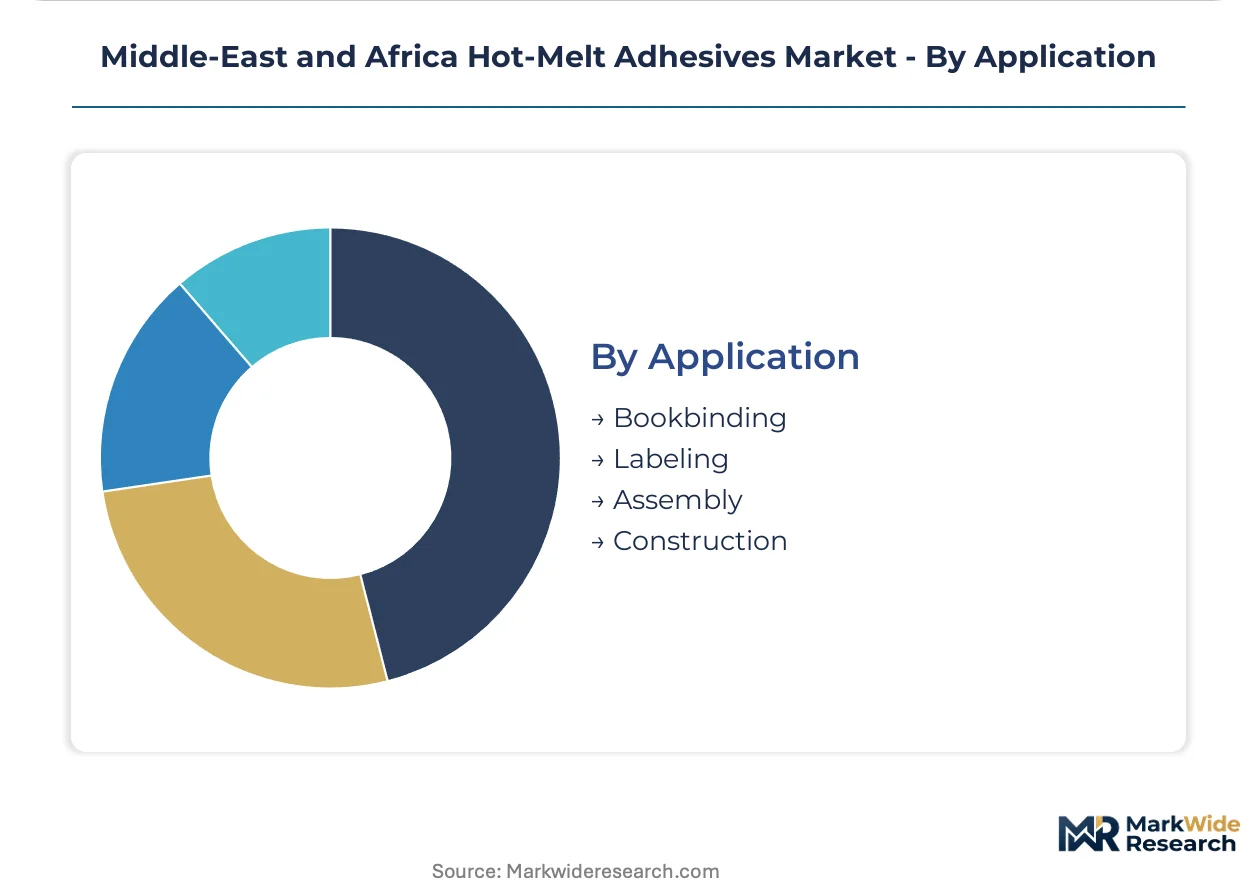
Application:
Performance specifications vary from the archival permanence demanded in bookbinding to the temporary repositionability required in consumer labeling.
- Labeling:Pressure-sensitive adhesive demand spans pharmaceutical serialization, logistics barcode applications, and consumer goods decoration across Gulf states.
- Assembly:Product attachment in automotive and electronics manufacturing is consolidating toward reactive systems with elevated temperature resistance.
- Bookbinding:Spine gluing and case-making in educational publishing concentrates in Egyptian and Lebanese printing clusters.
- Construction:Flooring installation and panel bonding face erosion from aqueous adhesive substitution under tightening emission frameworks.
Labeling represents the most mature application base. Assembly is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeddah and Riyadh industrial zones anchor hot-melt adhesive demand across the Middle-East and Africa, with Saudi packaging clusters pulling volume-grade ethylene vinyl acetate formulations for corrugated board sealing operations.
Saudi Arabia
Automated corrugated packaging lines in Jeddah and Riyadh industrial zones absorb the majority of regional ethylene vinyl acetate volume. The Saudi Food and Drug Authority enforces adhesive contact safety standards for food packaging applications. Jeddah's packaging cluster is consolidating supplier relationships toward certified formulation houses with established Gulf Standardization Organization documentation.
United Arab Emirates
UAE free zone assembly operations for electronics manufacturing are opening adoption of hybrid reactive hot-melt systems. MOHAP and the country's national standardization body administer adhesive emission protocols under Gulf Standardization Organization technical regulations. Dubai industrial zones are witnessing specification-driven procurement consolidation among large converters unbundling technical service from material supply.
South Africa
Automotive filter assembly and interior trim bonding in Eastern Cape and Gauteng manufacturing plants are capturing moisture-curing reactive technology. The National Regulator for Compulsory Specifications enforces VOC emission thresholds for interior building materials, eroding hot-melt share in construction applications. Durban's manufacturing corridor faces substitution pressure from water-based adhesive systems under tightening emission frameworks.
Morocco
Automotive assembly plants in Casablanca-Settat and Tangier-Med industrial zones are adopting reactive polyurethane hot-melt technology for elevated temperature resistance requirements. The country's national industrial development agency supports automotive supplier localization programs. Tangier-Med automotive cluster is restructuring procurement toward faster-setting adhesive grades for high-throughput interior trim attachment operations.
Nigeria
Pharmaceutical track-and-trace packaging in Lagos and Abuja manufacturing zones remains underdeveloped for pressure-sensitive adhesive applications. The country's national food and drug administration oversees packaging material safety standards. Lagos industrial zones offer first-mover positioning for styrenic block copolymer suppliers targeting serialization labeling demand.
Middle-East and Africa Hot-Melt Adhesives Market Competitive Landscape
Capacity expansion dominates the current landscape as regional compounders retrofit facilities to handle next-generation reactive hot-melt viscosities under tightening Gulf Standardization Organization deadlines. The vendor base separates into three distinct tiers: multinational formulation houses with certified low-VOC portfolios, regional blenders serving volume packaging grades, and specialized reactive technology suppliers. Strategic archetypes include emission-compliant specialists, automotive assembly integrators, and direct converter partnership builders. M&A activity and application equipment technical service partnerships represent the dominant competitive vectors reshaping channel structures.
Among multinational formulation houses, H.B. Fuller Company and Henkel AG & Co. KGaA occupy positions as archetypal direct converter partnership builders, while Arkema Group exemplifies the reactive technology specialist tier. These three anchors represent divergent strategic postures: the first two emphasize technical service integration with Saudi packaging clusters, while the third captures margin pools in moisture-curing applications. Sika AG and 3M sit within adjacent construction and industrial adhesive domains with transferable technology platforms. The competitive terrain rewards suppliers combining Gulf Standardization Organization certification depth with application engineering proximity to Jeddah and Riyadh industrial zones.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Arkema Group |
| Sika AG |
| Jowat |
| 3M |
| The Dow Chemical Company |
| Beardow Adams |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Reactive polyurethane technology adoption across Moroccan automotive plants simultaneously elevates formulation complexity costs and concentrates supply relationships toward certified specialty houses with moisture-cure application engineering capabilities. This chemistry transition compresses margins on legacy ethylene vinyl acetate grades while rewarding suppliers with Gulf Standardization Organization certification depth and direct technical service proximity to Jeddah packaging clusters.
Pricing Analysis
Crude oil derivative pass-through dominates ethylene vinyl acetate pricing, with naphtha volatility transmitting directly to volume-grade corrugated sealing formulations. Three-tier pricing structure across premium reactive systems, certified low-VOC standard grades, and economy EVA blends reflects Gulf Standardization Organization compliance investment and application engineering bundling. Pricing pressure stems from South African water-based adhesive substitution under National Regulator for Compulsory Specifications thresholds, eroding construction segment margins. Packaging converters in Saudi Arabia exhibit highest price sensitivity, while UAE electronics assemblers prioritize heat resistance over unit cost.
Supply Chain Analysis
Direct-to-converter channels handle high-volume demand from Saudi packaging clusters, bypassing traditional distributor markups through technical service partnerships. Raw material sourcing concentrates in Saudi Arabia, the UAE, and South Korea for polymer feedstocks, with dimer acid for polyamide synthesis drawing from specialized suppliers. Supply chain risk centers on single-source vulnerability for moisture-curing polyurethane precursors, with limited regional blending capacity for reactive systems. Distribution runs through Jeddah and Riyadh industrial zone logistics hubs, with East African markets dependent on transshipment through Durban.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
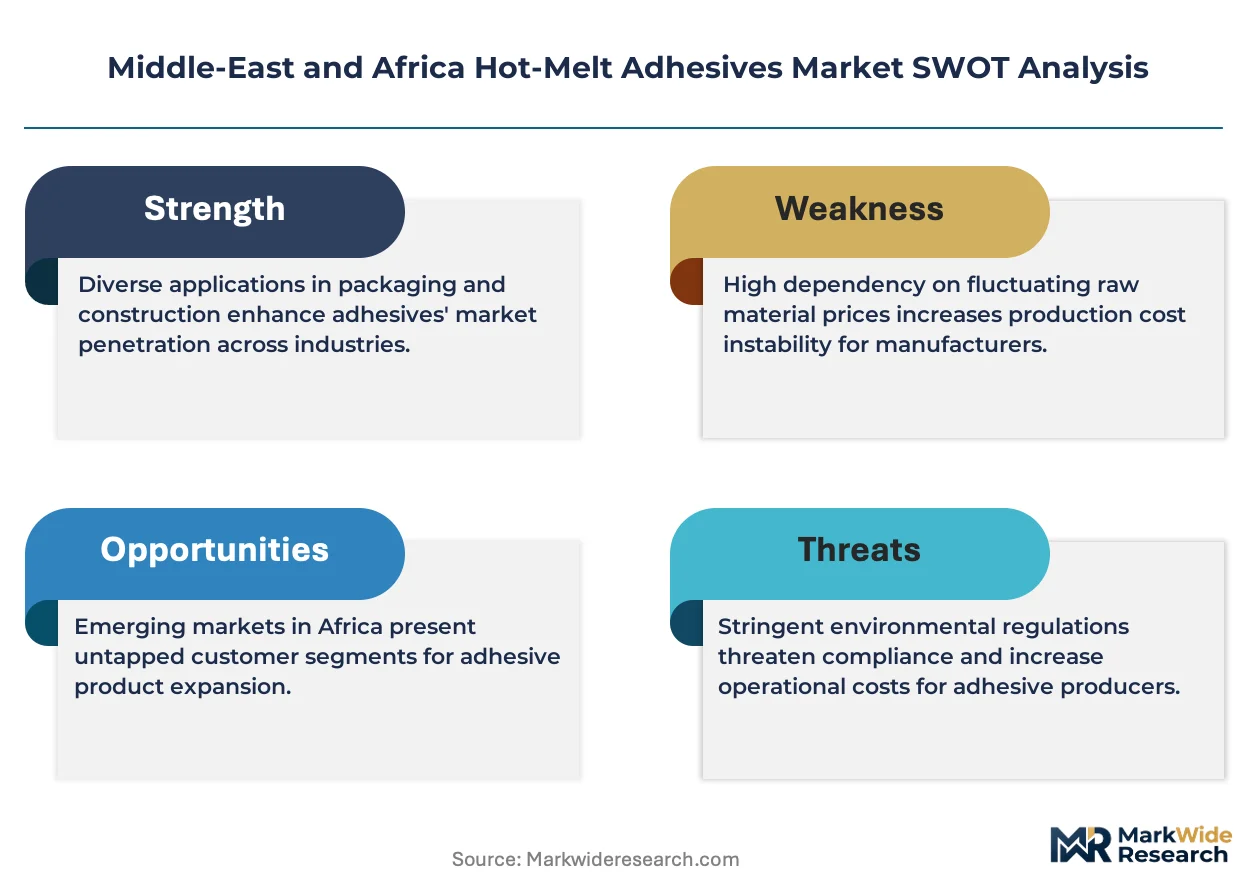
This market functions as a regulatory compounder, with Gulf Standardization Organization emission protocol deadlines forcing rapid formulation upgrades that consolidate buyer relationships toward certified suppliers.
For Market Incumbents: Acquire application engineering capabilities to defend specification control at Saudi packaging clusters. Water-based adhesive substitution in South African construction threatens volume erosion; counter through backward integration into low-VOC ethylene vinyl acetate feedstock sourcing. Prioritize Gulf Standardization Organization certification maintenance as the primary retention lever against emerging specialty compounders. For New Entrants and Emerging Players: Gulf Standardization Organization technical regulations in the UAE open a window for emission-compliant reactive technology positioning. Nigerian pharmaceutical labeling remains underpenetrated for styrenic block copolymer track-and-trace applications, offering first-mover access without incumbent technical service lock-in. Lead with direct converter partnerships rather than distributor channel builds to compress customer acquisition cost. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with Gulf Standardization Organization documentation because certification scarcity creates pricing power asymmetry against uncertified competitors. Target mid-cap compounders with established Saudi Food and Drug Authority compliance records and existing Jeddah industrial zone relationships. Watch for UAE free zone electronics assembly expansion as the demand inflection signal for reactive system capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive naphtha derivative supply insulates margins from crude oil volatility affecting EVA formulations. |
| Gulf Standardization Organization Certification Program | Third-party emission testing documentation locks in food packaging converter relationships across GCC states. |
| Direct Converter Technical Service Partnerships | Unbundling distributor channels accelerates specification wins at Jeddah and Riyadh corrugated sealing operations. |
| Reactive Hot Melt Capacity Expansion | Moisture-curing polyurethane systems capture automotive margin pools in Moroccan and South African assembly plants. |
| Pressure-Sensitive Adhesive Portfolio Development | Styrenic block copolymer investments target Nigerian pharmaceutical serialization labeling white space. |
Research Methodology
Coverage spans the Middle-East and Africa, with primary inputs from each regional production cluster, combining interviews with adhesive plant managers, packaging converter procurement leads, automotive Tier 1 supplier technical directors, and distribution channel partners. Secondary validation draws from Gulf Standardization Organization technical regulation filings, Saudi Food and Drug Authority compliance databases, South African National Regulator for Compulsory Specifications emission thresholds, customs trade data for polymer feedstock flows, and SEC filings of multinational formulation houses. Bottom-up demand modeling from end-use consumption patterns triangulates against top-down supply-side capacity assessments.
Granularity-level modeling operates at formulation chemistry, end-use industry, application technology, and regional production hub dimensions across the analysis window. CAGRs derive from segment-level volume trajectories weighted by value-per-ton differentials between commodity EVA and specialty reactive systems. Forecast inputs incorporate ethylene vinyl acetate copolymer melt viscosity specifications, automotive assembly plant capacity expansion announcements, and e-commerce fulfillment infrastructure buildout timelines.
Revisions become necessary when crude oil derivative cost shocks exceed historical volatility bands, Gulf Standardization Organization emission protocols accelerate implementation deadlines, or water-based adhesive substitution rates in South African construction outpace baseline assumptions. Forecasts reflect documented assumptions about polymer feedstock availability and regional converter capacity expansion schedules. Periodic stress-testing of base assumptions against regulatory enforcement intensity and application equipment retrofit adoption curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Textile Adhesives Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market