
 Asia-Pacific Polyurethane Adhesives Market | 2026-2036
Asia-Pacific Polyurethane Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyurethane Adhesives Market Outlook
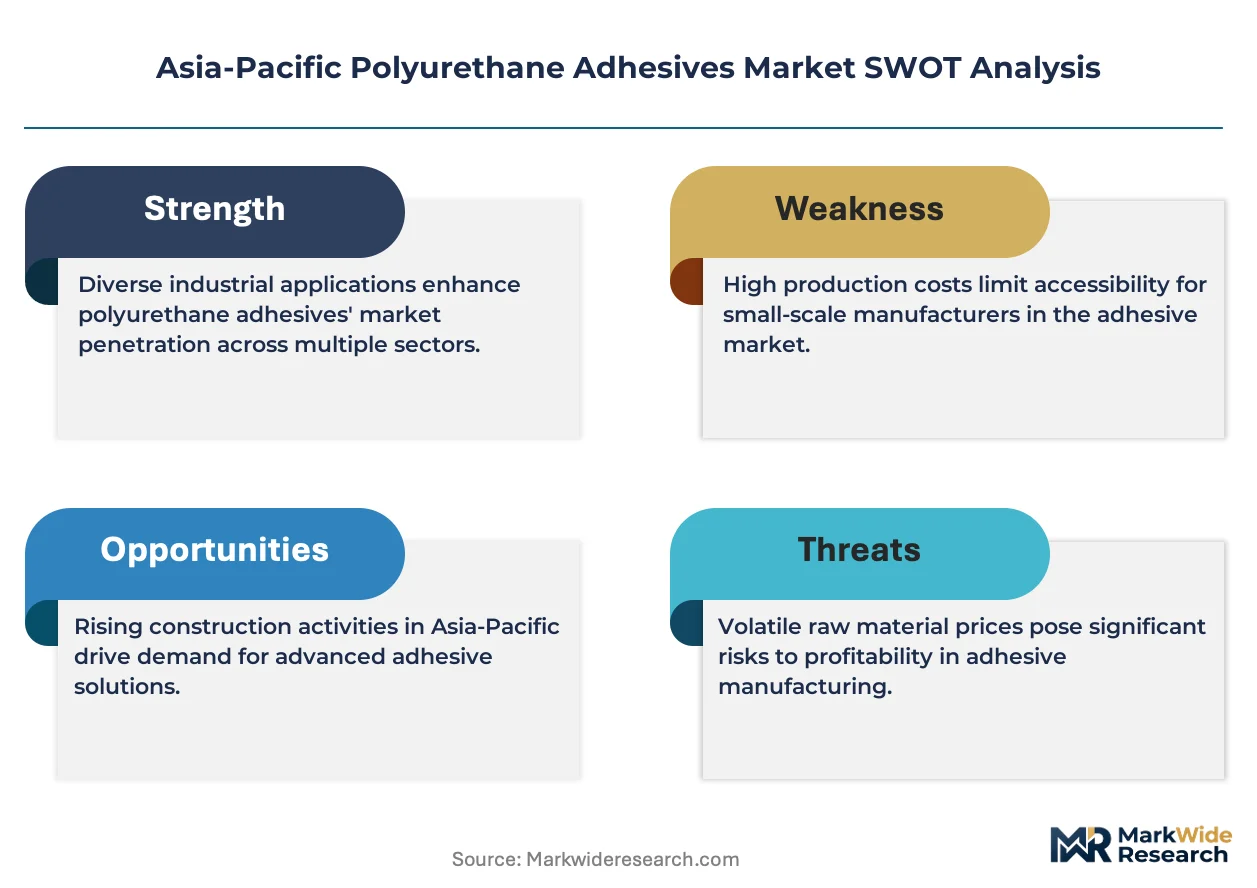
China's GB 30982 and GB 33372 standards on VOC content in adhesives is rebalancing the cost-of-entry calculus for polyurethane formulators, forcing legacy solvent-based producers toward waterborne and reactive system investments. BASF SE anchors its regional position through backward integration into isocyanate precursors at its Ludwigshafen-to-Shanghai supply chain. Henkel AG & Co. KGaA differentiates via high-performance automotive bonding solutions for electric vehicle platforms across South Korea and Japan. NANPAO RESINS CHEMICAL GROUP dominates Taiwan and Southeast Asian distribution channels for woodworking and footwear applications.
Asia-Pacific polyurethane adhesives comprise polymers formed from polyol and isocyanate reactions, typically exhibiting Shore A hardness of 40–90 and tensile shear strengths exceeding 10 MPa for structural bonding applications. These systems cure through moisture, heat, or chemical reaction to form elastomeric bonds resistant to impact, chemicals, and thermal cycling across substrates from metals to composites. Waterborne formulations now lead volume growth as environmental compliance hardens across the region, while reactive systems command premium positioning in automotive and electronics assembly where cure speed and structural integrity justify higher formulation costs. Hot melt polyurethane segments sustain steady demand in woodworking and furniture manufacturing, particularly within Vietnam and Indonesia's export-oriented processing industries.
Japan's METI enforces chemical substance reporting under its Industrial Safety and Health Act, directly shaping isocyanate handling protocols and workplace exposure limits for adhesive manufacturers. South Korea's MFDS and Ministry of Environment coordinate on hazardous substance classifications that affect import clearances and product registration timelines for foreign suppliers. India's BIS certification requirements for construction chemicals create additional compliance layers for entrants targeting infrastructure applications. Stakeholders must monitor how China's dual carbon goals and evolving GB standards cascade into formulation mandates, procurement specifications, and plant relocation decisions across the regional supply base.
Market Dynamics
China's GB 33372 VOC emission limits are compressing formulation margins while forcing solvent-based producers toward waterborne and reactive system investments. The regulatory squeeze concentrates competitive pressure on legacy manufacturers lacking backward integration into isocyanate precursors.
Growth Catalysts
- Automotive lightweighting mandates:Japan's METI fuel economy standards and South Korea's K-EV100 initiative accelerate solvent-free adhesive adoption for composite bonding in electric vehicle platforms.
- GB standards compliance pressure:China's tightening volatile organic compound limits under GB 30982 restructure procurement specifications across eastern manufacturing clusters.
- Waterborne formulation advances:Moisture-cure polyurethane systems achieve structural shear strengths exceeding 10 MPa, enabling displacement of solvent-based alternatives in electronics assembly.
Market Restraints
- Isocyanate feedstock concentration:MDI and TDI precursor supply clusters in coastal China create vulnerability to port congestion and environmental shutdowns.
- Reactive system cost premiums:Two-component polyurethane formulations carry 40-60% higher raw material costs versus conventional solvent-based alternatives.
- Cure speed limitations:Waterborne systems require extended open times incompatible with high-throughput automotive assembly lines.
Strategic Opportunities
- India infrastructure buildout:BIS certification requirements for construction chemicals create first-mover advantages for compliant polyurethane suppliers targeting metro rail and commercial building projects.
- Battery pack bonding specialization:Thermal management adhesive demand from electric vehicle manufacturers in South Korea and Japan supports premium positioning for flame-retardant formulations.
- Vietnam furniture export hub:Hot melt polyurethane segments sustain volume growth through woodworking applications serving North American and European retail supply chains.
Industry Challenges
- Formulation chemist scarcity:Asia-Pacific universities produce insufficient polymer science graduates to meet reactive system R&D demands.
- Dual carbon compliance timelines:China's 2030 peak emission targets compress capital allocation windows for plant retrofits and solvent recovery investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyurethane Adhesives Market |
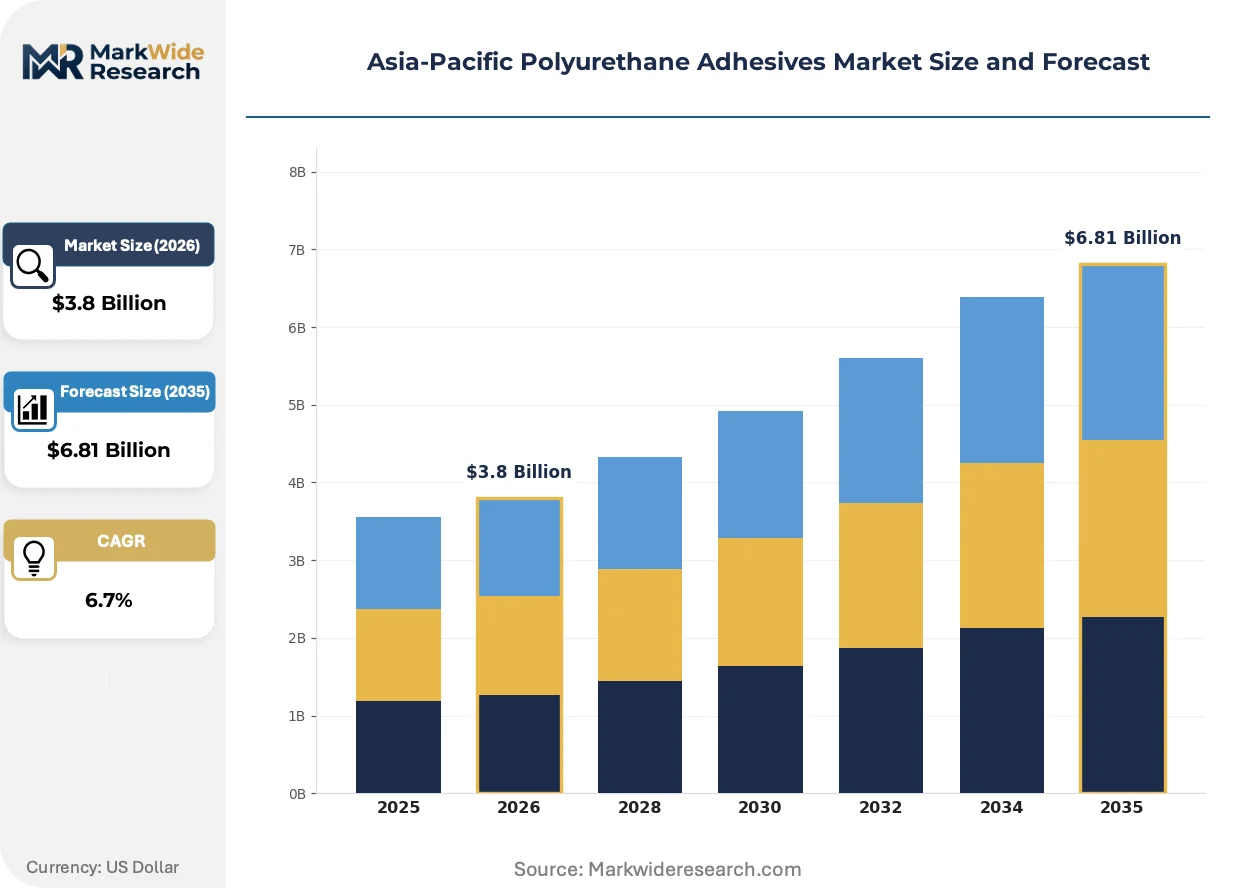
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solvent-based, Reactive, Hot Melt End User: Construction, Automotive, Electronics, Woodworking Application: Coating, Bonding, Sealing, Insulation Technology: Two-component, One-component, Spray, Extrusion |
| Companies Covered | Beijing Comens New Materials Co., Ltd., H.B. Fuller, 3M, BASF SE, Henkel AG & Co. KGaA, Sika AG, NANPAO RESINS CHEMICAL GROUP, Bostik, Pidilite Industries Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyurethane Adhesives Market Strategic Shifts
Reactive hot melt polyurethane technology is reshaping automotive and electronics assembly workflows across the region. Formulation advances now enable bond formation at lower activation temperatures while maintaining structural integrity under thermal cycling.
Reactive hot melt polyurethane systems combine initial thermoplastic bonding with subsequent moisture curing to achieve structural performance. Tier-1 automotive suppliers in South Korea and Japan deploy these systems for instrument panel and door module assembly. The technology is expanding into electric vehicle battery module bonding where rapid handling strength and long-term durability requirements converge.
China's MEE enforcement of GB standards is tightening real-time emissions monitoring at adhesive manufacturing facilities. Provincial environmental bureaus now mandate continuous VOC detection systems with automated shutdown triggers. Waterborne formulation producers in Jiangsu and Zhejiang provinces face accelerated compliance deadlines versus inland competitors.
Direct procurement relationships between automotive OEMs and adhesive formulators are displacing traditional distributor channels. Tier-1 suppliers in Japan and South Korea now specify approved chemical platforms rather than finished products. This pattern concentrates most visibly in electric vehicle programs where battery pack bonding specifications require joint development agreements between vehicle manufacturers and specialty chemical suppliers.
Asia-Pacific Polyurethane Adhesives Market Segmentation
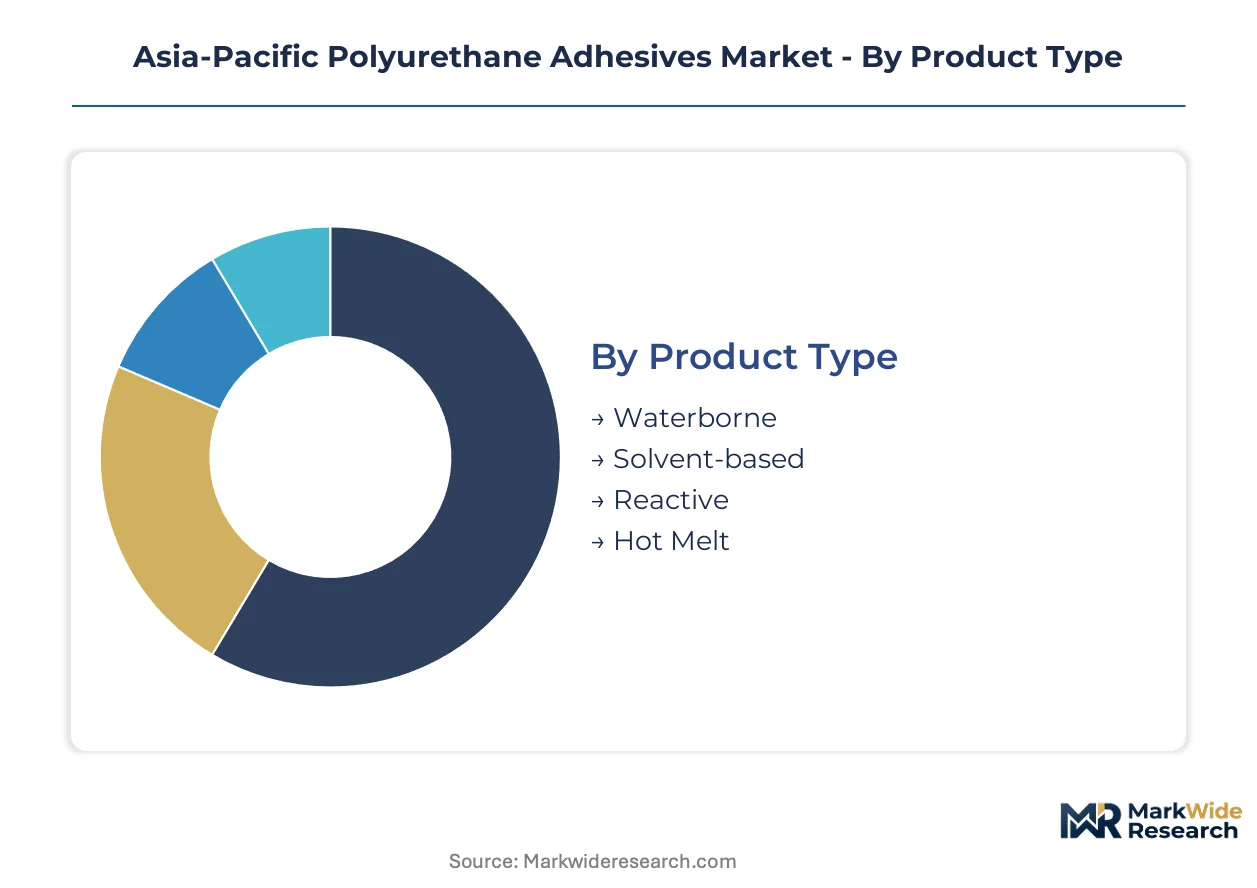
Formulation chemistry and application requirements drive distinct procurement patterns across Asia-Pacific polyurethane adhesives. Buyers prioritize VOC compliance, cure speed, and substrate compatibility when selecting between waterborne, reactive, and solvent-based systems.
Product Type:
Environmental compliance cost tiers now dominate procurement decisions, with GB standards forcing rapid migration from legacy solvent platforms.
- Waterborne:Polymer dispersions in aqueous carriers achieve structural shear strengths above 10 MPa through moisture-cure mechanisms. Eastern Chinese electronics manufacturers in Jiangsu and Zhejiang provinces now specify these systems exclusively for assembly line bonding to meet MEE enforcement timelines.
- Reactive:Two-component systems combining polyols with isocyanate hardeners deliver elastomeric bonds resistant to thermal cycling and chemical exposure. South Korean automotive OEMs specify reactive platforms for electric vehicle battery pack assembly where flame retardancy and structural integrity justify premium formulation costs.
- Solvent-based:Legacy formulations face margin compression from GB 33372 VOC limits and continuous emissions monitoring mandates.
- Hot Melt:Thermoplastic polyurethane segments sustain volume demand through woodworking applications serving Vietnam and Indonesia export furniture industries.
Waterborne leads on scale; reactive leads on momentum.
End User:
Application-specific performance requirements create divergent specification standards across manufacturing verticals.
- Automotive:Lightweighting mandates from Japan's METI and South Korea's K-EV100 initiative accelerate solvent-free adhesive adoption for composite bonding in electric vehicle platforms. Tier-1 suppliers now demand joint development agreements for battery thermal management applications.
- Electronics:Miniaturization trends in eastern Chinese manufacturing clusters drive demand for precision bonding with rapid handling strength. Waterborne moisture-cure systems displace solvent alternatives in smartphone and tablet assembly.
- Construction:India's BIS certification requirements for construction chemicals create compliance barriers for infrastructure applications including metro rail and commercial building projects.
- Woodworking:Export-oriented furniture processing in Vietnam and Indonesia sustains steady consumption of hot melt polyurethane segments for panel lamination and edge banding.
Automotive commands premium positioning; electronics expands most quickly.
Application:
Functional performance requirements determine formulation selection across coating, bonding, sealing, and insulation tasks.
- Bonding:Structural applications demand tensile shear strengths exceeding 10 MPa with Shore A hardness of 40–90. Reactive systems dominate automotive and electronics assembly where load-bearing performance is non-negotiable.
- Sealing:Elastomeric polyurethane formulations provide chemical resistance and thermal cycling durability for industrial equipment and transportation applications.
- Coating:Protective layers leverage polyurethane toughness for abrasion resistance across metal and composite substrates.
- Insulation:Thermal and acoustic management applications in building construction and appliance manufacturing utilize foam-in-place and spray-applied systems.
Bonding leads on scale; sealing leads on momentum.
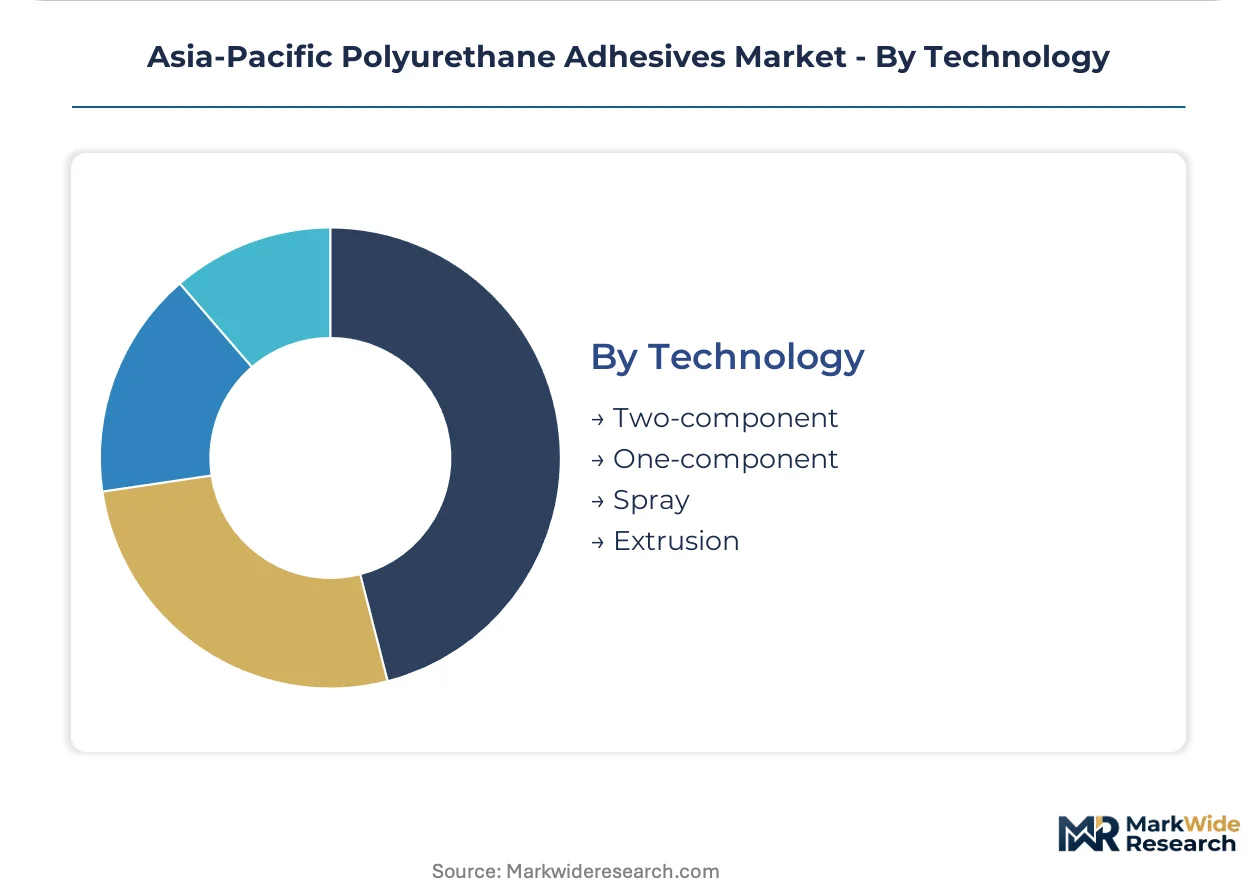
Technology:
Processing equipment compatibility and line speed requirements shape technology adoption across manufacturing operations.
- Two-component:Meter-mix-dispense systems deliver precise ratio control for high-performance structural applications. South Korean battery manufacturers specify these platforms for module assembly where pot life and cure speed must balance.
- One-component:Pre-formulated systems simplify handling and reduce equipment capital requirements for mid-volume operations.
- Spray:Atomized application enables rapid coverage of large surface areas in construction and transportation manufacturing.
- Extrusion:Bead deposition systems support automated assembly lines with consistent volume control for woodworking and furniture applications.
Two-component leads on scale; spray leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer science graduates from Shanghai Jiao Tong University and Tsinghua University anchor formulation R&D across the region. Eastern Chinese manufacturing clusters absorb the majority of technical talent, while South Korean and Japanese universities supply specialized automotive bonding expertise.
China
Electric vehicle battery pack assembly and electronics miniaturization drive waterborne formulation demand. MEE enforcement of GB 33372 VOC limits tightens emissions monitoring with automated shutdown triggers at Jiangsu province facilities. Shanghai and Zhejiang manufacturing corridors concentrate moisture-cure system production for smartphone and tablet assembly lines.
Japan
Automotive lightweighting programs for composite bonding sustain reactive system procurement. METI fuel economy standards and Industrial Safety and Health Act reporting shape isocyanate handling protocols. Nagoya and Osaka industrial zones host Tier-1 supplier joint development agreements for electric vehicle platform specifications.
South Korea
K-EV100 initiative accelerates solvent-free adhesive adoption across battery thermal management applications. MFDS hazardous substance classifications coordinate with Ministry of Environment on import clearances for foreign suppliers. Busan-Ulsan manufacturing belt concentrates flame-retardant formulation production for automotive OEM direct procurement.
India
Metro rail infrastructure and commercial building projects create construction chemical demand. BIS certification requirements for construction chemicals establish compliance barriers for infrastructure adhesive entrants. Maharashtra and Gujarat industrial corridors attract first-mover polyurethane suppliers targeting public works procurement.
Vietnam
Export-oriented furniture processing sustains hot melt polyurethane consumption for North American retail supply chains. Woodworking applications dominate panel lamination and edge banding demand. Ho Chi Minh City and Binh Duong province manufacturing zones concentrate thermoplastic system distribution for woodworking exporters.
Asia-Pacific Polyurethane Adhesives Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry tiers. The vendor base stratifies around three structural positions: backward-integrated chemical majors controlling isocyanate precursor supply, application-focused formulators serving automotive and electronics verticals, and regional distributors dominating woodworking and footwear channels. Strategic moves concentrate on capacity expansion in waterborne production and geographic expansion through Southeast Asian distribution partnerships.
Among diversified chemical majors, BASF SE and Henkel AG & Co. KGaA occupy positions exemplifying backward-integrated and application-focused archetypes respectively. NANPAO RESINS CHEMICAL GROUP represents the regional specialist tier with concentrated distribution across Taiwan and Southeast Asian woodworking markets. These three anchors illustrate how competitive positioning fragments across supply chain control, technical specification depth, and channel density.
| Leading Market Players |
|---|
| Beijing Comens New Materials Co., Ltd. |
| H.B. Fuller |
| 3M |
| BASF SE |
| Henkel AG & Co. KGaA |
| Sika AG |
| NANPAO RESINS CHEMICAL GROUP |
| Bostik |
| Pidilite Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
MDI and TDI precursor costs cascade through polyurethane adhesive pricing tiers from coastal Chinese petrochemical complexes to downstream formulators, with backward-integrated majors capturing margin buffers that solvent-dependent specialists cannot replicate under tightening GB 33372 compliance deadlines.
Pricing Analysis
Product-plus-technical-service bundling separates reactive system suppliers from commodity waterborne competitors across the Asia-Pacific polyurethane adhesives market. Price differentiation rests on formulation certification grade and joint development agreement depth, with South Korean automotive OEMs showing lowest price sensitivity for flame-retardant battery bonding specifications while Vietnamese woodworking exporters drive hardest volume negotiations for hot melt segments. Pricing pressure stems from MEE-mandated emissions control investments compressing legacy solvent-based margins. Three-tier pricing structure across premium reactive, standard waterborne, and economy solvent-based levels stratifies procurement specifications across end-use verticals.
Supply Chain Analysis
Isocyanate feedstock supply rests on concentrated MDI and TDI production clusters in coastal China, with supplementary precursor capacity in Japan and South Korea. Raw material dependencies span aromatic isocyanates, polyether polyols, and specialty flame-retardant additives. Single-source vulnerability concentrates around Shanghai port logistics chokepoints and Jiangsu province environmental shutdown triggers. Distribution runs through direct procurement relationships displacing traditional distributor channels, particularly for automotive OEM specification development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific polyurethane adhesives offer margin expansion through waterborne formulation premiumization and captive isocyanate supply integration, as GB standards compliance costs filter out non-integrated competitors.
For Market Incumbents: Hedge against solvent-based margin erosion by accelerating waterborne capacity additions in Zhejiang province ahead of inland compliance deadlines. Deepen backward integration into polyol precursors to offset MDI price volatility from Shanghai port congestion. Prioritize joint development agreements with South Korean battery manufacturers to lock in flame-retardant specification premiums before reactive system competition intensifies. For New Entrants and Emerging Players: Mid-tier Indian construction chemical buyers underserved by BIS-certified polyurethane suppliers present immediate white-space opportunity. Target Maharashtra and Gujarat infrastructure corridors with pre-certified adhesive systems for metro rail applications. Enter through technical partnership with local distributors holding existing public works relationships rather than direct specification challenges against entrenched incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional waterborne specialists with captive Jiangsu or Zhejiang production assets because GB 33372 enforcement is accelerating solvent-based plant obsolescence. Focus acquisition screening on formulators with existing MEE compliance infrastructure and automotive OEM qualification pipelines. Watch for MFDS hazardous substance reclassification announcements as inflection signal for South Korean import clearance disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Precursors | BASF's Ludwigshafen-to-Shanghai supply chain demonstrates margin capture from captive MDI supply. |
| Waterborne Capacity Expansion | Jiangsu province facilities gain compliance runway advantage over inland competitors under MEE enforcement timelines. |
| Joint Development Agreement | South Korean automotive OEMs now specify chemical platforms rather than finished products for battery bonding. |
| BIS Certification Investment | First-mover certification for construction chemicals unlocks Maharashtra metro rail procurement opportunities. |
| Reactive Hot Melt Technology Licensing | Lower activation temperature formulations enable displacement of conventional systems in Japanese instrument panel assembly. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down isocyanate precursor supply tracking forms the analytical core of this study. Primary interviews with polyurethane formulator R&D directors, automotive OEM procurement leads, and woodworking distributor channel managers combined with secondary validation from China customs trade data, ACC regional chemical reports, and SEC 10-K filings from diversified adhesive majors. Triangulation across these sources anchors volume estimates for waterborne, reactive, solvent-based, and hot melt formulation segments.
Historical trendline analysis of adhesive consumption patterns across automotive lightweighting, electronics assembly, construction, and woodworking verticals informed projection framework development. Segmentation dimensions modeled include formulation chemistry tier, end-use industry, cure mechanism technology, and regional manufacturing cluster. CAGRs derive from regression analysis of precursor supply growth, OEM platform rollout schedules, and regulatory compliance cost trajectories across the projection horizon. Electric vehicle battery pack bonding specifications and GB standards enforcement timelines served as key forecast inputs.
Underlying measurement precision varies by segment; waterborne and reactive systems carry tighter precision than legacy solvent-based categories due to more concentrated supplier reporting. Forecasts reflect documented assumptions about MEE enforcement consistency, K-EV100 initiative funding continuity, and isocyanate precursor supply stability from Shanghai corridor. A small set of triggers—including MFDS reclassification announcements, BIS certification timeline shifts, and Jiangsu environmental bureau shutdown orders—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Cold Seal Adhesives Market