
 North America Turbomachinery Control Systems Market | 2026-2036
North America Turbomachinery Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Turbomachinery Control Systems Market Analytics
Silicon carbide power electronics is realigning turbomachinery control architectures by enabling higher switching frequencies and reduced thermal losses in variable-speed drives. Siemens Energy AG leverages integrated digital twin platforms to anchor long-term service contracts across North American utility fleets. Woodward Inc. specializes in governor and fuel-control systems for aeroderivative gas turbines, occupying a defensible niche in peaking-power applications.
Turbomachinery control systems encompass the sensors, actuators, controllers, and software algorithms that regulate rotational speed, load, vibration, and thermal performance in turbines operating above 3,000 RPM. These systems employ redundant processor architectures with sub-10-millisecond loop times to prevent surge, stall, or overspeed events in compressors and generators. Gas turbine control technology leads absolute spending due to the installed base of combined-cycle plants across the United States, while programmable logic control is displacing legacy analog panels in retrofit programs across Canadian hydroelectric stations. Digital control platforms capture the fastest expansion as operators seek remote diagnostics and predictive maintenance integration.
The EPA enforces emissions monitoring and reporting under the Clean Air Act, compelling operators to upgrade combustion controls for NOx compliance. NERC reliability standards mandate cybersecurity hardening of turbine control networks, reshaping procurement specifications for critical infrastructure assets. OSHA process safety management rules govern turbomachinery maintenance protocols in petrochemical facilities, influencing spare-parts inventory and technician certification requirements. Stakeholders must weigh the capital efficiency of phased retrofits against the operational risk of extended analog system obsolescence.
Market Dynamics
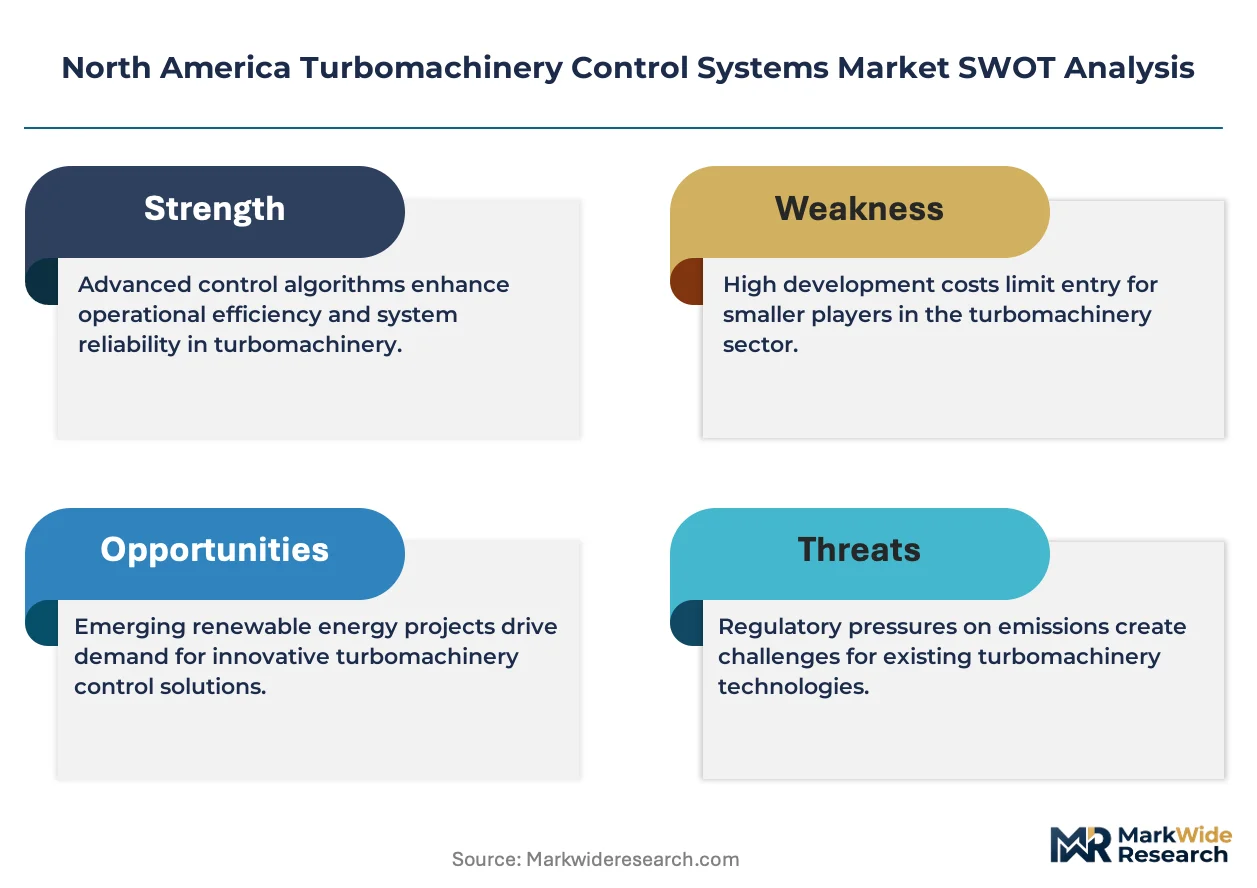
Silicon carbide power electronics is compressing thermal management costs in variable-speed turbomachinery drives, forcing incumbent analog control architectures toward obsolescence across North American utility and petrochemical fleets.
Growth Catalysts
- EPA Clean Air Act enforcement:Stationary source emissions mandates compel combustion control upgrades in combined-cycle gas turbines, accelerating digital retrofit spending across US power generation.
- Texas Gulf Coast petrochemical corridor:Expansive ethylene and ammonia capacity additions drive demand for anti-surge compressor controls in high-horsepower applications.
- Silicon carbide semiconductors:Higher switching frequencies and reduced switching losses enable compact inverter designs that shrink footprint in offshore platform installations.
Market Restraints
- Neodymium and dysprosium price volatility:Rare-earth magnet cost swings destabilize permanent-magnet synchronous motor supply chains for integrated turbomachinery drives.
- Single-source dependency for high-temperature pressure sensors:Concentrated supply of aerospace-grade sapphire sensor elements creates procurement risk for aeroderivative turbine OEMs.
- Cybersecurity certification delays:NERC CIP-013 supply chain security standards extend vendor qualification timelines for critical infrastructure control components.
Strategic Opportunities
- Canadian hydroelectric modernization:Aging Kaplan and Francis turbine fleets in Quebec and British Columbia present untapped demand for digital governor replacements.
- Hydrogen blending combustion controls:Emerging H2-ready gas turbine specifications create white space for fuel-flexible control algorithms in California and Texas peaker plants.
- Remote diagnostics platforms:Cloud-based vibration monitoring and predictive maintenance integration open recurring revenue streams beyond hardware sales.
Industry Challenges
- Control systems cybersecurity engineering:NERC CIP-005 and CIP-007 compliance requirements outpace available talent pools for industrial control network hardening.
- Legacy analog-to-digital migration complexity:Phased retrofit coordination with operational turbine availability constraints extends project timelines and elevates execution risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Turbomachinery Control Systems Market |
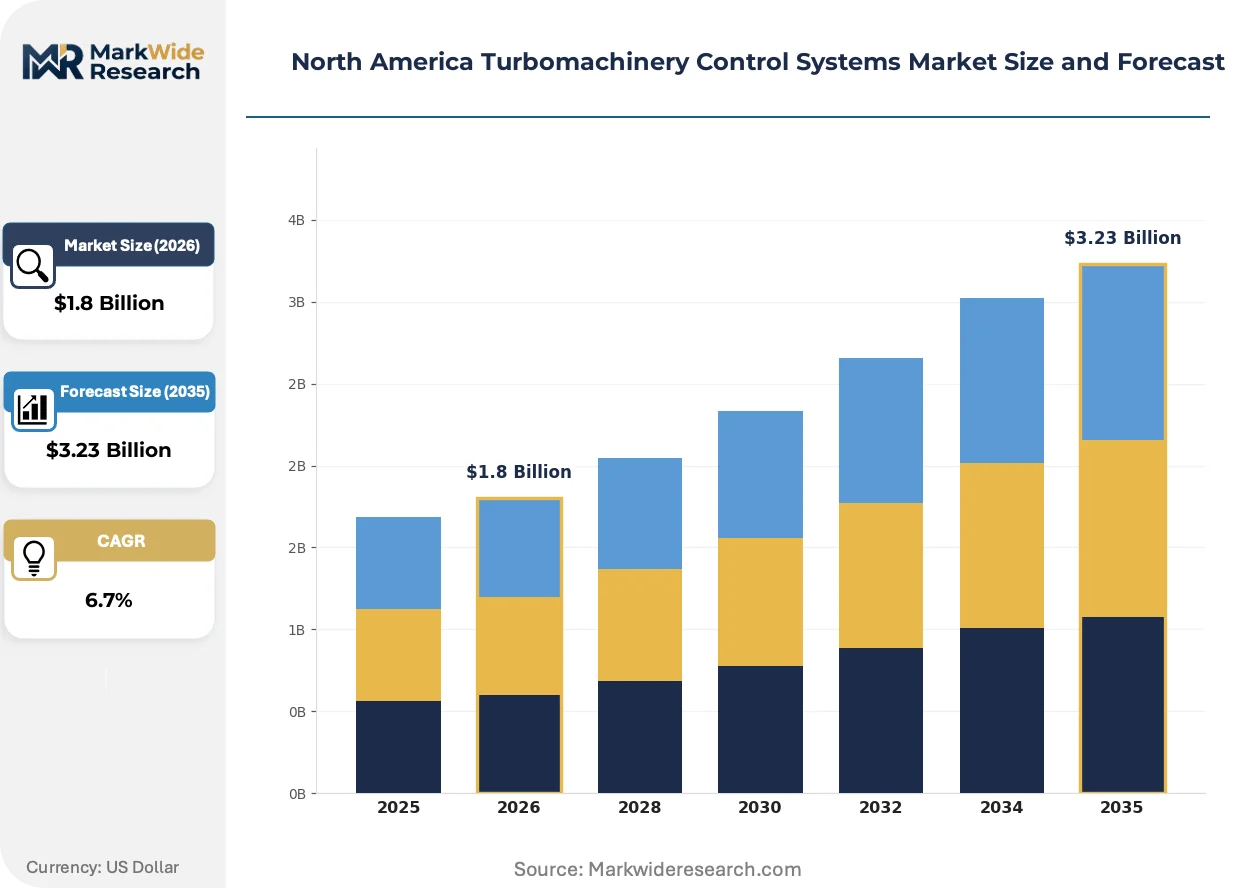
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
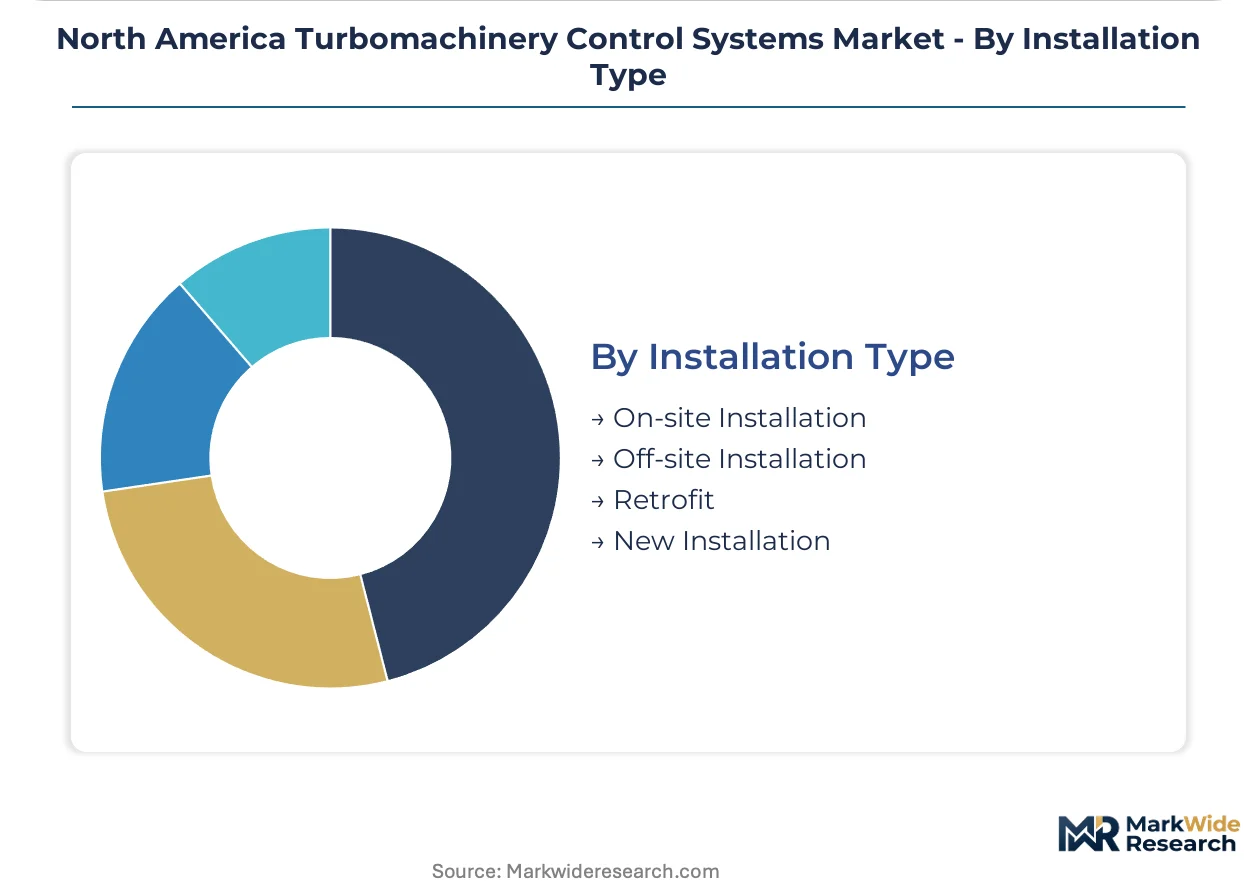
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Hydraulic Turbines, Wind Turbines Control Technology: Digital Control, Analog Control, Distributed Control, Programmable Logic Control End User: Power Generation, Oil & Gas, Marine, Aerospace Installation Type: On-site Installation, Off-site Installation, Retrofit, New Installation |
| Companies Covered | Siemens Energy AG, Compressor Controls Corporation, Rockwell Automation Inc., Woodward Inc., General Electric Company, ABB Ltd., Emerson Electric Co., Baker Hughes Co., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Turbomachinery Control Systems Market Evolving Landscape
Digital twin integration is compressing commissioning cycles and anchoring long-term service relationships across North American turbomachinery operators. Three interconnected developments are reshaping competitive positioning.
Model-based predictive control algorithms are automating surge avoidance in centrifugal compressors by processing real-time inlet flow dynamics and discharge pressure transients. US Gulf Coast petrochemical operators deploy these systems in ethylene cracker charge gas compressors, reducing manual intervention during load swings. The technology is automating operational decision-making that previously required dedicated control room staffing.
EPA's tightened NOx emissions standards for stationary gas turbines under the Clean Air Act are mandating advanced combustion monitoring and active tuning systems. Industrial operators must install continuous emissions monitoring hardware with closed-loop fuel-air ratio adjustments to maintain compliance. Combined-cycle plants in Texas and California face the steepest retrofit timelines due to non-attainment zone designations.
Power generation utilities are unbundling long-term service agreements from initial control system procurement, favoring multi-vendor maintenance strategies. Independent service providers now capture aftermarket work that OEMs historically retained through captive parts and proprietary software locks. This behavior shift concentrates in merchant power plants across PJM and ERCOT territories where asset owners prioritize operational flexibility over single-source dependencies.
North America Turbomachinery Control Systems Market Segmentation
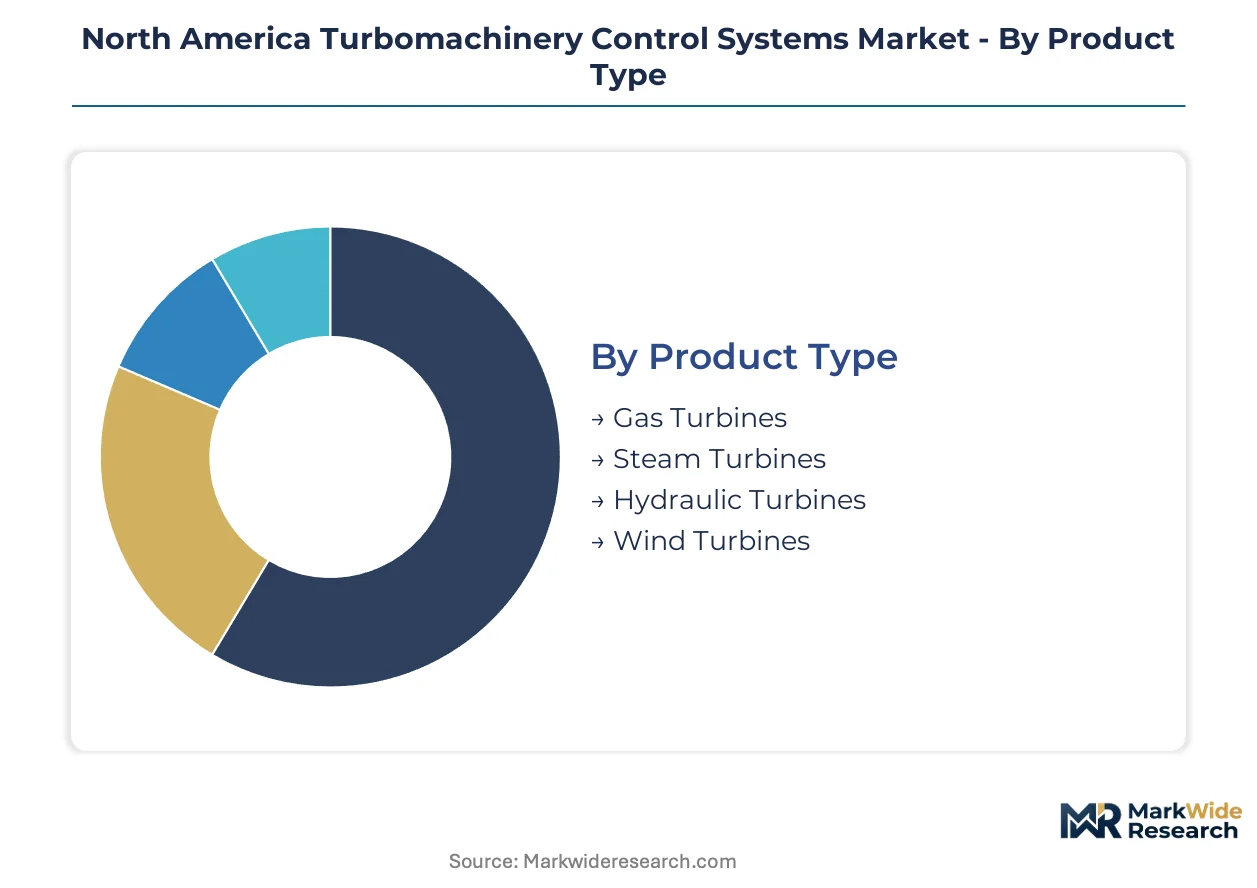
Control system procurement in North American turbomachinery diverges sharply by turbine thermodynamics, automation architecture, operational environment, and capital deployment model. Segment boundaries determine vendor qualification requirements, cybersecurity compliance tiers, and service contract structures.
Product Type:
Buyer priorities shift from baseload efficiency in combined-cycle plants to transient response in peaking units and renewable integration.
- Gas Turbines:Combined-cycle and simple-cycle installations dominate capital deployment across Texas and Gulf Coast petrochemical corridors. EPA NOx enforcement and hydrogen blending roadmaps are accelerating combustion control upgrades in existing F-class and H-class fleets.
- Steam Turbines:Legacy coal and nuclear steam turbine governor retrofits concentrate in Midwestern US utilities and Canadian provincial power authorities. Aging mechanical-hydraulic control replacement timelines extend 10-15 years due to operational availability constraints.
- Hydraulic Turbines:Kaplan and Francis turbine digital governor demand clusters in Quebec, British Columbia, and Pacific Northwest federal hydroelectric projects.
- Wind Turbines:Pitch and yaw control system standardization lags behind gas turbine sophistication; nacelle converter upgrades drive aftermarket activity in Texas and Great Plains wind corridors.
Volume sits with gas turbines; growth tilts toward hydraulic turbine digital retrofits as Canadian hydroelectric modernization accelerates.
Control Technology:
Architecture selection determines cybersecurity surface area, spare parts longevity, and technician certification requirements.
- Digital Control:Integrated turbine-generator control platforms with sub-10-millisecond loop times anchor new combined-cycle procurement and comprehensive retrofits. Remote diagnostics integration and predictive maintenance APIs are becoming standard specifications in utility RFPs.
- Analog Control:Obsolescence risk concentrates in 1980s-era mechanical-hydraulic governors and pneumatic positioners still operating in Canadian hydroelectric and US industrial captive power plants. Phased migration strategies balance operational continuity against parts scarcity.
- Distributed Control:Plant-wide DCS integration appeals to integrated petrochemical operators seeking unified HMI layers across turbine, compressor, and process unit control.
- Programmable Logic Control:Compact PLC architectures displace relay logic in auxiliary systems and balance-of-plant equipment; IEC 61131-3 programming standards reduce vendor lock-in.
Procurement velocity favors digital control platforms; PLC architectures gain share fastest in balance-of-plant standardization programs.
End User:
Operational duty cycles and regulatory exposure reshape control system specification priorities across verticals.
- Power Generation:Merchant plant operators in PJM and ERCOT territories prioritize operational flexibility and multi-fuel capability. NERC CIP cybersecurity mandates dominate procurement specifications for critical infrastructure designation.
- Oil & Gas:Anti-surge compressor controls and subsea turbomachinery drive demand in Gulf Coast ethylene crackers and offshore platform installations. Process safety management rules govern maintenance protocols and spare parts inventory.
- Marine:Naval and commercial propulsion turbine controls face MIL-SPEC and IMO emissions compliance dual requirements; fleet standardization programs concentrate procurement volume.
- Aerospace:Aeroderivative gas turbine governor and fuel-control systems serve peaking power and mechanical drive applications; FAA certification requirements limit vendor qualification pools.
Revenue concentration rests with power generation; expansion tilts toward oil and gas as petrochemical capacity additions accelerate.
Installation Type:
Capital deployment timing determines integration complexity and operational risk exposure.
- Retrofit:Digital control replacement in operational turbines demands phased cutover strategies to maintain availability. EPA emissions deadlines and NERC reliability standards are compressing project timelines for aging gas turbine fleets.
- New Installation:Greenfield combined-cycle and petrochemical projects specify integrated digital twin platforms from commissioning. Long-term service agreement unbundling is shifting aftermarket capture toward independent service providers.
- On-site Installation:Field assembly and commissioning of control cabinets persists for large-frame gas turbines and hydroelectric governors where transport constraints apply.
- Off-site Installation:Modular skid-mounted control systems reduce offshore platform and remote site construction schedules; factory acceptance testing precedes site integration.
Project flow favors retrofit activity; specification innovation concentrates in new installations with integrated digital twin deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for turbomachinery control systems concentrates along the US Gulf Coast petrochemical corridor and Canadian hydroelectric basins, with regulatory enforcement timelines compressing procurement schedules across both markets.
United States
Combined-cycle gas turbine retrofits and ethylene cracker expansions drive procurement volume in Texas and Louisiana. EPA Clean Air Act enforcement mandates NOx compliance upgrades in non-attainment zones, accelerating digital combustion control deployments. The Houston Ship Channel petrochemical cluster anchors demand for anti-surge compressor controls in high-horsepower applications.
Canada
Aging Kaplan and Francis turbine fleets in Quebec and British Columbia require digital governor replacements to maintain grid reliability. Provincial power authorities face extended 10-15 year migration timelines due to operational availability constraints. The Churchill Falls and La Grande hydroelectric complexes concentrate procurement activity for programmable logic control upgrades.
Mexico
Pemex refinery modernization and private power generation investments create demand for integrated turbine-generator control platforms. Energy reform implementation opens procurement channels for foreign control system vendors in combined-cycle greenfield projects. The Tula-Villahermosa petrochemical corridor attracts anti-surge control investments for natural gas processing infrastructure.
North America Turbomachinery Control Systems Market Competitive Landscape
Long-term service agreement unbundling dominates the current landscape as asset owners prioritize operational flexibility over single-source dependencies. The vendor base organizes around three strategic archetypes: integrated OEMs with captive digital twin platforms, specialized governor and fuel-control specialists, and automation conglomerates with distributed control system portfolios. Technology licensing partnerships and backward integration into silicon carbide power electronics represent the primary competitive vectors reshaping procurement specifications.
Within the integrated OEM tier, Siemens Energy AG and General Electric Company exemplify platform-centric positioning through digital twin anchoring strategies. Woodward Inc. occupies a defensible specialization position in aeroderivative gas turbine governor systems, while Emerson Electric Co. and Rockwell Automation Inc. represent automation-focused archetypes with plant-wide control integration capabilities. These named entities illustrate how competitive positioning fragments across technology stacks rather than consolidating around unified hardware specifications.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Compressor Controls Corporation |
| Rockwell Automation Inc. |
| Woodward Inc. |
| General Electric Company |
| ABB Ltd. |
| Emerson Electric Co. |
| Baker Hughes Co. |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
EPA Clean Air Act enforcement gates qualified supply access and premium-tier pricing power for turbomachinery control systems across North American power generation and petrochemical installations. Compliance-grade combustion control hardware commands pricing premiums while non-certified suppliers face exclusion from utility procurement channels.
Pricing Analysis
Volume concentrates in standard-tier digital control retrofits while margins concentrate in premium-tier integrated digital twin platforms with long-term service bundling. Price differentiation rests on NERC CIP cybersecurity certification tier and silicon carbide power electronics integration depth. Cost compression in analog-to-digital migration projects intensifies as EPA emissions deadlines compress vendor qualification timelines. Merchant power operators in ERCOT territories exhibit highest price sensitivity due to unbundled procurement strategies, while integrated petrochemical operators accept premium pricing for plant-wide DCS unification.
Supply Chain Analysis
Regional distribution centers in Houston, Calgary, and Mexico City anchor hub-and-spoke patterns for spare parts and field service deployment across North American turbomachinery fleets. Manufacturing concentration centers on Germany, the United States, and Japan for high-reliability pressure sensors and processor architectures. Raw material dependencies span silicon carbide wafers, aerospace-grade sapphire sensor elements, and rare-earth magnet feedstocks for integrated drive systems. Single-source vulnerability for high-temperature pressure sensors creates procurement risk concentration. Distribution runs through OEM captive channels and independent service provider networks with diverging aftermarket capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide semiconductor fabrication capacity constraints prop pricing power for qualified control system vendors across the forecast horizon. Supply scarcity in high-temperature sensor substrates reinforces margin protection for incumbents with backward-integrated component sourcing.
For Market Incumbents: Hedge against independent service provider encroachment by anchoring digital twin platforms to long-term combustion monitoring contracts. Secure captive supply of aerospace-grade sapphire sensor elements through direct sourcing agreements with Japanese and German substrate manufacturers. Defend position against automation conglomerate expansion by deepening cybersecurity certification investment for NERC CIP-013 compliance. For New Entrants and Emerging Players: EPA Clean Air Act enforcement in Texas and California opens a window for specialized combustion control algorithm developers to penetrate combined-cycle retrofit procurement. Target Canadian hydroelectric digital governor replacement timelines in Quebec and British Columbia where incumbent presence remains thin. Pursue cloud-based predictive maintenance platform licensing as the primary go-to-market angle to bypass hardware qualification barriers. For Investors and Strategic Acquirers: Hydrogen blending combustion control contract awards in Texas peaker plants are the leading indicator that fuel-flexible algorithm specialists warrant premium valuation multiples. Position acquisition screening around aeroderivative governor specialists with FAA certification and Woodward Inc. supply relationships. Monitor NERC CIP-005 engineering talent scarcity as the signal for cybersecurity-hardened control network service providers achieving pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Integration | Enables compact inverter designs that reduce offshore platform installation footprint and thermal management cost. |
| Digital Twin Platform Deployment | Compresses commissioning cycles and anchors recurring service revenue streams beyond initial hardware procurement. |
| NERC CIP Cybersecurity Certification Investment | Qualifies vendors for critical infrastructure procurement channels with mandatory compliance specifications. |
| Hydrogen-Ready Combustion Control Development | Positions suppliers for H2 blending roadmaps in California and Texas peaking power applications. |
| Canadian Hydroelectric Modernization Partnership | Captures digital governor replacement demand in Quebec and British Columbia aging turbine fleets. |
Research Methodology
Independent corroboration across utility planning officers, petrochemical plant engineers, EPC contractors, and aftermarket service directors underwrites the qualitative findings in this analysis. Primary fieldwork combined with secondary validation from FERC filings, EIA power plant databases, EPA emissions compliance records, and NERC reliability standard documentation established segment sizing. Bottom-up project pipeline enumeration and top-down utility capital expenditure triangulation anchored market estimates.
Comparable-period anchoring to historical gas turbine retrofit cycles and hydroelectric modernization timelines structured the projection horizon. Segmentation modeling spanned turbine thermodynamics, control technology architecture, end-use vertical, and installation type across the analysis window. CAGRs derived from unit deployment forecasts, average selling price trajectories, and service revenue attachment rates. Forecast inputs incorporated EPA compliance deadline schedules and provincial power authority replacement timelines.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide power electronics would alter the outlook if wide-bandgap semiconductor supply constraints persist longer than baseline assumptions. Forecasts reflect documented assumptions regarding NERC cybersecurity enforcement intensity and hydrogen blending specification adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
China Industrial Sensors Market