
 Turbomachinery Control Systems Market | 2026-2036
Turbomachinery Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Turbomachinery Control Systems Market Outlook
Power plant leasing and energy-as-a-service contracting is reconfiguring capital deployment patterns for turbomachinery automation. Siemens Energy AG anchors European retrofit programs through long-term service agreements. Emerson Electric Co. leverages its Ovation platform to dominate North American utility upgrades. Honeywell International Inc. competes in the Middle East through integrated control-and-safety packages.
Turbomachinery control systems integrate sensors, actuators, and digital controllers to regulate rotational speed, load, and thermal stress in dynamic fluid-energy machines, typically operating at response cycles under 50 milliseconds. These systems prevent surge, stall, and overspeed events that destroy billion-dollar rotating equipment. Distributed control systems command the largest installed base across power generation, though supervisory control systems are gaining share in offshore oil and gas where centralized monitoring reduces platform staffing. Human-machine interfaces capture disproportionate margin pools as operators demand augmented-reality diagnostics and predictive visualization layers.
EPA rules under the Clean Air Act mandate continuous emissions monitoring tied to turbine control logic, while IEC 61508 and IEC 61511 standards enforce safety integrity levels on shutdown systems. The EU F-Gas Regulation restricts fluorinated coolant use in turbomachinery ancillary systems, forcing control vendors to validate alternative thermal management protocols. Stakeholders must weigh the capital cost of control system modernization against the operational risk of regulatory non-compliance and unplanned outage penalties.
Market Dynamics
Power generation utilities in Asia are accelerating turbine automation retrofits to meet tightening emissions mandates and extend aging fleet lifespans. State-owned energy groups in China dominate procurement volumes as they modernize control platforms across combined-cycle and coal-gasification plants.
Growth Catalysts
- EPA Clean Air Act enforcement:Continuous emissions monitoring mandates tied to turbine control logic drive replacement cycles in US fossil fuel plants.
- Gas turbine fleet aging:Decades-old rotating machinery in North American and European baseload facilities requires upgraded surge protection and thermal stress management systems.
- IEC 61508 safety integrity requirements:Functional safety certification for shutdown systems creates specification pull for certified hardware in new installations.
Market Restraints
- Semiconductor supply concentration:Advanced control processors and FPGA chips source predominantly from East Asian foundries, exposing lead time volatility.
- Specialized field engineering scarcity:Commissioning turbomachinery controls demands rare expertise in rotordynamics and safety instrumented systems.
- Long asset replacement cycles:Gas turbines operate 25-35 years, compressing control system refresh frequency versus other industrial automation categories.
Strategic Opportunities
- Offshore platform staffing reduction:Supervisory control systems with centralized monitoring displace distributed architectures in North Sea and Gulf of Mexico oil and gas.
- Augmented reality diagnostic layers:Human-machine interface vendors capture margin expansion by overlaying predictive visualization on existing control networks.
- EU F-Gas Regulation compliance:Alternative thermal management protocol validation opens replacement demand for ancillary cooling system controls.
Industry Challenges
- IEC 61511 certification timelines:Safety instrumented system validation delays project commissioning by 8-14 months in complex retrofit environments.
- Legacy DCS integration friction:Proprietary communication protocols in installed distributed control systems obstruct seamless third-party controller insertion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbomachinery Control Systems Market |
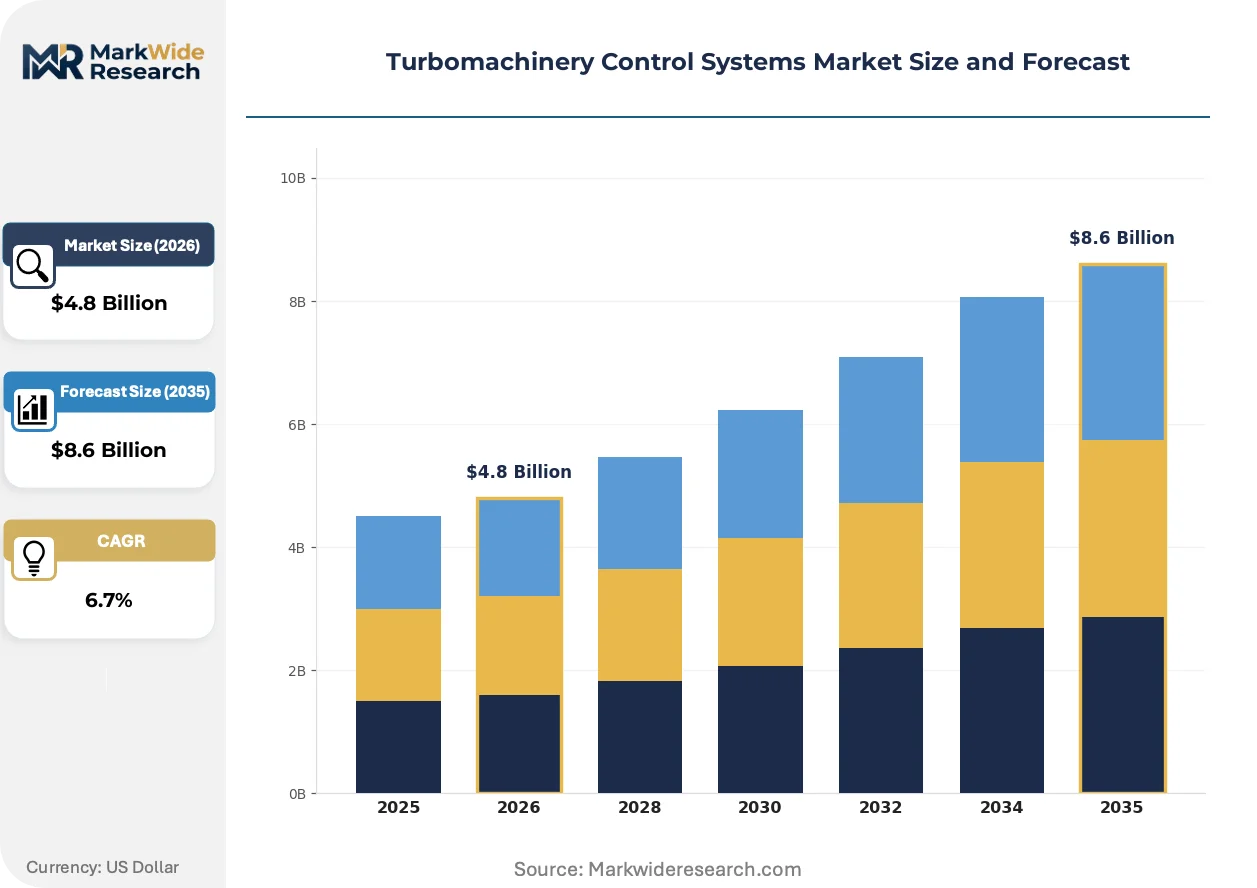
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
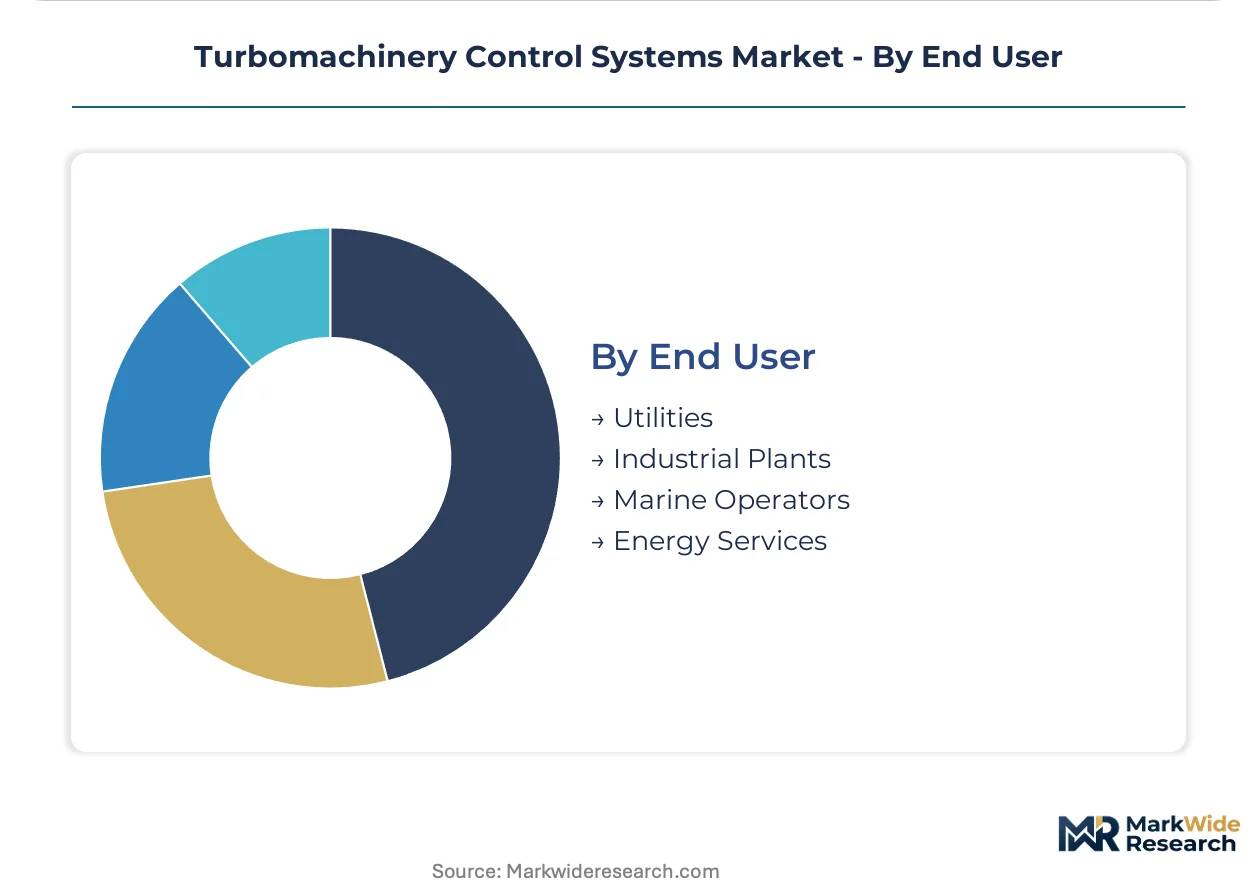
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Hydropower Turbines, Compressors Technology: Distributed Control Systems, Programmable Logic Controllers, Human-Machine Interfaces, Supervisory Control Systems Application: Power Generation, Oil & Gas, Aerospace, Manufacturing End User: Utilities, Industrial Plants, Marine Operators, Energy Services |
| Companies Covered | Emerson Electric Co., Rockwell Automation Inc., Honeywell International Inc., ABB Ltd., Siemens Energy AG, General Electric Co., Schneider Electric, Woodward Inc., Compressor Controls Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbomachinery Control Systems Market Strategic Shifts
Digital twin architectures and edge computing are compressing control response cycles while enabling predictive maintenance. Vendors race to embed machine learning inference directly on turbine-mounted controllers.
Model-based control software is virtualizing traditional hardware-dependent protection schemes. Power utilities in Germany and Japan deploy these platforms to simulate surge margins without dedicated analog safety relays. The shift is virtualizing capital allocation from physical redundancy toward software-defined resilience.
EU F-Gas Regulation restrictions on fluorinated coolants force control vendors to validate alternative thermal management protocols. Turbomachinery ancillary systems must demonstrate compatibility with low-global-warming-potential refrigerants. European OEMs accelerate qualification programs to maintain CE marking eligibility.
Energy-as-a-service contracting is unbundling control system ownership from turbine asset ownership. Independent power producers in Texas and California prefer operational expenditure models over capital-intensive automation purchases. Leasing structures transfer obsolescence risk to vendors while locking in long-term service revenue streams.
Turbomachinery Control Systems Market Segmentation
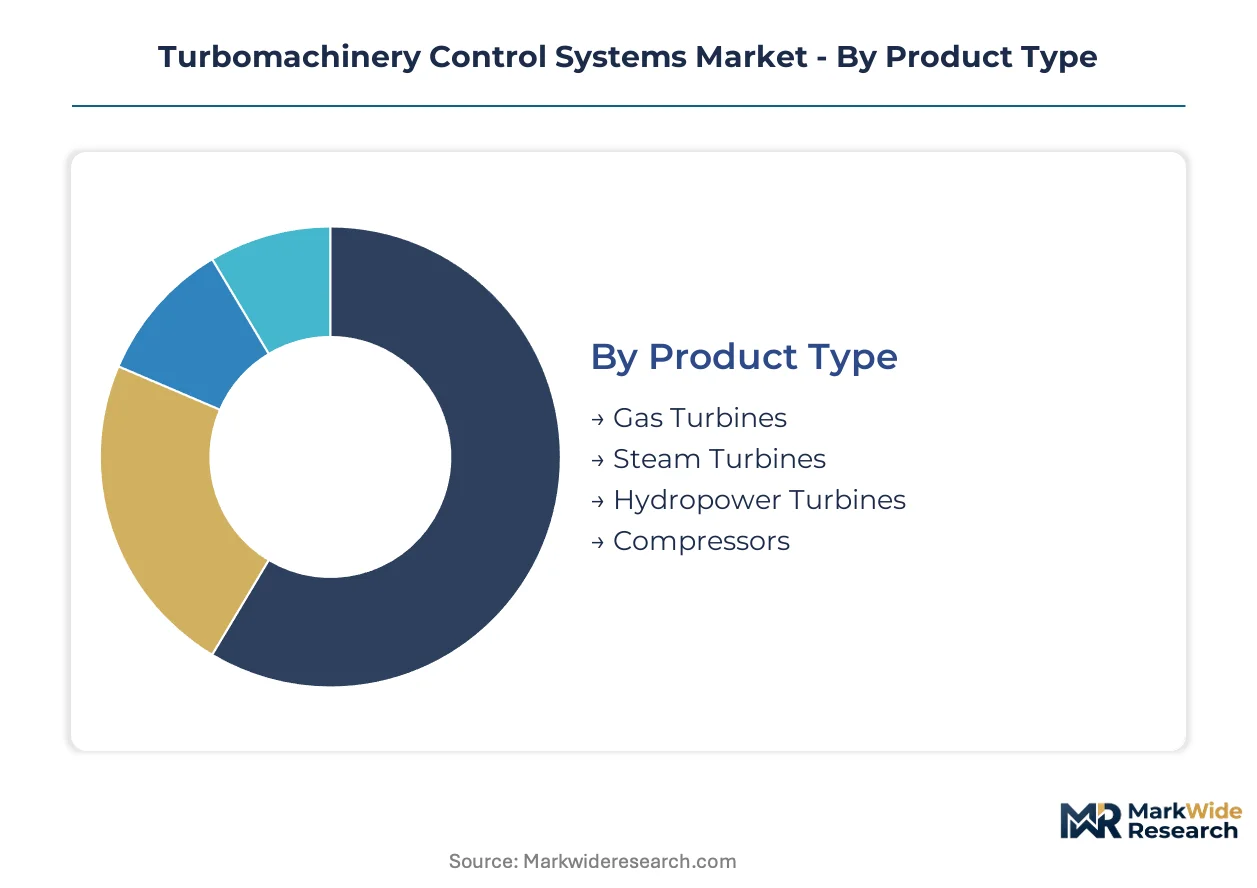
Segmentation in turbomachinery control systems reveals distinct procurement patterns across equipment vintages and operational criticality. Control platform selection varies sharply between baseload power utilities seeking longevity and offshore operators prioritizing remote diagnostics.
Product Type:
Mature rotating equipment categories dominate installed base volumes while emerging turbine technologies reshape specification requirements.
- Gas Turbines:Combined-cycle and simple-cycle units require surge protection algorithms and thermal stress governors with sub-50 millisecond response cycles. Procurement concentrates in Chinese state-owned energy groups executing fleet modernization retrofits under tightening MEE emissions mandates.
- Steam Turbines:Aging coal and nuclear baseload fleets in the US and Germany drive demand for upgraded overspeed protection and steam admission valve control systems. FERC grid reliability standards and KBA pressure equipment directives enforce hardware refresh timelines.
- Hydropower Turbines:Run-of-river and pumped-storage installations in Brazil and Norway utilize wicket gate servomotor controls.
- Compressors:Pipeline and process gas compression in the Permian Basin and Middle East requires anti-surge valve positioning systems.
Gas turbines handle the majority of throughput; hydropower turbines are climbing the fastest on share.
Technology:
Cost tier stratification separates capital-intensive distributed architectures from modular edge-computing alternatives.
- Distributed Control Systems:Redundant processor networks command turbine auxiliaries across multi-unit power plants with integrated boiler-turbine coordination. US utilities under EPA continuous emissions monitoring mandates favor these platforms for their proven regulatory audit trails.
- Programmable Logic Controllers:Compact ruggedized controllers execute safety instrumented functions in compressor stations and auxiliary turbine skids. IEC 61508 certification requirements from TÜV and exida create specification barriers for uncertified hardware entrants.
- Human-Machine Interfaces:Augmented-reality diagnostic overlays capture disproportionate margin expansion in Japanese and German markets.
- Supervisory Control Systems:Centralized monitoring architectures displace distributed systems in North Sea and Gulf of Mexico offshore platforms.
Distributed control systems anchor the largest installed base; supervisory control systems are expanding most quickly in oil and gas applications.
Application:
Volume concentration in power generation contrasts with margin-rich specialization in aerospace and offshore hydrocarbon extraction.
- Power Generation:Baseload and peaking plants require integrated turbine-generator excitation control and grid synchronization logic. Chinese provincial grid companies and Indian CEA-mandated modernization programs drive procurement volumes.
- Oil & Gas:Liquefaction trains and pipeline compression demand SIL-rated emergency shutdown integration. ANVISA process safety requirements in Brazil and SFDA mechanical integrity rules in Saudi Arabia shape specification compliance.
- Aerospace:Engine test cells and auxiliary power units utilize high-speed fuel control and variable stator vane positioning.
- Manufacturing:Cogeneration and mechanical drive applications in chemical and steel plants require load-sharing controllers.
Power generation commands the dominant share of unit deployments; oil and gas applications show the steepest expansion trajectory in value terms.
End User:
Customer type determines contracting structure, with utilities favoring capital purchases and energy services firms driving operational expenditure models.
- Utilities:Vertically integrated state-owned and investor-owned power companies specify 20-year service life and spare parts availability. Japanese METI efficiency standards and EU Green Deal decarbonization timelines accelerate control platform replacement cycles.
- Industrial Plants:Refineries and petrochemical complexes prioritize integration with existing DCS networks and IEC 61511 safety system compatibility.
- Marine Operators:LNG carriers and naval vessels require shock-qualified controllers with redundant power supplies.
- Energy Services:Independent power producers and leasing firms in Texas and California prefer performance-contracting and energy-as-a-service structures.
Utilities represent the largest addressable base; energy services are gaining share fastest through operational expenditure contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in turbomachinery control systems favor technology-exporting economies. Germany and the United States supply advanced control platforms to Asian retrofit markets. China reduces import dependency through domestic automation procurement mandates.
China
State-owned energy groups execute fleet modernization across combined-cycle and coal-gasification plants. MEE emissions mandates tighten continuously, forcing control system replacements. Procurement concentrates in Jiangsu and Guangdong provinces where provincial grid companies automate aging baseload facilities.
United States
EPA Clean Air Act enforcement drives replacement cycles in fossil fuel baseload plants. FERC grid reliability standards enforce hardware refresh timelines for overspeed protection systems. Texas and California independent power producers favor energy-as-a-service contracting over capital purchases.
Germany
Aging nuclear and coal baseload fleets require upgraded steam admission valve controls. KBA pressure equipment directives mandate safety instrumented system validation. Industrial clusters in North Rhine-Westphalia and Bavaria host turbine service centers executing IEC 61511-certified retrofits.
Saudi Arabia
Integrated control-and-safety packages dominate liquefaction train and pipeline compression projects. SFDA mechanical integrity rules shape specification compliance for emergency shutdown integration. The Eastern Province concentrates turbomachinery procurement for gas processing and power cogeneration.
Japan
METI efficiency standards accelerate control platform replacement cycles across utility fleets. Augmented-reality diagnostic overlays capture margin expansion in human-machine interface procurement. The Kanto region around Tokyo hosts precision engineering suppliers for turbine-mounted controllers.
Turbomachinery Control Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sensor and actuator supply. The vendor base stratifies across three tiers: diversified industrial conglomerates with full automation portfolios, energy-focused OEMs with captive control divisions, and niche safety instrumented system specialists. Siemens Energy AG and General Electric Co. exemplify the OEM-integrated archetype. Emerson Electric Co. and Honeywell International Inc. represent the diversified automation platform model. Competitive moves center on long-term service agreement structures and energy-as-a-service contracting models that transfer obsolescence risk from operators to vendors.
Among diversified automation conglomerates, Emerson Electric Co., Honeywell International Inc., and Siemens Energy AG occupy positions spanning distributed control systems and safety instrumented platforms. These companies exemplify the integrated platform archetype through multi-decade utility relationships and regulatory audit trail capabilities. Woodward Inc. and Compressor Controls Corp. represent specialized tier suppliers focused on anti-surge and fuel control subsystems. Their positioning reflects narrower scope but deeper rotordynamics expertise. The competitive terrain rewards vendors capable of bundling hardware, software, and decade-long service commitments under single-contract structures.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| ABB Ltd. |
| Siemens Energy AG |
| General Electric Co. |
| Schneider Electric |
| Woodward Inc. |
| Compressor Controls Corp. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on East Asian foundries for advanced control processors and FPGA chips compresses both pricing tier spreads and supply chain resilience. Tariff exposure between the United States and China forces tier-one vendors to absorb margin erosion while accelerating dual-sourcing qualification programs for safety-certified hardware.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium SIL-certified platforms, standard distributed control systems, and economy programmable logic controllers. Price differentiation hinges on IEC 61508 certification grade and geographic delivery cost from European versus Asian manufacturing footprints. Cost compression in the economy tier is intensifying because Chinese state-owned energy groups negotiate volume-scale concessions for fleet modernization programs. Independent power producers in Texas and California exhibit highest price sensitivity through energy-as-a-service contracting preferences, while Japanese utilities under METI mandates show lowest sensitivity for augmented-reality diagnostic overlays.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for control system vendors. Manufacturing concentrates in Germany, the United States, and China for final assembly, while semiconductor fabrication draws from Taiwan, South Korea, and Japan. Raw material dependencies center on rare-earth magnets for actuator servomotors, high-purity copper for signal transmission, and specialized ceramics for high-temperature sensors. Distribution runs through long-term service agreements that bundle hardware, software, and decade-long maintenance commitments under single-contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turbomachinery control systems constitute a defensive-moat market where regulatory entrenchment creates formidable barriers. IEC 61508 and IEC 61511 certification requirements embed switching costs that protect incumbent positions across multi-decade asset lifecycles.
For Market Incumbents: Build switching-cost moats through captive certification pipelines that lock in utility procurement specifications. Deepen vertical integration into safety instrumented system software to capture recurring revenue streams. Defend against emerging edge-computing entrants by embedding machine learning inference directly on turbine-mounted controllers before virtualization commoditizes hardware-dependent protection schemes. For New Entrants and Emerging Players: Build out augmented-reality diagnostic layers for human-machine interfaces where margin pools concentrate in Japanese and German markets. Target offshore oil and gas supervisory control systems in the North Sea and Gulf of Mexico where centralized monitoring architectures displace legacy distributed systems. Pursue qualification partnerships with established safety instrumented system specialists to compress IEC 61511 certification timelines. For Investors and Strategic Acquirers: Niche safety instrumented system specialists with TÜV and exida certification depth represent compelling acquisition targets. Long-term viability across the analysis window rests on regulatory audit trail capabilities and multi-decade utility relationships. Watch for inflection signals in energy-as-a-service contracting velocity among Texas and California independent power producers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Expansion | Siemens Energy AG and Emerson Electric Co. lock in twenty-year revenue streams through bundled hardware-software-maintenance contracts. |
| Edge Computing Controller Development | Machine learning inference embedded on turbine-mounted platforms compresses response cycles below fifty milliseconds for surge protection. |
| IEC 61511 Certification Acceleration | Compressed validation timelines address the eight-to-fourteen-month commissioning delays plaguing complex retrofit environments. |
| Energy-as-a-Service Contracting | Operational expenditure models transfer obsolescence risk from Texas and California independent power producers to vendors. |
| Alternative Thermal Management Qualification | EU F-Gas Regulation compliance opens replacement demand for ancillary cooling system controls using low-global-warming-potential refrigerants. |
Study Parameters
Desk research of regulatory filings from EPA, IEC, and EU F-Gas databases preceded structured interviews with utility planning officers, turbomachinery maintenance directors, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined with secondary validation against SEC 10-K disclosures, FERC reliability filings, and customs trade data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the turbomachinery control systems value chain.
Assumptions held fixed include prevailing EPA Clean Air Act enforcement intensity and IEC 61508 safety integrity level requirements, while semiconductor supply volatility and energy-as-a-service contracting penetration were varied across sensitivity scenarios. The analytical framework modeled technology type, application vertical, end-user category, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, with gas turbine fleet age profiles and emissions mandate tightening schedules as primary industry-specific inputs.
Stress conditions across semiconductor lead time volatility, tariff rate fluctuations, and safety certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and utility capital expenditure cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Piezoelectric Devices Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Pressure Monitoring Market