
 Italy Digital Thermometer Market | 2026-2036
Italy Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Digital Thermometer Market Insights
Equipment leasing for diagnostic peripherals is reconfiguring competitive entry barriers across Italy's thermometer supply base. OMRON Healthcare leverages its established pharmacy channel network to sustain brand visibility in retail settings. Microlife Corporation anchors its position through specialized ear and forehead infrared designs calibrated for pediatric use. Welch Allyn competes by controlling direct hospital procurement relationships across northern Italy's acute care systems.
A digital thermometer is an electronic temperature measurement instrument employing thermistors or infrared sensors to quantify body heat within calibrated precision ranges, typically displaying readings via LCD or LED interfaces for clinical or domestic diagnostic purposes. Infrared and forehead units lead product type segmentation due to their non-contact hygiene profile favored in post-pandemic protocols, while ear thermometers retain concentrated margin pools in pediatric and otolaryngology applications. Home care dominates end user expansion as Italian regional health authorities decentralize chronic monitoring responsibilities to patients, whereas hospital procurement maintains volume concentration through centralized tendering frameworks.
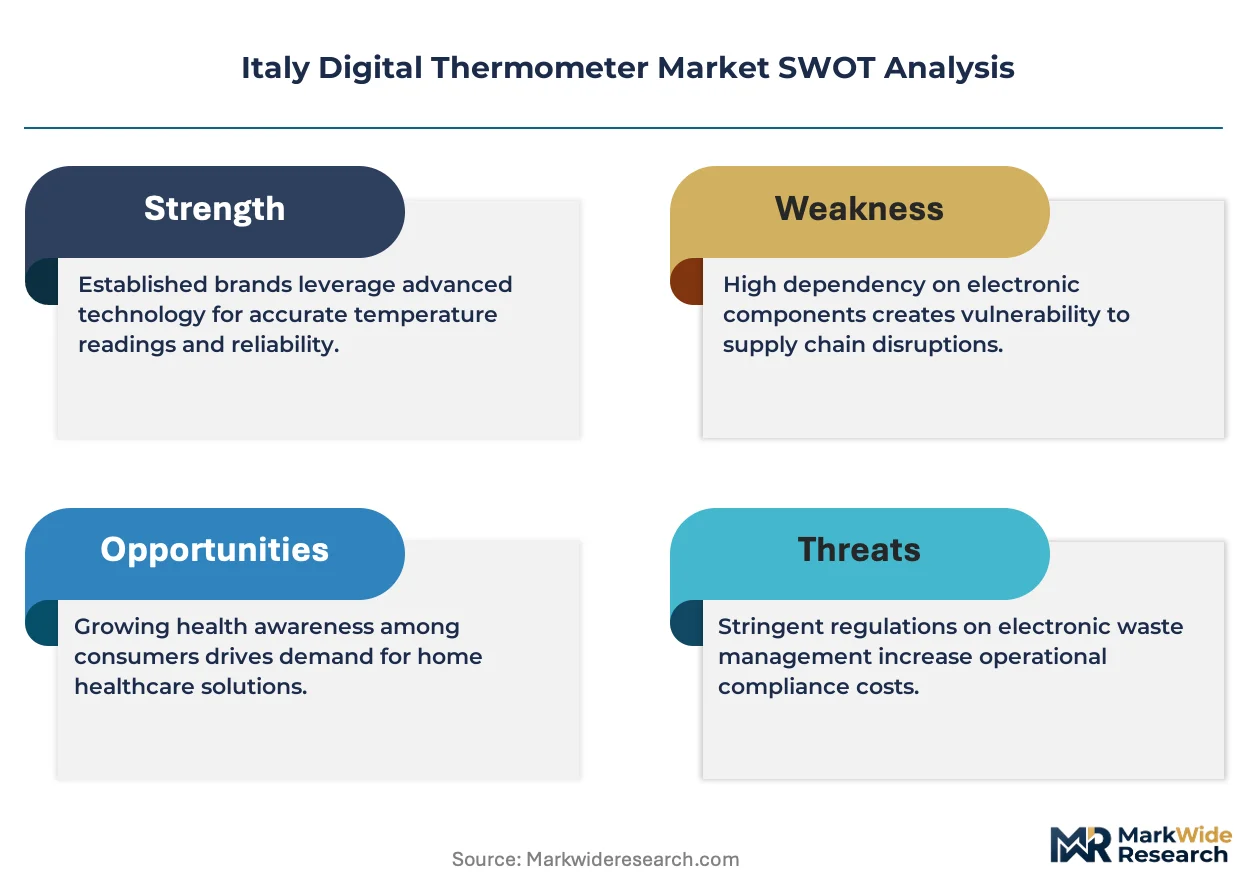
Italy's digital thermometer market operates under the EU Medical Device Regulation enforced by the Ministry of Health's Directorate General for Medical Devices, supplemented by CE marking requirements and ISO 13485 quality management standards for manufacturing traceability. The Italian Medicines Agency coordinates vigilance reporting for post-market surveillance, compelling manufacturers to maintain technical documentation and clinical evidence portfolios for market access continuity. Stakeholders must monitor evolving harmonized standards under the EU AI Act as algorithmic fever-detection features penetrate next-generation devices.
Market Dynamics
Italy's digital thermometer market is restructuring around the EU Medical Device Regulation's tightened conformity pathways, which are compressing vendor margins while elevating technical documentation burdens for Class I measuring devices.
Growth Catalysts
- EU MDR Convergence:Harmonized technical documentation requirements under the EU Medical Device Regulation are consolidating vendor bases, favoring manufacturers with established ISO 13485 quality management systems.
- Lombardy Clinical Density:Milan's acute care corridor concentrates procurement volumes, creating anchor demand for precision-calibrated infrared units across northern Italy's hospital networks.
- Home Care Decentralization:Italian regional health authorities are transferring chronic monitoring responsibilities to aging households, expanding self-monitoring tool adoption.
Market Restraints
- Sensor Input Volatility:Germanium and thermopile component costs fluctuate with semiconductor foundry capacity constraints, pressuring bill-of-materials stability for infrared manufacturers.
- Single-Source Calibration:Italian metrology traceability depends on INRIM (National Institute of Metrological Research) reference standards, creating bottleneck risk for batch certification.
- CE Marking Friction:Notified body capacity constraints under MDR Article 120 transition timelines are extending market access delays for new device submissions.
Strategic Opportunities
- Sicily and Southern Underpenetration:Calabria and Sicily exhibit lower home care device density, presenting whitespace for pharmacy-channel expansion beyond Lombardy's saturated corridor.
- EU AI Act Algorithmic Features:Fever-detection algorithms embedded in next-generation thermometers will require conformity assessment, creating first-mover advantage for vendors with clinical evidence portfolios.
- Telemedicine Integration:Bluetooth-enabled units connecting to regional electronic health record systems are capturing preference in Tuscany's integrated care pilots.
Industry Challenges
- Biomedical Software Competency Gap:Firmware engineering for algorithmic fever detection requires rare cross-training in clinical validation and embedded systems, constraining product development velocity.
- Legacy System Interoperability:Hospital information systems across Italy's 20 regional health authorities use heterogeneous data standards, complicating device integration.
- Post-Market Surveillance Bandwidth:AIFA vigilance reporting obligations demand dedicated regulatory affairs capacity that mid-tier manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Digital Thermometer Market |
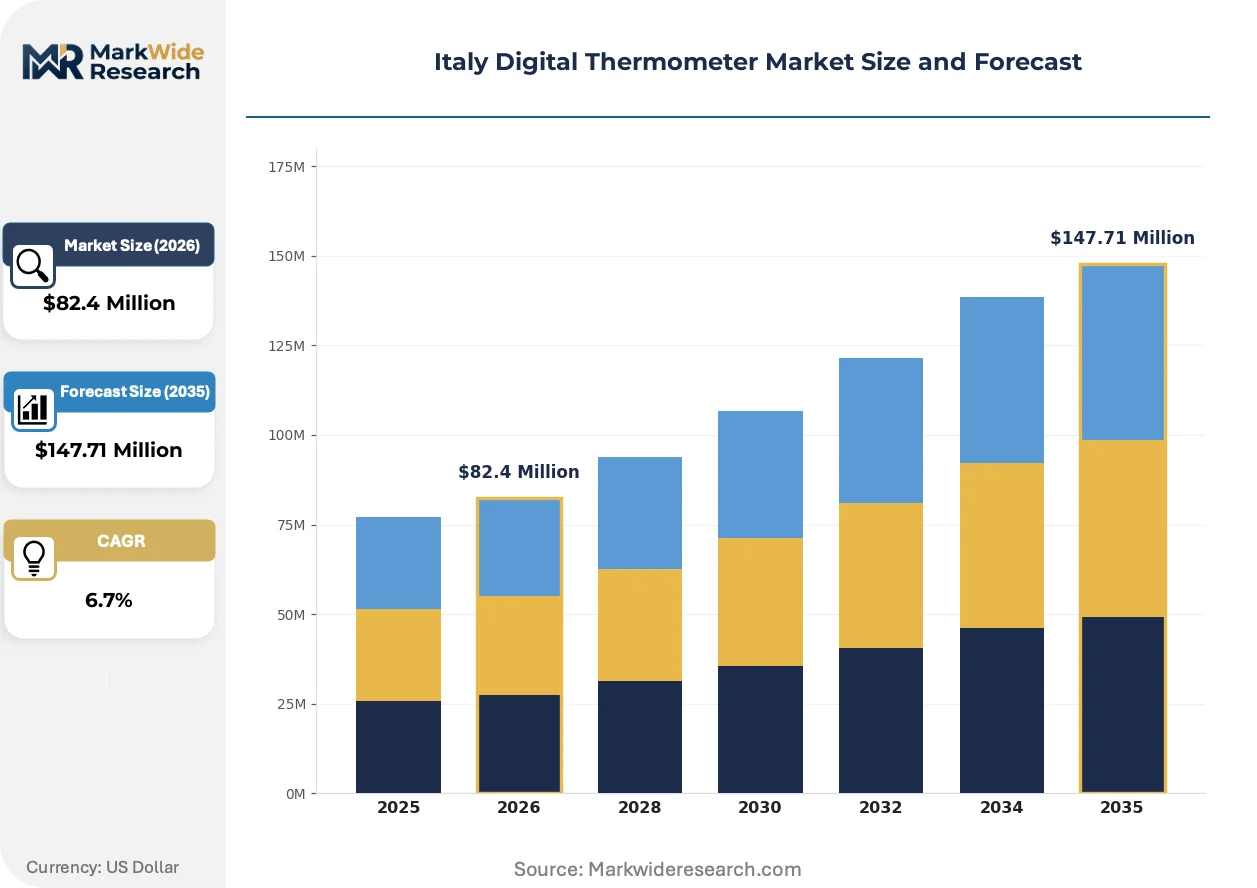
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $147.71 Million |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Forehead, Ear, Oral End User: Hospitals, Clinics, Home Care, Laboratories Distribution Channel: Online Retail, Pharmacies, Supermarkets, Direct Sales Temperature Measurement Range: Low-grade, Normal, High-grade, Hyperthermia |
| Companies Covered | OMRON Healthcare, Microlife Corporation, Terumo Corporation, Medline Industries, Welch Allyn, Medtronic, 3M Company, Exergen Corporation, American Diagnostic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Digital Thermometer Market Trends and Innovations
Sensor miniaturization and wireless connectivity are converging to redefine how temperature data flows from patient to provider, compressing diagnostic latency while expanding the addressable monitoring continuum.
Infrared thermopile arrays with integrated MEMS fabrication are virtualizing the traditional contact-thermometer form factor. Pediatric clinics across Emilia-Romagna are adopting these chip-scale packages for simultaneous multi-site skin temperature mapping. This architecture is virtualizing hardware boundaries, enabling smartphone-tethered diagnostics that bypass dedicated display units entirely.
Italy's Ministry of Health is enforcing EU MDR Article 10 technical documentation requirements with heightened scrutiny of clinical evaluation reports for fever-detection algorithms. Manufacturers must now submit post-market clinical follow-up protocols as condition of CE marking renewal. Pediatric and geriatric applications face the steepest compliance elevation, driving consolidation toward vendors with captive clinical research capabilities.
Regional tendering frameworks are fragmenting procurement authority from national centralized purchasing to Aziende Sanitarie Locali (Local Health Authorities). Hospital buyers in Veneto and Piedmont now negotiate directly with manufacturers for acute care deployments, displacing previous Ministry-mediated bulk agreements. This pattern concentrates volume leverage with Lombardy and Lazio's largest ASLs while marginalizing smaller regional purchasers.
Italy Digital Thermometer Market Segmentation
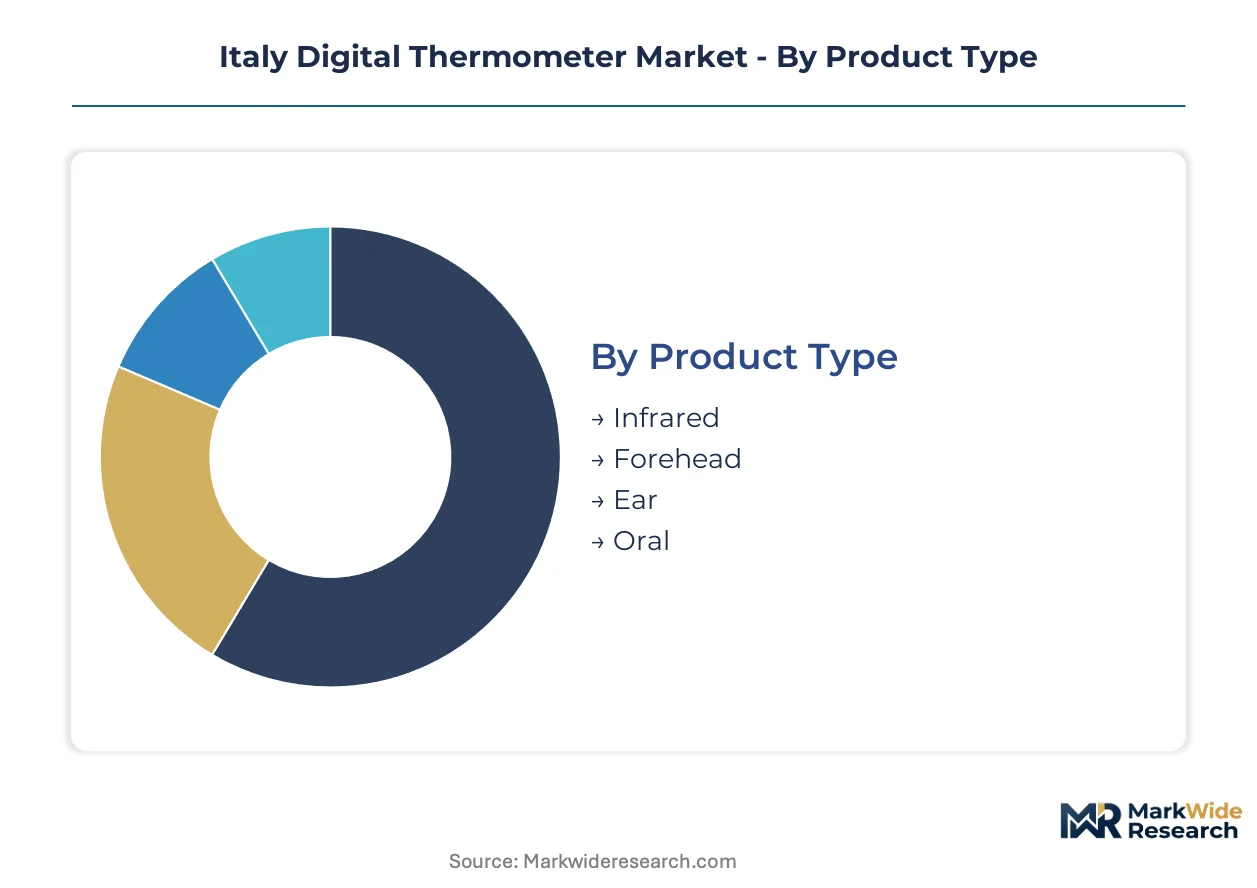
Digital thermometer segmentation in Italy reveals divergent replacement cycles across product architectures and procurement channels. Cycle-time variation from six-month retail turnover to decade-long hospital installations shapes inventory strategies and margin capture for vendors serving this market.
Product Type:
Infrared and forehead units rotate through consumer channels fastest, while ear and oral thermometers anchor slower-turning clinical procurement cycles.
- Infrared:Non-contact thermopile sensors measure surface temperature through emitted radiation detection without patient contact. Demand clusters in Lombardy's hospital procurement corridors where post-pandemic hygiene protocols remain stringent. CE marking under EU MDR Article 10 imposes elevated clinical evaluation burdens for algorithmic fever-detection variants.
- Forehead:Temporal artery scanning employs infrared arrays calibrated for rapid ambient-temperature compensation. Italian pharmacy chains in Milan and Turin report highest turnover velocity for these units among self-monitoring households. Bluetooth-enabled models connecting to regional electronic health record systems capture preference in Tuscany's integrated care pilots.
- Ear:Tympanic membrane measurement via infrared probes dominates pediatric and otolaryngology applications with concentrated margin pools.
- Oral:Thermistor-based contact measurement retains installed base in budget-conscious home care segments with slower replacement cycles.
Oral thermometers dominate installed base. Infrared and forehead units are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive hospital systems from dispersed low-unit-value household purchases.
- Hospitals:Centralized tendering through Aziende Sanitarie Locali demands ISO 13485-certified precision instruments with batch traceability. Northern Italy's acute care networks in Veneto and Piedmont negotiate directly with manufacturers, displacing previous Ministry-mediated bulk agreements. INRIM metrology traceability creates certification bottlenecks for infrared calibration.
- Home Care:Aging Italian households drive decentralization of chronic monitoring responsibilities under regional health authority mandates. Sicily and Calabria exhibit lower device density, presenting whitespace for pharmacy-channel expansion beyond Lombardy's saturated corridor. Bluetooth connectivity to regional electronic health record systems differentiates premium units.
- Clinics:Outpatient facilities balance precision requirements against capital constraints through equipment leasing arrangements.
- Laboratories:Reference-grade calibration demands metrology-standard traceability for clinical trial and quality control applications.
Home care dominates volume expansion. Hospital procurement maintains value concentration.
Distribution Channel:
Volume concentration varies sharply between fragmented retail endpoints and concentrated institutional procurement.
- Pharmacies:OMRON Healthcare leverages established channel networks to sustain brand visibility across Italy's retail settings. Regional pharmacy associations in Emilia-Romagna and Tuscany coordinate promotional placement for pediatric-calibrated units. CE marking documentation requirements favor vendors with dedicated regulatory affairs capacity.
- Online Retail:E-commerce platforms accelerate price transparency and comparison shopping for infrared and forehead categories. Algorithmic fever-detection features embedded in next-generation devices will require EU AI Act conformity assessment, creating compliance differentiation. Direct-to-consumer shipping bypasses traditional wholesale markups.
- Supermarkets:Mass-market placement captures impulse purchases for basic oral thermistor models with minimal feature differentiation.
- Direct Sales:Hospital procurement relationships concentrate volume leverage with Lombardy and Lazio's largest ASLs while marginalizing smaller regional purchasers.
Pharmacies dominate installed base. Online retail is where expansion concentrates.
Temperature Measurement Range:
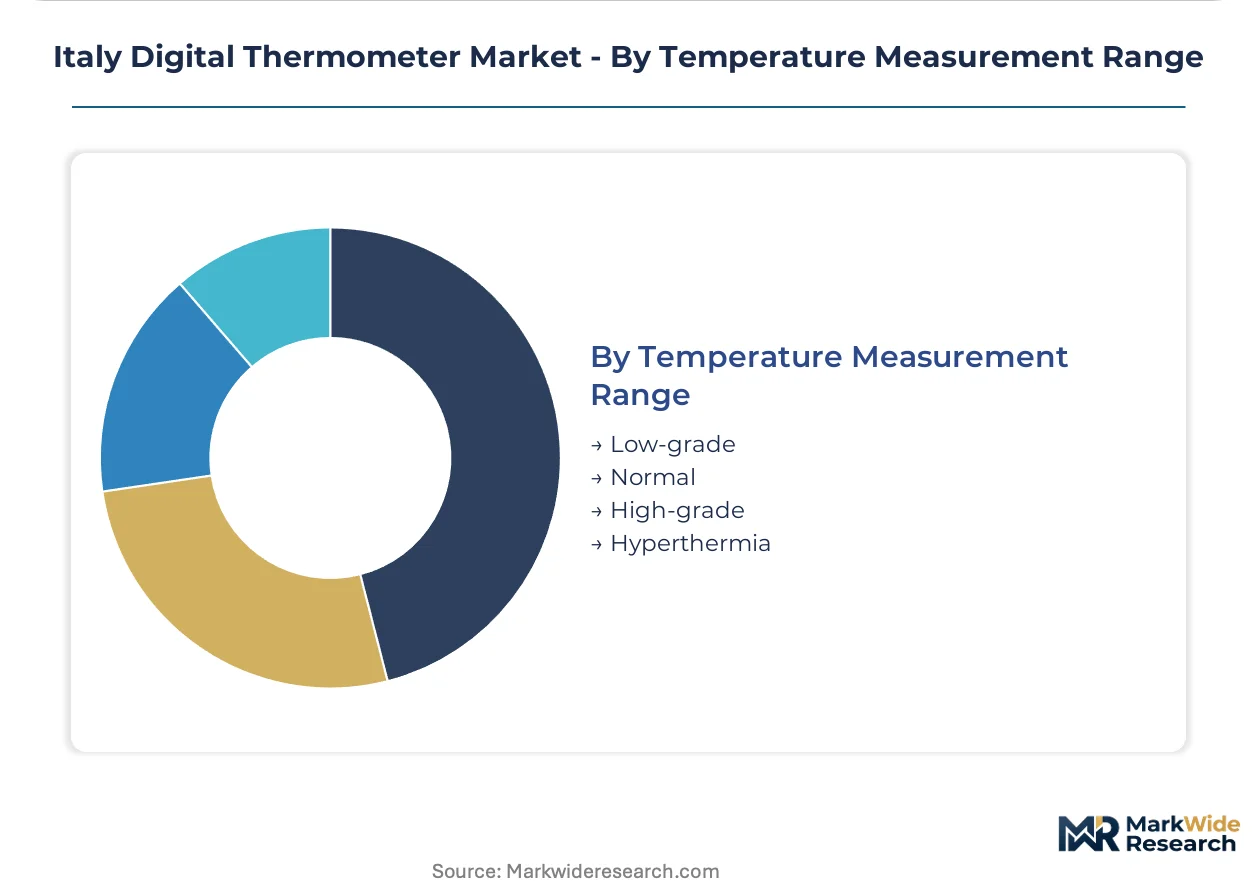
Maturity gradients separate established normal-range applications from emerging algorithmic detection at measurement extremes.
- Normal:Standard fever screening between 36.5°C and 37.5°C anchors household and routine clinical applications. Italian regional health authorities specify these ranges for decentralized chronic monitoring programs. Post-market surveillance obligations under AIFA vigilance reporting demand dedicated compliance infrastructure.
- High-grade:Elevated temperature detection between 37.5°C and 39.5°C concentrates in pediatric and acute care settings where rapid intervention protocols apply. EU MDR clinical evaluation requirements steepen for algorithmic classification at this threshold. Firmware engineering competency gaps constrain product development velocity for automated alert features.
- Low-grade:Subnormal temperature monitoring supports hypothermia risk assessment in geriatric and surgical recovery applications.
- Hyperthermia:Critical threshold detection above 39.5°C requires highest precision calibration for emergency department deployment.
Normal range dominates installed base. High-grade detection is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's acute care corridor extracts pricing premiums that southern regions cannot match, creating a two-tier procurement landscape across the peninsula. Northern Italy's hospital networks concentrate demand for precision-calibrated infrared units, while Sicily and Calabria lag in device density and reimbursement velocity.
Lombardy
Milan's dense clinical infrastructure drives demand for non-contact thermometry in post-pandemic hygiene protocols. The Ministry of Health's Directorate General for Medical Devices enforces EU MDR conformity assessments that favor established ISO 13485-certified suppliers. The metropolitan corridor from Monza to Pavia anchors procurement volume for infrared arrays with algorithmic fever detection.
Veneto
Decentralized Aziende Sanitarie Locali tendering shifts procurement authority from national bulk agreements to direct manufacturer negotiations. Regional health authority mandates accelerate home care device distribution to aging households in Verona and Padua corridors. The Veneto cluster demands Bluetooth-enabled units for integration with emerging electronic health record pilots.
Piedmont
Turin's hospital networks prioritize batch-traceable precision instruments for acute care deployment. CE marking friction under MDR Article 120 transition timelines extends market access delays for new device submissions. The city's medical technology corridor concentrates metrology-dependent procurement for pediatric and geriatric applications.
Emilia-Romagna
Pediatric clinics across Bologna and Modena adopt chip-scale thermopile arrays for simultaneous multi-site skin temperature mapping. AIFA vigilance reporting obligations compel manufacturers to maintain dedicated regulatory affairs capacity for post-market surveillance. The region's integrated care experiments favor smartphone-tethered diagnostics bypassing dedicated display units.
Sicily
Lower home care device density creates whitespace for pharmacy-channel expansion beyond northern saturation points. Italian Medicines Agency coordination of post-market clinical follow-up protocols applies uniform compliance burdens regardless of regional purchasing power. Palermo and Catania procurement offices struggle with heterogeneous data standards complicating device integration.
Italy Digital Thermometer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying calibrated sensor modules and firmware architectures. The vendor base stratifies between multinational healthcare conglomerates with captive distribution networks and mid-tier manufacturers dependent on third-party notified bodies for CE marking continuity. Three archetypes dominate: pharmacy-channel brand builders, hospital-direct procurement specialists, and telemedicine-integrated platform developers. Competitive moves concentrate on backward integration into thermopile sensor supply and strategic partnerships with regional electronic health record system vendors.
Among Japanese-origin healthcare conglomerates, OMRON Healthcare exemplifies the pharmacy-channel archetype through established retail visibility networks. Microlife Corporation occupies a position within the specialized pediatric-calibration tier, while Welch Allyn anchors the hospital-direct procurement specialist segment through relationships with northern Italy's acute care systems. These three entities represent divergent strategic postures: retail brand maintenance, clinical specialization, and institutional volume capture.
| Leading Market Players |
|---|
| OMRON Healthcare |
| Microlife Corporation |
| Terumo Corporation |
| Medline Industries |
| Welch Allyn |
| Medtronic |
| 3M Company |
| Exergen Corporation |
| American Diagnostic Corporation |
| Others |
Pricing and Supply Chain Analysis
Milan's thermopile sensor fabrication cluster anchors European infrared thermometer capacity, with its foundry utilization rates directly transmitting into OEM pricing leverage across downstream assembly tiers. Germanium wafer spot costs and INRIM calibration queue lengths cascade through bill-of-materials structures, compressing margins for mid-tier manufacturers lacking captive sensor supply.
Pricing Analysis
Configured-to-order pricing for hospital-grade infrared units with embedded fever-detection algorithms commands spreads exceeding standard pharmacy-channel forehead thermometers by certification burden and clinical validation depth. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified precision instruments from basic thermistor models, with CE marking tier and Bluetooth connectivity bundling as primary differentiation drivers. Cost compression in economy segments is intensifying because of e-commerce price transparency and direct-to-consumer shipping bypassing wholesale markups. Home care households exhibit highest price sensitivity, while Lombardy hospital procurement committees prioritize traceability and batch certification over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates component sourcing risk for thermopile arrays and MEMS fabrication substrates. Taiwan, China, and Germany concentrate thermopile sensor and precision optics supply, with Italian assembly drawing from Germanium wafers, infrared detector chips, and LCD display modules. Single-source vulnerability at INRIM for national metrology traceability creates batch certification bottlenecks extending procurement lead times. Distribution runs through pharmacy wholesale networks for retail volumes and direct manufacturer negotiations with Aziende Sanitarie Locali for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's digital thermometer market is crossing a platform-economics inflection where Bluetooth-enabled units tethering to regional electronic health record systems are displacing standalone devices, rewarding vendors with software competency and hospital system integration partnerships.
For Market Incumbents: Entrench pharmacy-channel control through exclusive calibration service bundling and backward integration into thermopile sensor supply to defend against Asian component specialists entering CE marking pathways. OMRON Healthcare's established retail visibility provides defensive anchor, though EU AI Act algorithmic conformity requirements demand fresh clinical evidence investment to maintain positioning against telemedicine-integrated challengers.
For New Entrants and Emerging Players: Sicily and Calabria's lower home care device density presents whitespace for pharmacy-channel expansion with pediatric-calibrated infrared units priced below Lombardy saturation points. Equipment leasing arrangements for diagnostic peripherals offer entry pathway into clinic segments without capital-intensive hospital procurement relationships. Direct online retail with algorithmic fever-detection features captures price-transparent comparison shoppers bypassing traditional wholesale markups.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated medical device consolidation play because EU MDR technical documentation burdens and AIFA vigilance reporting obligations are compressing vendor bases toward ISO 13485-certified manufacturers with captive clinical research capabilities. Acquisition targets with firmware engineering competency for algorithmic fever detection and existing Bluetooth health record integrations command strategic premium. The signal to watch is regional tendering framework fragmentation accelerating direct ASL negotiations and displacing Ministry-mediated bulk agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Article 120 transition timelines extend market access delays for unprepared submissions. |
| Hospital System Partnership | Direct ASL negotiations in Veneto and Piedmont concentrate volume leverage with largest regional purchasers. |
| Software Companion Development | Bluetooth-enabled units connecting to Tuscany's electronic health record pilots capture procurement preference. |
| Backward Integration into Sensors | Thermopile array supply control insulates margins from Germanium wafer spot cost volatility. |
| Reimbursement Strategy | Regional health authority chronic monitoring mandates create funded demand channels for home care devices. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, pharmacy chain category managers, and regulatory affairs specialists provided ongoing calibration against operating reality. Primary interviews with GPO contracts managers and AIFA vigilance reporting officers combined with secondary validation from EU MDR notified body disclosure databases, hospital procurement tender records, and ISO 13485 certification registries. Bottom-up volume triangulation across product architectures and top-down value reconciliation against regional health authority expenditure reports anchored estimate robustness.
Scenario-bracketing around EU AI Act implementation timing and MDR notified body capacity constraints bounded projection uncertainty across the analysis window. Segmentation dimensions modeled include product type, end user tier, distribution channel, and temperature measurement range, with algorithmic feature penetration as medical-device-specific overlay. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for regulatory transition impacts, incorporating thermopile sensor cost trajectories and regional electronic health record integration velocity as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telemedicine platform developers or Asian sensor specialists with expedited CE marking pathways would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Wireless Flow Sensors Market