
 Digital Flow Meter Market | 2026-2036
Digital Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Flow Meter Market Insights
A shortage of certified instrumentation engineers is unwinding project timelines across the process industries. Emerson Electric Co. leverages its PlantWeb digital ecosystem to anchor long-term service contracts in refining. Siemens AG competes through integrated automation portfolios that bundle flow measurement with distributed control systems. Endress+Hauser AG specializes in hygienic Coriolis designs that dominate food and pharmaceutical batching applications.
Digital flow meters are electronic instruments that measure fluid velocity, mass, or volume using electromagnetic, ultrasonic, Coriolis, or vortex sensing principles, typically achieving accuracies of ±0.1% to ±0.5% depending on technology and installation conditions. Their primary purpose is to enable real-time process control, custody transfer, and regulatory compliance across liquid and gas handling operations. Coriolis meters command premium positioning in chemical and hydrocarbon applications where direct mass measurement eliminates density compensation errors. Ultrasonic clamp-on installations are gaining fastest in water distribution retrofit programs where pipeline shutdown is prohibitively expensive. Smart technology segments with embedded diagnostics and wireless HART protocols are capturing margin pools through predictive maintenance subscriptions rather than hardware sales alone.
EPA effluent guidelines under the Clean Water Act mandate continuous monitoring at municipal and industrial discharge points, directly stimulating demand for self-validating digital meters. EU F-Gas Regulation and REACH compliance frameworks require refrigerant and process gas tracking with traceable measurement chains, favoring meters with SIL-certified outputs. In the US, FDA 21 CFR Part 11 drives validation requirements in pharmaceutical bioprocessing. Stakeholders must weigh capital deployment between in-line permanent installations and portable audit-grade instruments as facility decarbonization audits expand in scope and frequency.
Market Dynamics
The displacement of mechanical meters by ultrasonic and electromagnetic sensing architectures is restructuring capital allocation across water utilities and process industries, compressing replacement cycles and elevating service contract values over hardware margins.
Growth Catalysts
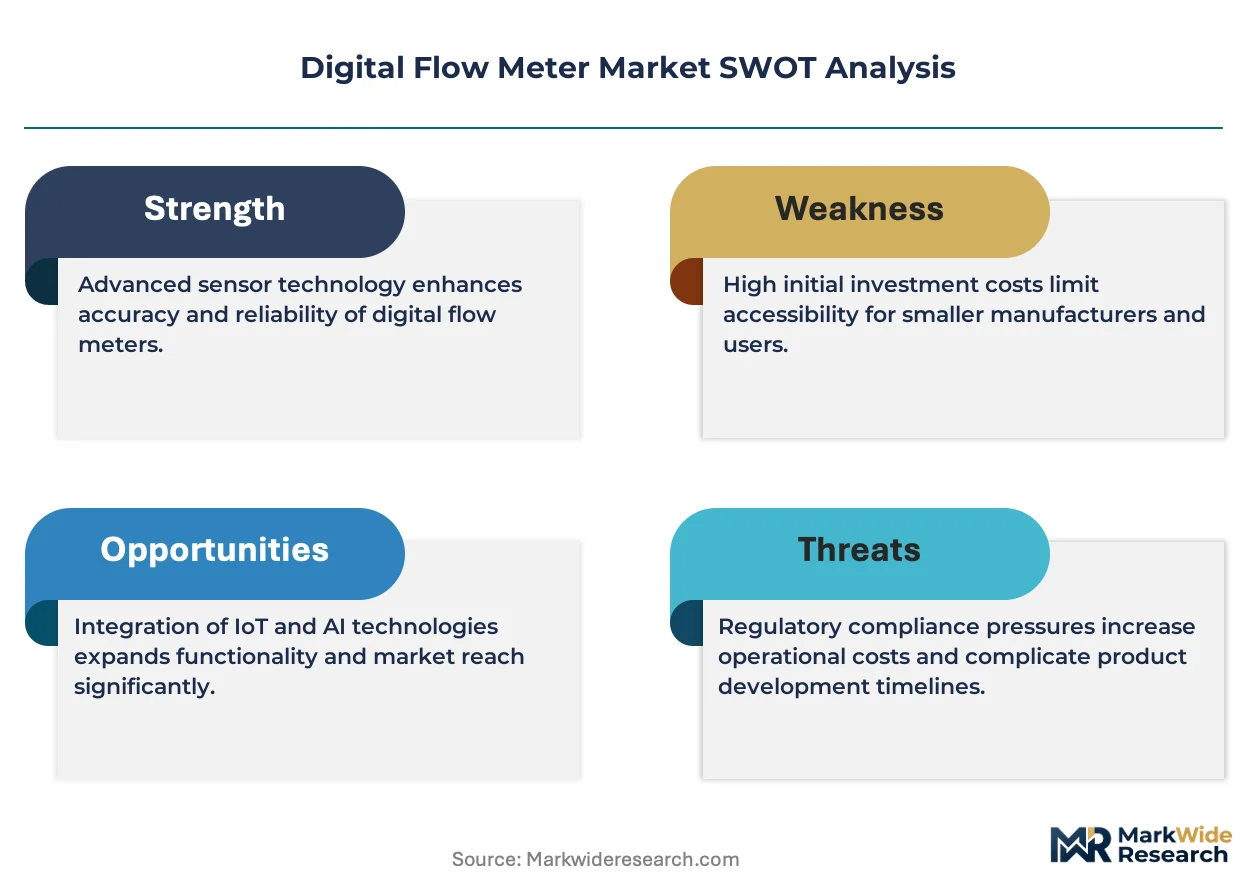
- EPA effluent monitoring mandates:Continuous discharge measurement requirements under the Clean Water Act are forcing municipal and industrial operators toward self-validating digital instrumentation with SIL-certified outputs.
- EU F-Gas phase-down compliance:Refrigerant tracking obligations are accelerating adoption of Coriolis mass flow meters in HVAC and chemical processing installations across Germany and France.
- Ultrasonic clamp-on retrofit economics:Water distribution authorities facing pipeline shutdown prohibitions are specifying non-invasive measurement for aging cast-iron infrastructure.
Market Restraints
- Neodymium and rare-earth magnet supply concentration:Electromagnetic meter production depends on Chinese-processed rare-earth elements, exposing manufacturers to export quota volatility.
- Certified instrumentation engineer scarcity:Project timelines are extending 15-25% across North American refining and chemical corridors due to qualified commissioning specialist shortages.
- Mechanical meter residual installed base:Decades-old turbine and positive-displacement units in low-accuracy applications resist replacement where capital budgets prioritize other infrastructure.
Strategic Opportunities
- Predictive maintenance subscription models:Embedded diagnostics and wireless HART protocols are enabling recurring revenue streams that decouple vendor economics from unit shipment volumes.
- Pharmaceutical bioprocessing validation demand:FDA 21 CFR Part 11 compliance requirements are creating premium positioning for hygienic Coriolis designs in single-use fermentation skids.
- India's smart city water metering programs:AMR and AMI infrastructure rollouts in Mumbai, Delhi, and Bangalore are opening volume opportunities for battery-powered ultrasonic residential units.
Industry Challenges
- Multi-protocol integration complexity:Fieldbus fragmentation between PROFIBUS, Modbus, and EtherNet/IP is forcing vendors to maintain redundant hardware variants, inflating SKU complexity.
- SIL certification timeline compression:Functional safety documentation requirements for process industries are extending product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Flow Meter Market |
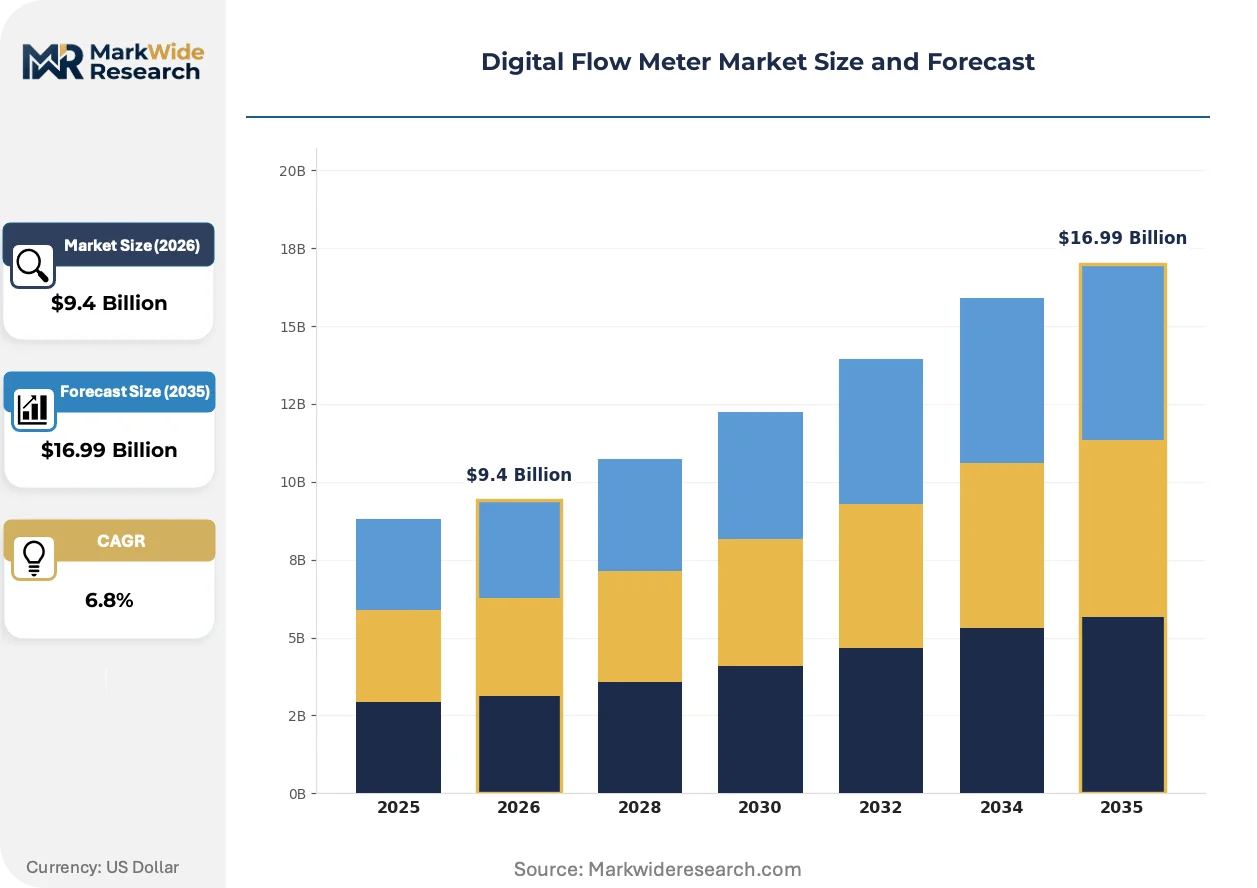
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electromagnetic, Ultrasonic, Coriolis, Vortex End User: Oil & Gas, Water & Wastewater, Chemical Processing, Food & Beverage Installation: In-line, Clamp-on, Portable, Submersible Technology: Analog, Digital, Wireless, Smart |
| Companies Covered | Emerson Electric Co., Siemens AG, ABB Ltd., Endress+Hauser AG, Honeywell International Inc., Yokogawa Electric Corporation, Badger Meter, Inc., Krohne Messtechnik GmbH, Sierra Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Flow Meter Market Trends and Innovations
Sensor fusion architectures and edge computing integration are redefining how flow measurement data is processed, transmitted, and monetized across industrial networks.
MEMS-based thermal mass sensing is miniaturizing into compact insertion probes for HVAC and semiconductor gas distribution applications. Facility operators in cleanroom environments are specifying these units for point-of-use nitrogen and argon monitoring. The form factor reduction is miniaturizing installation envelope requirements, enabling measurement in previously inaccessible pipeline geometries.
EU F-Gas Regulation tightening is mandating refrigerant leak detection with quantified mass balance verification. Industrial refrigeration OEMs are integrating Coriolis meters into packaged chiller systems to satisfy quarterly reporting obligations. German chemical corridor operators are retrofitting existing ammonia systems with SIL-rated transmitters to preempt enforcement actions.
Service unbundling is separating hardware procurement from calibration and validation contracts. Pharmaceutical and food processing buyers are awarding multi-year metrology agreements to third-party specialists rather than OEM service arms. This pattern is most pronounced in Switzerland and the Netherlands, where ISO 17025-accredited laboratories are capturing recurring calibration volumes from installed ultrasonic and electromagnetic bases.
Digital Flow Meter Market Segmentation
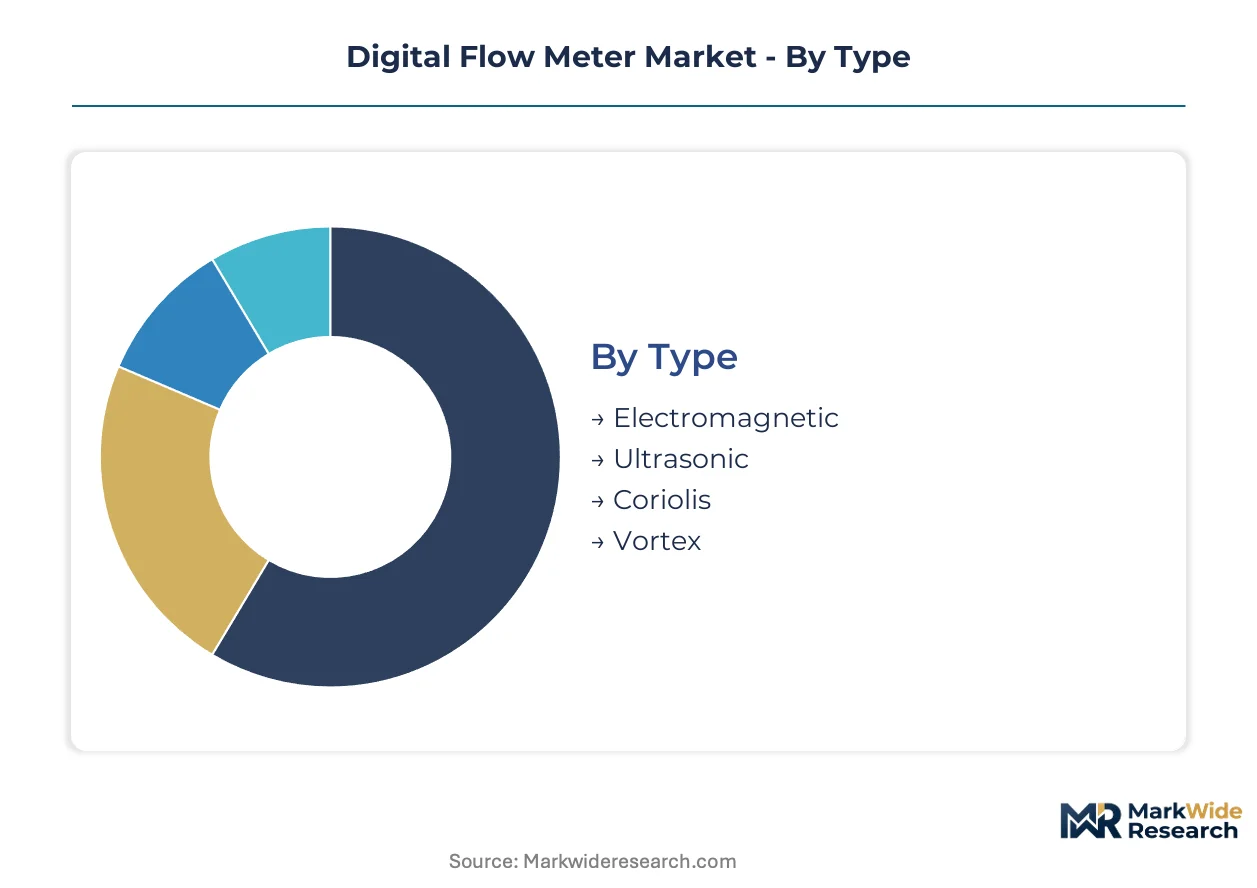
Digital flow meter procurement patterns diverge sharply across sensing architectures, installation constraints, and connectivity requirements. Understanding these segment boundaries clarifies where capital deployment concentrates versus where retrofit economics dominate purchasing decisions.
Type:
Electromagnetic and Coriolis variants anchor export demand from German and US manufacturing bases, while ultrasonic production increasingly regionalizes to serve water utility retrofit programs domestically.
- Electromagnetic:These meters exploit Faraday's law of induction, requiring conductive fluids above 5 μS/cm for reliable signal generation. Demand concentrates in German chemical corridor operations and US Gulf Coast petrochemical clusters where high-volume custody transfer mandates SIL-certified outputs. EPA effluent monitoring requirements under the Clean Water Act accelerate replacement of mechanical turbine units in municipal wastewater treatment.
- Coriolis:Direct mass measurement via vibrating tube mechanics eliminates density compensation errors that plague volumetric alternatives. German refrigeration OEMs specify these for EU F-Gas Regulation compliance, while US shale operators deploy them for multiphase wellhead metering where entrained gas corrupts other sensing principles.
- Ultrasonic:Transit-time and Doppler variants measure fluid velocity through acoustic pulse propagation. Clamp-on configurations dominate India's smart city water metering programs in Mumbai and Delhi.
- Vortex:Shedding frequency correlation with velocity suits steam and gas applications. Japanese semiconductor fabs specify these for high-purity nitrogen distribution.
Electromagnetic holds the largest share; momentum sits with ultrasonic as non-invasive retrofit economics improve.
End User:
Capital intensity and regulatory exposure create four distinct procurement profiles, from offshore platform specifications to hygienic batching validations.
- Oil & Gas:Upstream operators prioritize multiphase tolerance and hazardous area certifications. US shale plays and North Sea installations drive specification for high-pressure Coriolis designs.
- Water & Wastewater:Non-revenue water reduction targets push utilities toward AMR-enabled ultrasonic networks. India's AMR infrastructure rollouts in Bangalore and Chennai open volume opportunities.
- Chemical Processing:Aggressive media compatibility and SIL-rated safety outputs dominate purchasing criteria. German chemical corridor operators retrofit ammonia systems with SIL-rated transmitters.
- Food & Beverage:Hygienic Coriolis designs with 3A certification and CIP/SIP compatibility command premium positioning. FDA 21 CFR Part 11 validation requirements structure procurement around documented calibration chains.
Chemical Processing captures the highest unit margins; Water & Wastewater is climbing the fastest on smart city infrastructure commitments.
Installation:
Physical integration methods segment by capital recovery timeline and pipeline accessibility constraints.
- In-line:Permanent flanged or wafer installations deliver highest accuracy in continuous process applications. These dominate greenfield petrochemical construction.
- Clamp-on:External transducer mounting eliminates shutdown requirements. North American water distribution authorities facing cast-iron infrastructure deterioration specify these for priority leak detection zones.
- Portable:Battery-powered audit-grade instruments support verification campaigns and custody transfer disputes. Swiss and Dutch ISO 17025-accredited laboratories deploy these for third-party calibration services.
- Submersible:IP68-rated enclosures withstand permanent immersion in wet wells and open channel applications. These satisfy EPA continuous monitoring mandates at municipal discharge points.
In-line retains installed base dominance; clamp-on gains share fastest where pipeline shutdown economics are prohibitive.
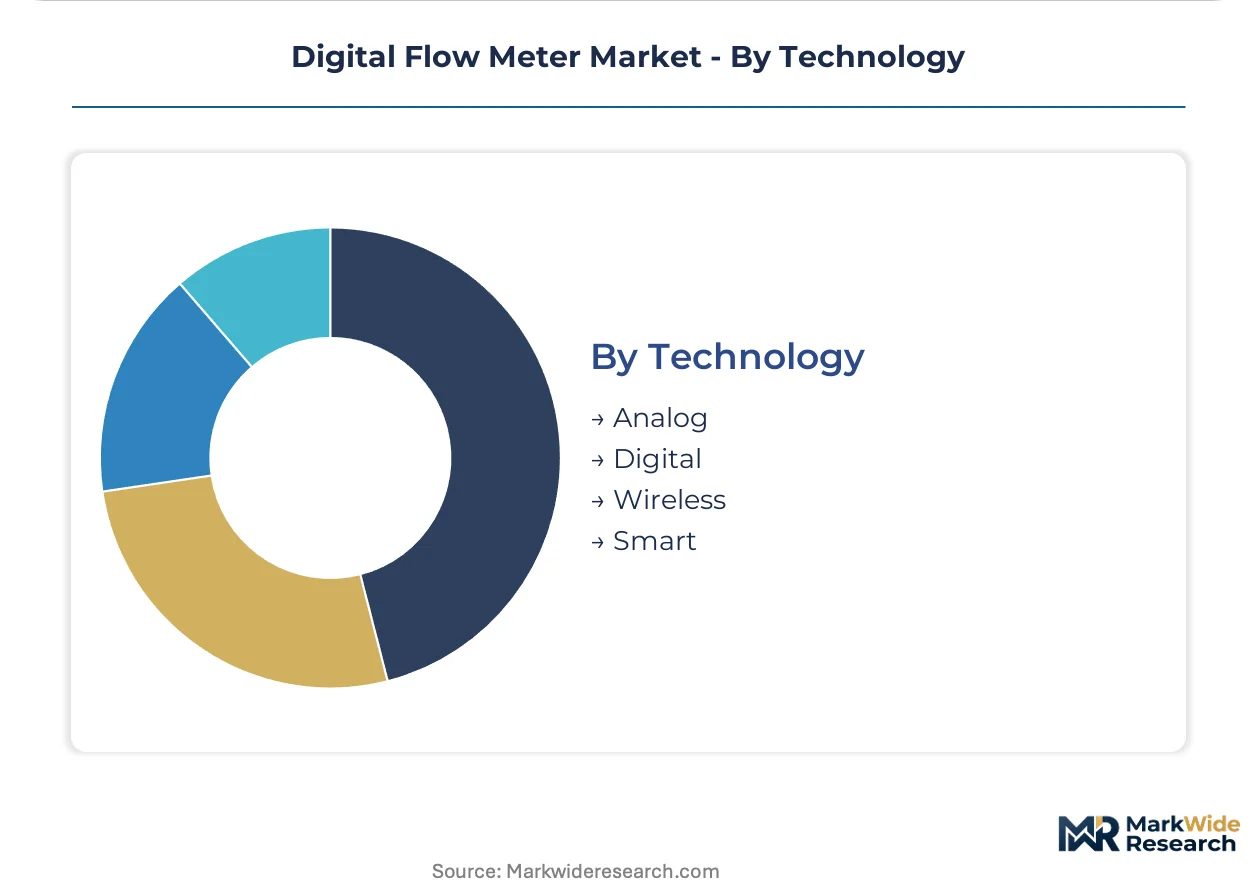
Technology:
Connectivity architectures separate commodity hardware procurement from recurring service revenue models.
- Analog:4-20 mA and pulse outputs persist in cost-sensitive retrofit applications where control system modernization lags. These concentrate in aging North American industrial infrastructure.
- Digital:Fieldbus protocols enable multi-parameter transmission and remote configuration. PROFIBUS and Modbus variants dominate European process automation integration.
- Wireless:ISA100 and WirelessHART eliminate cabling costs in geographically dispersed assets. These expand most quickly in upstream oilfield automation.
- Smart:Embedded diagnostics and edge computing enable predictive maintenance subscriptions. Pharmaceutical and food processing buyers in Switzerland and the Netherlands award multi-year metrology agreements around these capabilities.
Analog retains residual share in budget-constrained utilities; smart technology shows steepest expansion trajectory on predictive maintenance monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent guidelines under the Clean Water Act anchor North American demand, while EU F-Gas Regulation compliance drives European procurement patterns for refrigerant tracking applications.
United States
Water utilities across Texas and California face EPA mandates for continuous discharge monitoring at municipal treatment facilities. The US Gulf Coast petrochemical cluster specifications favor SIL-certified electromagnetic meters for custody transfer applications. Shale operators in the Permian Basin deploy Coriolis designs for multiphase wellhead metering where entrained gas corrupts alternative sensing principles.
Germany
Chemical corridor operators retrofit ammonia refrigeration systems with SIL-rated transmitters to satisfy EU F-Gas Regulation quarterly reporting obligations. REACH compliance frameworks require traceable measurement chains for process gas tracking in BASF and Bayer manufacturing complexes. Munich-based refrigeration OEMs integrate Coriolis meters into packaged chiller systems for export markets.
India
Smart city water metering programs in Mumbai, Delhi, and Bangalore specify battery-powered ultrasonic residential units for AMR infrastructure rollouts. The Central Electricity Authority mandates flow measurement accuracy standards for thermal power plant cooling water systems. Gujarat's chemical manufacturing belt imports German electromagnetic designs for aggressive media applications.
China
Municipal water authorities in the Yangtze River Delta accelerate replacement of mechanical turbine meters with digital ultrasonic units for non-revenue water reduction. The Ministry of Ecology and Environment tightens industrial discharge monitoring requirements for steel and petrochemical complexes. Shenzhen's semiconductor fabs specify high-purity gas flow measurement for nitrogen distribution systems.
Japan
Semiconductor manufacturing in the Kanto region drives specifications for vortex meters in high-purity nitrogen distribution. METI efficiency standards push HVAC contractors toward thermal mass sensing for building energy management. Yokogawa's domestic automation integration anchors fieldbus protocol preferences across process industries.
Digital Flow Meter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on single sensing architectures or regional service networks. The upper tier bundles flow measurement with distributed control systems and digital ecosystems to capture long-term service contracts. Mid-scale specialists compete through hygienic designs for pharmaceutical validation or clamp-on retrofit economics for water utilities. Competitive moves center on predictive maintenance subscription models and SIL certification acceleration to compress product development timelines.
Within the integrated automation tier, Emerson Electric Co. and Siemens AG exemplify portfolio breadth that spans multiple sensing principles and fieldbus protocols. Endress+Hauser AG occupies a specialist position anchored in hygienic Coriolis applications. These three entities represent distinct competitive vectors: ecosystem integration, automation bundling, and vertical specialization respectively.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| ABB Ltd. |
| Endress+Hauser AG |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| Badger Meter, Inc. |
| Krohne Messtechnik GmbH |
| Sierra Instruments, Inc. |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-week lead times for SIL-certified transmitters concentrate pricing power with German and US manufacturing bases while compressing margins for regional assemblers dependent on Chinese-processed rare-earth elements. This inventory tension feeds directly into how electromagnetic meter vendors structure volume discounts versus Coriolis specialists defending premium positioning through embedded diagnostics.
Pricing Analysis
German chemical corridor buyers face 15-25% price spreads versus US Gulf Coast procurement for equivalent SIL-rated electromagnetic units due to EU F-Gas compliance documentation burdens. Three-tier pricing structure across premium certified, standard industrial, and economy retrofit levels segments buyers by validation requirements and aftermarket service bundling. Pricing pressure stems from Indian smart city tenders favoring lowest-qualified-bid awards for battery-powered ultrasonic residential units. Municipal water authorities exhibit highest price sensitivity; pharmaceutical bioprocessors show least sensitivity due to FDA 21 CFR Part 11 validation lock-in costs.
Supply Chain Analysis
China processes 85% of global neodymium and rare-earth magnet feedstock for electromagnetic meter coils, while Germany and the United States anchor finished Coriolis and electromagnetic assembly. Copper winding stock and sapphire bearing components draw from Japanese and Swiss precision machining specialists. Single-source vulnerability concentrates in Chinese rare-earth export quota volatility. Distribution runs through OEM direct sales for process industries and third-party metrology laboratories for calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where PlantWeb-style digital ecosystems and wireless HART interoperability are redefining vendor capture from hardware margins to recurring predictive maintenance subscriptions.
For Market Incumbents: Consolidate service contract portfolios through backward integration into ISO 17025-accredited calibration laboratories, preempting third-party metrology specialists from capturing recurring revenue streams. Defend against ultrasonic clamp-on specialists by embedding edge-computing diagnostics that create switching costs through historical trend data lock-in.
For New Entrants and Emerging Players: Anchor in India's AMR infrastructure rollout for battery-powered ultrasonic residential units, where German and US incumbents lack localized service density. Target Swiss and Dutch pharmaceutical bioprocessing validation demand with hygienic Coriolis designs certified for single-use fermentation skids, leveraging service unbundling trends to capture multi-year metrology agreements.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because predictive maintenance subscriptions decouple vendor economics from cyclical capital expenditure cycles. Target acquisition profiles center on wireless protocol specialists with ISA100 or WirelessHART stack expertise. The signal to watch is SIL certification timeline compression below eight months as competitive differentiator.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Emerson-style digital ecosystems convert hardware sales to recurring service subscriptions through embedded diagnostics. |
| Backward Integration into Calibration Services | ISO 17025 laboratory acquisition captures recurring revenue from installed ultrasonic and electromagnetic bases in Switzerland. |
| SIL Certification Acceleration Program | Compressing functional safety documentation timelines below eight months creates procurement preference in German chemical corridor. |
| Wireless Protocol Stack Acquisition | ISA100 and WirelessHART expertise enables oilfield automation penetration without cabling infrastructure investment. |
| Localized Assembly for Indian Smart Cities | Battery-powered ultrasonic production in Mumbai and Delhi avoids import duty exposure on finished European units. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at US Gulf Coast petrochemical facilities, instrumentation procurement leads at German chemical corridor operators, water utility AMR program directors in India, and aftermarket service heads at Swiss metrology laboratories, then refined against secondary validation from EPA effluent monitoring guidance documents, EU F-Gas Regulation implementation reports, SEC 10-K filings of listed automation vendors, and customs trade data for electromagnetic meter imports. Bottom-up unit economics triangulated against top-down sector expenditure patterns.
Variance decomposition across sensing technology, end-user industry, installation configuration, and connectivity architecture structured the analytical framework over the projection horizon. CAGRs derived from segment-level unit shipment trajectories weighted by average selling price evolution, with specific inputs including Indian smart city tender award schedules and German refrigeration OEM integration timelines for Coriolis meter adoption.
Underlying assumptions cover regulatory enforcement continuity for EPA effluent guidelines and EU F-Gas quarterly reporting obligations, with deviation risk concentrated in Chinese rare-earth export quota volatility and certified instrumentation engineer scarcity extending commissioning timelines. Recalibration cycles align with material shifts in smart city infrastructure award schedules and SIL certification timeline benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Signal Calibrators Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Global Tilt Sensor Market