
 China Industrial Sensors Market | 2026-2036
China Industrial Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
China Industrial Sensors Market Analysis
Automotive OEMs are gaining share over traditional process manufacturers as demand is bifurcating toward electrification and autonomous assembly requirements. TE Connectivity Ltd. leverages its automotive sensor portfolio to anchor high-voltage battery monitoring contracts with domestic EV builders. Honeywell International Inc. competes through manufacturing scale in pressure transducers for petrochemical clients along China's eastern seaboard. Siemens AG dominates industrial automation integration, embedding sensors into its programmable logic controller ecosystems across state-owned steel mills.
Industrial sensors are electromechanical devices that transduce physical quantities—pressure, temperature, displacement, or optical reflectance—into standardized electrical signals, typically 4-20 mA or digital IO-Link protocols, enabling real-time process monitoring and closed-loop control in automated environments. Their primary commercial purpose is to reduce unplanned downtime and tighten quality tolerances in continuous-flow production. Pressure sensors lead product type revenue due to ubiquitous deployment in hydraulic systems and pipeline infrastructure, while optical technology is expanding fastest as machine vision replaces manual inspection in semiconductor packaging. Wireless installation is capturing incremental share in retrofit deployments where cabling costs would disrupt existing plant layouts.
MIIT's smart manufacturing standards and China's GB certification requirements for electromagnetic compatibility are tightening product entry criteria, forcing foreign suppliers to localize testing laboratories in Shenzhen or Suzhou. SAMR's metrology enforcement on sensor accuracy classes is reshaping procurement specifications for state-funded infrastructure projects. Stakeholders must monitor how NMPA's eventual extension of medical-device-grade sensor standards into industrial hygiene applications could open or foreclose adjacent revenue streams.
Market Dynamics
MIIT's smart manufacturing mandates are compressing deployment timelines across automotive and steel sectors, forcing sensor vendors to localize production and certification capabilities within 18-month procurement cycles.
Growth Catalysts
- Dual Carbon Policy Framework:Beijing's emissions reduction targets mandate real-time energy monitoring in heavy industry, accelerating demand for power consumption sensors in state-owned steel mills.
- Yangtze River Delta Cluster Concentration:Shanghai's automotive hub concentrates precision assembly demand, creating dense procurement pools for proximity and vision sensing systems.
- GB Electromagnetic Compatibility Standards:Mandatory certification for industrial equipment is filtering out uncertified imports and elevating compliant domestic suppliers in infrastructure tenders.
Market Restraints
- Semiconductor Input Volatility:MEMS die and ASIC shortages from Taiwan-based foundries create 12-16 week lead time variability for pressure sensor manufacturers.
- Foreign Vendor Localization Costs:SAMR's metrology enforcement requires in-country calibration laboratories, adding fixed cost burdens for European and North American suppliers without existing Suzhou or Shenzhen facilities.
- Optical Sensor Price Erosion:CMOS image sensor commoditization from consumer electronics overflow is compressing margins for machine vision applications in semiconductor packaging.
Strategic Opportunities
- Sichuan and Chongqing Industrial Corridor:Underpenetrated western provinces offer first-mover positioning as automotive supply chains diversify from coastal concentration.
- Wireless Retrofit Channel:Battery-powered IO-Link wireless adapters are opening brownfield installations where cable trenching would disrupt continuous chemical processing operations.
- Medical-Industrial Convergence:NMPA's draft hygiene standards for pharmaceutical manufacturing equipment create adjacent certification pathways for sensor vendors with cleanroom-grade product lines.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers proficient in real-time operating systems and edge computing architectures delays product development cycles for smart sensor variants.
- Legacy PLC Integration Complexity:Proprietary communication protocols from incumbent automation vendors create interoperability friction during brownfield sensor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Industrial Sensors Market |
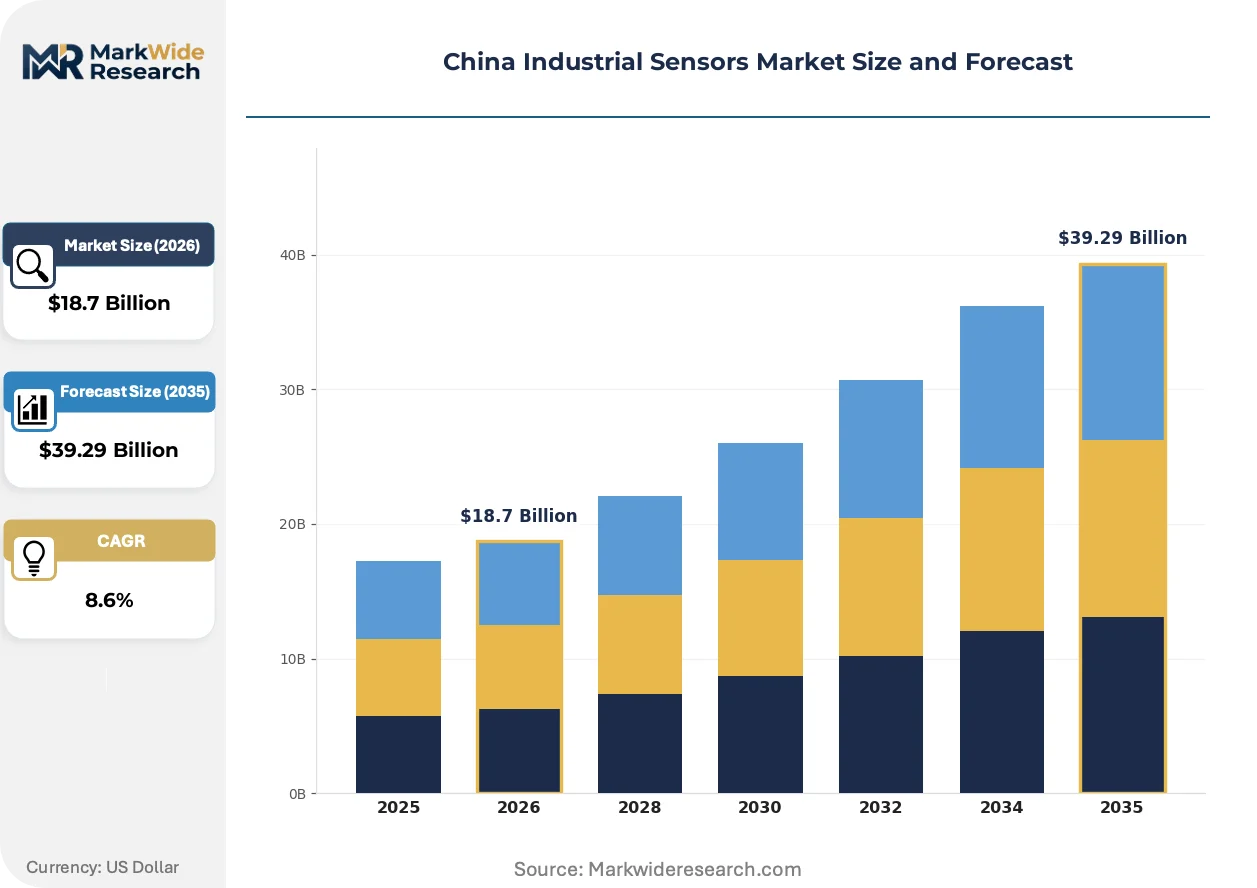
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Level Sensors Technology: Capacitive, Resistive, Optical, Inductive End User: Manufacturing, Automotive, Aerospace, Energy Installation: Fixed, Portable, Integrated, Wireless |
| Companies Covered | TE Connectivity Ltd., BYD Semiconductor, Honeywell International Inc., Siemens AG, Henan Hanwei Electronics, Emerson Electric Co., Shanghai Zhaohui Pressure Apparatus Co., Ltd., Texas Instruments Incorporated, STMicroelectronics N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Industrial Sensors Market Emerging Trajectories
Sensor architecture is splitting between high-performance edge computing nodes and stripped-down cost-optimized units, with deployment patterns diverging sharply by end-use sophistication.
Edge AI inference is bifurcating the product landscape. Advanced nodes with on-chip neural processing units handle real-time anomaly detection in automotive battery assembly. Cost-optimized units without compute capability dominate hydraulic pressure monitoring in bulk chemical processing. This split is compressing mid-tier sensor margins as buyers refuse to pay premium prices for undifferentiated 4-20 mA output devices.
MIIT's GB/T industrial internet standards are mandating unified data interface protocols across state-funded smart factory projects. Equipment vendors must certify OPC UA and MQTT compatibility to qualify for procurement lists. Automotive OEMs in the Yangtze Delta are responding fastest, embedding standardized communication stacks into new assembly line specifications ahead of petrochemical clients.
Buying committees are consolidating sensor procurement under central engineering teams, displacing plant-level maintenance departments that historically specified replacement units. Tier-1 automotive suppliers are leading this shift, negotiating enterprise-wide framework agreements with TE Connectivity and Honeywell for multi-site sensor supply. The pattern is most visible in Jiangsu and Zhejiang provinces where OEMs operate three or more assembly facilities.
China Industrial Sensors Market Segmentation
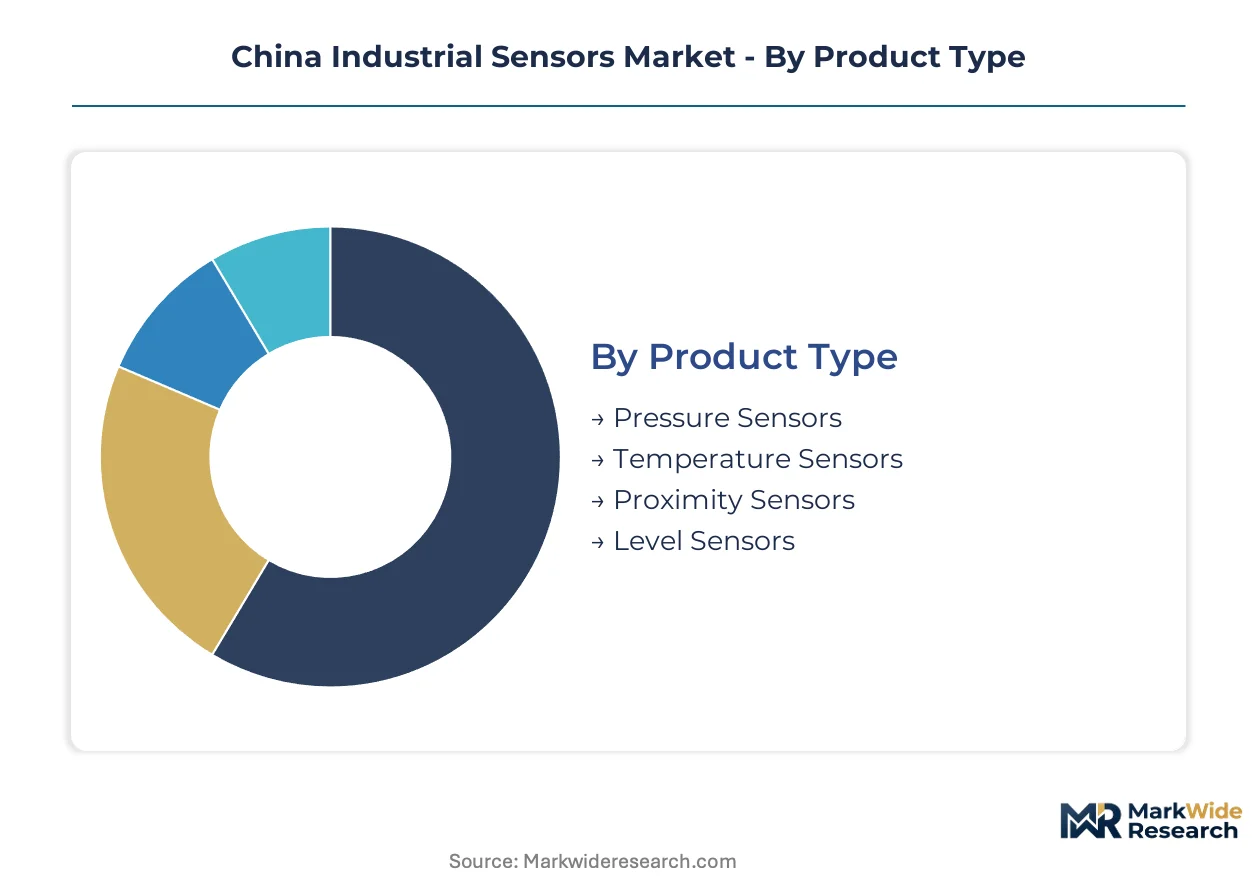
Segmentation in China's industrial sensors market exposes where MIIT's smart manufacturing mandates concentrate procurement power and which technologies face displacement from wireless retrofit alternatives. Buyers in the Yangtze River Delta automotive cluster are compressing supplier lists around certified product categories that integrate cleanly with Siemens PLC ecosystems.
Product Type:
Pressure sensors face the strongest substitution pressure from integrated multi-parameter units in new automotive battery assembly lines, while discrete temperature probes retain defensible positions in legacy steel mill retrofits.
- Pressure Sensors:Piezoresistive and capacitive transducers dominate hydraulic system monitoring with 4-20 mA output standardization. Demand concentrates in petrochemical pipelines along China's eastern seaboard where SAMR's metrology enforcement mandates accuracy class certification.
- Proximity Sensors:Inductive and capacitive variants handle position detection in automated welding cells. Shanghai's automotive OEMs specify IO-Link digital outputs for real-time quality traceability in electric vehicle battery module assembly.
- Temperature Sensors:RTD and thermocouple configurations monitor thermal profiles in continuous casting operations. State-owned steel mills under Dual Carbon policy mandates drive replacement cycles.
- Level Sensors:Ultrasonic and radar technologies manage bulk liquid inventory in chemical processing. Jiangsu province's fine chemical clusters prioritize non-contact measurement for corrosive media.
Pressure sensors anchor the volume base while proximity sensors gain share at the steepest rate.
Technology:
Cost tiers separate capacitive and resistive legacy platforms from optical systems where CMOS commoditization is eroding hardware margins.
- Capacitive:Microelectromechanical structures measure pressure and acceleration through dielectric displacement. Bulk chemical processors in Shandong province favor the technology's corrosion resistance in humid environments.
- Optical:Photoelectric and laser-based systems enable machine vision inspection in semiconductor packaging. CMOS image sensor overflow from consumer electronics is compressing unit economics.
- Resistive:Strain gauge configurations dominate load cell applications in materials handling. Mature supply chains limit differentiation.
- Inductive:Eddy-current and LVDT principles detect metallic target proximity without physical contact. Automotive tier-1s specify the technology for weld seam positioning.
Resistive platforms anchor installed base volumes while optical technology climbs the fastest despite margin pressure.
End User:
Customer type determines specification authority—central engineering teams at automotive OEMs versus plant-level maintenance departments in fragmented manufacturing.
- Automotive:Battery assembly and autonomous driving validation require precision position and current sensing. Yangtze River Delta OEMs consolidate procurement under enterprise framework agreements.
- Manufacturing:Discrete automation in consumer electronics and white goods production drives high-volume demand for cost-optimized proximity units. Zhejiang province's private manufacturers resist premium pricing for undifferentiated 4-20 mA devices.
- Energy:Power generation and grid infrastructure deploy temperature and pressure monitoring for turbine and transformer protection. State Grid procurement favors domestic suppliers with GB certification.
- Aerospace:Military and commercial aviation applications demand hermetic packaging and extended temperature ranges. Limited volume constrains supplier participation.
Manufacturing anchors volume demand while automotive applications expand most quickly through electrification mandates.
Installation:
Geography dictates installation architecture—coastal greenfield plants accept integrated systems while inland brownfield retrofits drive wireless adoption.
- Wireless:Battery-powered IO-Link adapters eliminate cable trenching in continuous chemical processing. Sichuan and Chongqing industrial corridors favor retrofit deployments where production disruption is cost-prohibitive.
- Integrated:Embedded sensor-PLC combinations dominate new automotive assembly line construction. Shanghai's smart factory mandates require OPC UA protocol compatibility.
- Fixed:Hardwired 4-20 mA installations persist in legacy steel and petrochemical infrastructure. Replacement cycles align with MIIT equipment upgrade timelines.
- Portable:Handheld diagnostic units support maintenance calibration and spot-checking applications. Limited standardization constrains scale.
Fixed installations anchor the installed base while wireless configurations gain adoption fastest in western corridor brownfield projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement committees concentrate demand in coastal manufacturing belts, while state-owned heavy industry drives replacement cycles in northern and western provinces. MIIT's smart manufacturing mandates compress deployment timelines unevenly across these geographies.
Yangtze River Delta
Shanghai's automotive hub concentrates precision proximity and vision sensing demand for electric vehicle battery assembly. MIIT's GB/T industrial internet standards mandate OPC UA protocol compatibility for state-funded smart factory projects. Jiangsu and Zhejiang OEMs negotiate enterprise-wide framework agreements covering multi-site sensor supply.
Pearl River Delta
Guangdong's consumer electronics manufacturing drives high-volume demand for cost-optimized position sensors. SAMR's metrology enforcement on accuracy classes shapes procurement specifications for export-oriented manufacturers. Shenzhen's industrial cluster hosts localized testing laboratories that foreign suppliers operate to meet GB electromagnetic compatibility certification.
Beijing-Tianjin-Hebei
State-owned steel mills under Dual Carbon policy mandates accelerate temperature and pressure sensor replacement cycles. MEE emissions reduction targets require real-time energy monitoring infrastructure. Tangshan's heavy industrial base deploys power consumption sensors for compliance reporting.
Sichuan-Chongqing Corridor
Underpenetrated western provinces attract first-mover positioning as automotive supply chains diversify from coastal concentration. Battery-powered IO-Link wireless adapters gain traction in brownfield chemical processing installations where cable trenching would disrupt continuous operations. Chongqing's growing automotive assembly capacity concentrates new demand.
Shandong Peninsula
Bulk chemical processors favor capacitive sensing technology for corrosion resistance in humid environments. Petrochemical pipelines along the eastern seaboard drive pressure transducer demand with SAMR-mandated accuracy class certification. Qingdao's fine chemical clusters prioritize non-contact level measurement for corrosive media.
China Industrial Sensors Market Vendor Landscape
Player mix skews toward multinational automation integrators and domestic component specialists competing on certification speed and localization depth. Market structure exhibits tiered consolidation with premium positioning held by full-system vendors and mid-tier fragmentation among discrete sensor fabricators. Strategic archetypes separate automotive-focused precision suppliers from process-industry scale players and emerging wireless retrofit specialists. Competitive moves center on in-country calibration laboratory establishment and backward integration into MEMS die sourcing.
Within the multinational integrator tier, TE Connectivity Ltd., Honeywell International Inc., and Siemens AG exemplify divergent positioning strategies. TE Connectivity anchors automotive-oriented precision sensing through high-voltage battery monitoring relationships with domestic EV builders. Honeywell occupies a position emphasizing manufacturing scale in pressure transduction for petrochemical applications. Siemens represents full-system integration dominance, embedding sensing capabilities within programmable logic controller ecosystems deployed across state-owned steel operations.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| BYD Semiconductor |
| Honeywell International Inc. |
| Siemens AG |
| Henan Hanwei Electronics |
| Emerson Electric Co. |
| Shanghai Zhaohui Pressure Apparatus Co., Ltd. |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| Others |
Supply Flow & Price Mechanics
MIIT's GB electromagnetic compatibility certification gates both supplier qualification and price differentiation simultaneously, forcing foreign vendors to absorb fixed laboratory costs in Shenzhen or Suzhou while domestic competitors leverage pre-certified status for aggressive positioning in state-funded tenders.
Pricing Analysis
Current-generation optical sensors with on-chip neural processing units command substantial premiums over prior-generation 4-20 mA analog devices, while next-generation wireless IO-Link variants are entering at mid-tier price points. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in optical hardware is intensifying because CMOS image sensor overflow from consumer electronics feeds component spot markets. Plant-level maintenance departments in Zhejiang's private manufacturers exhibit the highest price sensitivity, whereas central engineering teams at Yangtze River Delta automotive OEMs prioritize performance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for MEMS die and ASIC components that feed pressure sensor assembly, while Japan supplies specialized ceramic substrates for high-temperature applications. The supply chain draws from silicon foundries, rare earth magnet producers, and precision machining houses concentrated in East Asia. Single-source vulnerability around Taiwan-based MEMS foundries creates procurement risk for European and North American vendors without captive supply arrangements. Distribution runs through authorized distributor networks serving provincial industrial clusters, with direct enterprise contracts gaining share among automotive OEM procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated multi-parameter sensing units threaten discrete sensor incumbents by collapsing multiple measurement functions into single hardware nodes, forcing established vendors to defend installed base positions through firmware lock-in and protocol entrenchment.
For Market Incumbents: Consolidate calibration laboratory footprints in Suzhou and Shenzhen to satisfy SAMR metrology enforcement before procurement cycles close. Deepen backward integration into MEMS die sourcing to insulate margin structures from Taiwan foundry lead time variability. Lock in automotive OEM relationships through enterprise framework agreements spanning multiple Yangtze River Delta assembly facilities.
For New Entrants and Emerging Players: Anchor in Sichuan-Chongqing corridor brownfield retrofit opportunities where wireless IO-Link adapters eliminate cable trenching costs that incumbent systems cannot address. Target battery-powered installation architectures in continuous chemical processing plants where production disruption renders wired alternatives uneconomical. Pursue certification-fast partnerships with domestic automation integrators already qualified on state-funded smart factory project lists.
For Investors and Strategic Acquirers: NMPA's eventual extension of medical-device-grade standards into industrial hygiene applications reshapes the acquisition landscape by privileging sensor vendors with cleanroom-grade product lines and pharmaceutical manufacturing equipment relationships. Five-to-ten year viability hinges on positioning for medical-industrial convergence rather than pure process automation exposure. Monitor draft hygiene standard publication timelines as the critical signal for allocating capital toward certified cleanroom capability platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Die Sourcing | Captive supply from Taiwan foundries insulates margin structures from 12-16 week lead time volatility. |
| Localized Calibration Laboratory Establishment | Suzhou and Shenzhen facilities satisfy SAMR metrology enforcement for state-funded infrastructure tenders. |
| Wireless IO-Link Product Line Launch | Battery-powered adapters unlock Sichuan-Chongqing brownfield retrofit demand without cable trenching disruption. |
| Enterprise Framework Agreement Negotiation | Multi-site automotive OEM contracts in Jiangsu and Zhejiang consolidate procurement under central engineering teams. |
| Cleanroom-Grade Certification Pathway Investment | NMPA hygiene standard alignment opens adjacent revenue streams in pharmaceutical manufacturing equipment. |
Methodological Framework
The analysis maps pressure, proximity, temperature, and optical sensing sub-sectors, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and MIIT policy specialists. Primary fieldwork with maintenance directors at state-owned steel mills and central engineering leads at automotive OEMs combined with secondary validation from SAMR metrology bulletins, MIIT smart manufacturing standard releases, and enterprise procurement database extracts. Bottom-up sensor shipment modeling and top-down industrial automation spend estimates provided cross-check triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology generation, end-use industry, installation architecture, and regional cluster dimensions. CAGRs were derived from fitted growth curves incorporating MIIT mandate implementation timelines, Dual Carbon policy compliance deadlines, and automotive electrification content expansion assumptions.
Material uncertainties — semiconductor input volatility, regulatory standard revision timelines, and automotive supply chain geographic diversification — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification pathway durations and procurement committee consolidation patterns. Recalibration cycles align with material shifts in MIIT standard publication, NMPA hygiene draft finalization, and foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
MEMS-Based Oscillator Market