
 Tactile Indicators Market | 2026-2036
Tactile Indicators Market Size, Share, and Industry Trends Forecast 2026-2036
Tactile Indicators Market Insights
The EU Green Deal is repositioning procurement criteria across European manufacturing supply chains, compelling material suppliers to certify carbon footprints for silicone and metal substrates used in tactile indicator production. Guardian Tactile Systems leverages vertically integrated polymer compounding to secure batch consistency for automotive tier-one contracts. DTAC Pty Ltd anchors its competitiveness in precision-molded electromechanical assemblies serving medical device OEMs across Asia-Pacific. Classic Architectural Group dominates specification-driven public infrastructure projects through direct relationships with municipal accessibility officers.
Tactile indicators are surface-mounted or integrated physical features—typically raised domes, bars, or textured pads manufactured through injection molding, CNC machining, or stamped forming from elastomer, thermoplastic, or stainless steel stock—that provide positional, directional, or hazard-warning feedback through fingertip contact in low-visibility environments. Their primary purpose spans pedestrian wayfinding compliance, machine interface operability without visual confirmation, and enhanced safety in transportation hubs. Silicone formulations command premium positioning in medical and food-contact applications where biocompatibility and sterilization resistance justify higher unit economics. Electromechanical technology is gaining fastest in automotive and consumer electronics as force-feedback integration deepens, while mechanical variants remain the volume base in public infrastructure where capital budgets constrain sensorization.
The EU's CE marking framework and the F-Gas Regulation constrain polymer processing inputs for European-based manufacturers, while the US ADA Standards for Accessible Design mandate dimensional and contrast specifications that shape product development priorities for North American suppliers. ISO 23599 provides the international reference for tactile walking surface indicators, creating a baseline that national regulators including Japan's METI and Australia's building code authorities adapt with local amendments. Stakeholders must monitor divergence between electromechanical performance standards emerging from automotive OEMs and the static compliance benchmarks that still govern public-sector procurement cycles.
Market Dynamics
Automotive OEM integration standards for haptic feedback systems are compressing development cycles and forcing material suppliers to certify carbon footprints under EU Green Deal procurement criteria.
Growth Catalysts
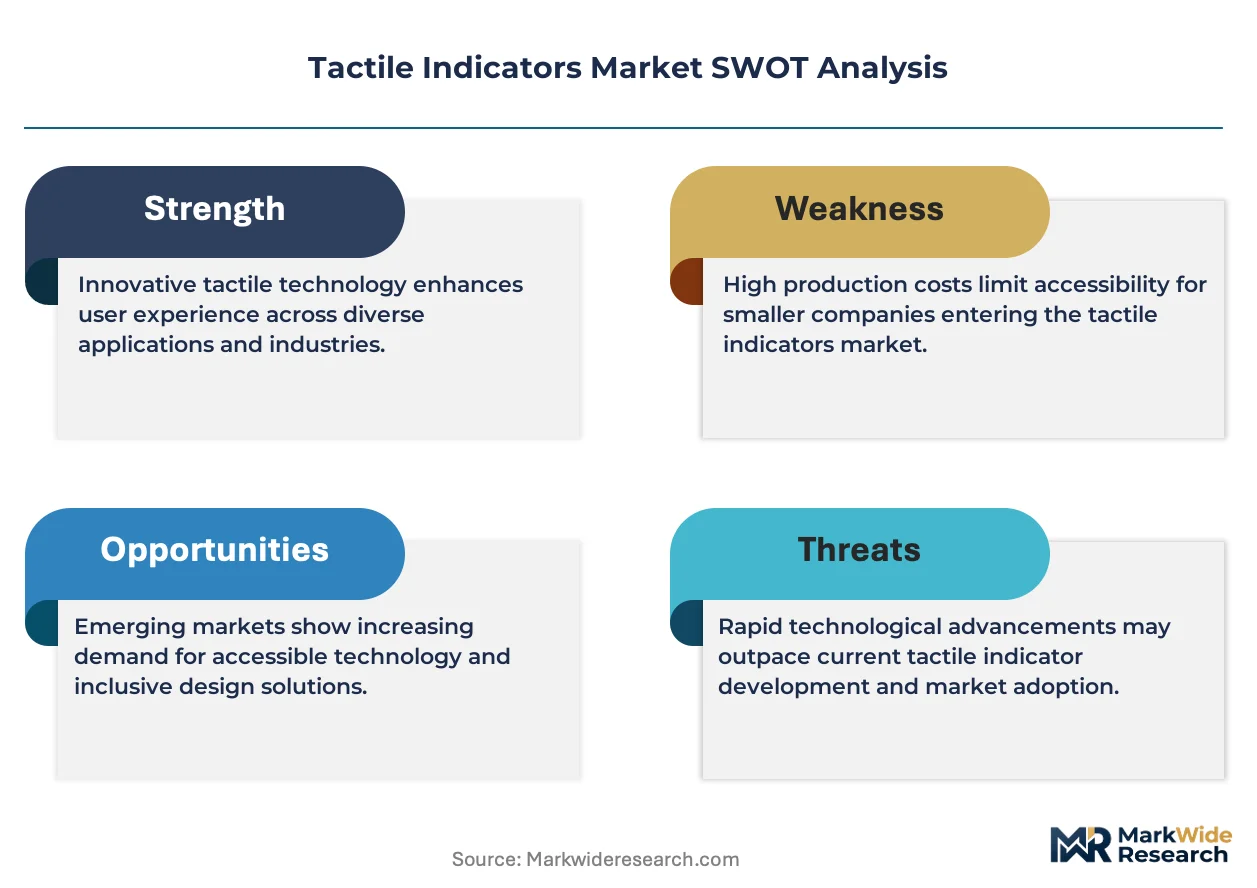
- EU Green Deal carbon certification:Procurement criteria now mandate verified lower-carbon silicone and recycled metal substrates, redirecting supplier investment toward polymer compounding capabilities.
- Automotive haptic interface deployment:Force-feedback integration in vehicle control panels is accelerating order flows from tier-one suppliers seeking compliant tactile components.
- Medical device sterilization requirements:Biocompatible silicone formulations are capturing premium positioning in surgical equipment and diagnostic interfaces where autoclave resistance is mandatory.
Market Restraints
- Silicone feedstock volatility:Energy-intensive silicone polymer production exposes margins to natural gas price swings and carbon border adjustment mechanisms.
- Electromechanical sensor supply concentration:Piezoelectric actuator sourcing clusters in East Asian manufacturing corridors, creating single-source vulnerability for automotive programs.
- ADA dimensional compliance rigidity:US Standards for Accessible Design constrain design flexibility for exporters seeking cross-border product uniformity.
Strategic Opportunities
- German OEM specification tightening:Integration standards for haptic feedback systems are creating first-mover advantage for certified suppliers in Europe's largest automotive market.
- Force-feedback convergence with capacitive sensing:Hybrid electromechanical architectures are opening new application space in consumer electronics wearables.
- Municipal accessibility officer direct contracting:Specification-driven public infrastructure procurement is enabling bypass of traditional distribution channels in Australia and Japan.
Industry Challenges
- Polymer compounding talent scarcity:Batch consistency for automotive contracts requires specialized rheology expertise that outpaces vocational training pipeline output.
- CE marking timeline compression:F-Gas Regulation compliance documentation is extending certification cycles for European market entry.
- Legacy mechanical-electromechanical integration:Public-sector procurement cycles still favor static compliance benchmarks while automotive OEMs demand dynamic performance validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactile Indicators Market |
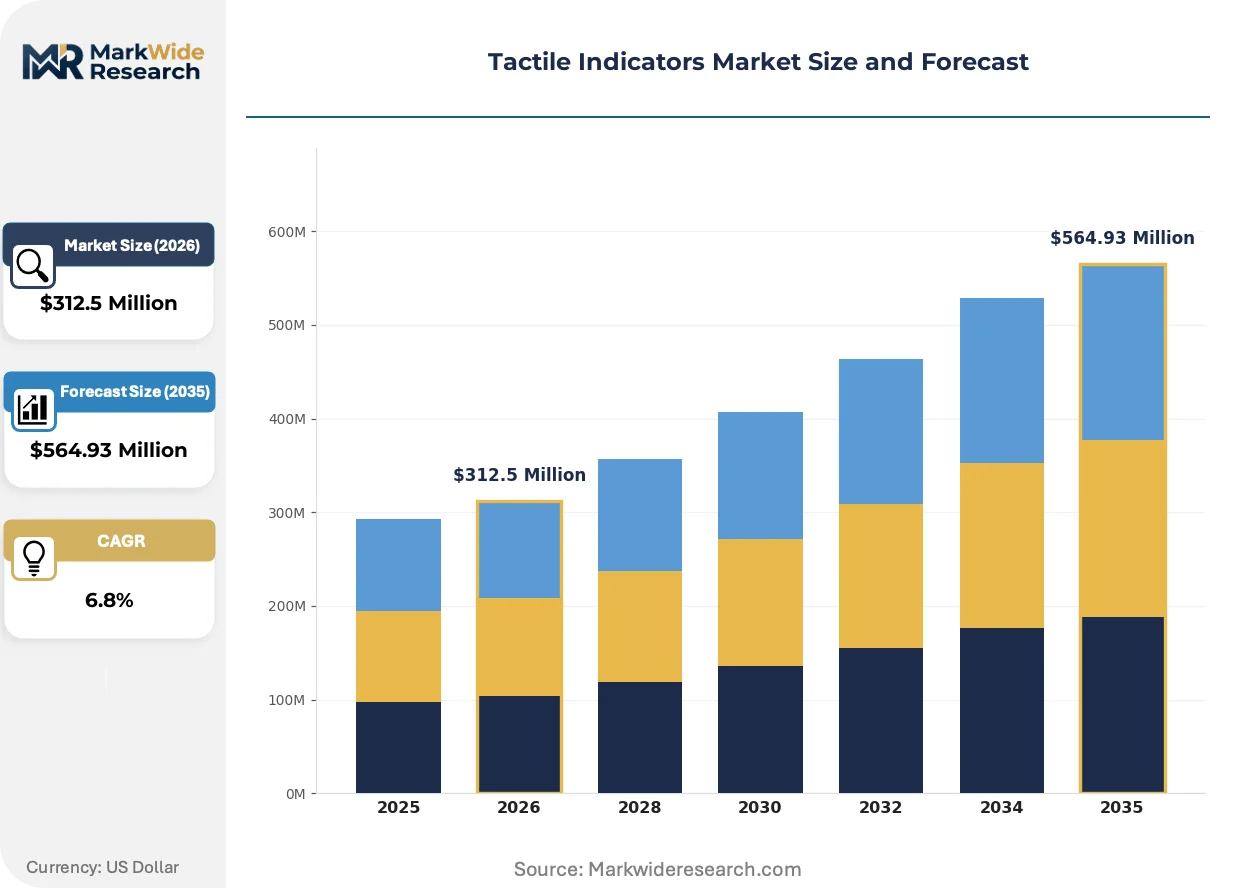
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Consumer Electronics, Automotive Controls, Medical Devices, Home Appliances Material: Silicone, Rubber, Plastic, Metal Technology: Mechanical, Electromechanical, Optical, Magnetic End User: Manufacturers, OEMs, Retailers, Distributors |
| Companies Covered | ARFEN, Guardian Tactile Systems, DTAC Pty Ltd, Classic Architectural Group, Eminent Tactiles, Maruti Engineers, Gimi Access, Eleazar International, Nu Way Industries Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactile Indicators Market Trends and Innovations
Haptic technology maturation is splitting the market between premium electromechanical systems and cost-optimized mechanical variants, with regulatory carbon accounting adding a third axis of supplier differentiation.
Silicone-thermoplastic hybrid formulations are absorbing medical device and food-contact applications where sterilization cycles previously limited material options. Surgical equipment OEMs in Germany and Japan are qualifying these compounds for repeated autoclave exposure. The resulting specification lock-in is absorbing volume from conventional elastomer suppliers unable to match biocompatibility documentation.
REACH substance restriction updates are forcing reformulation of flame-retardant additives in polymer substrates used for transportation hub installations. European compounders are accelerating halogen-free alternatives through pre-registration dossiers. Infrastructure contractors in France and the Netherlands are now specifying certified low-toxicity materials for underground rail projects.
Buyer concentration among automotive tier-one suppliers is compressing switching cycles and demanding consolidated vendor qualification. Haptic module integrators in Stuttgart and Nagoya are unbundling after-sales service contracts from component supply agreements. This pattern is most visible in Germany, where OEM platform standardization is reducing qualified supplier pools to three or four certified compounders per vehicle program.
Tactile Indicators Market Segmentation
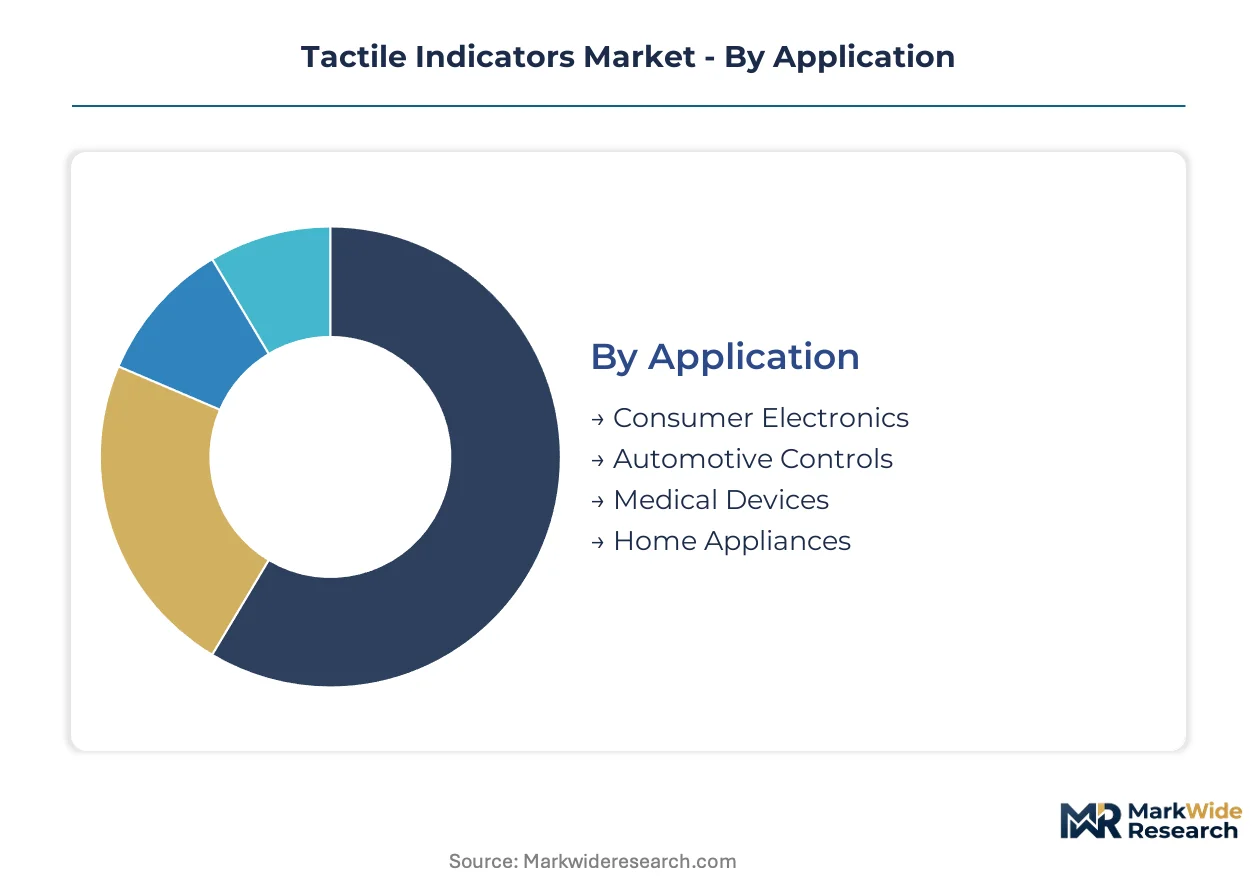
Tactile indicators serve divergent performance requirements across automotive haptic modules, medical sterilization cycles, and public infrastructure compliance. Procurement criteria split sharply between electromechanical force-feedback specifications and static mechanical durability benchmarks.
Application:
End-use buyers prioritize either haptic fidelity for interface differentiation or regulatory compliance for accessibility mandates.
- Consumer Electronics:Force-feedback integration in smartphones and wearables demands micron-level actuation precision. Apple and Samsung supplier qualification programs in South Korea and California are compressing development cycles for piezoelectric actuator assemblies.
- Automotive Controls:Center-stack and steering-wheel haptic modules require vibration damping across temperature extremes. German OEM platform standardization is consolidating qualified supplier pools to three certified compounders per vehicle program.
- Medical Devices:Surgical equipment interfaces specify autoclave-resistant silicone formulations for repeated sterilization.
- Home Appliances:Cost-optimized rubber domes dominate white-goods control panels where haptic sophistication remains secondary to moisture sealing.
Automotive Controls leads on scale; Consumer Electronics leads on momentum.
Material:
Carbon footprint certification under EU Green Deal procurement is redirecting specification authority toward lower-emission substrate options.
- Silicone:Platinum-catalyzed liquid silicone rubber offers biocompatibility and thermal stability for medical and automotive applications. FDA and EU MDR documentation requirements lock in German and Japanese surgical equipment OEMs.
- Metal:Stainless steel stamped domes provide durability for transportation hub installations. Recycled-content certification is becoming mandatory for Paris and Amsterdam metro accessibility contracts.
- Rubber:Nitrile and EPDM compounds serve cost-sensitive appliance and industrial markets.
- Plastic:Thermoplastic elastomers enable overmolding with capacitive touch substrates in consumer electronics.
Silicone commands premium positioning; Metal anchors public infrastructure volume.
Technology:
Development investment splits between sensorized feedback architectures and legacy mechanical reliability.
- Electromechanical:Piezoelectric and linear resonant actuators deliver programmable force profiles. East Asian actuator manufacturing concentration creates single-source vulnerability for Stuttgart and Nagoya haptic module integrators.
- Mechanical:Compression-molded elastomer domes and CNC-machined metal bars remain the volume base. ADA and ISO 23599 dimensional compliance favors proven designs with established certification pathways.
- Optical:Photoelectric position sensing enables non-contact feedback in sterile medical environments.
- Magnetic:Hall-effect based actuation suits extreme-temperature industrial applications.
Mechanical technology dominates unit volume; Electromechanical systems are expanding most quickly.
End User:
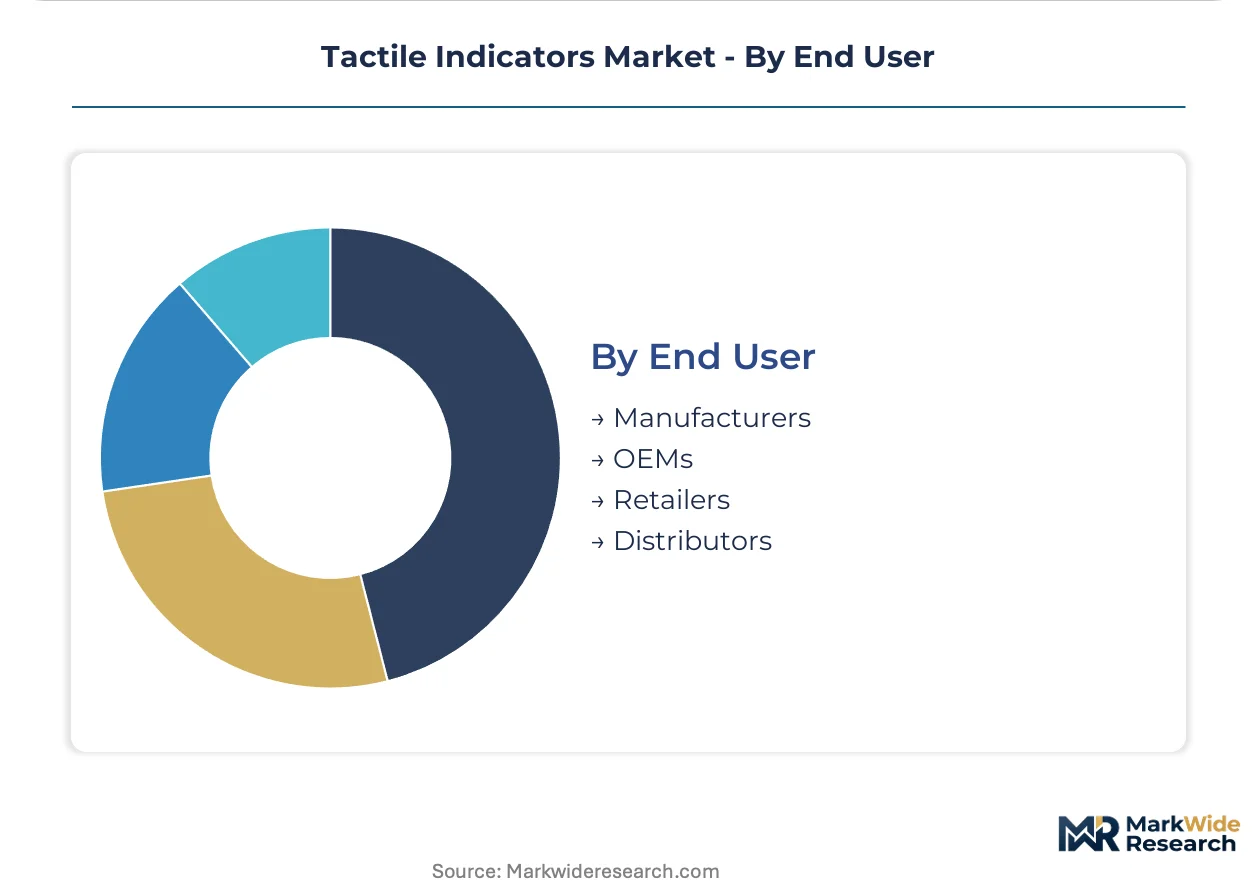
Channel power concentrates among automotive tier-one suppliers and municipal accessibility officers with direct specification authority.
- OEMs:Vehicle platform and medical device manufacturers consolidate vendor qualification and demand consolidated after-sales service contracts. German automotive haptic module integrators are unbundling service agreements from component supply.
- Manufacturers:Tier-two component producers face compressed margins as buyer concentration accelerates.
- Distributors:Traditional channels are losing share to direct municipal contracting in Australian and Japanese public infrastructure.
- Retailers:Consumer electronics aftermarket sales remain fragmented across e-commerce platforms.
OEMs lead on contract value; Manufacturers face the steepest margin pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tactile indicators originated in post-war European accessibility infrastructure before expanding through Japanese precision manufacturing and North American ADA standardization. The current geographic footprint reflects this tripartite heritage with distinct regulatory and industrial specializations across three continents.
Germany
Automotive OEM haptic module integration and medical device sterilization requirements dominate procurement. The EU Green Deal's carbon certification mandates under F-Gas Regulation redirect supplier investment toward lower-emission silicone compounding. Stuttgart and Munich host the continent's densest concentration of tier-one haptic integrators consolidating qualified supplier pools.
United States
ADA Standards for Accessible Design enforcement drives public infrastructure replacement cycles and constrains design flexibility for cross-border exporters. FDA biocompatibility documentation requirements lock in surgical equipment OEMs for premium silicone formulations. California and Massachusetts accessibility officers wield direct specification authority over municipal transit hub installations.
Japan
METI-adapted ISO 23599 amendments shape domestic tactile walking surface indicator procurement for aging population infrastructure. Precision-molded electromechanical assembly demand from surgical equipment manufacturers concentrates in Nagoya and Osaka industrial corridors. JIS standards divergence from international baselines creates specification friction for imported components.
Australia
Building code authorities mandate tactile indicator deployment in transportation hubs with direct municipal accessibility officer contracting bypassing traditional distribution. DTAC Pty Ltd anchors precision-molded electromechanical supply relationships across Asia-Pacific medical device channels. Sydney and Melbourne specification-driven procurement enables domestic compounders to capture public infrastructure volume.
China
Dual carbon goals and GB standards for accessible design are repositioning domestic silicone feedstock sourcing toward lower-emission production corridors. Consumer electronics force-feedback module manufacturing for Apple and Samsung supplier programs concentrates in Shenzhen and Dongguan clusters. MIIT industrial policy accelerates piezoelectric actuator domestication to reduce East Asian sourcing vulnerability.
Tactile Indicators Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors. Mechanical indicator fabricators with captive metal stamping and polymer compounding assets face margin pressure from electromechanical specialists outsourcing actuator sourcing. Three archetypes dominate: vertically integrated compounders serving automotive tier-one programs, precision molders capturing medical sterilization contracts, and specification-driven infrastructure specialists with direct municipal relationships. Consolidation concentrates among automotive haptic module integrators unbundling after-sales service from component supply, while municipal accessibility procurement fragments across regional fabricators.
Among Australia-based specification specialists, DTAC Pty Ltd occupies a position exemplifying precision-molded electromechanical assembly focus. Classic Architectural Group represents the direct municipal contracting archetype with accessibility officer relationships. Guardian Tactile Systems anchors the vertically integrated polymer compounding tier with batch consistency capabilities for certified automotive programs.
| Leading Market Players |
|---|
| ARFEN |
| Guardian Tactile Systems |
| DTAC Pty Ltd |
| Classic Architectural Group |
| Eminent Tactiles |
| Maruti Engineers |
| Gimi Access |
| Eleazar International |
| Nu Way Industries Private Limited |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon certification mandates gate qualified supply and premium-tier pricing access, compelling compounders to document lower-emission silicone and recycled metal substrates before automotive tier-one suppliers will award volume contracts. Buyers without certified documentation face exclusion from German OEM platform standardization programs, compressing margins for uncertified producers while securing pricing power for compliant compounders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates platinum-catalyzed silicone formulations for medical sterilization from nitrile compounds for appliances and stamped metal domes for infrastructure. Price differentiation rests on carbon footprint certification grade and after-sales service bundling rather than raw material cost alone. Cost compression in standard-tier mechanical indicators is intensifying because municipal procurement cycles favor lowest-compliant-bid awards. Appliance manufacturers exhibit highest price sensitivity; surgical equipment OEMs in Germany and Japan demonstrate lowest sensitivity due to autoclave resistance requirements.
Supply Chain Analysis
Single-source vulnerability sits with East Asian piezoelectric actuator manufacturing corridors serving Stuttgart and Nagoya haptic module integrators. Geographic supply concentration clusters in China for consumer electronics force-feedback assembly, Germany for automotive polymer compounding, and Japan for precision-molded medical device components. Raw material dependencies draw from platinum-group metal catalysts for silicone curing, high-purity quartz for piezoelectric substrates, and recycled stainless steel feedstock for transportation hub installations. Tariff exposure on Chinese electronics components threatens cost structures for wearable haptic programs. Distribution runs through automotive tier-one supplier qualification pipelines and direct municipal accessibility officer contracting in Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tactile indicators market functions as a stable compounder where regulatory accessibility mandates and automotive haptic integration sustain predictable replacement cycles and specification-driven procurement.
For Market Incumbents: Acquire polymer compounding facilities with certified batch consistency capabilities to defend against emerging Asian electromechanical specialists. Consolidate after-sales service contracts with component supply agreements as German OEMs unbundle these relationships. Secure F-Gas Regulation pre-registration dossiers ahead of REACH substance restriction updates to maintain European market access. For New Entrants and Emerging Players: Force-feedback convergence with capacitive sensing offers white-space entry into consumer electronics wearables where Apple and Samsung supplier programs compress development cycles. Municipal accessibility officer direct contracting in Australian and Japanese public infrastructure presents the most penetrable channel bypass. Target specification-driven procurement with halogen-free compound documentation for European underground rail projects. For Investors and Strategic Acquirers: Roll-up economics work for precision-molded electromechanical assembly specialists because buyer concentration among automotive tier-one suppliers demands consolidated vendor qualification pools. Five-to-ten-year viability hinges on electromechanical technology share expansion in automotive and medical segments. Watch German OEM platform standardization announcements as inflection indicators for qualified supplier pool consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive silicone formulation control secures batch consistency for automotive tier-one contracts under EU Green Deal mandates. |
| CE Marking Pre-Registration for F-Gas Compliance | Accelerated documentation pathways prevent European market exclusion as REACH substance restrictions tighten. |
| Direct Municipal Accessibility Officer Contracting | Bypass of traditional distribution channels captures specification-driven public infrastructure volume in Australia and Japan. |
| Hybrid Electromechanical-Mechanical Product Architecture | Dual-capability offerings bridge automotive OEM dynamic performance demands with legacy static compliance benchmarks. |
| Halogen-Free Compound Qualification | Certified low-toxicity materials unlock Paris and Amsterdam metro accessibility contracts under updated flame-retardant standards. |
Research Methodology
Bottom-up automotive and medical device modeling reconciled against top-down silicone and metal substrate supply tracking forms the analytical core of this study. Primary interviews with haptic module integrators, municipal accessibility officers, polymer compounding plant managers, and surgical equipment procurement leads combined with secondary validation from SEC filings of listed automotive suppliers, FDA 510(k) clearance databases, EU MDR technical documentation registries, and building code authority procurement records. Triangulation between end-use demand signals and raw material supply constraints validates volume and value estimates.
Historical trendline analysis of automotive platform standardization cycles and medical device sterilization equipment replacement patterns informed projection framework construction across the modeling period. Segmentation dimensions include application type, material substrate, technology architecture, and end-user channel structure. CAGRs derive from fitted growth curves adjusted for regulatory implementation timelines and OEM qualification cycle durations. Industry-specific forecast inputs incorporate German OEM haptic integration roadmaps and METI-adapted ISO 23599 amendment adoption trajectories.
The model holds under stable regulatory enforcement and continued automotive electrification; deviation in EU carbon border adjustment implementation speed or East Asian actuator supply disruption would shift trajectory bands. Forecasts reflect documented assumptions about procurement cycle timing and certification pathway completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Machine Control System Market