
 Piezoelectric Materials Market | 2026-2036
Piezoelectric Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Materials Market Intelligence
Multi-source procurement among precision component buyers is rebalancing toward hybrid models that blend captive ceramic production with external specialty suppliers. CeramTec GmbH anchors European supply through integrated alumina and piezoceramic manufacturing in Germany. Kyocera Corporation dominates fine ceramic value chains across sensor and actuator applications. TDK Corporation leverages thin-film deposition expertise to sustain leadership in microelectromechanical systems.
Piezoelectric materials generate electric charge under mechanical stress and conversely deform under applied voltage, with lead zirconate titanate achieving coupling coefficients above 0.70 for high-efficiency energy conversion in ultrasonic and sensing applications. Bulk ceramics command the largest installed base in industrial sonar and medical imaging transducers due to mature pressing and sintering infrastructure. Thin films and single crystals are capturing accelerated investment from semiconductor equipment and high-frequency telecommunications vendors seeking miniaturization and broader bandwidth. Composite materials occupy premium positioning in aerospace phased arrays where acoustic impedance matching determines performance thresholds.
EPA regulates lead content in electronic materials under TSCA while REACH mandates substitution assessments for persistent substances in European manufacturing, directly influencing formulation roadmaps for lead-free alternatives. Japan's METI promotes piezoelectric energy harvesting through industrial technology grants targeting IoT sensor networks. Stakeholders must monitor evolving material certification requirements and assess captive versus outsourced crystal growth capacity before committing to next-generation actuator and transducer platforms.
Market Dynamics
REACH substitution mandates and China's dual carbon goals are forcing simultaneous reformulation of lead-based piezoceramics while medical imaging OEMs scale ultrasonic transducer procurement, creating a supply squeeze for high-performance lead-free alternatives.
Growth Catalysts
- Diagnostic imaging expansion:Ultrasound equipment manufacturers in Germany and Japan are expanding transducer orders for portable and point-of-care systems, pulling demand for precision-sintered piezoceramic discs.
- RoHS and REACH compliance deadlines:European electronics assemblers face mandatory lead-content thresholds, accelerating qualification of potassium sodium niobate and bismuth sodium titanate formulations.
- Semiconductor equipment miniaturization:Atomic layer deposition tools for wafer processing require thin-film piezoelectric actuators with nanometer-scale precision, concentrating procurement among Japanese and US equipment builders.
Market Restraints
- Raw material concentration:High-purity niobium and tantalum supply routes through Brazilian and Rwandan mining operations expose processors to export licensing volatility and conflict mineral tracing costs.
- Technical performance gaps:Lead-free piezoelectric ceramics currently achieve electromechanical coupling coefficients 15-25% below PZT benchmarks, limiting adoption in high-frequency surgical and industrial applications.
- Energy-intensive sintering:Elevated furnace temperatures required for perovskite-structured ceramics inflate electricity costs, particularly impacting European producers facing carbon border adjustment mechanisms.
Strategic Opportunities
- IoT energy harvesting:METI industrial technology grants in Japan are funding vibration-powered sensor networks for predictive maintenance, opening volume contracts for flexible piezoelectric polymer films.
- Aerospace phased array radar:1-3 piezoelectric composite architectures with tailored acoustic impedance are displacing conventional ceramics in fighter and satellite platforms, with procurement concentrated in US and French defense supply chains.
- Additive manufacturing integration:Binder jetting of piezoceramic pastes enables complex electrode geometries impossible through dry pressing, attracting medical catheter and MEMS probe developers in Switzerland and Massachusetts.
Industry Challenges
- Crystal growth technician scarcity:Bridgman and Czochralski methods for relaxor-PT single crystals require specialized operators, with training pipelines concentrated at Japanese national laboratories and limited university programs in the US and Germany.
- Cross-certification timelines:Medical device PMA and 510(k) submissions for new piezoelectric transducer materials face 18-36 month FDA review cycles, compressing product refresh windows against faster-moving consumer electronics competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Materials Market |
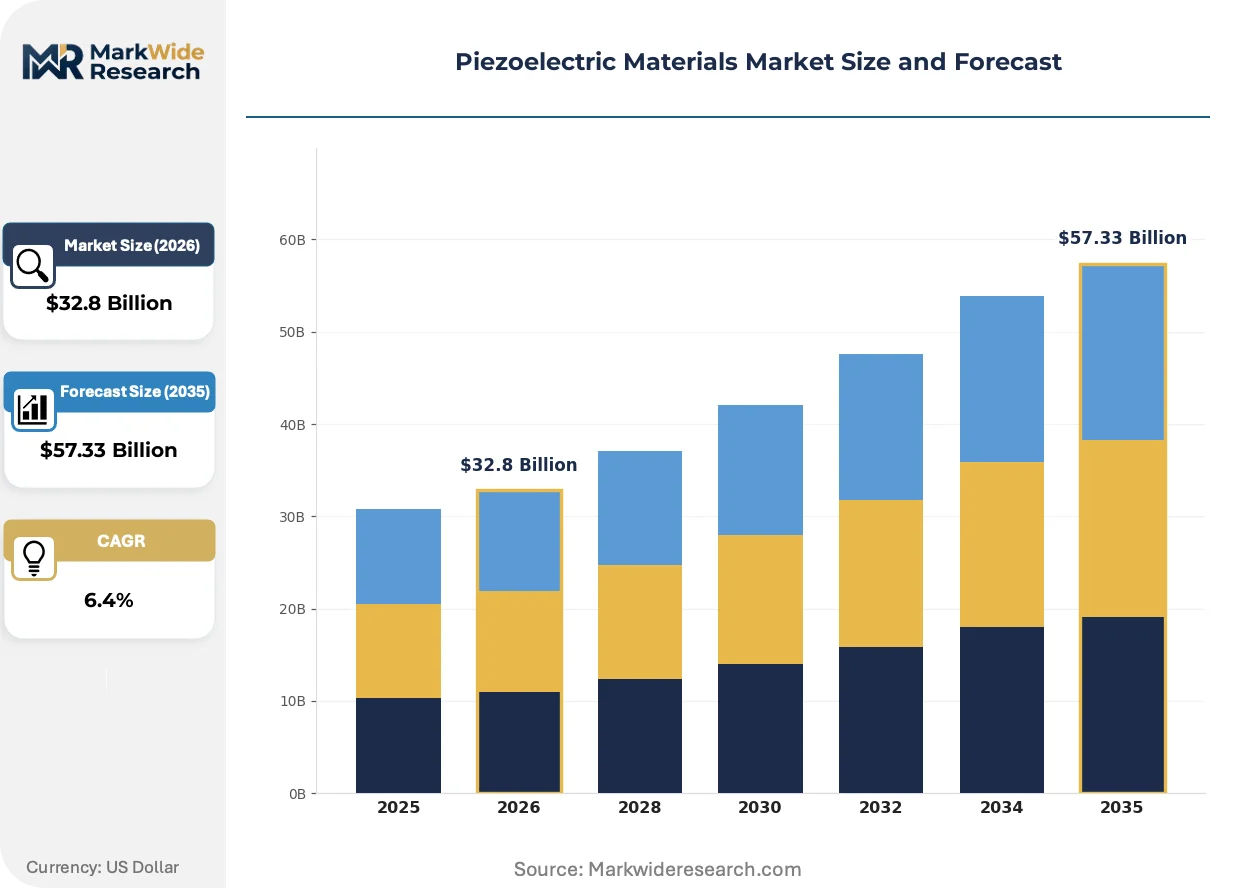
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Zirconate Titanate, Quartz, Barium Titanate, Polyvinylidene Fluoride, Zinc Oxide, Gallium Orthophosphate Technology: Bulk Ceramics, Thin Films, Single Crystals, Composite Materials, Microelectromechanical Systems, Nanostructured Materials Application: Ultrasonic Transducers, Vibration Sensors, Energy Harvesting, Actuators, Medical Imaging, Automotive Sensors End User Industry: Consumer Electronics, Aerospace, Defense, Telecommunications, Industrial Automation, Renewable Energy |
| Companies Covered | CTS Corporation, CeramTec GmbH, Murata Manufacturing Co., Ltd., Kistler Group, Physik Instrumente (PI) GmbH & Co. KG, TDK Corporation, APC International, Ltd., Piezo Technologies, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Materials Market Strategic Shifts & Innovations
Formulation chemistry, deposition techniques, and buyer sourcing protocols are undergoing parallel transformation as environmental compliance and precision manufacturing requirements tighten simultaneously.
Textured potassium sodium niobate ceramics processed through templated grain growth are rewriting performance expectations for lead-free alternatives, with Japanese specialty ceramic houses achieving longitudinal coupling coefficients approaching 0.60. Automotive knock sensor and fuel injector manufacturers in Germany and South Korea are qualifying these materials for 2026 platform introductions. The technology is compressing the historical 15-year gap between laboratory demonstration and industrial adoption for environmentally substituted piezoelectrics.
EPA TSCA Section 6 restrictions on lead in electronic materials are converging with ECHA REACH authorization requirements to force dual-continent formulation roadmaps, compelling material suppliers to maintain parallel development tracks. US-based piezoceramic processors face state-level variations in hazardous substance reporting, with California's Proposition 65 litigation risk adding compliance overhead distinct from federal mandates. Medical ultrasound transducer assemblers are responding by consolidating supplier audits around ISO 13485 and MDR technical documentation standards.
Consignment inventory arrangements are displacing traditional spot purchasing for high-value single-crystal boules, with semiconductor capital equipment OEMs in California and Tokyo assuming carrying costs to secure allocation. Japanese trading houses and German specialty distributors are repositioning as logistics partners rather than margin-stacking intermediaries. The shift is most visible in 300mm wafer inspection tool supply chains, where tool downtime costs exceed $100,000 per hour and material availability guarantees override unit price negotiations.
Piezoelectric Materials Market Segmentation
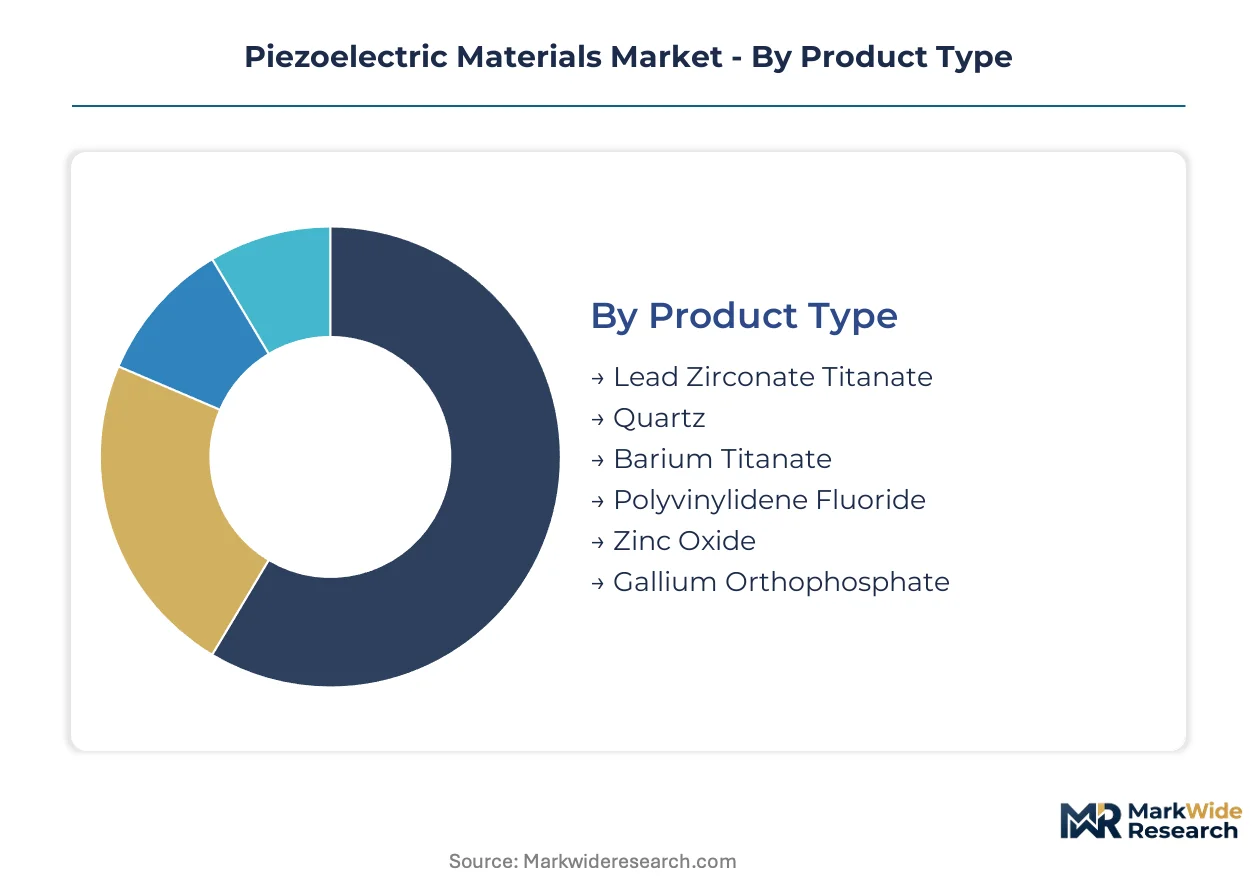
Formulation chemistry, deposition architecture, and end-use specifications fragment procurement requirements across piezoelectric supply chains. Buyers source materials through parallel qualification tracks that match performance thresholds to environmental compliance mandates.
Product Type:
High-purity precursor supply concentrates among German and Japanese chemical processors, with formulation IP determining margin capture across ceramic and polymer categories.
- Lead Zirconate Titanate:Perovskite-structured ceramics achieve electromechanical coupling coefficients exceeding 0.70, enabling high-efficiency energy conversion in diagnostic ultrasound systems. REACH substitution deadlines and China's dual carbon goals are forcing parallel development of lead-free alternatives while medical imaging OEMs in Germany and Japan sustain procurement volumes.
- Polyvinylidene Fluoride:Semi-crystalline fluoropolymer films exhibit piezoelectric response through mechanical stretching and poling, with flexibility suited to curved sensor geometries. IoT vibration monitoring networks in Japanese industrial facilities are scaling procurement under METI technology grants targeting predictive maintenance applications.
- Quartz:Single-crystal SiO2 provides exceptional frequency stability for precision timing applications.
- Barium Titanate:Lead-free perovskite ceramic serves lower-frequency actuator and sensor requirements.
- Zinc Oxide:Wide-bandgap semiconductor nanostructures enable transparent thin-film piezoelectronics.
- Gallium Orthophosphate:Temperature-stable crystal for high-precision resonator and filter applications.
Lead Zirconate Titanate absorbs the bulk of installed capacity; Polyvinylidene Fluoride is expanding most quickly.
Technology:
Processing infrastructure investment separates volume ceramic producers from specialty deposition houses serving semiconductor and aerospace precision requirements.
- Bulk Ceramics:Pressed and sintered piezoceramic discs and plates leverage mature manufacturing infrastructure with established pressing, binder burnout, and high-temperature furnace operations. Industrial sonar and medical imaging transducer assemblers in Germany and the United States source standardized geometries through long-term supply agreements.
- Thin Films:Sputtered or sol-gel deposited layers from nanometers to micrometers thick enable integration with silicon microelectronics. Atomic layer deposition equipment manufacturers in California and Tokyo require nanometer-scale thickness control for wafer positioning actuators in 300mm processing tools.
- Single Crystals:Bridgman and Czochralski growth methods produce relaxor-PT compositions with superior electromechanical coupling.
- Composite Materials:1-3 connectivity architectures tailor acoustic impedance for underwater and biomedical arrays.
- Microelectromechanical Systems:Silicon-compatible micromachining integrates piezoelectric actuation at chip scale.
- Nanostructured Materials:Zinc oxide nanowires and nanoplate arrays enable self-powered sensing platforms.
Bulk Ceramics command the largest production footprint; Thin Films are climbing the fastest on semiconductor equipment demand.
Application:
End-use performance specifications drive material selection across frequency range, power handling, and environmental tolerance requirements.
- Ultrasonic Transducers:Medical imaging systems require precision-sintered piezoceramic elements with matched acoustic impedance to tissue and coupling fluid. Portable and point-of-care ultrasound equipment manufacturers in Germany and Japan are expanding transducer orders, pulling demand for high-density ceramic formulations with consistent grain structure.
- Medical Imaging:Diagnostic equipment spans radiology, cardiology, and point-of-care modalities with stringent FDA PMA and 510(k) certification requirements. Transducer assemblers are consolidating supplier audits around ISO 13485 and MDR technical documentation standards to compress 18-36 month regulatory review cycles.
- Vibration Sensors:Industrial condition monitoring and automotive knock detection deploy ceramic and polymer sensing elements.
- Energy Harvesting:Ambient vibration conversion powers wireless sensor networks without battery replacement.
- Actuators:Precision positioning systems in semiconductor and optical equipment require nanometer-scale displacement control.
- Automotive Sensors:Piezoelectric elements enable fuel injection, tire pressure monitoring, and safety system triggering.
Ultrasonic Transducers represent the dominant demand category; Medical Imaging is gaining share fastest on point-of-care expansion.
End User Industry:
Defense and aerospace procurement concentrates among qualified suppliers with ITAR and security clearance infrastructure, while consumer electronics drives volume through standardized geometries.
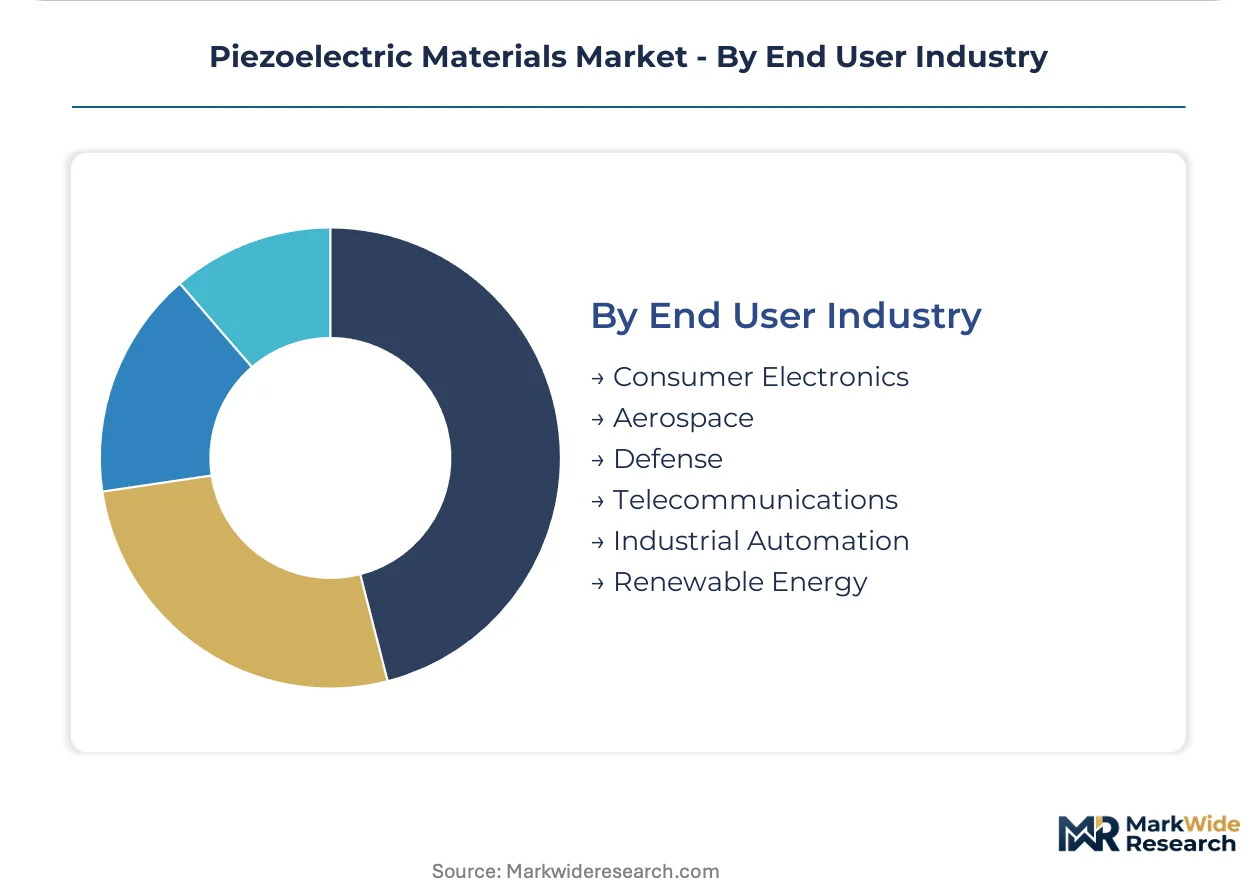
- Consumer Electronics:Touch feedback actuators, microphones, and precision timing devices deploy piezoelectric elements at billion-unit annual scale. Smartphone and wearable manufacturers in South Korea and China source standardized ceramic discs and polymer films through consolidated supplier panels with aggressive cost-down requirements.
- Aerospace:Phased array radar and structural health monitoring systems demand materials with thermal stability across extreme operating environments. Fighter and satellite platforms in US and French defense supply chains are qualifying 1-3 piezoelectric composite architectures with tailored acoustic impedance for weight-critical installations.
- Defense:Sonar, guidance, and electronic warfare systems require qualified materials with traceable supply chains.
- Telecommunications:RF filters and oscillators depend on temperature-compensated resonator materials.
- Industrial Automation:Precision positioning and force sensing integrate piezoelectric actuation and measurement.
- Renewable Energy:Vibration harvesting and structural monitoring support wind turbine and infrastructure applications.
Consumer Electronics captures the greatest unit volume; Aerospace is scaling fastest on defense modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian niobium deposits and Rwandan tantalum routes anchor raw material security for piezoelectric processors. Germany, Japan, and the United States concentrate precision manufacturing clusters. REACH deadlines and China's dual carbon goals are reshaping formulation roadmaps across all three markets.
United States
Semiconductor capital equipment builders in California and Massachusetts drive thin-film actuator procurement for 300mm wafer processing tools. EPA TSCA Section 6 restrictions on lead content force dual-track formulation development alongside European REACH compliance. Boston-area medical device developers face 18-36 month FDA PMA review cycles for new transducer materials.
Germany
Automotive knock sensor and fuel injector manufacturers qualify potassium sodium niobate ceramics for 2026 platform introductions. ECHA REACH authorization requirements mandate substitution assessments for persistent substances in manufacturing. Bavaria and North Rhine-Westphalia host precision-sintering operations supplying diagnostic ultrasound OEMs across Europe.
Japan
METI industrial technology grants fund vibration-powered IoT sensor networks for predictive maintenance in industrial facilities. Japanese specialty ceramic houses achieve longitudinal coupling coefficients approaching 0.60 in textured lead-free formulations. Kanto and Kansai regions concentrate Bridgman and Czochralski crystal growth operations with technician training pipelines at national laboratories.
China
Dual carbon goals accelerate development of lead-free piezoelectric formulations while domestic medical imaging equipment scales production. MEE environmental standards tighten sintering emissions controls for perovskite-structured ceramics. Yangtze River Delta electronics assemblers consolidate supplier panels for standardized ceramic discs and polymer films.
South Korea
Automotive sensor manufacturers qualify Japanese-developed lead-free ceramics for next-generation fuel injection systems. The country's national industrial technology programs support piezoelectric energy harvesting for smart factory applications. Seoul Capital Area and Busan-Ulsan regions concentrate touch feedback actuator production for smartphone and wearable device OEMs.
Piezoelectric Materials Market Key Industry Players
Global majors compete with regional champions across formulation chemistry and deposition architecture. The vendor base separates into integrated ceramic processors with captive sintering infrastructure, thin-film deposition specialists serving semiconductor equipment, and precision actuator assemblers with medical device certification. Strategic moves concentrate on backward integration into high-purity precursor supply and technology licensing for lead-free formulations.
Among Germany-based fabricators, CeramTec GmbH and Physik Instrumente (PI) GmbH & Co. KG occupy positions in integrated alumina and piezoceramic manufacturing. Kyocera Corporation represents Japanese fine ceramic value chains across sensor applications. These three exemplify how geographic clustering around precision manufacturing infrastructure determines competitive positioning.
| Leading Market Players |
|---|
| CTS Corporation |
| CeramTec GmbH |
| Murata Manufacturing Co., Ltd. |
| Kistler Group |
| Physik Instrumente (PI) GmbH & Co. KG |
| TDK Corporation |
| APC International, Ltd. |
| Piezo Technologies |
| Kyocera Corporation |
| Others |
Cost & Logistics Intelligence
REACH substitution mandates and China's dual carbon goals are forcing medical imaging OEMs to dual-source lead-free piezoceramic formulations, compelling suppliers to absorb qualification costs while buyers extend contract terms to secure allocation.
Pricing Analysis
Warranty and technical service bundling separates premium sintered ceramics from commodity-grade discs, with ultrasonic transducer manufacturers in Germany and Japan paying 15-25% premiums for ISO 13485-certified supply with documented grain-structure consistency. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, though cost compression in standard-tier formulations is intensifying as Chinese electronics assemblers consolidate supplier panels. Automotive sensor manufacturers exhibit highest price sensitivity; semiconductor capital equipment builders prioritize availability guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian niobium and Rwandan tantalum routes, where export licensing volatility exposes processors to feedstock disruption. High-purity precursor supply draws from German and Japanese chemical processors, while precision-sintering operations concentrate in Bavaria, North Rhine-Westphalia, and Kanto. Tariff exposure runs through conflict mineral tracing costs and carbon border adjustment mechanisms affecting European furnace operations. Distribution runs through Japanese trading houses and German specialty distributors repositioning as logistics partners with consignment inventory arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piezoelectric materials sector is navigating a technology-transition phase as textured potassium sodium niobate ceramics displace legacy PZT formulations in automotive and industrial sensor applications.
For Market Incumbents: Deepen backward integration into high-purity niobium and tantalum precursor supply to defend against raw material concentration risks, while accelerating captive crystal growth capacity for relaxor-PT single crystals before technician training pipelines at Japanese national laboratories tighten further. Prioritize dual-continent formulation roadmaps that satisfy both EPA TSCA Section 6 and ECHA REACH authorization requirements without parallel development cost duplication. For New Entrants and Emerging Players: Begin with additive manufacturing integration for medical catheter and MEMS probe developers in Switzerland and Massachusetts, where binder jetting of piezoceramic pastes enables complex electrode geometries impossible through conventional dry pressing. Target IoT energy harvesting applications under METI industrial technology grants, positioning flexible piezoelectric polymer films for volume contracts in Japanese predictive maintenance networks. For Investors and Strategic Acquirers: The window for entry favors thin-film deposition specialists with atomic layer deposition expertise serving California and Tokyo semiconductor equipment builders, where tool downtime costs exceeding $100,000 per hour create material availability premiums. Watch textured lead-free ceramic qualification timelines at German automotive OEMs as the inflection indicator for industrial adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Secures niobium and tantalum routes against Brazilian and Rwandan export volatility. |
| Lead-Free Formulation Licensing | Accelerates potassium sodium niobate adoption for REACH and dual carbon compliance. |
| Consignment Inventory Partnerships | Aligns Japanese trading houses with semiconductor capital equipment OEMs in California. |
| Additive Manufacturing Capability Buildout | Enables binder jetting geometries for Massachusetts MEMS probe developers. |
| Crystal Growth Technician Pipeline Investment | Addresses scarcity of Bridgman and Czochralski operators at Japanese national laboratories. |
Research Approach
Independent corroboration across primary interviews with ceramic plant managers, procurement leads at medical imaging OEMs, distribution channel partners, and technical R&D directors, combined with secondary validation through SEC 10-K filings, customs and trade data, and ECHA REACH authorization databases, underwrites the qualitative findings. Bottom-up triangulation across formulation chemistry, deposition architecture, and end-use specifications converges with top-down market sizing.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchor the forecast window across the analysis window. Segmentation dimensions modeled include product type, technology, application, and end-user industry alongside regional production hub clustering. CAGRs derive from slope analysis of normalized growth trajectories, with inputs including METI grant disbursement patterns and FDA PMA submission velocity for transducer materials.
Underlying measurement precision varies by segment; bulk ceramics and thin films carry tighter precision than nanostructured materials and emerging composite architectures. Forecasts reflect documented assumptions about regulatory timeline adherence and substitution technology performance convergence. Specific risks that could revise projections include accelerated REACH deadlines, niobium export licensing moratoriums, and breakthrough single-crystal growth automation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Latin America Wireless Sensors Market