
 Vision Sensor Market | 2026-2036
Vision Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Vision Sensor Market Intelligence
CE marking under the EU Machinery Directive is hardening compliance costs for vision sensor vendors serving European automotive and robotics clients. Cognex Corporation leverages its Massachusetts-based R&D footprint to sustain leadership in industrial barcode verification and defect detection. Keyence Corporation anchors its competitive position through direct sales channels and rapid custom sensor turnaround for Japanese and Southeast Asian factories. Teledyne Technologies differentiates via vertical control over sensor chip design and camera module assembly.
A vision sensor integrates an image sensor, processor, and communication interface into a single device that captures optical data and renders pass-fail decisions without external computing. CMOS sensors now dominate unit shipments due to lower power draw and on-chip integration capabilities, while time-of-flight technology leads growth in robotics and gesture recognition where depth perception matters. Quality inspection remains the most mature application with compressed margins, whereas semiconductor manufacturing demands the highest sensor precision and commands premium pricing tiers.
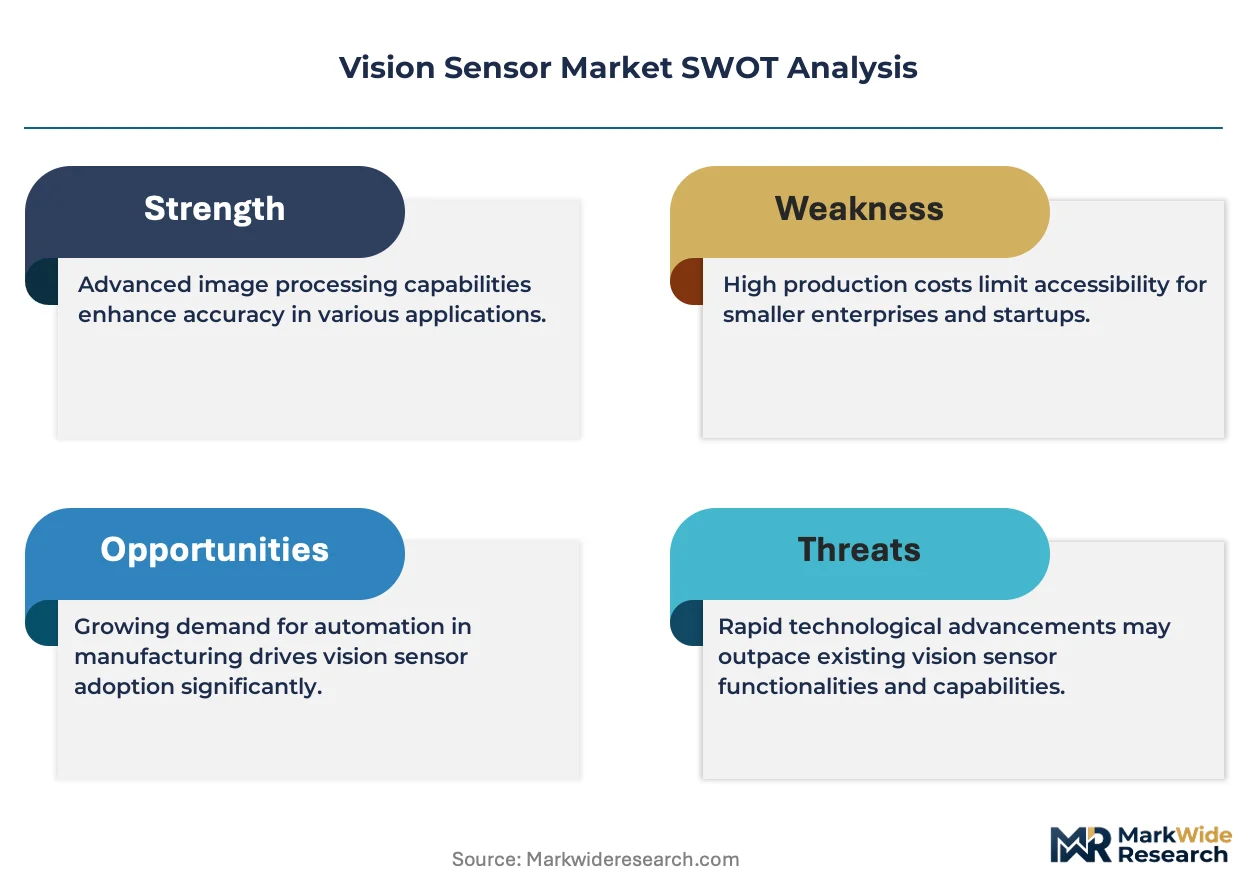
The EU AI Act, FDA software-as-medical-device guidance, and China's GB standard framework for intelligent manufacturing equipment are collectively elevating documentation and validation burdens. FDA scrutiny of machine vision in diagnostic imaging and surgical robotics is redirecting vendor investment toward algorithm auditability and clinical evidence generation. Stakeholders must weigh regulatory pre-certification timelines against product development cycles when prioritizing geographic rollout sequences.
Market Dynamics
The EU AI Act's conformity requirements for safety-critical machine vision are forcing vendors to restructure product architectures around algorithmic auditability, while automotive OEMs in Germany's Stuttgart-Munich corridor accelerate sensor deployment for driver-assistance systems.
Growth Catalysts
- Automotive ADAS mandates:OEM procurement of stereo and time-of-flight sensors for lane-keeping and collision avoidance is tightening specification windows across German, Japanese, and South Korean supply chains.
- CE marking hardening:The EU Machinery Directive's expanded scope for machine vision in robotics is redirecting vendor R&D toward pre-certified modular designs that reduce client validation cycles.
- Semiconductor fab precision demands:Wafer inspection and lithography alignment applications in Taiwan and South Korea are pulling sub-micron resolution sensors into volume production.
Market Restraints
- CMOS sensor supply concentration:Fabrication capacity for specialized industrial-grade imagers concentrates among Taiwanese and South Korean foundries, exposing buyers to allocation risk during capacity crunches.
- FDA validation timelines:Software-as-medical-device pathways for diagnostic imaging applications impose 18-36 month pre-market review cycles that compress commercialization windows.
- Time-of-flight cost structure:Vertical-cavity surface-emitting laser arrays and specialized driver electronics keep depth-sensing modules priced at 3-5x equivalent 2D sensors, limiting adoption outside robotics and premium automotive.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for component manufacturing are attracting sensor assembly investments that could serve ASEAN automation demand with reduced tariff exposure.
- Edge-AI convergence:On-chip neural processing unit integration with CMOS imagers is enabling pass-fail decisions without host computing, opening battery-powered inspection tools for remote agricultural and infrastructure monitoring.
- China's GB standard framework:Intelligent manufacturing equipment certifications are creating a captive domestic market for vendors willing to localize algorithm training data and documentation.
Industry Challenges
- Optics-mechanics-electronics integration:Miniaturized lens assembly and thermal management expertise sits with a narrow supplier base in Japan and Germany, constraining in-house development timelines for mid-tier vendors.
- Multimodal sensor fusion:Combining vision with lidar and radar outputs for automotive perception stacks requires systems engineering capabilities that outpace traditional camera module suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vision Sensor Market |
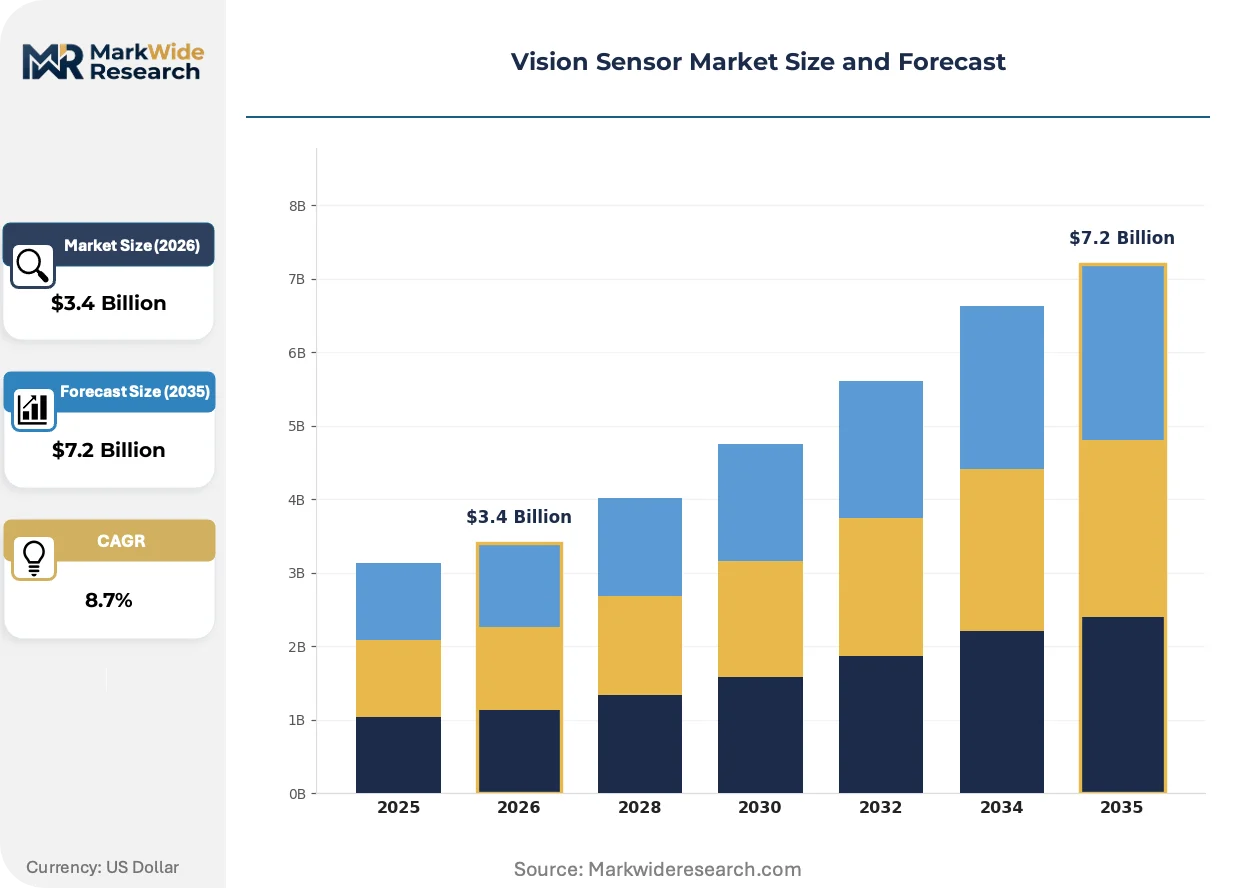
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCD Sensors, CMOS Sensors, Infrared Sensors, Ultrasonic Sensors Technology: Time-of-Flight, Structured Light, Stereo Vision, Laser Triangulation Application: Robotics, Quality Inspection, Traffic Monitoring, Gesture Recognition, Security Surveillance End User Industry: Consumer Electronics, Automotive OEMs, Semiconductor Manufacturing, Agriculture Automation |
| Companies Covered | Cognex Corporation, Keyence Corporation, Teledyne Technologies, Basler AG, SICK AG, Omron Corporation, Baumer Holding AG, National Instruments Corporation, Datalogic S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vision Sensor Market Strategic Shifts & Innovations
On-device processing capabilities are compressing the traditional separation between image capture and decision execution, while regulatory frameworks across the EU, US, and China impose divergent documentation burdens that fragment product roadmaps.
Event-based vision sensors using dynamic vision pixel architectures are decentralizing motion detection and object tracking from centralized frame-processing pipelines. Automotive tier-1 suppliers in Germany and Japan are qualifying these devices for pedestrian detection at 10,000 fps equivalent temporal resolution. The technology is enabling sub-10 millisecond latency perception stacks that compress the sensor-to-actuator loop in emergency braking systems.
The EU AI Act's risk-classification framework for machine vision in safety-critical applications is mandating conformity assessments that extend beyond hardware to training data provenance and model update protocols. Industrial automation vendors serving European automotive clients are restructuring quality management systems around documented algorithm lineage. Medical device manufacturers face overlapping MDR and AI Act obligations that require dual-track regulatory strategies for surgical robotics deployments.
After-sales service unbundling is fragmenting the traditional bundled hardware-software-support contract model in industrial inspection. German automotive suppliers and Japanese electronics manufacturers are piloting sensor-as-a-service arrangements where per-inspection fees replace capital expenditure. This shift concentrates procurement influence with plant-level operations managers rather than central engineering functions, compressing sales cycles but demanding localized technical support capabilities in manufacturing clusters around Stuttgart, Nagoya, and Shenzhen.
Vision Sensor Market Segmentation
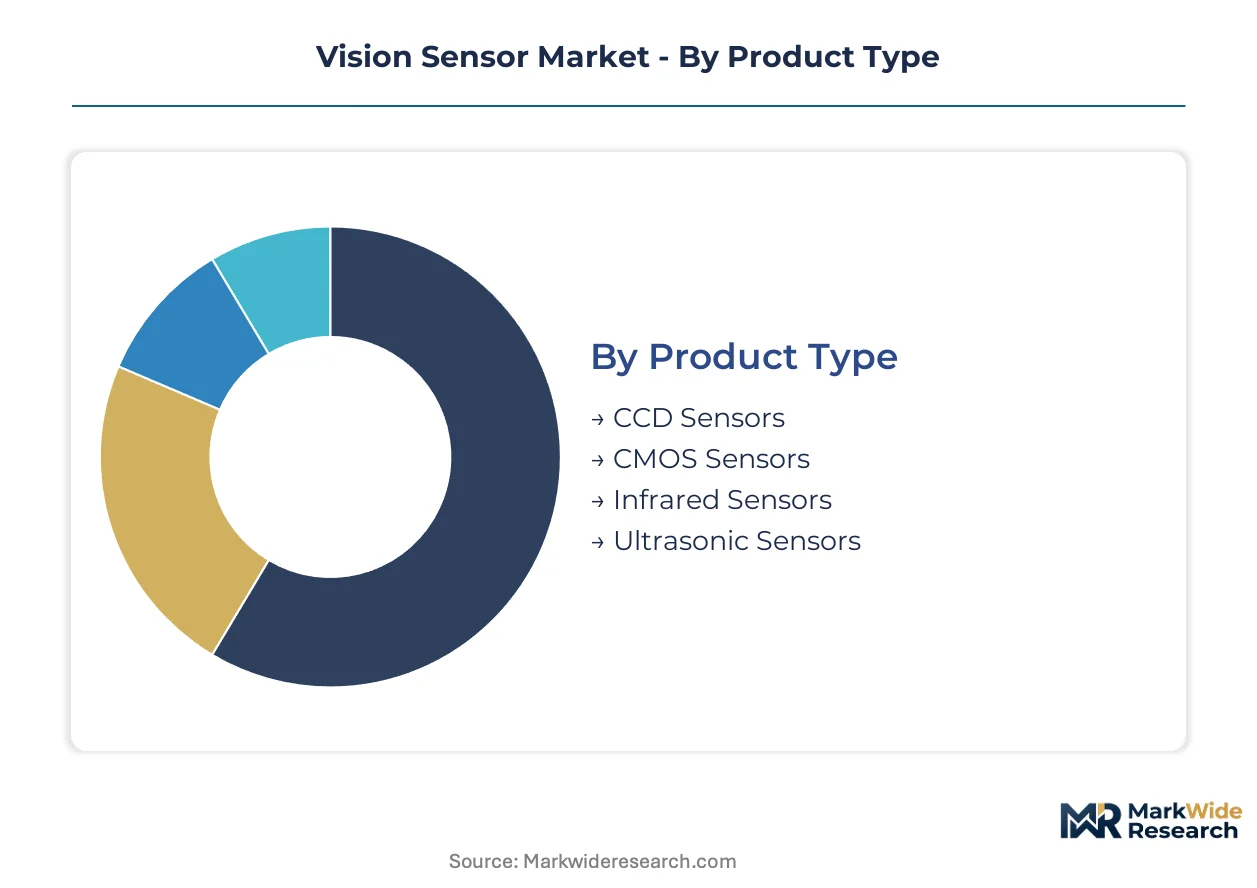
Technology choices in vision sensors lock in performance ceilings and regulatory pathways for years. Upgrade cycles vary sharply across product architectures and end-use environments, creating divergent competitive dynamics within each segment category.
Product Type:
Replacement cycles stretch from 5-7 years in industrial installations to 2-3 years in consumer devices, reshaping vendor revenue predictability across each sensor architecture.
- CMOS Sensors:These devices integrate photodiodes with readout circuitry on a single silicon substrate, enabling lower power consumption and direct on-chip processing. Automotive OEMs in Germany and Japan are specifying automotive-grade CMOS for lane-keeping systems, though supply allocation from Taiwanese foundries tightens during capacity crunches.
- CCD Sensors:Charge-coupled devices deliver superior dynamic range and noise performance through dedicated analog shift registers. Semiconductor manufacturing in Taiwan and South Korea maintains legacy CCD procurement for wafer inspection where absolute precision trumps power efficiency.
- Infrared Sensors:Thermal imaging arrays detect emitted radiation beyond visible wavelengths for night vision and process monitoring.
- Ultrasonic Sensors:Piezoelectric transducers measure distance via sound wave reflection, serving as backup sensing in automotive parking systems.
Volume placements concentrate in CMOS Sensors; the faster expansion belongs to Infrared Sensors.
Technology:
Cost tiers separate premium depth-sensing modules from commodity 2D imaging, with price multiples of 3-5x governing adoption boundaries.
- Time-of-Flight:Vertical-cavity surface-emitting laser arrays measure photon travel time to generate depth maps in real time. Robotics OEMs in Japan and Germany are qualifying these modules for bin-picking applications, though VCSEL driver electronics keep bill-of-materials elevated.
- Stereo Vision:Dual-camera configurations compute depth through geometric disparity matching without active illumination. Automotive tier-1 suppliers around Stuttgart deploy stereo arrays for pedestrian detection, leveraging mature calibration algorithms and passive operation.
- Structured Light:Projected pattern deformation enables sub-millimeter surface mapping for industrial metrology.
- Laser Triangulation:Angular displacement of a laser line yields precise height profiling for inline dimensional inspection.
Structured Light commands the highest average selling prices; Time-of-Flight is climbing the fastest.
Application:
Application maturity governs margin structures, with established quality inspection facing compression while emerging use cases sustain premium pricing.
- Quality Inspection:Automated optical verification of assembly defects and dimensional compliance represents the most penetrated vision sensor application. Electronics manufacturers in Shenzhen and Nagoya operate saturated installed bases, pressuring vendors toward sensor-as-a-service pricing models.
- Robotics:Manipulation and navigation systems demand real-time depth perception and object recognition. German automotive suppliers and Japanese electronics factories are accelerating cobot deployments, pulling multimodal sensor fusion requirements.
- Traffic Monitoring:License plate recognition and vehicle classification systems deploy hardened outdoor cameras.
- Gesture Recognition:Consumer electronics and automotive HMIs interpret hand movements for touchless control.
- Security Surveillance:Perimeter monitoring and facial authentication applications drive volume in government and commercial installations.
Quality Inspection retains the largest installed base; Robotics is gaining share fastest.
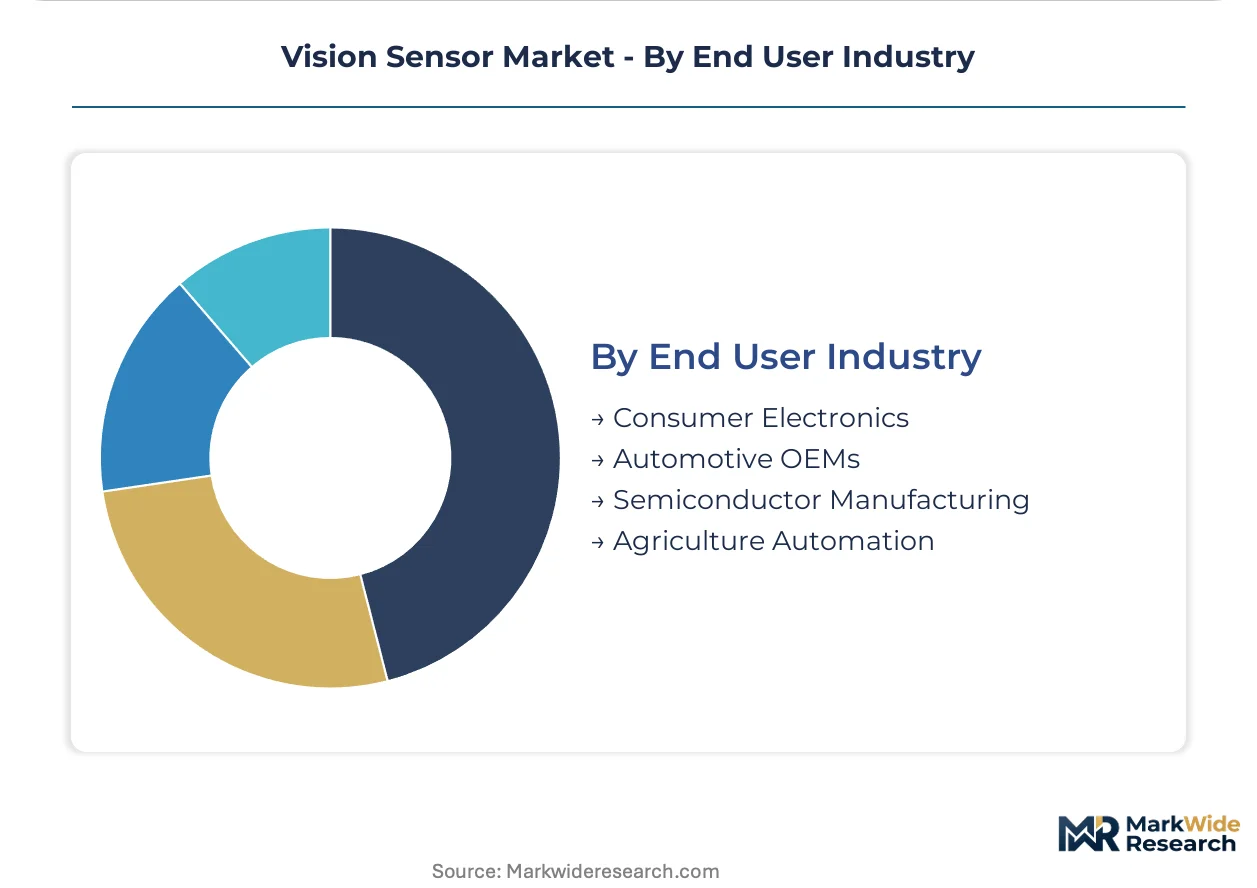
End User Industry:
Customer procurement sophistication varies from centralized engineering specifications in automotive to distributed plant-level decisions in agriculture.
- Automotive OEMs:Tier-1 integration mandates and functional safety certifications under ISO 26262 impose rigorous validation protocols. German manufacturers around Stuttgart and Munich are expanding ADAS sensor procurement, though CE marking under the EU Machinery Directive extends compliance timelines.
- Semiconductor Manufacturing:Wafer inspection and lithography alignment demand sub-micron resolution and vibration isolation. Taiwanese and South Korean fabs command premium pricing tiers for the highest-precision sensor configurations.
- Consumer Electronics:Smartphone and wearable manufacturers drive CMOS volume through annual product refresh cycles.
- Agriculture Automation:Precision farming and autonomous equipment applications are emerging with localized technical support requirements.
Semiconductor Manufacturing captures the steepest pricing premium; Agriculture Automation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in Germany's Stuttgart-Munich corridor, while semiconductor fabs in Taiwan and South Korea pull precision sensor volumes. Regulatory divergence across the EU, US, and China is fragmenting vendor product roadmaps.
Germany
ADAS sensor deployment by BMW, Mercedes-Benz, and Volkswagen anchors European demand for stereo and time-of-flight modules. CE marking under the EU Machinery Directive and ISO 26262 functional safety certifications extend validation timelines for robotics and automotive suppliers. The Stuttgart-Munich industrial corridor hosts concentrated tier-1 integration activity for lane-keeping and collision avoidance systems.
United States
FDA software-as-medical-device pathways for diagnostic imaging and surgical robotics redirect vendor investment toward algorithm auditability and clinical evidence generation. The FDA's 18-36 month pre-market review cycles compress commercialization windows for machine vision in healthcare applications. Greater Boston and Silicon Valley clusters concentrate venture funding for edge-AI sensor startups.
China
GB standard framework for intelligent manufacturing equipment creates a captive domestic market for vendors localizing algorithm training data and documentation. MIIT and SAMR oversight of intelligent manufacturing equipment certifications elevates documentation burdens. The Yangtze River Delta and Pearl River Delta manufacturing belts drive volume demand for quality inspection and cobot vision systems.
Japan
METI industrial automation policies and JIS standards govern robotics sensor procurement by Toyota, Honda, and electronics manufacturers. PMDA oversight of surgical robotics imports imposes parallel validation requirements to FDA pathways. The Nagoya-Toyota industrial corridor and Kansai manufacturing belt concentrate cobot deployment and multimodal sensor fusion development.
South Korea
MFDS medical device regulations and MIIT-aligned industrial standards shape dual-track compliance for semiconductor and healthcare applications. Samsung and SK Hynix fab operations in Gyeonggi Province command sub-micron resolution sensors for wafer inspection at premium pricing tiers. The Seoul Capital Area anchors both semiconductor manufacturing and robotics OEM headquarters.
Vision Sensor Market Key Industry Players
German and Japanese producers anchor one tier; US and Swiss specialists hold differentiated positions in precision imaging and medical applications. The vendor base structures around three strategic archetypes: diversified industrial automation conglomerates, pure-play machine vision specialists, and vertically integrated sensor component suppliers. Consolidation pressure concentrates among mid-tier players lacking captive fabrication or direct sales channel control. Dominant competitive moves include backward integration into sensor chip design and geographic expansion through localized technical service networks.
Within the diversified industrial tier, Cognex Corporation and Keyence Corporation exemplify contrasting channel strategies—Cognex leverages its Massachusetts-based R&D footprint while Keyence anchors competitive position through direct sales coverage. Teledyne Technologies occupies a position emphasizing upstream control over sensor chip design and camera module assembly. These three entities represent the spectrum from software-centric to hardware-integrated competitive positioning in industrial and scientific imaging applications.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Teledyne Technologies |
| Basler AG |
| SICK AG |
| Omron Corporation |
| Baumer Holding AG |
| National Instruments Corporation |
| Datalogic S.p.A. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up machine vision specialists in Germany and Japan exercise pricing discipline through captive service networks while sourcing CMOS wafers from Taiwanese foundries on long-term offtake terms. Their ownership structure concentrates procurement leverage and shields margin structures from spot-market volatility in imaging components.
Pricing Analysis
Short lead-time premiums of 15-25% apply to automotive-grade CMOS sensors for German OEMs facing ISO 26262 recertification deadlines, while spot inventory of standard industrial modules trades at discounts. Three-tier pricing structure across automotive-certified, industrial-grade, and commercial variants separates segments. Pricing pressure stems from sensor-as-a-service unbundling in quality inspection applications. Electronics manufacturers in Shenzhen exhibit highest price sensitivity; semiconductor fabs in Taiwan show least sensitivity due to precision requirements.
Supply Chain Analysis
VCSEL driver electronics rest on Japanese specialty semiconductor producers Hamamatsu and Sony for time-of-flight modules, while precision optics concentrate with German and Japanese lens assembly houses. CMOS imager fabrication draws from Taiwanese and South Korean foundries; structured light pattern projectors source from Chinese optical component mills. Single-source vulnerability runs through automotive-qualified VCSEL arrays. Distribution runs through direct sales forces for Japanese and German vendors, distributor networks for mid-tier players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMOS-on-chip neural processing units are displacing host-computer-dependent architectures, compressing decision latency and enabling battery-powered inspection tools that legacy CCD-based systems cannot match.
For Market Incumbents: Lock in automotive OEM qualification pipelines by pre-certifying modular designs under EU AI Act risk-classification frameworks before CE marking windows tighten. Backward integration into sensor chip design at Massachusetts or Stuttgart R&D centers defends margin position against Taiwanese foundry allocation risk. Channel control through localized technical service networks in the Stuttgart-Munich corridor maintains procurement influence as plant-level operations managers gain decision authority. For New Entrants and Emerging Players: Begin with India's PLI scheme for electronics manufacturing, where production-linked incentives reduce tariff exposure to ASEAN automation demand. Agriculture automation in precision farming and autonomous equipment represents the most penetrable white-space segment, lacking established vendor footprints and requiring only localized technical support. A sensor-as-a-service go-to-market angle bypasses capital expenditure approval cycles at central engineering functions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier industrial automation vendors with CE marking pre-certification assets and direct sales coverage in Germany's industrial corridor. Long-term viability hinges on algorithm auditability capabilities as EU AI Act conformity assessments extend to training data provenance. Watch FDA software-as-medical-device clearance timelines for diagnostic imaging applications as inflection indicator for healthcare segment entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| On-Chip NPU Integration | Edge-AI convergence enables pass-fail decisions without host computing for remote agricultural monitoring. |
| EU AI Act Pre-Certification | Algorithm auditability investments reduce client validation cycles for German automotive robotics suppliers. |
| India PLI Manufacturing Footprint | Production-linked incentives attract sensor assembly investments serving ASEAN demand with reduced tariff exposure. |
| Sensor-as-a-Service Unbundling | Per-inspection pricing concentrates procurement influence with plant-level operations managers in manufacturing clusters. |
| VCSEL Supply Agreement | Long-term offtake terms with Japanese specialty producers mitigate allocation risk for time-of-flight module production. |
Research Approach
Independent corroboration across Tier 1 automotive supplier procurement officers, semiconductor fab equipment managers, robotics OEM platform engineers, and machine vision system integrators underwrites the qualitative findings. Secondary validation draws from FDA software-as-medical-device guidance documents, EU AI Act implementing acts, MIIT GB standard publications, and SEC filings of listed sensor component suppliers. Bottom-up unit shipment estimates triangulate against top-down value projections across the analysis window.
The forecast window anchors to historical CMOS sensor adoption curves in automotive ADAS deployment and industrial automation penetration rates. Segmentation dimensions modeled include sensor architecture, depth-sensing technology, application maturity, and end-user industry procurement sophistication. CAGRs derive from fitted growth curves applied to technology-specific replacement cycles and regulatory adoption timelines. Industry-specific inputs include Taiwanese foundry capacity allocation patterns and German automotive OEM sensor procurement specifications.
Taiwanese foundry capacity crunches, FDA pre-market review timeline extensions, and EU AI Act conformity assessment scope expansions are the dominant revision risks. Forecasts reflect assumptions about regulatory pre-certification timelines and technology transition rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Printed and Flexible Sensors Market