
 Aeroderivative Sensor Market | 2026-2036
Aeroderivative Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Aeroderivative Sensor Market Analysis
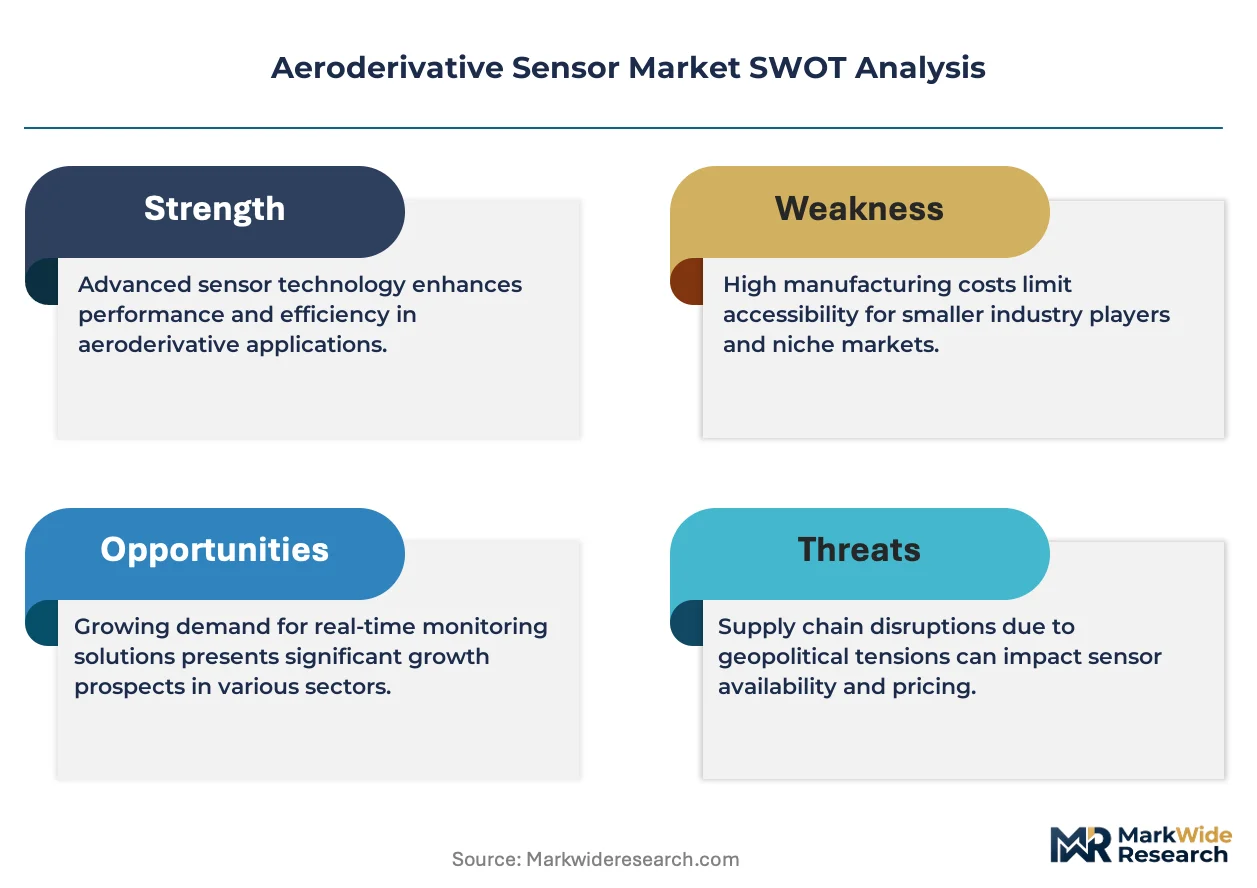
Utility fleet consolidation among independent power producers is repositioning procurement patterns toward integrated sensor-software packages. Bently Nevada (Baker Hughes) leverages its heritage in vibration monitoring to anchor long-term service contracts with consolidated turbine operators. Honeywell International Inc. competes through embedded sensing architectures that extend from combustion dynamics to exhaust gas analysis. General Electric Company dominates the OEM channel, controlling sensor specification for its LM-series aeroderivative turbines across installed fleets.
An aeroderivative sensor is a precision transducer designed to measure physical parameters in gas turbines derived from aviation jet engines, typically operating at temperatures exceeding 600°C and rotational speeds above 10,000 RPM. These instruments convert mechanical, thermal, or fluid dynamic signals into electrical outputs for real-time engine control and predictive maintenance systems. Temperature sensors and vibration sensors command the largest installed base, with vibration sensing generating disproportionate margin pools due to the complexity of spectral analysis and fault signature libraries. MEMS technology is displacing conventional piezoelectric designs in non-critical measurement points, while optical sensing gains traction in high-electromagnetic-interference environments near power generation equipment.
The FAA's airworthiness standards for derivative engine designs and the EPA's emissions compliance frameworks for stationary gas turbines jointly shape sensor accuracy requirements and calibration protocols. European operators face additional constraints from ECHA's REACH regulations on hazardous substances in sensor materials and the EU Green Deal's methane intensity benchmarks. Stakeholders must weigh the trade-off between retrofitting existing turbine instrumentation and specifying next-generation digital sensor platforms in new-build projects.
Market Dynamics
Utility fleet consolidation is compressing procurement cycles and forcing sensor vendors to bundle hardware with predictive analytics platforms. Independent power producers now demand unified sensor-software contracts rather than discrete component purchases.
Growth Catalysts
- EPA emissions frameworks:Stationary gas turbine operators in the United States face mandatory continuous emissions monitoring, driving replacement of analog instrumentation with digital sensor networks capable of real-time methane and NOx detection.
- Peaking power expansion:Grid operators across Texas, California, and the PJM interconnection are deploying aeroderivative turbines for rapid ramping, each unit requiring 40-60 vibration and temperature sensors for condition-based maintenance.
- MEMS miniaturization:Micro-electromechanical systems are penetrating non-critical measurement points previously served by piezoelectric designs, reducing unit costs and enabling denser sensor arrays on turbine casings.
Market Restraints
- Inconel and platinum supply concentration:High-temperature sensor sheathing relies on specialty alloys where Russian and South African refining capacity dominates, exposing manufacturers to input cost volatility and sanctions-related disruption.
- FAA airworthiness certification timelines:Derivative engine designs require sensor validation against aviation standards, extending product development cycles by 18-24 months for cross-platform applications.
- Optical sensing substitution:Fiber-optic temperature measurement is displacing thermocouples in electromagnetic interference zones near power generation equipment, threatening incumbent electrical sensor architectures.
Strategic Opportunities
- EU Green Deal methane intensity benchmarks:European operators must achieve 0.2% methane leakage rates by 2030, creating mandatory upgrade cycles for legacy turbine sensor infrastructure across Germany, Italy, and the Netherlands.
- Edge computing convergence:On-turbine sensor data processing is merging with 5G private networks, enabling millisecond-latency anomaly detection without cloud dependency for offshore platform applications.
- Independent power producer channel restructuring:Consolidated fleet operators are centralizing sensor procurement through integrated service agreements, favoring vendors with embedded software capabilities over component specialists.
Industry Challenges
- Thermocouple drift calibration:Type K and Type N thermocouples in combustion zones require 90-day recertification cycles, consuming field engineering capacity and complicating predictive maintenance model accuracy.
- Legacy SCADA integration:Digital sensor networks must interface with 1990s-era distributed control systems through protocol gateways, adding commissioning complexity and failure points at gas turbine installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aeroderivative Sensor Market |
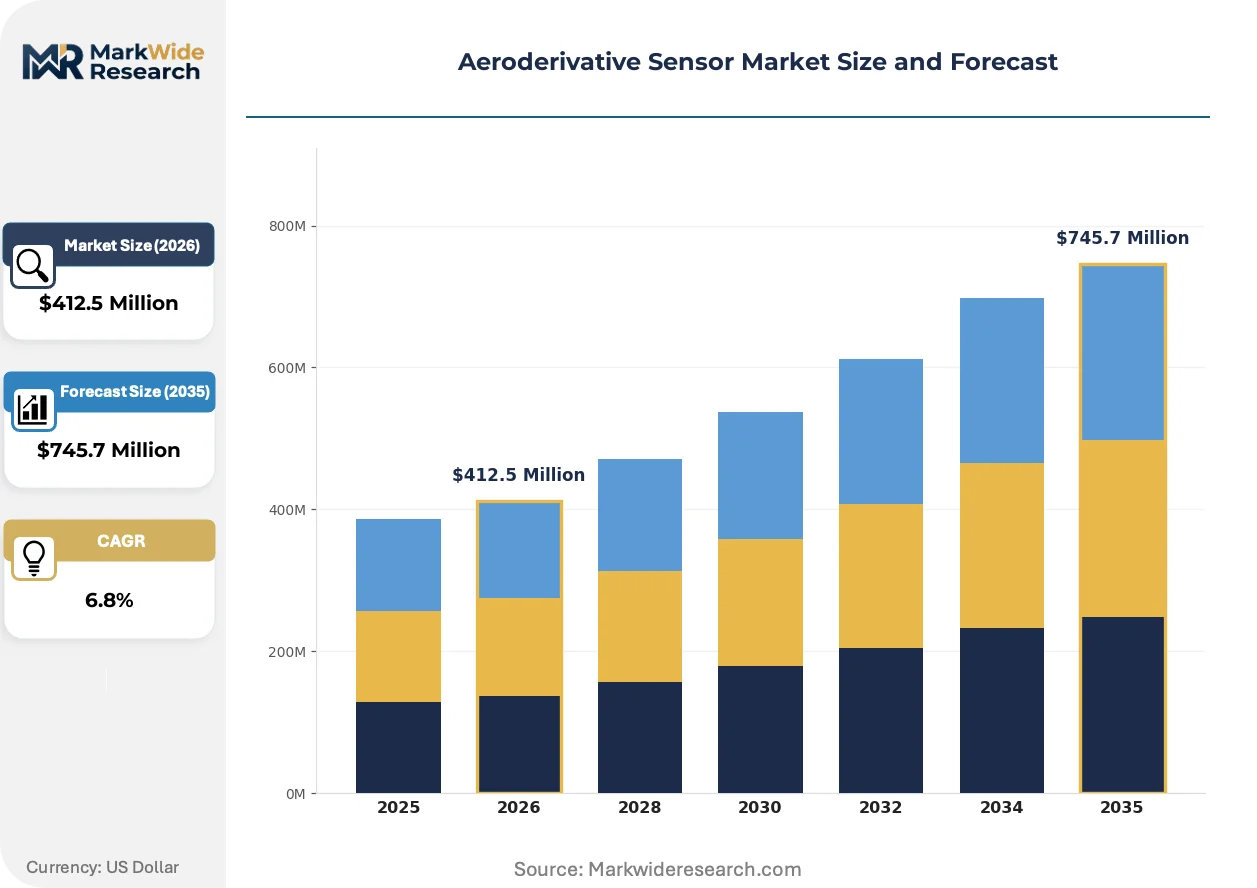
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Vibration Sensors, Flow Sensors Technology: MEMS, Optical, Magnetic, Capacitive End User: Aerospace, Defense, Automotive, Energy Deployment: On-premises, Cloud-based, Edge Computing, Hybrid |
| Companies Covered | Bently Nevada (Baker Hughes), PCB Piezotronics Inc., Meggitt PLC, Honeywell International Inc., Kistler Instrument Corp., General Electric Company, AMETEK Inc., Unison LLC, Sensirion AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aeroderivative Sensor Market Emerging Trajectories
Digital twin architectures are reshaping how sensor data transforms into maintenance decisions. Vendors are racing to embed edge intelligence directly on turbine casings.
Optical fiber Bragg grating sensing is integrating temperature and strain measurement into single cable runs for high-EMI environments near generator sets. Offshore platform operators in the Gulf of Mexico are deploying these systems at twice the rate of onshore installations. The technology is integrating vibration, thermal, and pressure signals into unified health monitoring dashboards, collapsing the vendor stack from three suppliers to one.
REACH regulations on hazardous substances are mandating lead-free solder and cadmium-free coatings in European sensor supply chains. Manufacturers serving EEA markets must requalify welding processes and coating chemistries by 2026. Aerospace-derived turbine sensors face dual compliance burdens, as FAA airworthiness standards and ECHA substance restrictions impose conflicting material specifications on transducer housings.
Power utilities are unbundling sensor hardware from long-term service agreements, reversing a decade of integrated procurement. Independent power producers now separate capital equipment purchasing from predictive analytics subscriptions, forcing Bently Nevada and Honeywell to price sensors as standalone products. This disaggregation is most visible among Texas-based peaking plant operators who rotate equipment vendors every five years.
Aeroderivative Sensor Market Segmentation
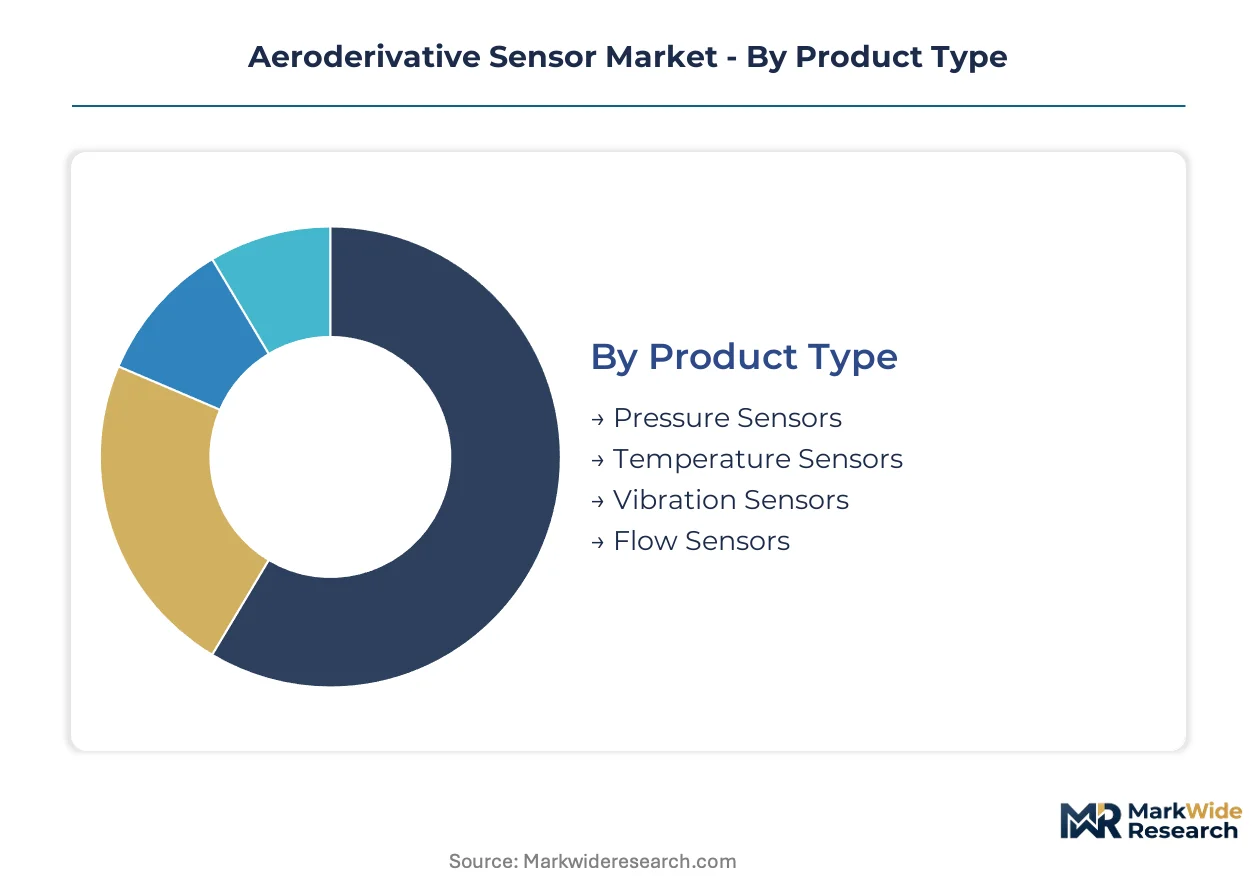
Aeroderivative sensor procurement patterns diverge sharply across measurement modalities and deployment architectures. Fleet operators calibrate instrumentation mixes to specific turbine duty cycles, from baseload combined-cycle plants to intermittent peaking units. Understanding these segment boundaries clarifies where upgrade investments concentrate versus where legacy systems persist.
Product Type:
Replacement cycles for legacy instrumentation are accelerating as EPA emissions monitoring mandates force digital sensor network upgrades across installed gas turbine fleets. Operators now evaluate sensor longevity against calibration burden when specifying instrumentation for combustion zones and rotating assemblies.
- Temperature Sensors:Type K and Type N thermocouples dominate combustion zone measurement, with sheathing alloys rated beyond 1000°C. Demand clusters in Texas and California peaking plants where thermal cycling degrades sensor accuracy within 90-day recertification windows. The FAA's airworthiness standards for derivative engine designs impose dual validation burdens on cross-platform temperature sensing architectures.
- Vibration Sensors:Piezoelectric accelerometers and emerging MEMS designs monitor rotor dynamics and bearing health through spectral signature analysis. Gulf Coast mechanical drive applications require 40-60 vibration sensing points per unit for condition-based maintenance contracts. Margin pools here exceed other modalities due to proprietary fault signature libraries and predictive analytics integration.
- Pressure Sensors:Capacitive and piezoresistive transducers measure compressor discharge and fuel manifold pressures.
- Flow Sensors:Thermal mass and Coriolis designs quantify fuel gas and cooling air distribution.
Volume placements concentrate in Temperature Sensors; the faster expansion belongs to Vibration Sensors.
Technology:
Cost tier differentiation separates established piezoelectric architectures from emerging solid-state and photonic alternatives. Procurement teams weigh unit economics against electromagnetic immunity and miniaturization potential when specifying sensing platforms for new-build versus retrofit applications.
- MEMS:Micro-electromechanical systems are displacing conventional piezoelectric designs in non-critical measurement points on turbine casings and auxiliary skids. Unit cost reductions of 60-70% versus legacy accelerometers enable denser sensor arrays for spatial vibration mapping. Texas independent power producers favor MEMS for rotating equipment on five-year replacement cycles.
- Optical:Fiber Bragg grating sensors integrate temperature and strain measurement into single cable runs immune to electromagnetic interference near generator sets. Gulf of Mexico offshore platforms deploy these at twice onshore rates. ECHA REACH regulations on hazardous substances accelerate optical adoption by eliminating lead-based solder compliance burdens.
- Magnetic:Variable reluctance and eddy-current proximity probes monitor shaft position and rotational speed.
- Capacitive:Differential capacitive designs serve static pressure measurement in compressor bleed air systems.
MEMS claims the largest installed base by unit count; optical architectures are gaining share fastest in high-EMI power generation environments.
End User:
Application-specific performance requirements dictate sensor specification, with aerospace-derived standards cascading into stationary power and defense procurement protocols. Each vertical imposes distinct calibration, traceability, and environmental qualification demands on transducer suppliers.
- Energy:Power utilities and gas turbine operators represent the dominant demand pool, driven by EPA continuous emissions monitoring mandates and condition-based maintenance programs. PJM interconnection peaking plants and Gulf Coast mechanical drive installations anchor procurement volumes. Fleet consolidation among independent power producers is repositioning buying patterns toward integrated sensor-software packages.
- Aerospace:Derivative engine OEMs specify sensors for LM-series turbines crossing over from aviation to stationary power applications. FAA airworthiness certification timelines extend product development cycles by 18-24 months for cross-platform instrumentation. Dual compliance with ECHA substance restrictions creates material specification conflicts for transducer housings.
- Defense:Military turbine applications require hardened sensors with extended shock and vibration qualification.
- Automotive:Turbocharger test stands and racing derivatives represent niche demand for high-temperature, high-RPM measurement.
Energy applications generate the highest absolute volumes; aerospace specifications command premium positioning through dual-use technology transfer.
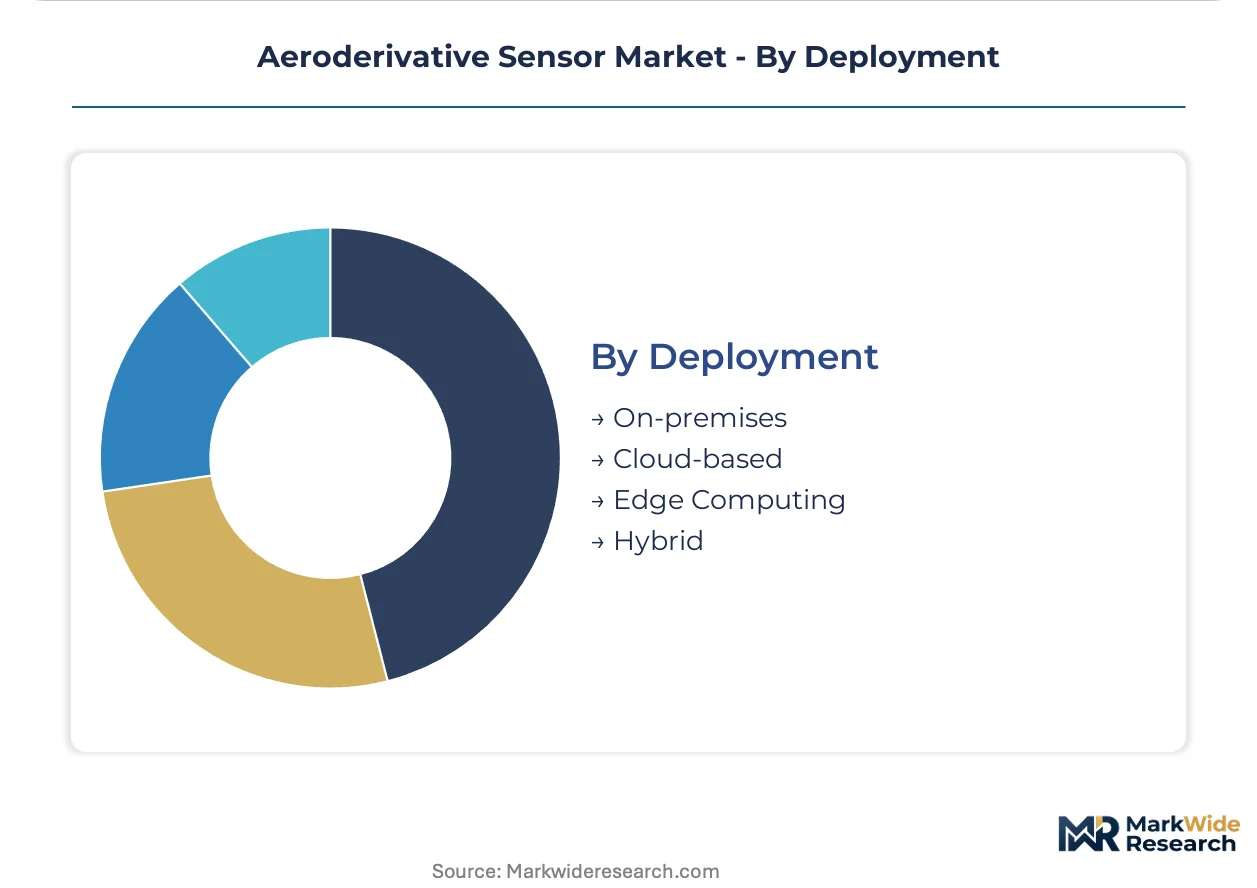
Deployment:
Customer type stratification separates capital-intensive on-premises architectures from subscription-oriented cloud and edge computing models. Procurement centralization among consolidated fleet operators favors vendors with embedded software capabilities over component specialists.
- Edge Computing:On-turbine sensor data processing merges with 5G private networks for millisecond-latency anomaly detection without cloud dependency. Offshore platform operators in the Gulf of Mexico prioritize edge architectures where satellite bandwidth constraints limit centralized processing. Real-time combustion dynamics monitoring and predictive fault detection drive specification.
- On-premises:Legacy SCADA integration requirements preserve demand for local data acquisition systems interfacing with 1990s-era distributed control systems. Protocol gateways add commissioning complexity at gas turbine installations across the United States. Thermocouple drift calibration burdens fall heaviest on on-premises deployments requiring 90-day recertification cycles.
- Cloud-based:Centralized fleet analytics platforms aggregate sensor data across multiple turbine installations for pattern recognition.
- Hybrid:Architectures partition critical control loops to edge processors while archiving historical data to cloud repositories.
On-premises architectures retain the largest installed base; edge computing deployments are climbing the fastest among new-build peaking power installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty alloy refining capacity in South Africa and Russia anchors high-temperature sensor sheathing supply chains, creating geographic dependencies that ripple through procurement strategies. Aeroderivative sensor demand concentrates where gas turbine fleets serve peaking power and mechanical drive applications.
United States
Texas and California peaking plants drive vibration and temperature sensor procurement for rapid-ramp aeroderivative units. EPA continuous emissions monitoring mandates force digital sensor network upgrades across Gulf Coast mechanical drive installations. PJM interconnection operators in the Mid-Atlantic anchor replacement cycles for legacy thermocouple infrastructure.
Germany
Combined-cycle baseload operators in the Rhine-Ruhr industrial corridor prioritize thermocouple accuracy for combustion zone monitoring. ECHA REACH regulations on hazardous substances mandate lead-free solder requalification by 2026, accelerating optical fiber adoption. Bavarian turbine service hubs concentrate calibration engineering capacity for Central European fleets.
United Kingdom
North Sea offshore platform operators deploy edge-computing sensor architectures where satellite bandwidth constraints limit cloud processing. EU Green Deal methane intensity benchmarks drive legacy instrumentation replacement across North England peaking facilities. Aberdeen energy service clusters anchor predictive maintenance software integration with hardware procurement.
China
Provincial grid operators in Jiangsu and Guangdong provinces expand aeroderivative deployments for load-following capacity. MIIT industrial standards for gas turbine instrumentation shape sensor accuracy specifications for domestic manufacturers. Yangtze River Delta manufacturing clusters concentrate MEMS sensor packaging capacity for cost-sensitive applications.
United Arab Emirates
Dubai and Abu Dhabi power authorities specify high-temperature sensors for aeroderivative units in district cooling and desalination complexes. The country's national oil company procurement frameworks favor integrated sensor-software service agreements over discrete hardware purchases. Jebel Ali industrial zones concentrate turbine maintenance contractor networks for Middle East fleet operators.
Aeroderivative Sensor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue optical sensing and edge-computing integration. The vendor base stratifies between OEM-captive sensor specifications and independent aftermarket suppliers. Three archetypes dominate: aerospace-derived turbine OEMs controlling design specifications, industrial instrumentation specialists with predictive analytics platforms, and MEMS-focused component suppliers penetrating non-critical measurement points. Competitive dynamics center on bundled service contract capture and calibration engineering capacity expansion.
Within the industrial instrumentation tier, Bently Nevada and Honeywell International Inc. exemplify vendors bundling hardware with predictive analytics platforms. General Electric Company anchors the OEM-captive specification channel for LM-series aeroderivative fleets. These three represent divergent strategic positions: integrated service contracts, embedded sensing architectures, and derivative engine design control.
| Leading Market Players |
|---|
| Bently Nevada (Baker Hughes) |
| PCB Piezotronics Inc. |
| Meggitt PLC |
| Honeywell International Inc. |
| Kistler Instrument Corp. |
| General Electric Company |
| AMETEK Inc. |
| Unison LLC |
| Sensirion AG |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up instrumentation specialists have consolidated calibration engineering capacity across Texas and California peaking plant corridors, tightening pricing discipline for high-temperature thermocouple replacements while forcing bundled sensor-software contracts on independent power producers seeking volume discounts.
Pricing Analysis
Volume placements concentrate in temperature sensors where unit economics favor transactional per-unit pricing for Type K and Type N thermocouples; margin pools accrue disproportionately to vibration sensing architectures due to proprietary spectral analysis software integration. Price differentiation separates FAA-certified aerospace-grade instrumentation from standard industrial tiers, with certification level and predictive analytics bundling as primary tiering mechanisms. Cost compression in MEMS-based non-critical measurement points is intensifying because Texas independent power producers rotate vendors on five-year replacement cycles. Peaking plant operators exhibit highest price sensitivity for standalone hardware purchases, while offshore platform operators in the Gulf of Mexico show lowest sensitivity due to satellite bandwidth constraints forcing premium edge-computing sensor specifications.
Supply Chain Analysis
Refurbishment flows for platinum-rhodium thermocouple sheathing anchor reverse-logistics networks in South Africa and Russia, where specialty alloy refining capacity dominates high-temperature sensor material supply. Inconel and platinum feedstock dependencies draw from Russian and South African refining corridors, creating input cost volatility exposure for temperature sensor manufacturers. Single-source vulnerability concentrates in aerospace-derived alloy specifications where FAA airworthiness standards constrain alternative material qualification. Distribution runs through turbine OEM captive channels for LM-series specifications and independent aftermarket suppliers for legacy fleet retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as sensor vendors pursue backward control over calibration engineering capacity to capture long-term service contract renewals from consolidated utility fleets.
For Market Incumbents: Anticipate optical fiber Bragg grating substitution threatening electrical sensor architectures in high-EMI generator environments by embedding edge intelligence directly on turbine casings and securing 5G private network partnerships with Gulf of Mexico offshore operators. In-house production of spectral analysis software libraries defends margin pools in vibration sensing against MEMS-focused component suppliers penetrating non-critical measurement points. For New Entrants and Emerging Players: Mid-Atlantic PJM interconnection peaking plants undergoing EPA-mandated digital sensor network upgrades represent the most penetrable buyer archetype, as legacy SCADA integration burdens deter incumbent bundling strategies. White-space targets include REACH-compliant optical sensing for German combined-cycle operators facing 2026 solder requalification deadlines, and standalone MEMS hardware for Texas independent power producers disaggregating sensor procurement from predictive analytics subscriptions. Channel entry through turbine maintenance contractor networks in Jebel Ali industrial zones bypasses OEM-captive specification control. For Investors and Strategic Acquirers: Distressed-cycle entries favor calibration engineering specialists with FAA dual-use certification capabilities in the United States, as utility fleet consolidation compresses field service capacity and stranded assets emerge from independent power producer bankruptcies. Long-term viability hinges on software-enabled recurring revenue attachment rates rather than transactional hardware margins. Monitor EPA enforcement patterns for continuous emissions monitoring mandates as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Integration | On-turbine sensor data processing with 5G private networks enables millisecond-latency anomaly detection for offshore platforms. |
| REACH Compliance Transition | Lead-free solder and cadmium-free coating requalification secures European market access ahead of 2026 regulatory deadlines. |
| Predictive Analytics Platform Development | Proprietary fault signature libraries for vibration sensing capture disproportionate margin pools from condition-based maintenance contracts. |
| Calibration Engineering Capacity Expansion | Field service density in Texas and California corridors supports 90-day thermocouple recertification cycles for peaking plant operators. |
| Optical Sensing Technology Licensing | Fiber Bragg grating architectures penetrate high-EMI environments near generator sets where electrical sensors face displacement. |
Methodological Framework
Independent corroboration across turbine operator maintenance directors, OEM procurement teams, and calibration engineering specialists underwrites the qualitative findings in this study. Primary interviews with independent power producer fleet managers, EPC contractors specifying instrumentation for new-build peaking plants, and aftermarket service heads at Gulf Coast mechanical drive installations combined with secondary validation from EPA continuous emissions monitoring enforcement records, FAA airworthiness directive filings, and ECHA REACH substance restriction updates. Bottom-up sensor placement quantification across LM-series installed fleets triangulates against top-down aeroderivative gas turbine production data.
Comparable-period anchoring to historical replacement cycles for legacy thermocouple infrastructure and MEMS penetration trajectories in non-critical measurement points structured the projection framework across the analysis window. Segmentation dimensions modeled include measurement modality, sensing technology architecture, end-user vertical, and deployment topology. CAGRs derived from installed fleet growth rates and regulatory-mandated upgrade cycles incorporate EPA emissions framework enforcement intensity and EU Green Deal methane intensity benchmark adoption curves as industry-specific forecast inputs.
Revisions become necessary when FAA certification timeline extensions for derivative engine designs, sanctions-related disruption to South African or Russian specialty alloy supply, or abrupt shifts in utility fleet consolidation patterns materialize. Forecasts reflect assumptions regarding regulatory enforcement continuity and aerospace-to-power technology transfer rates. Practitioners should monitor EPA regional enforcement variance and ECHA substance restriction amendment schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market