
 Inertial Sensors Market | 2026-2036
Inertial Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Inertial Sensors Market Foresight
AS9100 certification is reorganizing competitive tiers in aerospace-grade inertial sensing, favoring suppliers with traceable quality systems. Honeywell International Inc. leverages decades of ring laser gyroscope heritage to dominate defense navigation contracts. STMicroelectronics N.V. competes on MEMS volume, supplying consumer electronics with high-shipment accelerometers. Robert Bosch GmbH anchors automotive stability control with integrated sensor modules engineered for ASIL-D functional safety.
Inertial sensors detect acceleration, angular rate, and tilt using micromachined silicon structures, piezoelectric crystals, or fiber-optic coils, with bias stability specifications ranging from degrees per hour in navigation-grade units to degrees per second in consumer devices. These instruments enable dead-reckoning position fixes where GPS signals degrade or jam. Combo sensors now command premium positioning in robotics and drone autopilots by fusing accelerometer and gyroscope data in single packages. Optical technology retains margin concentration in offshore drilling and satellite attitude control where MEMS drift rates prove unacceptable.
FAA airworthiness directives and EU MDR requirements impose traceability mandates on inertial units deployed in commercial aviation and surgical navigation systems. REACH restrictions on lead-based solders and RoHS substance thresholds reshape MEMS packaging material selections across European supply chains. Stakeholders must weigh certification investment timelines against MEMS cost curves when allocating R&D across navigation-grade and consumer-grade product lines.
Market Dynamics
MEMS cost curves are compressing navigation-grade specifications downward while optical gyroscopes defend premium positioning in satellite and offshore applications where drift tolerance remains non-negotiable.
Growth Catalysts
- Autonomous vehicle mandates:Germany's KBA and Japan's MLIT are accelerating validation protocols for high-precision gyroscopes in Level 4 navigation stacks.
- REACH material compliance:RoHS substance thresholds are forcing MEMS packaging redesigns that incidentally improve thermal stability in consumer-grade units.
- Robotics corridor concentration:South Korea's Gyeonggi-do manufacturing belt is absorbing combo sensor volumes for collaborative robot joint feedback systems.
Market Restraints
- Optical component supply concentration:Fiber coil winding expertise clusters in a handful of Japanese and US defense contractors, creating single-source vulnerability for navigation-grade units.
- Platinum-group metal volatility:Piezoelectric crystal electrodes depend on palladium and ruthenium spot markets subject to South African supply disruptions.
- MEMS temperature drift:Silicon resonator bias instability above 85°C limits deployment in downhole drilling without costly thermal compensation.
Strategic Opportunities
- India's PLI scheme for electronics:Component manufacturing incentives are attracting MEMS foundry investments serving domestic automotive and smartphone assembly.
- EU AI Act compliance:High-risk autonomous system categories will mandate redundant inertial sensing for safety-critical decision loops in industrial drones.
- Silicon photonics convergence:Integrated optical gyroscopes on CMOS substrates promise navigation-grade performance at MEMS-scale unit economics within aerospace qualification timelines.
Industry Challenges
- AS9100 certification backlog:Aerospace-grade quality system audits face 14-18 month queues at accredited registrars, delaying new supplier market entry.
- Packaging engineer scarcity:Hermetic MEMS cavity sealing and vacuum maintenance expertise concentrates among retiring specialists in German and Austrian precision manufacturing regions.
- Legacy avionics integration:ARINC 429 and MIL-STD-1553 bus architectures in existing commercial fleets complicate retrofit of modern digital inertial reference units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inertial Sensors Market |
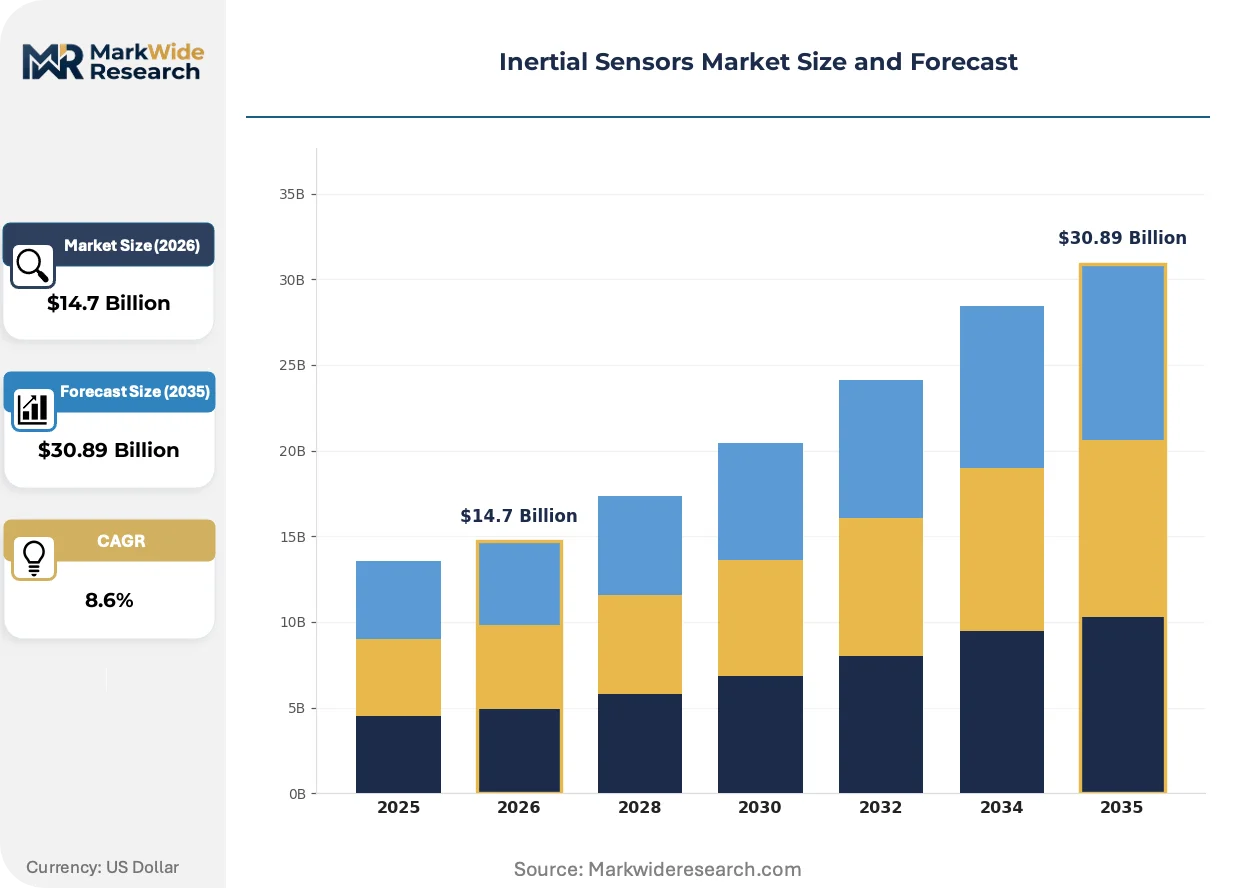
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometer, Gyroscope, Inclinometer, Combo Sensor End User: Aerospace, Consumer Electronics, Automotive, Robotics Application: Navigation, Motion Tracking, Stabilization, Industrial Automation Technology: MEMS, Optical, Fiber Optic, Ultrasonic |
| Companies Covered | Honeywell International Inc., Northrop Grumman Corporation, Robert Bosch GmbH, Analog Devices Inc., STMicroelectronics N.V., Safran Electronics & Defense, Thales Group, TDK Corporation, Silicon Sensing Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inertial Sensors Market Shifts & Advancements
Sensor fusion architectures are collapsing discrete component procurement into unified system sourcing, rewiring supplier-buyer relationships across robotics, automotive, and aerospace verticals.
Silicon MEMS gyroscopes with sub-degree-per-hour bias stability are decomposing the traditional navigation-grade price floor. Automotive Tier 1 suppliers in Stuttgart and Nagoya are qualifying these devices for highway autopilot redundancy. The technology is decomposing the historical segmentation between tactical-grade and navigation-grade product tiers.
EU MDR traceability mandates are extending Unique Device Identification requirements to surgical navigation systems employing inertial tracking. Manufacturers must now maintain device history records spanning crystal sourcing through final calibration. European orthopedic instrument suppliers are consolidating vendor lists to reduce compliance audit burden.
Chinese EV battery suppliers are demanding inertial-based cell formation monitoring to detect electrode swelling during charge cycles. Direct procurement from sensor manufacturers is displacing module integrators in Shenzhen and Ningbo supply chains. This pattern is most visible in cylindrical cell production lines where vibration signature analysis prevents thermal runaway.
Inertial Sensors Market Segmentation
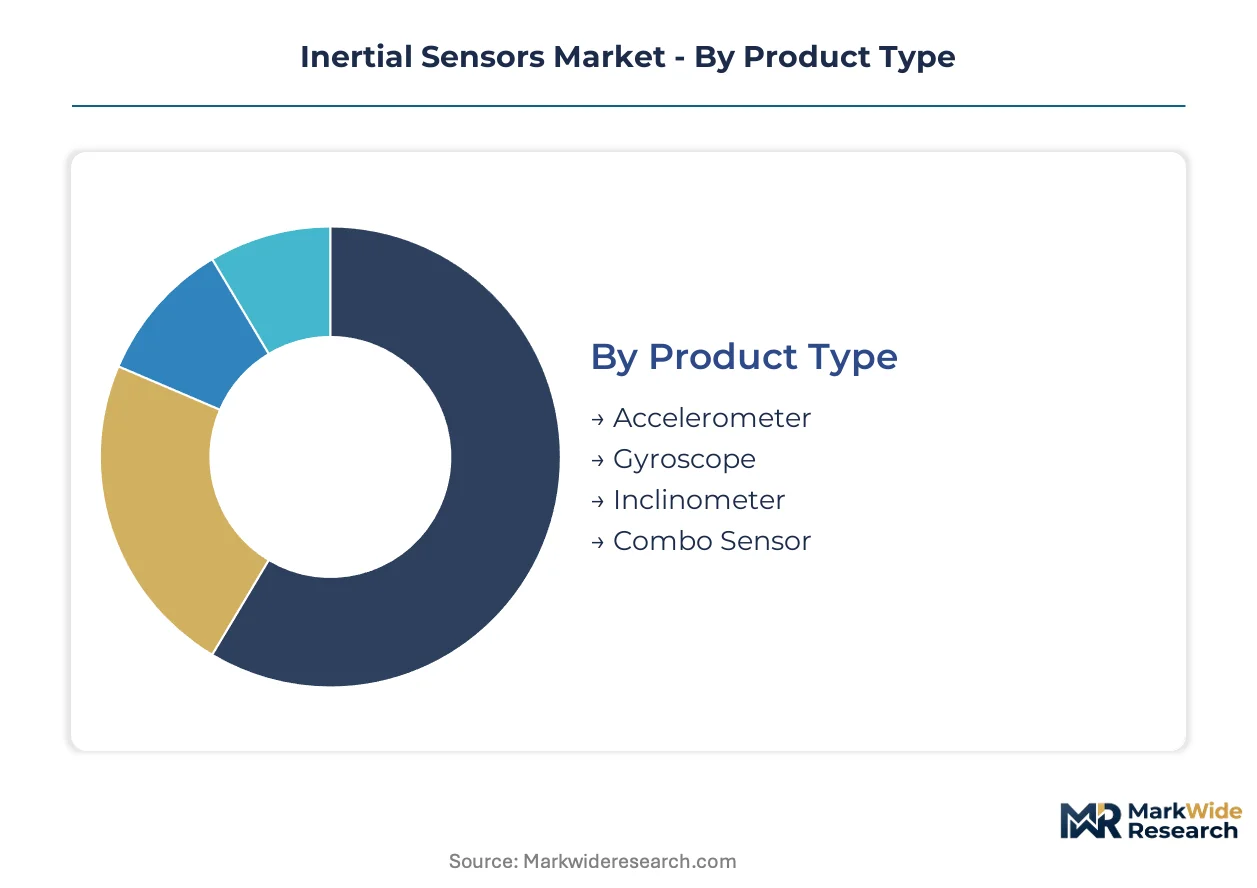
Inertial sensors serve divergent performance requirements across navigation-grade aerospace and consumer-grade mobile devices. Segmentation reveals how certification tiers, cost curves, and application criticality allocate procurement budgets across supplier ecosystems.
Product Type:
AS9100 certification separates aerospace-grade units from consumer-grade shipments, with traceability mandates extending to crystal sourcing and calibration records.
- Accelerometer:Silicon MEMS structures detect linear acceleration across 2g to 200g ranges. Consumer electronics procurement in South Korea's smartphone assembly corridors absorbs high-volume shipments, though temperature drift above 85°C limits downhole deployment without thermal compensation.
- Gyroscope:Ring laser and fiber-optic coils measure angular rate with bias stability from degrees per hour down to degrees per second. Germany's KBA and Japan's MLIT are accelerating validation protocols for Level 4 autonomous vehicle navigation stacks, concentrating demand among Stuttgart and Nagoya Tier 1 suppliers.
- Inclinometer:Tilt sensors employing electrolytic or MEMS technologies monitor structural alignment in construction and mining equipment.
- Combo Sensor:Fused accelerometer-gyroscope packages in single hermetic housings command premium positioning in robotics and drone autopilots.
Established volume favors accelerometers; emerging adoption favors combo sensors.
End User:
Customer procurement patterns range from million-unit consumer electronics contracts to hundred-unit aerospace programs with 18-month qualification timelines.
- Aerospace:Navigation-grade inertial reference units for commercial aviation and satellite attitude control require ARINC 429 and MIL-STD-1553 bus compatibility. FAA airworthiness directives impose traceability mandates that extend device history records through final calibration.
- Automotive:Integrated sensor modules engineered for ASIL-D functional safety anchor electronic stability control and highway autopilot redundancy systems.
- Consumer Electronics:MEMS accelerometers in smartphones and wearables compete on unit economics, with process refinements cutting die costs across foundry networks.
- Robotics:Collaborative robot joint feedback systems in South Korea's Gyeonggi-do manufacturing belt absorb combo sensor volumes for precision motion control.
Automotive represents the steepest expansion trajectory; aerospace commands the highest unit margins.
Application:
Functional requirements determine whether optical precision or MEMS cost efficiency dominates procurement specifications.
- Navigation:Dead-reckoning position fixes where GPS signals degrade or jam demand bias stability measured in degrees per hour. Offshore drilling and satellite operations retain optical technology where MEMS drift rates prove unacceptable.
- Motion Tracking:Gesture recognition and fitness monitoring in consumer devices prioritize power consumption and package size over absolute accuracy.
- Stabilization:Camera gimbals and platform leveling systems fuse gyroscope and accelerometer outputs for real-time compensation.
- Industrial Automation:Vibration signature analysis in Chinese EV battery cell formation monitoring detects electrode swelling during charge cycles.
Navigation commands premium pricing; industrial automation is gaining share fastest.
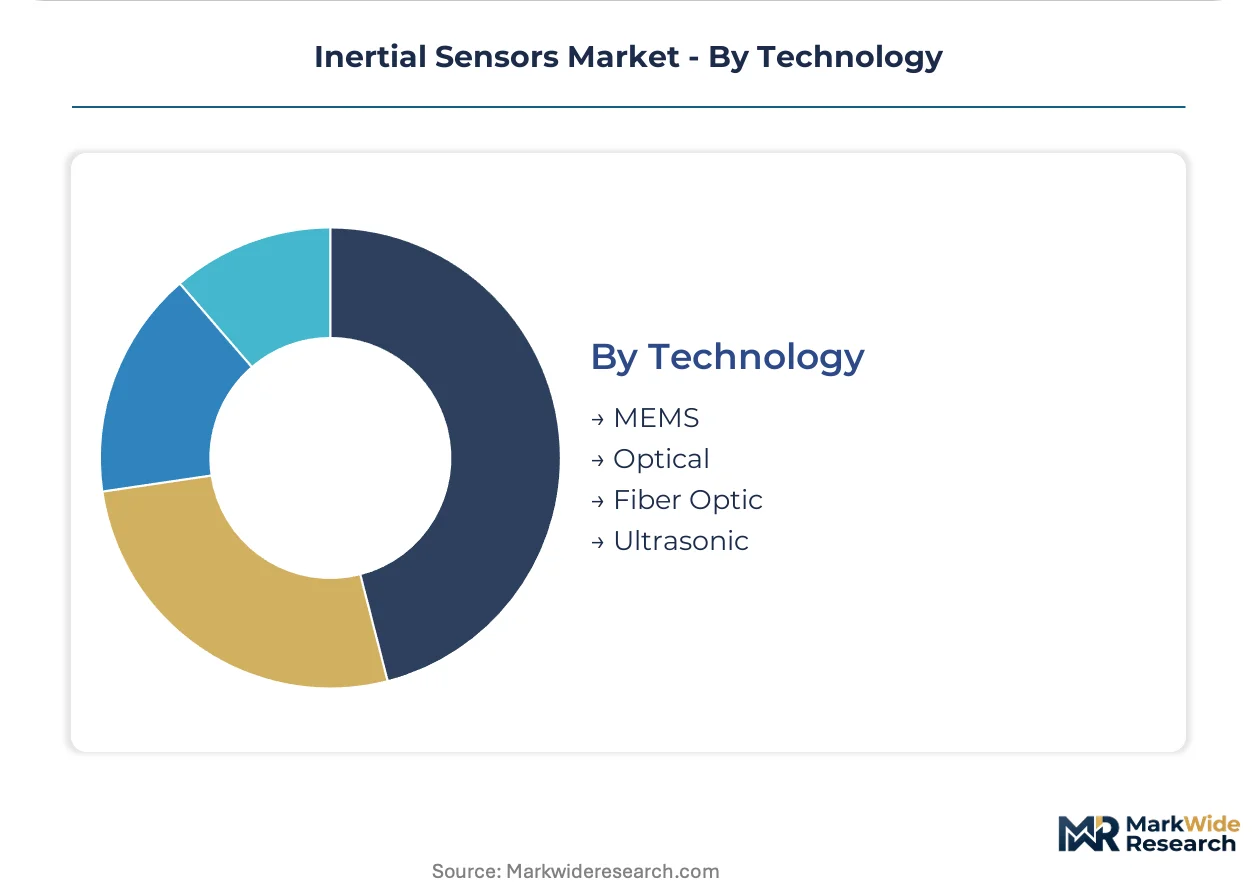
Technology:
Process maturity and material constraints create divergent cost-performance frontiers across fabrication approaches.
- MEMS:Micromachined silicon resonators and capacitive structures dominate consumer and automotive volume. REACH restrictions on lead-based solders and RoHS substance thresholds are forcing packaging redesigns that incidentally improve thermal stability.
- Optical:Ring laser gyroscopes defend margin concentration in defense navigation contracts where drift tolerance remains non-negotiable.
- Fiber Optic:Fiber coil winding expertise clusters in Japanese and US defense contractors, creating single-source vulnerability for navigation-grade units.
- Ultrasonic:Piezoelectric crystal electrodes depend on palladium and ruthenium spot markets subject to South African supply disruptions.
MEMS holds cost advantage; silicon photonics convergence promises navigation-grade performance at MEMS-scale economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and automotive Tier 1 suppliers concentrate procurement across Germany, Japan, China, South Korea, and the United States. Each market exhibits distinct certification requirements and cluster-based demand patterns.
Germany
KBA validation protocols for Level 4 autonomous navigation are accelerating gyroscope procurement from Stuttgart-based Tier 1 suppliers. REACH and RoHS substance mandates are forcing MEMS packaging redesigns that improve thermal stability. The Baden-Württemberg automotive corridor anchors European demand for ASIL-D certified sensor modules.
Japan
MLIT highway autopilot mandates are concentrating ring laser gyroscope orders among Nagoya precision manufacturers. METI industrial automation subsidies are absorbing combo sensor volumes for collaborative robotics. Fiber coil winding expertise clusters in defense contractors around Tokyo and Osaka, creating single-source vulnerability for navigation-grade units.
China
MIIT dual carbon goals are driving inertial-based battery cell formation monitoring in Shenzhen and Ningbo cylindrical cell lines. SAMR quality system requirements are reshaping supplier qualification timelines for domestic EV supply chains. The Yangtze River Delta electronics corridor is absorbing direct procurement from sensor manufacturers, displacing module integrators.
South Korea
MFDS medical device traceability mandates are extending to surgical navigation systems employing inertial tracking. The Gyeonggi-do robotics manufacturing belt is absorbing combo sensor volumes for collaborative robot joint feedback systems. Seoul-based smartphone assemblers dominate consumer-grade accelerometer procurement.
United States
FAA airworthiness directives impose traceability mandates on commercial aviation inertial reference units. NHTSA autonomous vehicle guidance is accelerating highway autopilot redundancy qualification. Defense navigation contracts concentrate in contractors with MIL-STD-1553 bus heritage and decades of ring laser gyroscope production.
Inertial Sensors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with aerospace heritage and specialized MEMS foundries serving consumer volume. Market structure exhibits tiered consolidation: three to four defense-aerospace primes dominate navigation-grade procurement, while fragmented MEMS suppliers compete on die cost across automotive and consumer electronics. Strategic archetypes include ring laser gyroscope heritage houses, high-volume MEMS foundries, and integrated automotive Tier 1 module suppliers. Dominant competitive moves center on AS9100 certification acquisition for aerospace market entry and silicon photonics R&D partnerships bridging optical performance with MEMS economics.
Within the defense-aerospace prime tier, Honeywell International Inc. and Northrop Grumman Corporation exemplify heritage positioning built on decades of navigation-grade gyroscope production. STMicroelectronics N.V. occupies a position among high-volume MEMS suppliers competing on unit economics for consumer and automotive shipments. Robert Bosch GmbH anchors the integrated automotive module supplier archetype, engineering sensor packages for functional safety certification.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| Robert Bosch GmbH |
| Analog Devices Inc. |
| STMicroelectronics N.V. |
| Safran Electronics & Defense |
| Thales Group |
| TDK Corporation |
| Silicon Sensing Systems Ltd. |
| Others |
Supply & Pricing Matrix
Die-level economies in MEMS foundries concentrate volume leverage among TSMC and GlobalFoundries customers, compressing unit costs for consumer-grade accelerometers while optical gyroscope suppliers defend margin floors through fiber coil winding expertise concentrated in Japanese and US defense contractors.
Pricing Analysis
Cost-plus contracts with palladium and ruthenium indexation dominate piezoelectric crystal procurement, exposing electrode costs to South African spot market volatility. Three-tier pricing structure across navigation-grade, tactical-grade, and consumer-grade levels separates AS9100-certified aerospace units from automotive ASIL-D modules and smartphone MEMS die. Cost compression in consumer accelerometers is intensifying because foundry process refinements expand 200mm wafer output. Smartphone OEMs in South Korea exhibit highest price sensitivity; satellite attitude control programs show least.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane extend lead times for hermetic packaging materials sourced from German precision manufacturing regions. Fiber coil winding draws from Japanese defense contractors and US primes; MEMS die fabrication centers on Taiwan and South Korea; final module assembly clusters in China's Yangtze River Delta. Single-source vulnerability in navigation-grade fiber optic gyroscopes creates supply chain risk. Distribution runs through automotive Tier 1 suppliers and direct procurement from robotics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration and recertification services are expanding faster than hardware shipments as FAA airworthiness directives and EU MDR traceability mandates extend device history record requirements across commercial aviation and surgical navigation systems.
For Market Incumbents: Secure AS9100 certification capacity before audit queues lengthen further, locking out emerging competitors from aerospace navigation contracts. Defend fiber optic gyroscope margins by acquiring captive fiber coil winding capacity in Japan, reducing single-source exposure that threatens delivery reliability. Expand calibration service attach rates to capture recurring revenue from installed navigation-grade bases.
For New Entrants and Emerging Players: Lead with silicon photonics convergence R&D targeting navigation-grade performance at MEMS-scale unit economics, exploiting the technology gap between optical precision and silicon cost curves. Target India's PLI scheme for MEMS foundry investment serving domestic automotive and smartphone assembly demand. Pursue direct procurement relationships with Chinese EV battery manufacturers bypassing module integrators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors MEMS foundries with automotive qualification heritage and silicon photonics R&D partnerships bridging optical performance with semiconductor economics. Long-term viability hinges on backward integration into hermetic packaging expertise as German and Austrian specialist retirements accelerate. Watch silicon photonics navigation-grade qualification timelines as inflection indicator for optical gyroscope displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Investment | Unlocks aerospace navigation contracts requiring traceable quality systems and device history records. |
| Silicon Photonics R&D Partnership | Bridges navigation-grade performance with MEMS-scale unit economics through CMOS substrate integration. |
| India PLI Scheme Foundry Investment | Captures domestic automotive and smartphone MEMS demand under component manufacturing incentives. |
| Hermetic Packaging Specialist Acquisition | Secures scarce German and Austrian vacuum maintenance expertise before specialist retirements. |
| Calibration Service Platform Buildout | Generates recurring revenue from FAA and EU MDR-mandated device recertification requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research, including MEMS foundry engineering directors, automotive Tier 1 procurement managers, aerospace navigation system integrators, and robotics OEM supply chain leads. Secondary validation drew from FAA airworthiness directive filings, ECHA REACH substance restriction updates, MIIT dual carbon policy documents, and customs trade data for palladium and ruthenium electrode materials. Bottom-up die shipment estimates and top-down navigation system procurement values were triangulated to anchor volume and value outputs.
Across the analysis window, forecasts model product type segmentation by performance grade, end user verticals spanning aerospace through consumer electronics, application functional requirements, and technology fabrication approach. CAGRs were derived from segment-level shipment trajectories weighted by unit value and certification tier mix. Forecast inputs include KBA and MLIT autonomous vehicle validation protocol timelines, EU MDR traceability mandate implementation phases, and silicon photonics navigation-grade qualification progress.
Forecasts assume regulatory continuity in FAA airworthiness directives, EU MDR and REACH substance regimes, and India's PLI scheme incentive structures; material policy shifts would require re-modeling. Specific risks that could revise projections include AS9100 certification backlog extensions, platinum-group metal supply disruptions from South Africa, and MEMS temperature drift limitations in downhole drilling applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Global Biosensors Market