
 Flow Sensor Market | 2026-2036
Flow Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Sensor Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is broadening the compliance scope for industrial water and energy usage reporting. This regulation expands the addressable market for high-precision flow measurement technologies beyond traditional process industries. Emerson Electric Co. leverages its extensive process automation portfolio to serve large-scale infrastructure projects. In contrast, Honeywell International Inc. differentiates through integrated sensor and control systems tailored for complex industrial environments.
A flow sensor is an instrument engineered to quantify the volume or mass of a gas or fluid moving through a defined passage. These devices function by detecting physical properties such as pressure differentials, thermal dispersion, or ultrasonic wave transit times. The primary industrial purpose is to provide critical data for automated process control, leak detection, and resource consumption monitoring. Ultrasonic sensors represent the fastest-growing product type due to non-invasive installation, while the water treatment end-user segment drives substantial volume.
Regulatory mandates from bodies like the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) enforce strict standards for industrial effluent and water quality. These frameworks make certified, high-accuracy flow sensors a prerequisite for operational permits in sectors from chemical processing to food and beverage. In parallel, Japan's initiatives under METI promote energy efficiency, requiring precise flow monitoring in HVAC and industrial systems. Future competitive advantage will depend on integrating smart sensor capabilities with evolving digital reporting platforms.
Market Dynamics
The flow sensor market is shaped by the non-discretionary global mandate for resource efficiency and environmental monitoring. Regulatory frameworks from the EU to China are transforming flow measurement from a process optimization tool into a prerequisite for compliance, compelling investment in higher-precision technologies across industries.
Growth Catalysts
- Regulatory Reporting Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) compels a wider range of companies to report on water and energy consumption, directly stimulating demand for auditable, high-accuracy flow measurement systems.
- Ultrasonic Sensor Technology:Non-invasive clamp-on ultrasonic sensors reduce installation downtime and are compatible with corrosive or high-purity fluids, spurring adoption in the chemical processing and pharmaceutical sectors where process interruption is costly.
- Water Infrastructure Modernization:Government initiatives in countries like India to upgrade municipal water and wastewater treatment plants to meet stricter environmental standards are driving large-scale procurement of durable flow sensors for network monitoring and management.
Market Restraints
- High Capital Outlay:The initial investment for high-precision, certified flow sensors, such as Coriolis or magnetic types, presents a significant cost barrier for small and medium-sized enterprises in sectors like food processing or textiles.
- Measurement of Complex Fluids:Standard flow sensors face technical limitations and accuracy degradation when measuring multiphase flows, high-viscosity slurries, or non-conductive hydrocarbons, requiring more specialized and expensive solutions.
- Component Supply Chain Risks:The production of advanced sensors relies on a concentrated supply chain for specific microcontrollers and high-performance analog-to-digital converters, primarily centered in East Asia, creating vulnerability to geopolitical and logistical disruptions.
Strategic Opportunities
- Smart City Integration:The development of smart city projects creates new applications for networked flow sensors in district energy systems, intelligent water grids for leak detection, and automated environmental monitoring networks.
- Sensor Fusion with AI:Combining flow sensor data with temperature, pressure, and vibration analytics on a single IoT platform enables predictive maintenance alerts for industrial equipment, creating value beyond simple volume measurement.
- Industrial Automation in Southeast Asia:Rapid industrialization in Vietnam, Indonesia, and Thailand presents an underpenetrated market for process automation solutions, including flow sensors for improving efficiency in manufacturing, electronics, and food production.
Industry Challenges
- Legacy System Integration:Integrating modern digital flow sensors with older, analog-based Distributed Control Systems (DCS) or SCADA infrastructure in established industrial plants is a complex and costly challenge for many operators.
- Skilled Technician Scarcity:A shortage of technicians with the dual expertise in traditional instrumentation and modern IT networking complicates the installation, calibration, and maintenance of smart, IoT-enabled flow sensor systems.
- Interoperability Standards:A lack of universal communication protocols between sensor devices from different manufacturers can lead to vendor lock-in and hinder the development of cohesive, plant-wide monitoring and control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Sensor Market |
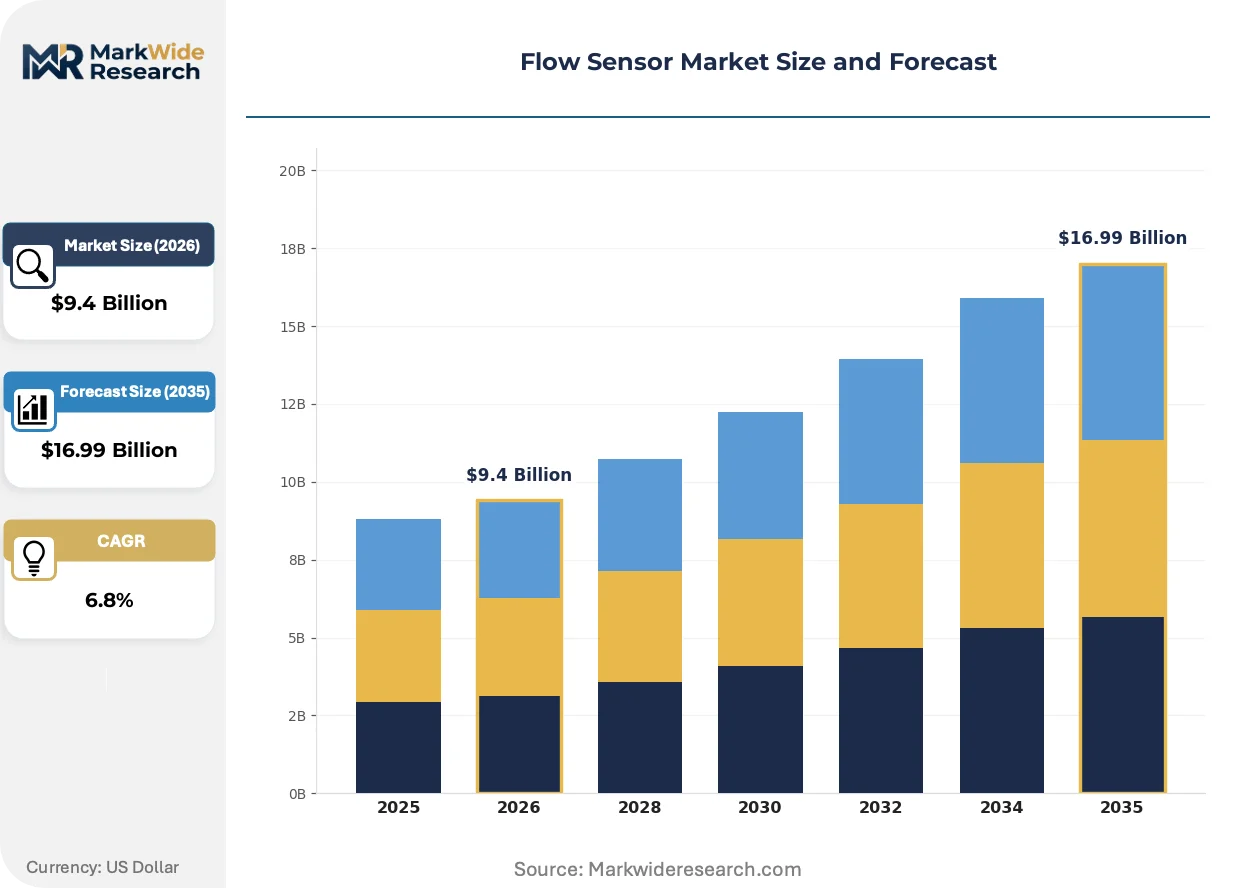
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ultrasonic, Thermal, Vortex Technology: Analog, Digital, Wireless, Smart End User: Oil & Gas, Water Treatment, Food & Beverage, HVAC Application: Process Control, Flow Measurement, Leak Detection, Water Quality |
| Companies Covered | ABB Ltd, Honeywell International Inc., Emerson Electric Co., Badger Meter Inc., KROHNE Messtechnik GmbH, Endress+Hauser Group, Yokogawa Electric Corporation, Christian Bürkert GmbH and Co. KG, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from discrete component sales to integrated data solutions. This shift prioritizes intelligent sensors that can provide actionable insights for process control and resource management, rather than just raw measurement data.
Micro-Electro-Mechanical Systems (MEMS) technology enables the production of highly compact, low-power thermal mass flow sensors. Medical device manufacturers are adopting these for precise gas control in ventilators and anesthesia machines, while the semiconductor industry uses them for process gas monitoring. This miniaturized sensor platform is converging with edge computing, allowing for on-device data processing and analytics which reduces system latency and data transmission costs.
In the United States, the EPA enforces strict monitoring requirements for industrial effluent and air emissions under the Clean Water Act and Clean Air Act. This regulation establishes a mandatory market for certified, tamper-proof flow meters in sectors such as power generation, refining, and chemical manufacturing. The food and beverage segment is particularly affected by new Food Safety Modernization Act (FSMA) rules, which are accelerating the replacement of older meters with new hygienic-design sensors.
A notable behavioral change is the move away from one-time transactional hardware purchases toward performance-based service contracts. Under this model, industrial buyers procure flow measurement as a managed service, which includes the sensor, installation, ongoing calibration, and data analysis for a recurring fee. This disrupts traditional component distributors and favors vendors with strong service infrastructures. This trend is most visible in Europe's municipal water sector, where utilities use it to tackle non-revenue water challenges.
Flow Sensor Market Segmentation
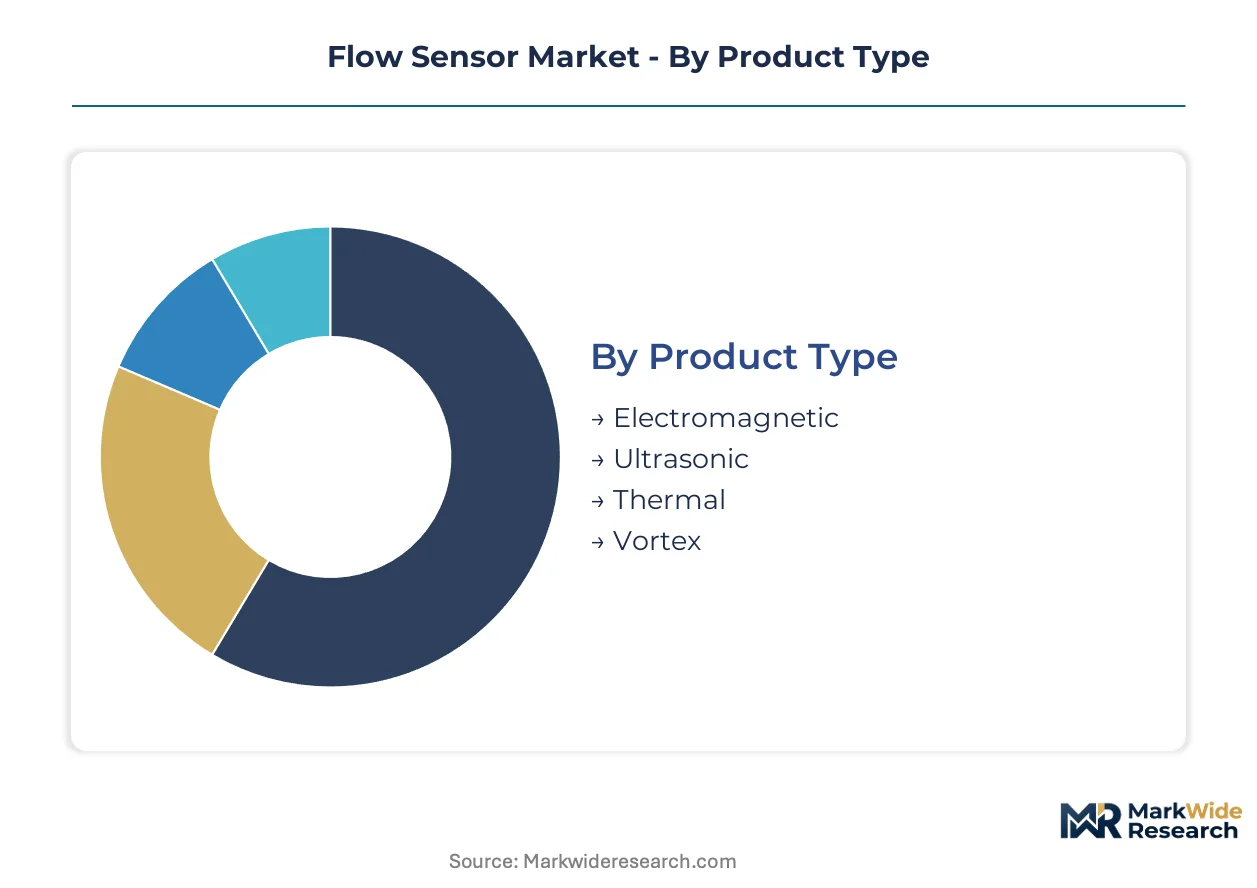
The flow sensor market's segmentation reveals diverse technological approaches and end-user requirements. Understanding these distinctions is crucial for manufacturers to align product development with specific industry needs. This granular view helps stakeholders identify precise demand pockets and tailor solutions for optimal resource management and regulatory compliance.
Product Type:
Buyers frequently select flow sensor product types based on fluid characteristics, required accuracy, and installation constraints.
- Ultrasonic:These sensors measure flow using sound waves, offering non-invasive installation and suitability for corrosive or high-purity fluids. Demand concentrates in chemical processing and pharmaceutical sectors due to reduced downtime and process integrity requirements.
- Electromagnetic:Operating on Faraday's law of induction, these sensors are ideal for conductive liquids, providing high accuracy with minimal pressure drop. Water treatment plants and municipal infrastructure projects rely on electromagnetic sensors for precise billing and network management.
- Thermal:Thermal mass flow sensors quantify flow by measuring heat transfer from a heated element, commonly used for gas applications such as process gas monitoring.
- Vortex:These sensors detect flow by measuring pressure fluctuations caused by vortices shed from an obstruction, suitable for steam and gas in various industrial settings.
Electromagnetic sensors lead on scale for conductive fluids; ultrasonic sensors lead on momentum for non-invasive applications.
Technology:
Technology segmentation reflects the evolving maturity of data acquisition and integration capabilities within industrial environments.
- Smart:Smart sensors integrate microprocessors for on-device data processing, analytics, and communication capabilities, enabling predictive maintenance and remote monitoring. Industrial automation in Germany and the United States drives adoption for optimizing complex manufacturing processes.
- Digital:Digital sensors convert analog signals into digital outputs, providing enhanced accuracy, noise immunity, and direct compatibility with modern control systems. The rapid industrialization across Southeast Asia fuels demand for digital flow measurement in new manufacturing facilities.
- Analog:Analog flow sensors produce continuous electrical signals proportional to flow rate, serving as foundational components in older control systems and basic instrumentation.
- Wireless:These sensors transmit data via radio frequencies, reducing cabling costs and enabling deployment in remote or hazardous locations without extensive wiring.
Advanced technologies like Smart sensors are driving innovation, while foundational technologies like Digital remain critical for widespread adoption.
End User:
End-user segments are differentiated by the specific operational challenges and the sheer volume of fluid monitoring required.
- Water Treatment:This segment includes municipal water supply, wastewater management, and industrial effluent treatment, requiring durable and accurate sensors for resource monitoring and regulatory compliance. Government initiatives in India to upgrade water infrastructure are driving substantial sensor procurement.
- Oil & Gas:The sector demands robust, high-pressure flow sensors for upstream production, midstream transportation, and downstream refining processes. Strict safety regulations and the need for accurate hydrocarbon accounting concentrate demand in North American and Middle Eastern facilities.
- Food & Beverage:This industry requires hygienic-design sensors for process control, ingredient measurement, and cleaning-in-place (CIP) verification under stringent safety standards.
- HVAC:Heating, Ventilation, and Air Conditioning systems utilize flow sensors for optimizing energy consumption and ensuring precise climate control in commercial buildings and industrial facilities.
The Water Treatment sector represents a significant volume driver, while Oil & Gas demands highly specialized sensor solutions.
Application:
The application of flow sensors varies significantly depending on the operational criticality and the specific data insights industrial customers seek.
- Process Control:This application involves maintaining specific flow rates, volumes, or pressures within industrial manufacturing processes to ensure product quality and operational efficiency. Chemical processing plants and semiconductor fabrication facilities heavily rely on these sensors for critical process stability.
- Leak Detection:Flow sensors identify abnormal fluid losses in pipelines and distribution networks, crucial for resource conservation and preventing environmental damage. Smart city initiatives in Europe are integrating these sensors into intelligent water grids for proactive infrastructure management.
- Flow Measurement:This fundamental application quantifies the volume or mass of fluid passing a point, essential for inventory management, billing, and general operational oversight.
- Water Quality:Flow sensors are often integrated with other sensors to monitor parameters like pH, conductivity, and dissolved oxygen, ensuring compliance with environmental standards and process integrity.
Applications such as Process Control are fundamental to industrial operations, while Leak Detection is expanding most quickly due to environmental mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled engineering workforce anchors demand for sophisticated flow sensor technologies across several developed and developing economies. These regions prioritize advanced manufacturing, environmental compliance, and infrastructure modernization, creating sustained procurement needs for precise measurement solutions. Regulatory frameworks and industrial clusters significantly influence the adoption rates and technological preferences within these markets.
United States
Demand for flow sensors in the United States stems from strict environmental regulations governing industrial effluent and air emissions. The US Environmental Protection Agency (EPA) enforces the Clean Water Act and Clean Air Act, mandating certified monitoring equipment. Industries along the Gulf Coast, particularly refining and chemical manufacturing, rely on high-accuracy sensors for operational permits and compliance reporting.
Germany
Germany's robust industrial base and focus on resource efficiency drive significant demand for smart flow sensors in manufacturing process optimization. The EU Green Deal and Corporate Sustainability Reporting Directive (CSRD) compel companies to report on water and energy usage. Bavaria, a hub for automotive and machinery production, concentrates advanced sensor adoption for precision control systems.
China
China's rapid industrial expansion and environmental protection goals fuel the market for flow sensors, especially for industrial effluent control. The Ministry of Ecology and Environment (MEE) sets stringent standards for wastewater discharge and air quality. The Yangtze River Delta region, with its electronics and chemical processing industries, is a key area for high-volume sensor deployment.
India
India's ambitious water infrastructure modernization projects are a primary catalyst for flow sensor procurement. Government initiatives to upgrade municipal water and wastewater treatment plants necessitate durable and accurate sensors for network management. Maharashtra, home to significant industrial zones and urban centers, represents a substantial market for large-scale water management solutions.
Japan
Japan's emphasis on energy efficiency and precision manufacturing supports the demand for flow sensors in HVAC and industrial systems. The Ministry of Economy, Trade and Industry (METI) promotes technologies that reduce energy consumption across various sectors. The Kanto region, encompassing Tokyo, sees widespread integration of flow sensors in smart building management and precision manufacturing facilities.
Flow Sensor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the flow sensor market, creating a tiered competitive structure. This landscape includes large industrial technology providers offering comprehensive automation portfolios and niche manufacturers specializing in specific sensor types or applications. Strategic partnerships for integrated solutions and continuous portfolio diversification are dominant competitive moves.
Within the diversified industrial technology archetype, Honeywell International Inc. and Emerson Electric Co. represent established players leveraging extensive process automation and control system expertise. These US-based corporations offer broad product ranges suitable for large-scale infrastructure projects and complex industrial environments. Germany-based KROHNE Messtechnik GmbH exemplifies a specialized manufacturer with a strong focus on advanced measurement technologies for challenging applications, particularly in water and wastewater treatment.
| Leading Market Players |
|---|
| ABB Ltd |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Badger Meter Inc. |
| KROHNE Messtechnik GmbH |
| Endress+Hauser Group |
| Yokogawa Electric Corporation |
| Christian Bürkert GmbH and Co. KG |
| Siemens AG |
Cost & Logistics Intelligence
Government procurement for municipal water infrastructure projects often dictates project-based pricing structures for flow sensors. These large-scale tenders prioritize long-term service contracts, influencing vendor selection and profitability.
Pricing Analysis
Bundled service contracts, encompassing sensor hardware, installation, and data analytics, are displacing traditional per-unit transactional sales. Price differentiation stems from certification levels for regulatory compliance and the degree of customization for complex industrial processes. Pricing pressure stems from the commoditization of basic analog sensors. Small and medium-sized enterprises exhibit the highest price sensitivity, while large industrial conglomerates prioritize performance and reliability over upfront cost.
Supply Chain Analysis
Domestic content mandates in countries like India, for water infrastructure projects, are reshaping flow sensor sourcing strategies. Production concentrates in East Asia, particularly China and South Korea, for microcontrollers and high-performance analog-to-digital converters. A structural risk involves geopolitical disruptions affecting these concentrated component supply chains. Distribution runs primarily through specialized industrial distributors and direct sales channels to large end-users like municipal utilities and chemical plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flow sensor market offers geographic-arbitrage opportunities, particularly in leveraging lower manufacturing costs in East Asia for component production while serving high-margin regulatory-driven demand in Europe and the United States. This dynamic influences investment and operational footprints.
For Market Incumbents: Lock in existing large-scale infrastructure projects with long-term service contracts to counter competitive pressure from new entrants. Invest in advanced R&D for smart sensor capabilities, integrating AI for predictive maintenance, to stay ahead of basic sensor commoditization. Deepen vertical integration into critical component manufacturing to mitigate supply chain risks. Secure certifications like CE marking and EPA compliance to reinforce market access.
For New Entrants and Emerging Players: Enter via specialized applications requiring non-invasive ultrasonic sensors, targeting the pharmaceutical and food and beverage sectors where hygiene and process integrity are paramount. The most penetrable segment is smart city initiatives in Europe, focusing on intelligent water grids for leak detection. A strong go-to-market angle involves offering performance-based service contracts that reduce upfront capital outlay for municipal utilities.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirers in this space, seeking to expand their digital portfolio and enhance integrated solutions over the next five to ten years. Acquisition targets should be pure-play specialists in smart sensor technology with strong intellectual property in AI-driven analytics. The signal to watch is the widespread adoption of interoperability standards, which would accelerate platform integration and market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Ultrasonic Sensor Production | Addresses growing demand for non-invasive flow measurement in chemical and pharmaceutical sectors. |
| Strategic Partnership for AI Integration | Combines sensor data with advanced analytics for predictive maintenance and optimized process control. |
| Geographic Expansion into Southeast Asia | Capitalizes on rapid industrialization and infrastructure development in Vietnam and Indonesia. |
| Acquisition of Software Analytics Firm | Enhances capability to deliver integrated data solutions and value-added services beyond hardware. |
| Investment in MEMS Sensor R&D | Develops compact, low-power flow sensors for medical devices and semiconductor process monitoring. |
Research Approach
Bottom-up water treatment end-use modeling reconciled against top-down flow sensor supply-side tracking forms the analytical core of this study. Primary interviews with plant managers, process engineers, procurement leads, and regulatory compliance officers provided qualitative insights. Secondary validation utilized EPA reports, EU Green Deal documents, METI publications, and company 10-K filings. This approach triangulates market sizing and growth projections.
Historical trendline analysis, coupled with a forward-looking econometric model, projects market growth across the analysis window. Segmentation dimensions modeled include product type, technology, end-user, application, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) derive from a regression analysis of historical performance and projected demand drivers. Industrial output growth rates and environmental compliance spending serve as key forecast inputs.
The model holds under current regulatory stability and projected industrial investment; deviation in geopolitical stability or raw material costs would shift the forecast. Forecasts reflect assumptions concerning technological adoption rates and infrastructure spending. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Timing Device Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
North America Turbomachinery Control Systems Market