
 Middle East Robotic Sensors Market | 2026-2036
Middle East Robotic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Robotic Sensors Market Insights
Project finance tied to sovereign wealth infrastructure programs is reshaping competitive access in the Middle East robotic sensors space. FANUC Corporation leverages its established distributor networks across Gulf manufacturing zones to sustain equipment placement volumes. Honeywell International Inc. anchors regional petrochemical automation through its process control heritage and localized service infrastructure. Omron Corporation competes on compact sensor architectures suited to space-constrained installations in retrofit factory environments.
Middle East robotic sensors are electromechanical transducers that convert physical stimuli—displacement, thermal flux, optical reflectance, or pressure differentials—into processable electrical signals, typically operating across temperature ranges from minus forty to one hundred twenty degrees Celsius in desert industrial conditions. These devices enable closed-loop control in unmanned systems where human operator presence is impractical or hazardous. Vision sensors command premium positioning in the product type matrix due to computational demands and integration complexity with AI-driven quality inspection. Ultrasonic technology leads deployment in automated guided vehicles where dust and particulate interference degrade optical alternatives. Industrial automation applications concentrate margin pools through multi-sensor integration contracts and recurring calibration service attachments.
SFDA in Saudi Arabia and MOHAP in the UAE govern medical robotics sensor certifications, while the EU AI Act extraterritorially influences Gulf-based manufacturers exporting to European markets. BIS-equivalent conformity assessment procedures in the UAE and Saudi Arabia's SASO technical regulations shape product entry requirements for industrial sensor imports. Stakeholders must monitor evolving Gulf harmonization efforts between national standards bodies and IEC frameworks to anticipate compliance cost shifts.
Market Dynamics
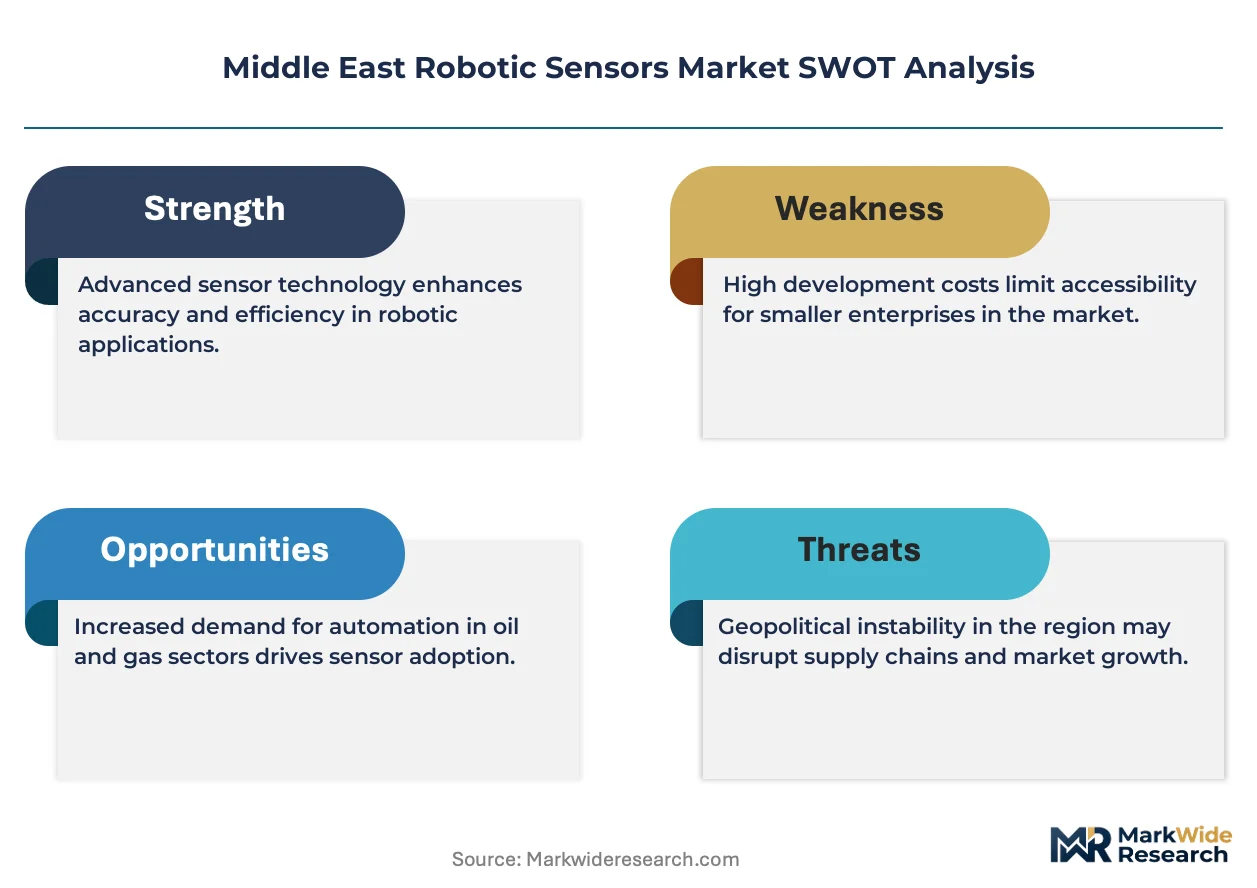
Sovereign wealth infrastructure programs are redirecting procurement flows toward integrated automation bundles, compressing standalone sensor margins while elevating system-level contract values across Gulf manufacturing and energy corridors.
Growth Catalysts
- SFDA Medical Device Framework:Saudi Arabia's regulatory pathway accelerates healthcare robotics sensor approvals, expanding addressable demand in surgical automation and diagnostic imaging systems.
- Pipeline Inspection Robotics:Oil and gas operators across the Gulf deploy autonomous crawler systems for subsea and desert pipeline monitoring, driving multi-sensor procurement for pressure, thermal, and vision modules.
- Retrofit Factory Environments:Space-constrained manufacturing facilities in the UAE prioritize compact sensor architectures that enable closed-loop control without production line reconfiguration.
Market Restraints
- ASIC Supply Concentration:Custom signal processing chips for robotic sensors concentrate fabrication in East Asian foundries, exposing Gulf integrators to geopolitical supply interruptions.
- Desert Thermal Cycling:Ambient temperature swings from minus forty to one hundred twenty degrees Celsius degrade MEMS calibration stability, forcing redundant sensor deployments that inflate unit economics.
- SASO Conformity Costs:Saudi Arabia's technical regulations impose extended testing timelines for industrial sensor imports, delaying revenue recognition for foreign suppliers.
Strategic Opportunities
- AI Regulatory Guidelines:The UAE's emerging framework for autonomous system governance creates first-mover positioning for sensor vendors demonstrating explainable AI integration in quality inspection.
- Automated Guided Vehicles:Ultrasonic sensor deployments in logistics hubs across Qatar and Kuwait address dust-degraded optical alternatives, opening application-specific volume pools.
- Calibration Service Attachments:Multi-sensor integration contracts in petrochemical automation generate recurring revenue streams through mandatory recertification protocols tied to process safety mandates.
Industry Challenges
- Embedded Systems Engineering Talent:Gulf universities produce insufficient firmware developers for sensor fusion algorithms, forcing vendors to import expensive expatriate technical teams.
- IEC Harmonization Delays:Divergent national standards between Saudi Arabia and the UAE complicate pan-Gulf product certification, fragmenting addressable market scale.
- Legacy DCS Integration:Brownfield industrial sites operate proprietary communication protocols that require costly gateway hardware for robotic sensor connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Robotic Sensors Market |
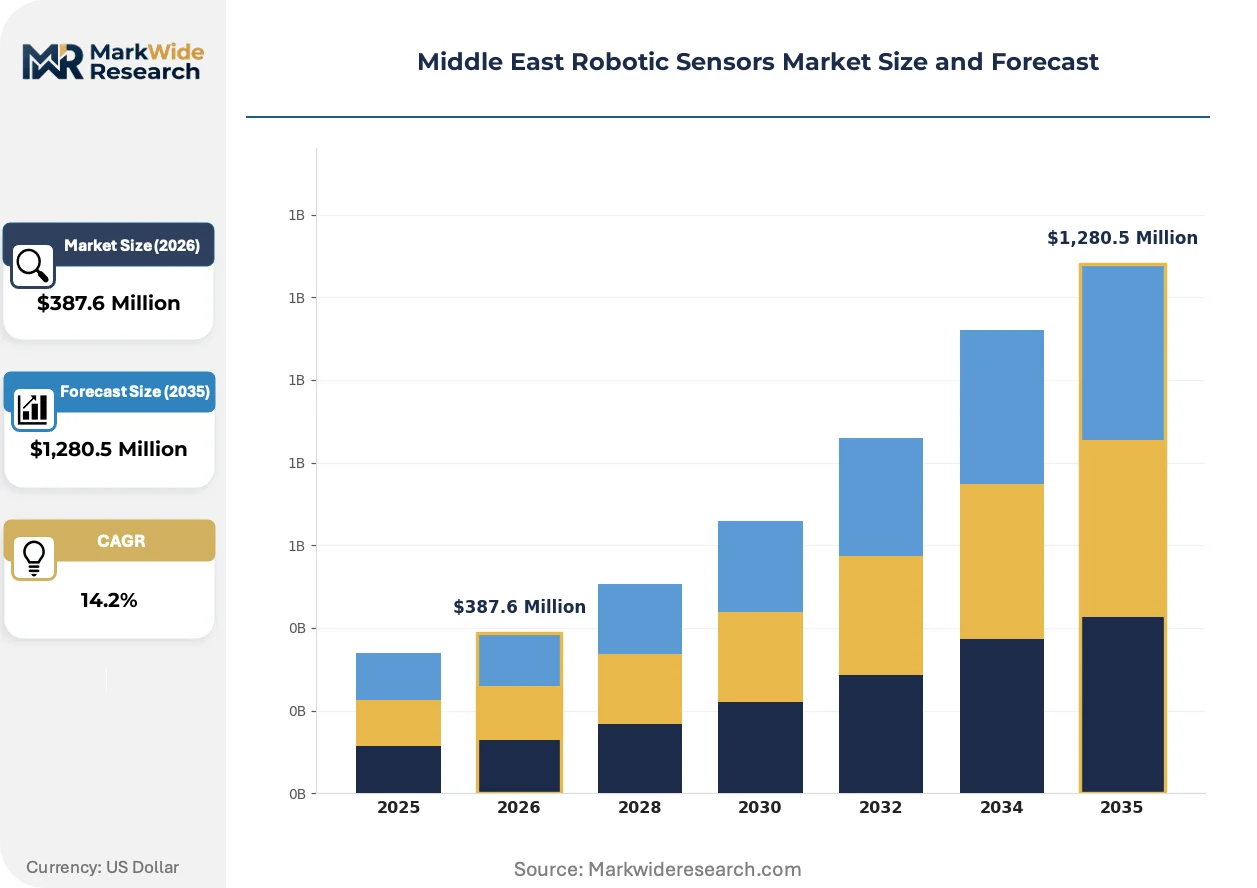
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proximity Sensors, Vision Sensors, Pressure Sensors, Temperature Sensors End User: Aerospace, Manufacturing, Healthcare, Agriculture Technology: Infrared, Ultrasonic, Laser, Magnetic Application: Automated Guided Vehicles, Drones, Industrial Automation, Surveillance |
| Companies Covered | FANUC Corporation, Honeywell International Inc., Omron Corporation, Baumer Group, Infineon Technologies, TE Connectivity Ltd., Sensata Technologies Inc., ATI Industrial Automation Inc., SICK AG, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Robotic Sensors Market Trends and Innovations
Computational sensor architectures are converging with edge AI inference, compressing decision latency in unmanned systems while regulatory frameworks across the Gulf codify performance benchmarks for autonomous operation.
Time-of-flight vision modules are hybridizing with structured light patterns to deliver sub-millimeter depth accuracy in high-ambient-light desert conditions. Petrochemical inspection contractors in Saudi Arabia's Eastern Province deploy these fused systems for corrosion mapping on above-ground storage tanks. The technology is hybridizing optical and ultrasonic modalities into single-package solutions that reduce sensor count per robotic platform.
Saudi Arabia's SFDA and the UAE's MOHAP are synchronizing electromagnetic compatibility requirements for surgical robotics sensors, creating a unified Gulf compliance corridor. Manufacturers targeting both markets now submit single technical files rather than parallel national dossiers. Medical device distributors in Dubai and Riyadh are consolidating certification management to capture economies from this regulatory convergence.
Integrated automation procurement now bundles sensors, actuators, and control software into single-source contracts that displace component-level vendor relationships. Oilfield service companies in Abu Dhabi and Dammam favor turnkey system integrators over discrete sensor suppliers. This consolidation concentrates margin capture with FANUC, Honeywell, and Omron's regional service infrastructure, compressing opportunities for standalone sensor specialists without local calibration capabilities.
Middle East Robotic Sensors Market Segmentation
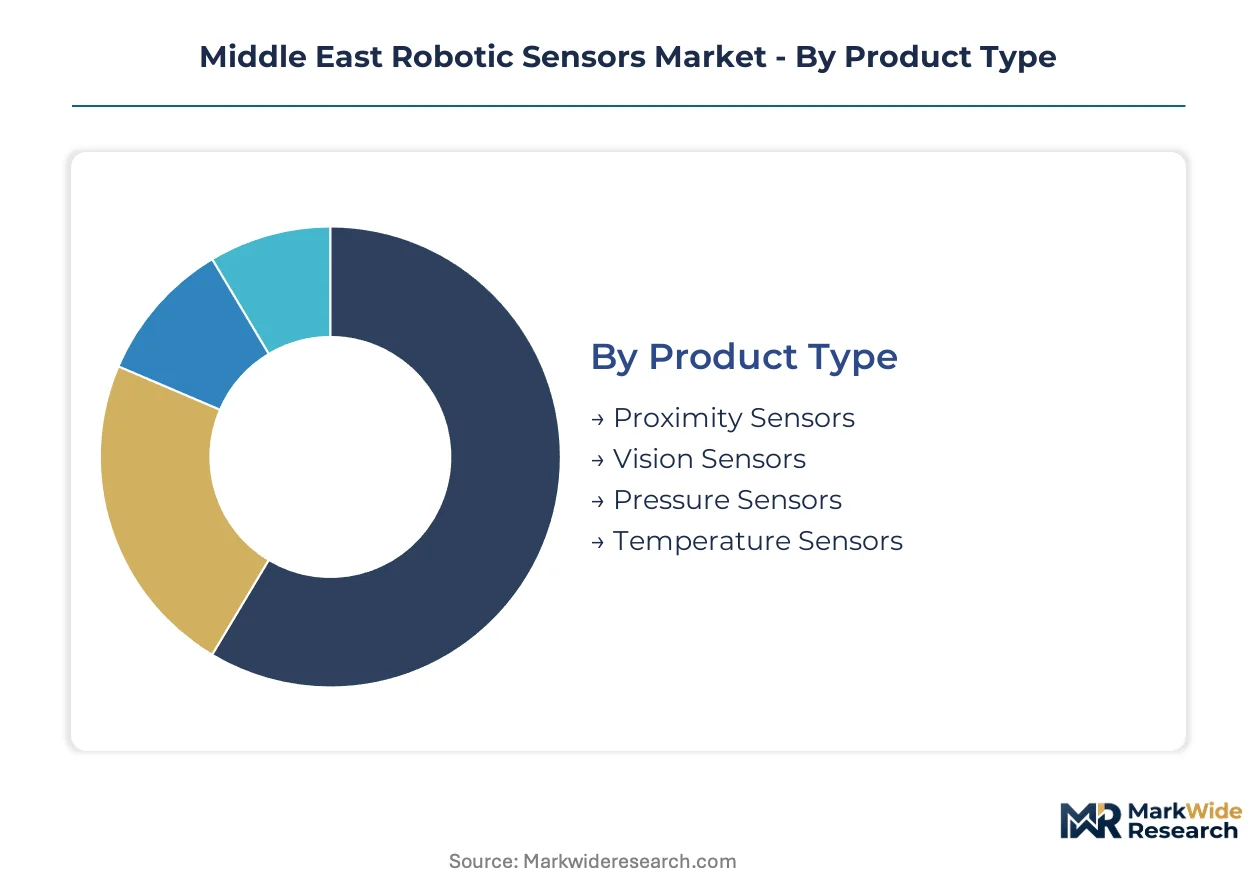
Segmentation in the Middle East robotic sensors market reveals distinct procurement patterns across Gulf industrial corridors. Understanding these divisions enables vendors to align technical specifications with sector-specific compliance requirements and environmental operating conditions.
Product Type:
Sensor selection spans displacement detection through thermal monitoring, with each technology addressing distinct automation challenges in desert industrial environments.
- Vision Sensors:Computational imaging modules process optical reflectance into machine-readable data streams for quality inspection and navigation. Saudi petrochemical operators deploy these for corrosion mapping on above-ground storage tanks, where sub-millimeter depth accuracy justifies premium positioning despite integration complexity.
- Proximity Sensors:Electromechanical devices detect object presence without physical contact through capacitive, inductive, or photoelectric principles. UAE manufacturing hubs favor compact architectures that enable retrofit installation in space-constrained production lines without reconfiguration downtime.
- Pressure Sensors:Transducers convert fluid or gas pressure differentials into electrical signals for process control.
- Temperature Sensors:Thermal monitoring devices track gradients across minus forty to one hundred twenty degrees Celsius operating ranges in desert conditions.
The dominant share belongs to Vision Sensors, while Proximity Sensors is closing the gap fastest.
End User:
Demand concentrates in sectors where sovereign wealth deployment and regulatory frameworks create structured procurement channels.
- Oil and Gas:Pipeline inspection robotics and refinery maintenance systems drive multi-sensor procurement for pressure, thermal, and vision modules across Gulf energy corridors.
- Manufacturing:Retrofit factory environments in the UAE prioritize sensor architectures that deliver closed-loop control without production line reconfiguration.
- Healthcare:SFDA medical device framework and MOHAP certifications govern surgical robotics and diagnostic imaging sensor approvals in Saudi Arabia and the UAE.
- Agriculture:Precision farming applications in arid climates deploy soil moisture and crop monitoring sensors with limited penetration compared to industrial segments.
Oil and Gas commands the largest procurement volumes, though Healthcare is expanding most quickly through regulatory harmonization between Riyadh and Dubai.
Technology:
Signal propagation methods compete on environmental resilience and integration cost in Gulf deployment conditions.
- Ultrasonic:Acoustic ranging systems transmit high-frequency pulses and measure return time for distance calculation. Automated guided vehicles in Qatar and Kuwait logistics hubs favor this technology where dust and particulate interference degrade optical alternatives.
- Laser:Time-of-flight and structured light modules deliver precise depth mapping for industrial metrology and navigation applications.
- Infrared:Thermal detection systems capture radiant heat signatures for presence sensing and temperature monitoring.
- Magnetic:Hall-effect and magnetoresistive sensors detect field variations for position and speed measurement in harsh environments.
Ultrasonic maintains installed base leadership in logistics applications, while Laser is gaining share fastest through hybrid optical-structured light architectures.
Application:
Deployment scenarios range from mobile autonomous platforms to fixed industrial infrastructure across Gulf economic zones.
- Industrial Automation:Multi-sensor integration contracts in petrochemical and manufacturing facilities generate recurring calibration service attachments tied to process safety mandates.
- Automated Guided Vehicles:Warehouse and logistics automation in Dubai and Dammam corridors drives ultrasonic and vision sensor procurement for navigation and obstacle avoidance.
- Drones:Aerial inspection platforms for pipeline monitoring and facility surveillance require lightweight sensor payloads with stabilized imaging capabilities.
- Surveillance:Security and monitoring applications deploy motion detection and thermal imaging sensors with limited growth relative to industrial segments.
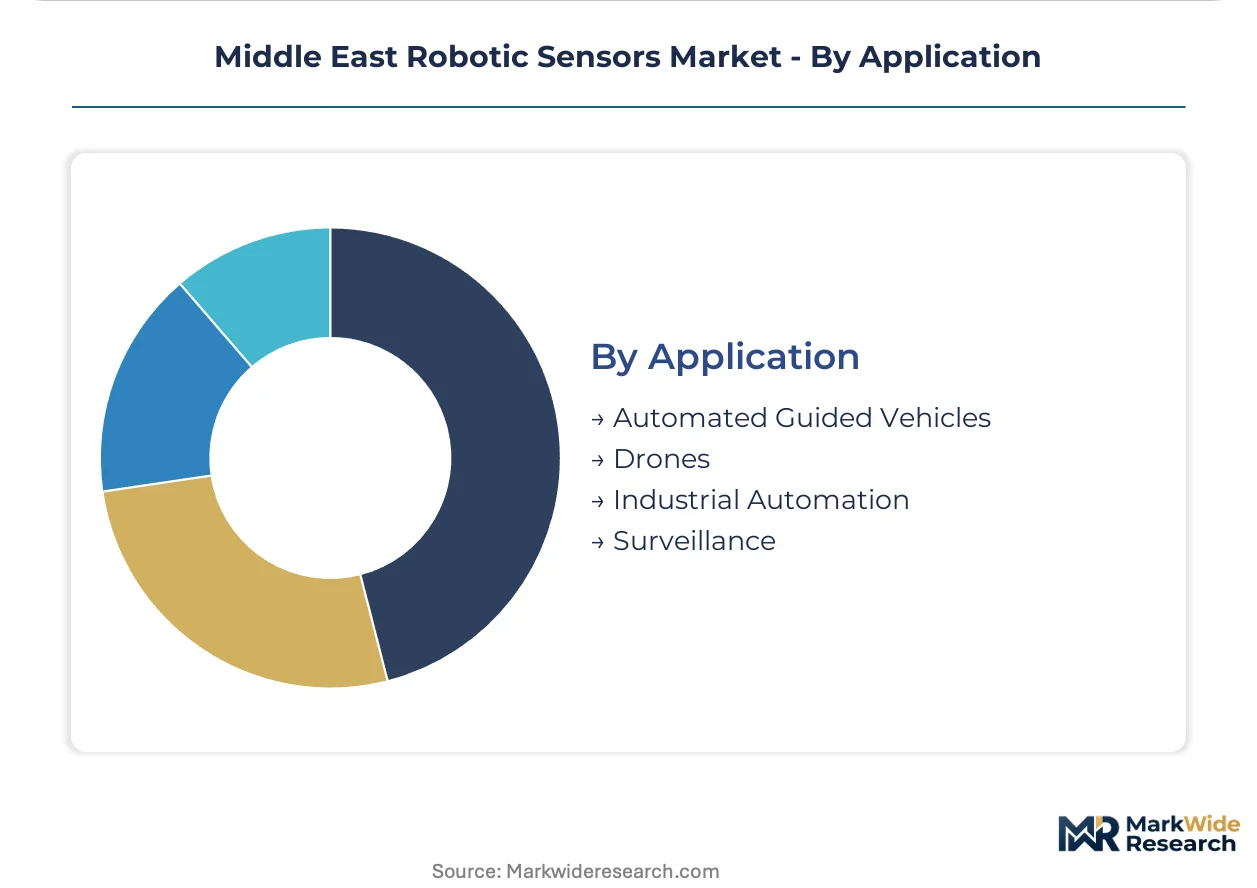
Industrial Automation captures the dominant revenue share, while Automated Guided Vehicles shows the steepest expansion trajectory through logistics hub development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oil and gas operators, healthcare system integrators, and logistics automation buyers concentrate procurement decisions in Riyadh, Dubai, and Dammam industrial corridors, with sovereign wealth infrastructure programs redirecting contract flows toward bundled system providers.
Saudi Arabia
SFDA medical device approvals and pipeline inspection robotics drive sensor demand across surgical automation and energy infrastructure. SASO technical regulations govern industrial sensor imports through extended conformity assessment timelines. Eastern Province petrochemical clusters deploy multi-sensor crawler systems for above-ground storage tank corrosion mapping.
United Arab Emirates
MOHAP healthcare certifications and AI regulatory guidelines create compliance pathways for surgical robotics and autonomous quality inspection. Retrofit manufacturing facilities in Dubai prioritize compact sensor architectures for space-constrained production lines. Jebel Ali logistics corridors drive ultrasonic sensor procurement for automated guided vehicles in dust-intensive warehouse environments.
Qatar
Logistics hub development and automated port operations concentrate demand for navigation and obstacle avoidance sensors. The country's national standardization body aligns with IEC frameworks for industrial automation equipment. Lusail smart city infrastructure deploys integrated sensor-actuator bundles for municipal robotics applications.
Kuwait
Automated warehouse expansion in free trade zones favors ultrasonic ranging systems over optical alternatives degraded by particulate interference. National industrial strategy programs prioritize manufacturing automation through sovereign procurement channels. Shuwaikh industrial area retrofit projects require closed-loop sensor integration without production line reconfiguration.
Israel
Defense and aerospace robotics R&D generates specialized demand for vision and thermal sensor modules with stabilized imaging capabilities. The country's national innovation authority funds autonomous system development through targeted grant programs. Tel Aviv metropolitan technology clusters concentrate startup activity in sensor fusion algorithm development.
Middle East Robotic Sensors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Gulf procurement corridors. System integrators with localized calibration capabilities capture recurring service attachments, while component suppliers without regional infrastructure face margin compression. Three archetypes dominate: turnkey automation providers with sovereign wealth relationships, compact sensor specialists targeting retrofit environments, and semiconductor fabricators supplying custom signal processing chips. M&A activity concentrates on calibration service networks, while strategic partnerships between Gulf distributors and East Asian foundries secure ASIC supply continuity.
Within the channel-controlling tier, FANUC Corporation and Honeywell International Inc. anchor regional positioning through established distributor networks and petrochemical automation heritage. Omron Corporation exemplifies the compact sensor specialist archetype, with architectures suited to space-constrained UAE manufacturing retrofits. These three occupy positions that concentrate margin capture with integrated automation procurement trends.
| Leading Market Players |
|---|
| FANUC Corporation |
| Honeywell International Inc. |
| Omron Corporation |
| Baumer Group |
| Infineon Technologies |
| TE Connectivity Ltd. |
| Sensata Technologies Inc. |
| ATI Industrial Automation Inc. |
| SICK AG |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian MEMS foundries is compressing wafer pricing and enabling Gulf integrators to negotiate favorable ASIC supply terms, while simultaneously pressuring standalone sensor vendors to bundle calibration services to defend margin structures.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate multi-sensor integration agreements in Saudi petrochemical automation. Three-tier pricing structure across premium, standard, and economy levels separates vision modules with AI-ready edge processing from basic proximity sensors. Pricing pressure stems from sovereign wealth procurement bundling sensors with actuators and control software. System integrators with localized calibration capabilities exhibit lowest price sensitivity; standalone component suppliers face acute margin compression.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Pegatron holding capacity for sensor module assembly and system integration. Taiwan, South Korea, and China anchor semiconductor fabrication for custom signal processing chips. Raw material dependencies include silicon wafers, rare earth magnets, and optical-grade glass substrates. Single-source vulnerability around East Asian foundry concentration threatens supply continuity. Distribution runs through authorized distributor networks anchored in Jebel Ali and Dammam industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as oil and gas capital expenditure inflects upward following the 2020-2023 retrenchment, with pipeline inspection robotics driving replacement demand for degraded sensor fleets.
For Market Incumbents: Insulate margin structures by deepening backward integration into calibration service networks across Saudi Arabia's Eastern Province and the UAE's Jebel Ali corridor. Acquire regional distributors with SASO certification expertise to compress conformity assessment timelines. Sovereign wealth bundling of automation systems threatens standalone sensor pricing power. For New Entrants and Emerging Players: Compact sensor architectures for space-constrained retrofit factories in Dubai and Sharjah represent the most penetrable entry point. Automated guided vehicle navigation modules for Qatar and Kuwait logistics hubs offer application-specific volume pools with lower incumbent saturation. Partner with established Gulf system integrators to bypass direct SASO conformity costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across calibration service networks as software-defined recertification protocols reduce labor dependency. Long-term viability centers on recurring revenue attachment rates rather than hardware shipment volumes. Acquisition targets should demonstrate explainable AI integration capabilities aligned with emerging UAE regulatory frameworks. Monitor sovereign wealth infrastructure program announcement cadence as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Captures recurring revenue streams tied to SFDA and MOHAP recertification mandates in Riyadh and Dubai. |
| ASIC Supply Agreement with East Asian Foundries | Secures fabrication priority for custom signal processing chips amid geopolitical supply interruption risks. |
| AI-Ready Sensor Architecture Development | Positions vendors for first-mover advantage under emerging UAE autonomous system governance frameworks. |
| Retrofit Factory Partnership Program | Addresses space-constrained installation demand in UAE manufacturing hubs without production line reconfiguration. |
| Sovereign Wealth System Integrator Alliance | Concentrates margin capture with bundled automation procurement flows redirecting from component vendors. |
Research Methodology
Initial hypotheses were tested against primary input from robotics system integrators, petrochemical maintenance directors, biomedical engineers at SFDA-regulated facilities, and logistics automation procurement leads, then refined through secondary validation against IEC standard documentation, SASO technical regulation filings, customs import records for industrial sensors, and sovereign wealth infrastructure program disclosures. Bottom-up sensor shipment estimates were triangulated with top-down automation capex allocations.
Demand-supply balance modeling anchored forecast construction, with segmentation across vision, proximity, pressure, and temperature sensor product types; oil and gas, manufacturing, healthcare, and agriculture end users; ultrasonic, laser, infrared, and magnetic technologies; and industrial automation, automated guided vehicles, drones, and surveillance applications. CAGRs were derived from fitted growth curves against historical procurement patterns and projected sovereign wealth deployment schedules. Forecast inputs incorporated desert thermal cycling degradation rates and regulatory harmonization timelines between Riyadh and Dubai.
Macroeconomic conditions sit as an overlay; deviation in oil prices, Gulf sovereign wealth liquidity, or East Asian semiconductor export restrictions would shift the trajectory. Forecasts reflect documented assumptions about regulatory convergence and foundry capacity expansion. Quarterly review of SFDA approval cadence, SASO conformity assessment backlogs, and UAE AI regulatory framework publication schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market