
 North America Tumor Ablation Market | 2026-2036
North America Tumor Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tumor Ablation Market Insights
Premium catheter-based systems and commodity electrode kits is repositioning across distinct clinical workflows. Medtronic plc anchors its presence through integrated navigation platforms that pair ablation hardware with real-time imaging. Boston Scientific Corporation differentiates via specialized cryoablation portfolios targeting renal and pulmonary lesions. HealthTronics, Inc. competes through service-based delivery models that place mobile ablation units directly into outpatient settings.
North America tumor ablation encompasses percutaneous and intraoperative techniques that apply thermal, electromagnetic, or cryogenic energy to destroy malignant tissue while sparing adjacent structures; radiofrequency systems typically operate at 460–480 kHz and generate temperatures exceeding 60°C to achieve coagulative necrosis. Microwave ablation dominates procedural volume in liver and lung applications due to faster heating profiles and reduced susceptibility to heat-sink effects from adjacent vasculature. Cryoablation commands premium positioning in kidney cancer, where ice-ball visualization under CT guidance enables precise margin control. Ambulatory surgical centers represent the fastest-growing end-user channel as payors shift reimbursement toward same-day interventional oncology.
FDA premarket notification and FDA premarket approval pathways govern device commercialization, while CMS reimbursement determinations directly shape hospital capital allocation toward ablation technologies. The Joint Commission accreditation standards for interventional radiology suites influence site-of-care expansion decisions across hospital networks. Stakeholders must monitor state-level Medicaid coverage expansion for outpatient ablation procedures, as these policies will determine whether ambulatory growth materializes in secondary metropolitan markets.
Market Dynamics
Reimbursement migration toward outpatient settings is compressing hospital capital cycles and forcing device manufacturers to reconfigure delivery models around ambulatory surgical centers.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for minimally invasive ablation systems is shortening commercialization timelines from 18 months to under 12 months for predicate-eligible devices.
- Ambulatory surgical center expansion:CMS reimbursement parity for same-day tumor ablation procedures is redirecting procedural volume away from inpatient settings across Texas and California metropolitan corridors.
- Microwave ablation technology maturation:Faster heating profiles and reduced heat-sink susceptibility are displacing radiofrequency systems in hepatic and pulmonary applications.
Market Restraints
- Capital equipment intensity:Integrated navigation platforms requiring CT or MRI compatibility demand $800,000–$1.2 million upfront investment per installation site.
- Specialized workforce scarcity:Interventional radiology fellowship programs produce fewer than 300 ablation-trained physicians annually across the United States and Canada.
- Reimbursement code fragmentation:Inconsistent CPT coding for cryoablation versus thermal modalities creates claims denial risk and payment delay.
Strategic Opportunities
- Secondary metropolitan penetration:Phoenix, Nashville, and Austin cancer corridors remain undersupplied with mobile ablation service units relative to patient incidence density.
- Artificial intelligence navigation convergence:Real-time tumor segmentation algorithms paired with electromagnetic tracking are enabling novice operators to achieve expert-equivalent margin control.
- Medicaid expansion tailwinds:State-level coverage determination for outpatient ablation in Florida and Georgia will unlock previously uninsured patient populations.
Industry Challenges
- Interventional oncology training pipeline:Fellowship programs lack standardized ablation curriculum, forcing device manufacturers to fund proprietary education infrastructure.
- Legacy EMR integration friction:Proprietary navigation platforms require custom HL7 interfaces with hospital electronic medical record systems, extending implementation timelines.
- Supply chain single-source risk:Cryogen delivery for argon-helium systems depends on concentrated industrial gas suppliers with limited redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tumor Ablation Market |
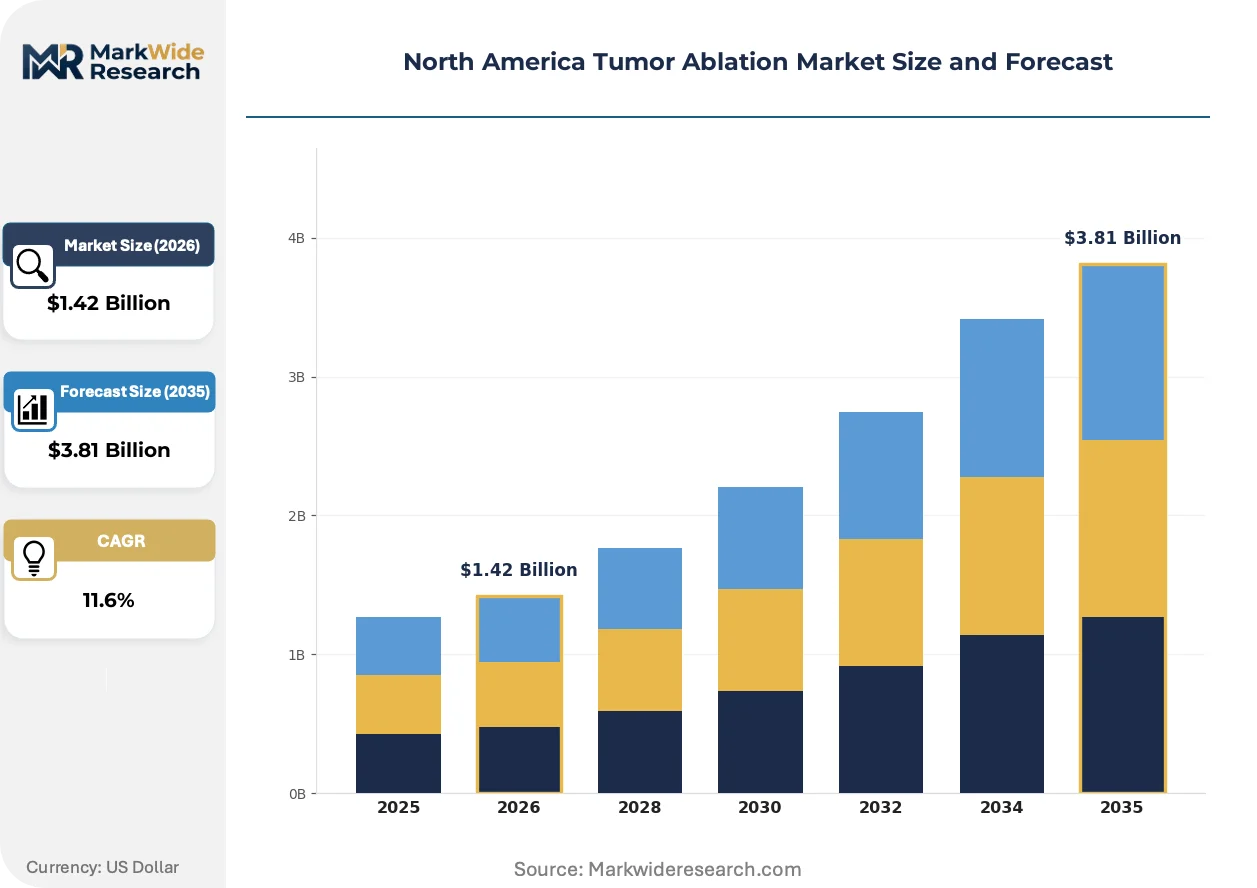
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Microwave Ablation, Cryoablation, Laser Ablation End User: Hospitals, Ambulatory Surgical Centers, Oncology Clinics, Research Institutes Technology: Electromagnetic, Thermal, Cryogenic, Optical Application: Liver Cancer, Lung Cancer, Kidney Cancer, Bone Cancer |
| Companies Covered | AngioDynamics Inc., EDAP TMS S.A., Medtronic plc, HealthTronics, Inc., Stryker Corporation, Boston Scientific Corporation, Bioventus Inc., Mermaid Medical, Johnson & Johnson Service Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tumor Ablation Market Trends and Innovations
Device architecture is converging around disposable-electrode business models that decouple hardware revenue from capital sales cycles. This shift is compressing pricing transparency and forcing service-based differentiation.
Pulsed-field ablation is electrifying cardiac and oncologic tissue destruction through non-thermal electroporation mechanisms that spare collagen and nerve architecture. Academic medical centers in Boston and Houston are adopting these systems for prostate and pancreatic lesions where thermal damage risks functional deficit. The technology is electrifying competitive positioning by enabling treatment of tumors adjacent to critical structures previously deemed unresectable.
CMS national coverage determination for percutaneous ablation of small renal masses is clarifying reimbursement thresholds and reducing administrative burden for prior authorization. The policy compresses variation in Medicare Advantage plan coverage across state lines. Hospital networks in the Midwest are responding by consolidating purchasing decisions at the system level rather than individual facility procurement.
Site-of-care economics is driving hospital-employed physicians toward office-based interventional suites equipped with C-arm fluoroscopy and portable ultrasound. Equipment lessors are displacing traditional capital sales with per-procedure fee structures that align vendor revenue with patient throughput. This pattern is most visible in Florida and Arizona where certificate-of-need restrictions on hospital expansion push procedural volume into outpatient settings.
North America Tumor Ablation Market Segmentation
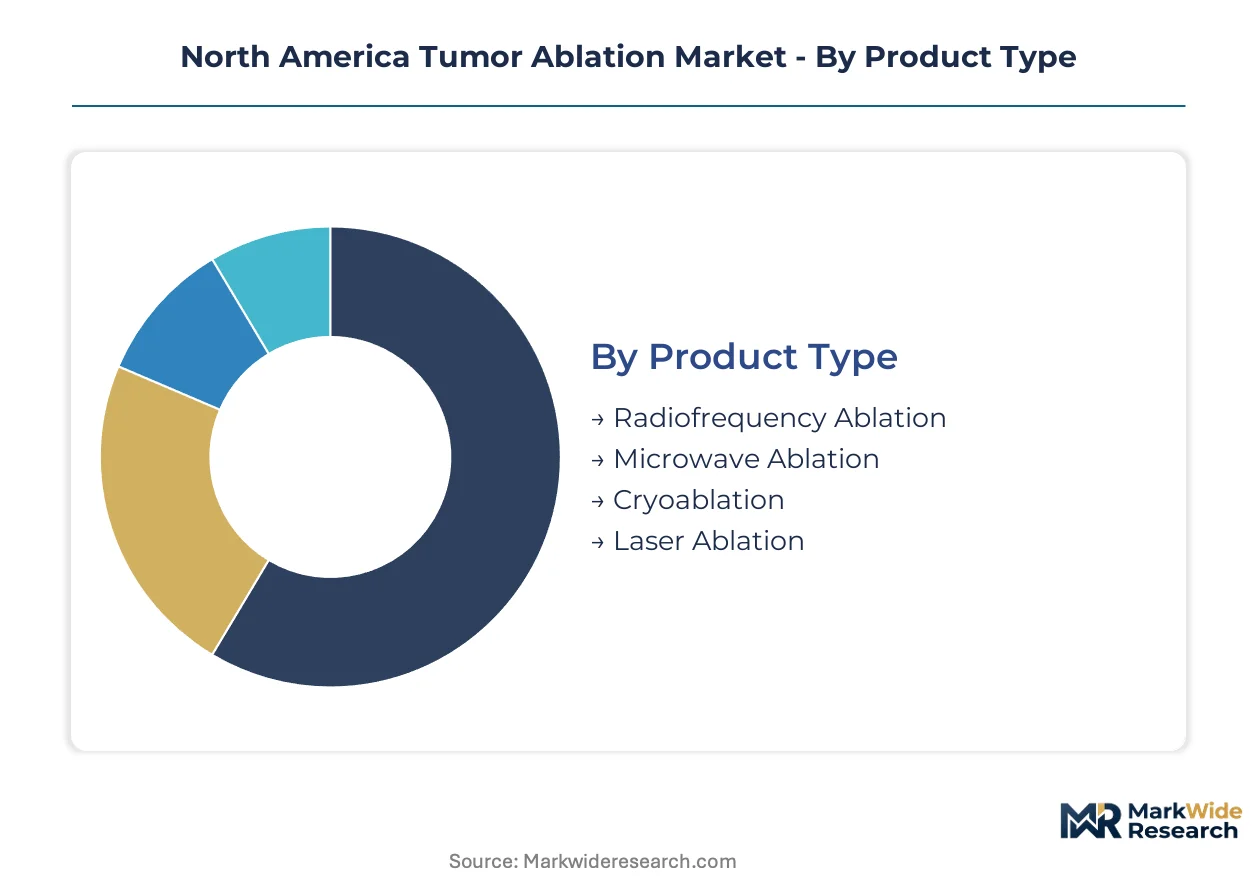
Segmentation in tumor ablation reveals how technology choices cascade through reimbursement structures and site-of-care economics. Each dimension—product type, end user, technology platform, and clinical application—carries distinct capital intensity and regulatory pathways that shape vendor strategy.
Product Type:
Microwave systems command premium pricing through faster procedural throughput, while radiofrequency hardware dominates installed base volume across hospital networks.
- Microwave Ablation:Generates electromagnetic energy at 915 MHz or 2.45 GHz to achieve rapid thermal coagulation with minimal heat-sink interference from adjacent vasculature. Demand concentrates in California and Texas liver cancer centers where reduced procedure time translates to higher ambulatory surgical center throughput.
- Radiofrequency Ablation:Operates at 460–480 kHz to produce resistive heating through ionic agitation, constituting the most mature installed base across United States hospital networks. Procurement is shifting toward disposable electrode kits that reduce per-procedure cost in Medicare-reimbursed settings.
- Cryoablation:Deploys argon-helium gas cycles to create precise ice-ball margins visible under CT guidance, commanding premium positioning in kidney cancer applications.
- Laser Ablation:Delivers concentrated optical energy through fiberoptic probes, finding niche adoption in neuro-oncology and spinal metastasis cases.
Today's leader: Microwave Ablation. Tomorrow's challenger: Cryoablation.
End User:
Site-of-care migration is fragmenting purchasing authority between centralized hospital procurement and decentralized ambulatory operators.
- Hospitals:Maintain capital equipment ownership for integrated navigation platforms requiring CT or MRI suite compatibility, with interventional radiology departments anchoring procedural volume in metropolitan hubs.
- Ambulatory Surgical Centers:Represent the steepest expansion trajectory as CMS reimbursement parity redirects same-day tumor ablation away from inpatient settings across Texas and California corridors.
- Oncology Clinics:Deploy portable ultrasound-guided systems for superficial lesions, operating under distinct state-level licensure frameworks.
- Research Institutes:Drive early adoption of pulsed-field ablation and artificial intelligence navigation convergence through investigator-initiated trials.
Procurement authority fragments fastest where reimbursement migrates.
Technology:
Thermal modalities anchor current revenue, while electromagnetic platforms enable next-generation precision.
- Thermal:Encompasses radiofrequency and microwave systems that elevate tissue temperature beyond 60°C to induce coagulative necrosis, dominating procedural volume in hepatic and pulmonary applications.
- Electromagnetic:Includes microwave and emerging pulsed-field systems that leverage field effects rather than pure heat transfer, gaining share in lesions adjacent to critical structures.
- Cryogenic:Utilizes rapid gas expansion to achieve temperatures below -40°C, enabling real-time margin visualization that commands premium pricing in renal cancer.
- Optical:Delivers laser energy through flexible fiberoptics, constrained by limited tissue penetration depth and specialized operator training requirements.
Margin capture follows modality differentiation.
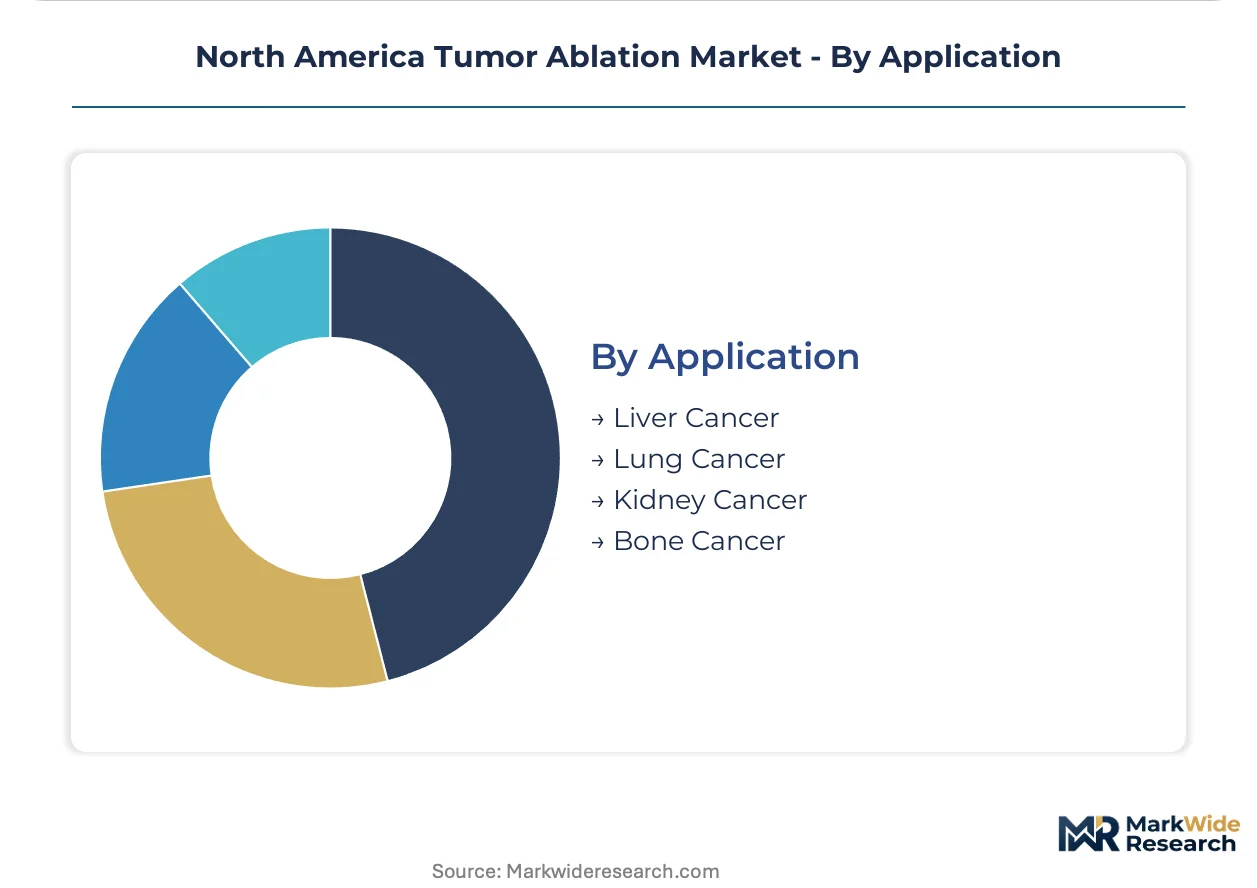
Application:
Organ-specific reimbursement determinations by CMS concentrate investment in approved indications.
- Liver Cancer:Represents the most established ablation indication with extensive long-term survival data, driving microwave system adoption in United States academic medical centers.
- Kidney Cancer:Benefits from clarified CMS national coverage determination for percutaneous ablation of small renal masses, reducing prior authorization burden across Medicare Advantage plans.
- Lung Cancer:Requires navigation platform integration with CT fluoroscopy to address respiratory motion, elevating capital requirements for procedural sites.
- Bone Cancer:Targets palliative pain control in metastatic disease, operating under distinct reimbursement codes that create claims complexity.
Reimbursement clarity determines capital deployment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional radiology fellowship programs in the United States and Canada produce fewer than 300 ablation-trained physicians annually, constraining procedural capacity across metropolitan corridors. This workforce scarcity concentrates specialized care within established cancer centers while creating penetration opportunities in secondary markets.
United States
California and Texas metropolitan hubs anchor demand through clustered NCI-designated cancer centers expanding interventional oncology departments. FDA 510(k) pathway acceleration for predicate-eligible ablation devices shortens commercialization timelines below twelve months. Phoenix, Nashville, and Austin corridors remain undersupplied with mobile ablation service units relative to patient incidence density.
Canada
Provincial health authorities in Ontario and Quebec prioritize microwave ablation for hepatic metastases within centralized academic medical center networks. Health Canada device licensing requirements align with FDA predicate pathways, enabling synchronized North American product launches. Toronto and Montreal anchor procurement decisions for integrated navigation platforms requiring MRI suite compatibility.
Mexico
Private hospital groups in Mexico City and Monterrey deploy radiofrequency systems for liver and kidney cancer through cash-pay oncology programs. COFEPRIS regulatory convergence with FDA standards accelerates importation of predicate-cleared devices from US manufacturers. Guadalajara's medical tourism corridor attracts cross-border patients seeking same-day ablation procedures at cost-advantaged rates.
North America Tumor Ablation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America tumor ablation landscape. Integrated navigation platform vendors owning CT and MRI-compatible hardware anchor the consolidated tier, while disposable electrode manufacturers occupy fragmented downstream positions. Strategic archetypes separate into three clusters: navigation-integrated system vendors, specialized cryoablation technology holders, and mobile service delivery operators. Dominant competitive moves include per-procedure fee structures displacing capital sales and artificial intelligence navigation convergence enabling novice operator proficiency.
Within the navigation-integrated tier, Medtronic plc and Boston Scientific Corporation exemplify platform-scale positioning through hardware-imaging pairings and cryoablation specialization respectively. HealthTronics, Inc. occupies the service-delivery archetype, placing mobile ablation units directly into outpatient settings without capital ownership transfer. These three anchors represent divergent responses to reimbursement migration toward ambulatory surgical centers.
| Leading Market Players |
|---|
| AngioDynamics Inc. |
| EDAP TMS S.A. |
| Medtronic plc |
| HealthTronics, Inc. |
| Stryker Corporation |
| Boston Scientific Corporation |
| Bioventus Inc. |
| Mermaid Medical |
| Johnson & Johnson Service Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into cryogen supply and navigation platform manufacturing anchors pricing power for integrated system vendors while compressing margins for disposable electrode assemblers. This supply position stratifies the market into capital-heavy navigation owners and commodity component suppliers.
Pricing Analysis
Bundled service contracts that wrap hardware, software, and per-procedure technical support command premium positioning against unbundled capital sales. Three-tier pricing structure across premium navigation-integrated systems, mid-range microwave platforms, and economy radiofrequency electrode kits reflects FDA 510(k) clearance tier and imaging compatibility depth. Cost compression in the electrode kit segment is intensifying because ambulatory surgical centers prioritize per-procedure cost minimization over capital ownership. Hospital purchasing committees exhibit lowest price sensitivity due to bundled reimbursement, while independent outpatient clinics drive hardest bargain on disposable consumables.
Supply Chain Analysis
Regional distribution centers in California, Texas, and Ontario anchor hub-and-spoke patterns that position inventory within four-hour ground transport of major metropolitan cancer corridors. Component sourcing draws from precision-machined electrodes manufactured in the United States, semiconductor navigation chips from Taiwan, and argon-helium cryogen from industrial gas suppliers concentrated in the Gulf Coast petrochemical complex. Single-source vulnerability in cryogen delivery creates supply chain risk during regional weather disruptions or plant maintenance cycles. Distribution runs through manufacturer-direct sales forces for capital platforms and medical device distributors for disposable electrodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America tumor ablation market functions as a stable compounder, with CMS reimbursement parity for outpatient procedures providing predictable demand expansion regardless of macroeconomic cycles.
For Market Incumbents: Cement navigation platform dominance by acquiring electromagnetic tracking specialists before pulsed-field ablation maturation disrupts thermal modality positioning. Expand service-based delivery models into Phoenix, Nashville, and Austin corridors to preempt mobile ablation unit deployment by competitors. Vertical integration into artificial intelligence segmentation software protects margin structure against algorithm commoditization. For New Entrants and Emerging Players: Ambulatory surgical center networks represent the most penetrable channel, with purchasing authority fragmenting away from centralized hospital procurement. Target microwave ablation electrode manufacturing where FDA predicate pathways enable rapid 510(k) clearance without clinical trial burden. Pursue white-label supply partnerships with established navigation platform vendors rather than competing head-to-head on integrated systems. For Investors and Strategic Acquirers: Roll-up economics work for mobile ablation service operators because reimbursement migration toward outpatient settings creates scalable fleet deployment models with recurring revenue characteristics. Platform-agnostic disposable electrode manufacturers with FDA-cleared predicates across thermal modalities offer acquisition appeal. Watch for artificial intelligence navigation convergence achieving novice-operator equivalence as inflection indicator for technology obsolescence risk in traditional hardware.| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Securing prior authorization automation with Medicare Advantage plans in Florida and Georgia unlocks volume. |
| Hospital System Partnership | Integrated navigation platform placement within NCI-designated cancer centers anchors long-term disposable revenue. |
| Software Companion Development | Real-time tumor segmentation algorithms paired with electromagnetic tracking reduce operator training burden. |
| FDA Submission Acceleration | Predicate-eligible 510(k) pathways for microwave systems compress commercialization timelines below twelve months. |
| CE Marking Pathway | Health Canada alignment with FDA standards enables synchronized North American product launches from Ontario. |
Research Methodology
Direct dialogue with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings in clinical workflow realities. Secondary validation drew from FDA 510(k) premarket notification databases, CMS national coverage determinations, hospital procurement contract repositories, and interventional radiology fellowship program accreditation records. Bottom-up procedure volume estimates triangulated against top-down capital equipment installation data across the analysis window.
Bottom-up modeling segmented the market by technology platform, end-user site of care, and clinical application, with cross-validation against manufacturer-reported system placements. Top-down approaches assessed total addressable patient populations eligible for percutaneous ablation by cancer type and stage distribution. CAGRs derived from procedure volume growth trajectories, reimbursement rate evolution, and technology substitution patterns in hepatic and pulmonary applications. Forecast inputs incorporated CMS reimbursement parity implementation timelines and state-level Medicaid expansion determinations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulsed-field ablation clinical trial results and artificial intelligence navigation regulatory classification. Forecasts reflect documented assumptions regarding physician training pipeline expansion and ambulatory surgical center certificate-of-need policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Oncology Market
Oncology
Testicular Cancer Treatment Market
Oncology
Australia Cancer Treatment Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Outpatient Oncology Infusion Market
Oncology
South Korea Radiotherapy Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
Metastatic Cancer Drug Market
Oncology
Gynecological Cancers Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Sterile Oncology Injectable Market
Oncology
Metastatic Breast Cancer Market
Oncology
Throat Cancer Market
Oncology
Osteosarcoma Market