
 Throat Cancer Market | 2026-2036
Throat Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Throat Cancer Market Outlook
Modular combination therapy packaging is recalibrating how oncologists sequence treatment across radiation and systemic protocols. Merck & Co Inc leverages its checkpoint inhibitor portfolio to anchor immuno-oncology positioning in head and neck malignancies. Bristol Myers Squibb competes through sustained investment in dual immunotherapy combinations, while AstraZeneca plc differentiates via antibody-drug conjugate programs targeting EGFR-expressing tumors.
Throat cancer encompasses malignant neoplasms arising from the pharynx, larynx, and adjacent hypopharyngeal structures, classified histologically as squamous cell carcinoma in over ninety percent of cases and staged via TNM criteria assessing tumor invasion, nodal spread, and metastasis. Immunotherapy segments lead value generation as PD-1 inhibitors displace platinum-based chemotherapy in first-line recurrent or metastatic settings, while radiation therapy equipment segments retain stable replacement demand tied to linear accelerator upgrade cycles in hospital networks. Early-stage treatment categories concentrate margin pools due to curative-intent surgical margins and shorter total treatment durations, whereas metastatic segments command higher per-patient pharmaceutical spend despite smaller addressable volumes.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme compress regulatory review timelines for novel biologics in oropharyngeal indications, while the EU's Medical Device Regulation imposes stricter clinical evidence requirements on radiotherapy equipment and biopsy instrument manufacturers seeking CE marking. The NMPA's streamlined oncology drug approval reforms in China are expanding patient access to imported checkpoint inhibitors through local trial requirements. Stakeholders must monitor evolving biomarker-driven label expansions and radiotherapy fractionation protocols to anticipate shifts in treatment sequencing and capital equipment procurement cycles.
Market Dynamics
Checkpoint inhibitor protocols are compressing treatment timelines and recalibrating how oncology clinics sequence radiation with systemic therapy, forcing capital equipment vendors to align upgrade cycles with immunotherapy adoption curves.
Growth Catalysts
- Accelerated FDA pathways:Breakthrough therapy designations compress review timelines for novel biologics in recurrent or metastatic settings, enabling earlier patient access.
- Combination immunotherapy protocols:Dual checkpoint blockade regimens are expanding addressable patient pools beyond platinum-refractory populations.
- Tertiary care concentration:United States academic medical centers drive protocol standardization that diffuses through hospital network affiliations.
Market Restraints
- Platinum supply constraints:Persistent volatility in platinum group metal pricing elevates cost pressure for chemotherapy manufacturing.
- Radiotherapy equipment lead times:Linear accelerator component shortages extend procurement cycles for hospital capital budgets.
- Biomarker testing fragmentation:Non-standardized PD-L1 assay platforms create diagnostic friction that delays treatment initiation.
Strategic Opportunities
- Antibody-drug conjugate expansion:EGFR-targeting payloads offer differentiation in head and neck malignancies with limited targeted therapy options.
- Hypofractionation protocols:Compressed radiation schedules reduce total treatment duration and free linear accelerator capacity.
- China's NMPA reforms:Streamlined oncology drug approvals expand access for imported checkpoint inhibitors through localized trial requirements.
Industry Challenges
- Immuno-oncology talent scarcity:Specialized clinical trial design expertise for combination protocols remains concentrated at academic centers.
- Legacy linear accelerator integration:New software-defined radiotherapy systems require costly retrofitting of installed base hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Throat Cancer Market |
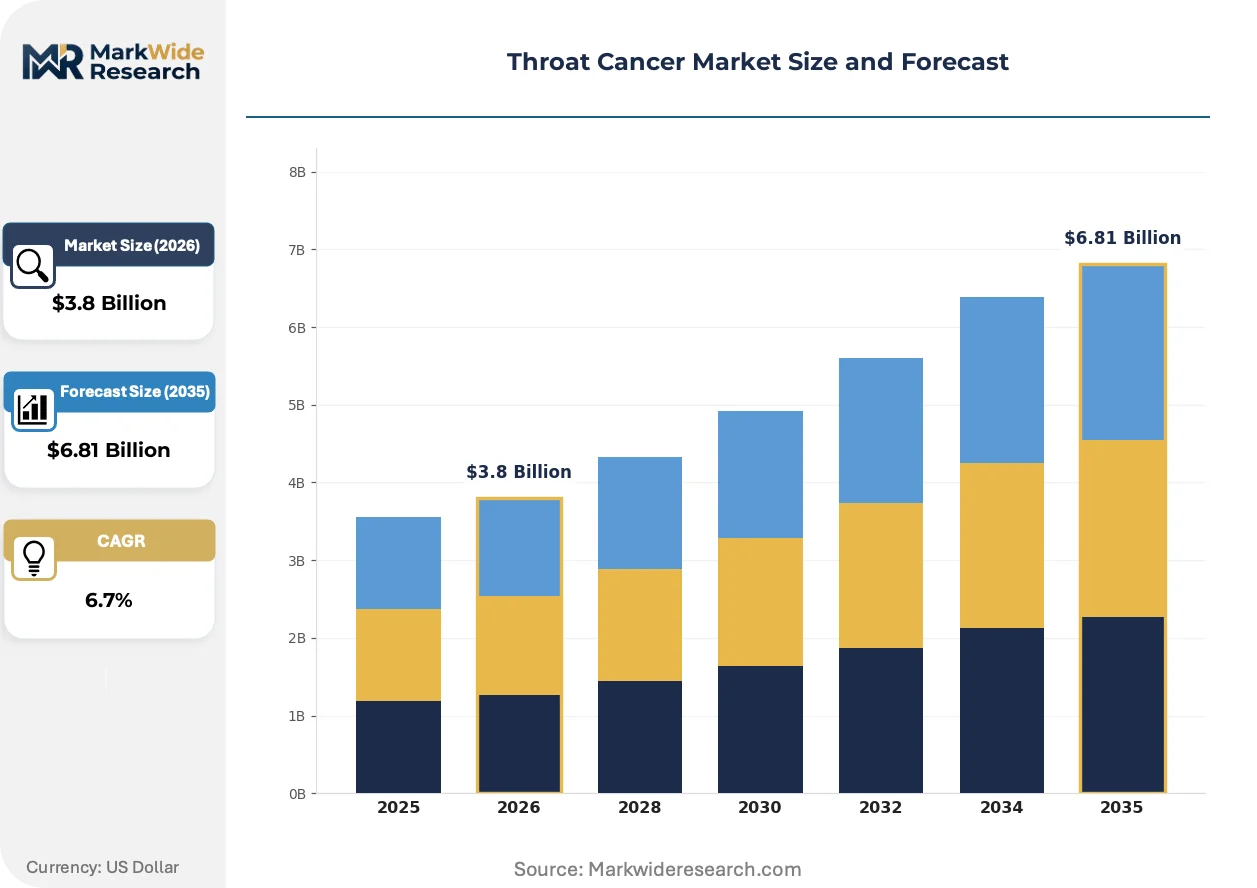
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Targeted Therapy End User: Hospitals, Oncology Clinics, Outpatient Facilities, Research Institutions Treatment Stage: Early-Stage, Locally Advanced, Metastatic, Recurrent Device Type: Radiotherapy Equipment, Imaging Systems, Surgical Instruments, Biopsy Devices |
| Companies Covered | Pfizer Inc, Roche Holding AG, Merck & Co Inc, AbbVie Inc, Sanofi SA, Bristol Myers Squibb, AstraZeneca plc, Novartis AG, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Throat Cancer Market Strategic Shifts
Artificial intelligence applications are penetrating diagnostic and treatment planning workflows, altering how pathology and radiation oncology teams collaborate. Three developments merit particular attention.
AI-powered contouring tools are decentralizing radiation treatment planning from centralized physics departments to satellite clinic networks. Community oncology practices adopt these platforms to retain patients locally rather than referring to academic centers. This compression of planning geography is reshaping how hospital systems configure their radiotherapy footprints.
The EU's Medical Device Regulation imposes stricter clinical evidence requirements on radiotherapy equipment and biopsy instrument manufacturers seeking CE marking. Device makers must now generate prospective clinical data rather than relying on equivalence arguments. Radiation therapy segments face the steepest compliance burden, prompting some manufacturers to prioritize FDA 510(k) pathways over European market entry.
Pathology laboratories are unbundling molecular testing from centralized reference models, with regional hospitals investing in in-house next-generation sequencing platforms. This fragmentation of diagnostic infrastructure reduces turnaround times for biomarker results. The United States exhibits the most pronounced shift, where integrated delivery networks negotiate direct platform purchases rather than relying on commercial laboratory contracts.
Throat Cancer Market Segmentation
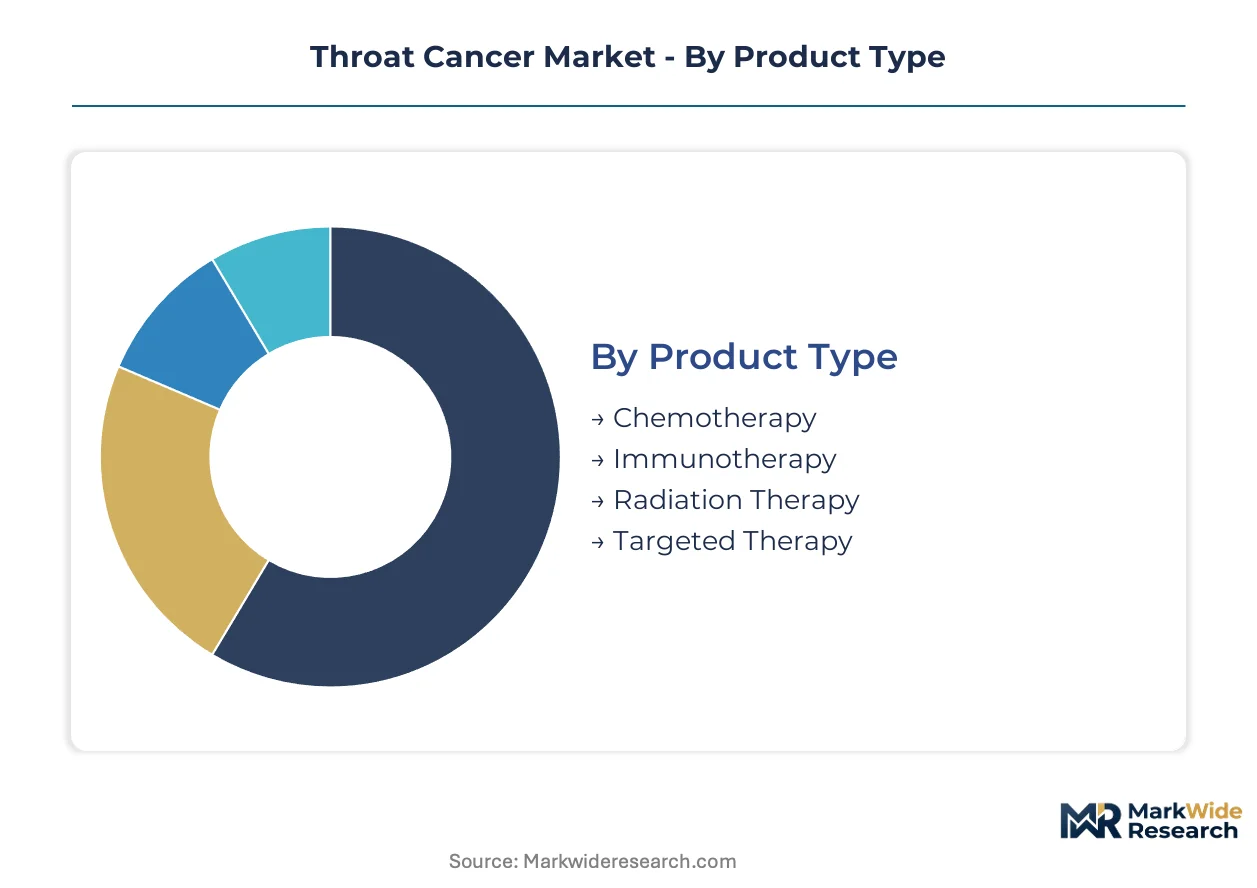
Treatment modality selection in throat cancer hinges on histology, staging, and biomarker status. Segmentation reveals how capital equipment replacement cycles intersect with pharmaceutical protocol shifts across care settings.
Product Type:
Upgrade and replacement cycles for radiotherapy hardware are compressing as immunotherapy protocols recalibrate treatment sequencing decisions across oncology departments.
- Immunotherapy:PD-1 and PD-L1 inhibitors dominate first-line recurrent or metastatic settings, displacing platinum-based chemotherapy. Academic medical centers in the United States anchor protocol standardization that diffuses through hospital network affiliations, though biomarker testing fragmentation creates diagnostic friction.
- Radiation Therapy:Linear accelerator replacement demand stabilizes around upgrade cycles tied to hypofractionation protocol adoption. Equipment vendors face extended procurement timelines from component shortages, forcing alignment with immunotherapy adoption curves rather than independent hardware refresh schedules.
- Chemotherapy:Platinum-based regimens retain adjuvant and concurrent roles despite immunotherapy encroachment, constrained by volatile precious metal pricing.
- Targeted Therapy:EGFR-directed agents serve niche populations with limited combination options, awaiting antibody-drug conjugate pipeline maturation.
Immunotherapy sits at the top of the volume ranking, with targeted therapy climbing the fastest as precision payloads advance through clinical development.
End User:
Cost tier stratification separates high-complexity tertiary centers from community-based delivery models.
- Hospitals:Integrated delivery networks concentrate capital-intensive radiotherapy infrastructure and multidisciplinary tumor boards. United States academic centers drive protocol innovation that cascades to affiliated community sites through telemedicine and shared physics support.
- Oncology Clinics:Freestanding infusion centers capture systemic therapy volume as checkpoint inhibitor administration shifts away from inpatient settings. AI-powered contouring tools enable these clinics to retain radiation planning locally rather than referring to hospital-based departments.
- Outpatient Facilities:Same-day surgical and diagnostic procedures concentrate in ambulatory surgery centers with lower reimbursement profiles.
- Research Institutions:Phase I trial units anchor combination protocol development, though immuno-oncology talent scarcity limits expansion.
Hospitals retain the dominant cost tier position, with oncology clinics expanding their volume capture most aggressively.
Treatment Stage:
Margin structure inverts across the curative-to-palliative spectrum, with early-stage categories pooling surgical margins against metastatic segments commanding pharmaceutical intensity.
- Early-Stage:Transoral robotic surgery and definitive radiotherapy achieve curative intent with shorter total treatment durations. Margin pools concentrate here from single-modality completion and reduced supportive care requirements.
- Locally Advanced:Concurrent chemoradiation remains standard despite toxicity profiles, with checkpoint inhibitor consolidation trials reshaping post-radiation sequencing.
- Metastatic:First-line immunotherapy drives per-patient pharmaceutical spend despite smaller addressable volumes, with platinum-refractory definitions expanding eligible populations.
- Recurrent:Salvage surgery and re-irradiation face technical limitations from prior treatment fields, funneling patients toward systemic options.
Early-stage treatment commands the deepest margin pool, with metastatic segments showing the steepest pharmaceutical spend trajectory.
Device Type:
Supply concentration for radiotherapy components is forcing procurement consolidation among hospital networks with sufficient capital scale.
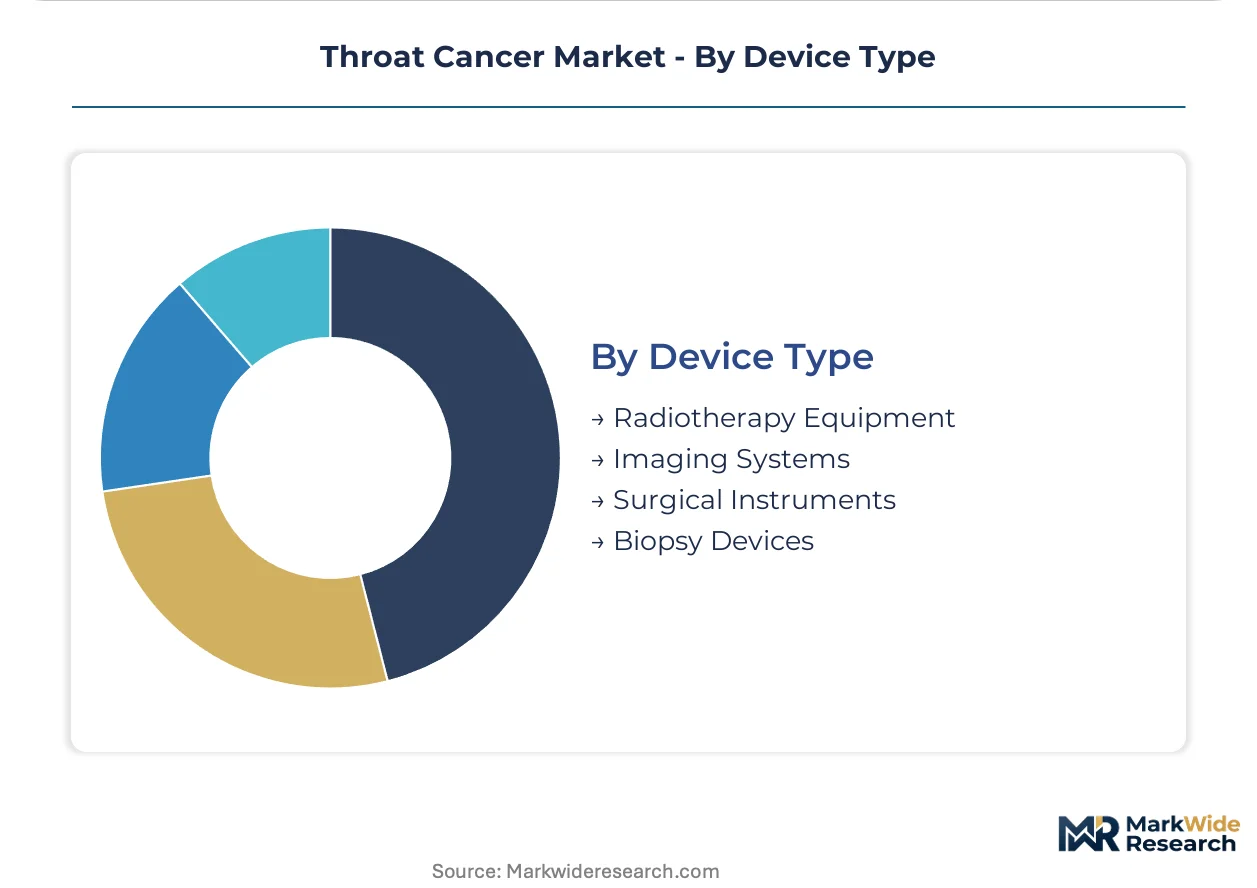
- Radiotherapy Equipment:Linear accelerator manufacturers face EU Medical Device Regulation compliance burdens requiring prospective clinical data rather than equivalence arguments. Some prioritize FDA 510(k) pathways over European market entry given documentation requirements.
- Imaging Systems:PET-CT and MRI platforms support radiation planning and response assessment, with software-defined upgrades extending hardware lifecycles.
- Surgical Instruments:Transoral robotic systems enable minimally invasive resections with reduced functional morbidity.
- Biopsy Devices:Image-guided sampling tools face similar MDR evidence requirements in Europe, with turnaround time pressure from regional pathology laboratory unbundling trends.
Radiotherapy equipment dominates capital allocation, with imaging systems gaining share fastest through software upgrade monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern oncology infrastructure traces its commercial roots to post-war pharmaceutical manufacturing clusters in the northeastern United States and the Basel-Rhine corridor, where centralized production of cytotoxic agents established distribution patterns that still shape therapeutic access today.
United States
Academic medical centers in Boston, Houston, and the Research Triangle anchor protocol innovation for head and neck malignancies. FDA breakthrough therapy designations compress review timelines for novel checkpoint inhibitors. The MD Anderson Cancer Center in Texas drives immuno-oncology trial enrollment that diffuses standardization through hospital network affiliations.
Germany
Heidelberg and Munich university hospitals concentrate radiation oncology expertise with heavy ion therapy capabilities. The EMA's priority medicines scheme accelerates access to biologics in recurrent settings. The Rhine-Main metropolitan region hosts integrated cancer centers that sequence immunotherapy with hypofractionated radiotherapy protocols.
China
NMPA oncology drug approval reforms expand patient access to imported checkpoint inhibitors through localized trial requirements. Shanghai and Beijing tertiary centers drive adoption of combination immunotherapy protocols. The Yangtze River Delta region concentrates proton therapy infrastructure investment from municipal health budgets.
Japan
PMDA sakigake designation pathways enable earlier patient access to novel agents in oropharyngeal indications. Tokyo and Osaka metropolitan areas concentrate multidisciplinary tumor board capacity. The Kansai region hosts specialized head and neck cancer centers that integrate transoral robotic surgery with adjuvant systemic protocols.
United Kingdom
NHS England's Cancer Drugs Fund provides managed access to immunotherapy combinations ahead of full NICE appraisal. London and Manchester academic centers anchor clinical trial networks for recurrent disease settings. The Oxford-Cambridge arc concentrates antibody-drug conjugate development partnerships between university spinouts and multinational manufacturers.
Throat Cancer Market Competitive Environment
Premium-margin players sit above commodity-margin players across the innovation-intensity spectrum, with biologics developers commanding pricing power against generic chemotherapy manufacturers. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with checkpoint inhibitor portfolios, mid-cap specialists in radiation therapy equipment, and regional distributors of cytotoxic agents. Consolidation pressure concentrates among linear accelerator manufacturers facing EU MDR compliance costs, while pharmaceutical segments see portfolio diversification through antibody-drug conjugate licensing.
Among integrated pharmaceutical developers, Merck & Co Inc, Bristol Myers Squibb, and AstraZeneca plc occupy positions defined by immuno-oncology infrastructure and combination protocol capabilities. These entities represent the archetype of checkpoint inhibitor commercialization, with each anchoring distinct strategic positioning within head and neck malignancy indications. Their market presence exemplifies how regulatory acceleration pathways and academic center relationships concentrate competitive advantage in this therapeutic area.
| Leading Market Players |
|---|
| Pfizer Inc |
| Roche Holding AG |
| Merck & Co Inc |
| AbbVie Inc |
| Sanofi SA |
| Bristol Myers Squibb |
| AstraZeneca plc |
| Novartis AG |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Backward integration into platinum group metal sourcing anchors both supply security and cost predictability for chemotherapy manufacturers, while checkpoint inhibitor developers leverage captive biologics manufacturing to defend premium positioning against biosimilar encroachment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates branded checkpoint inhibitors from platinum-based chemotherapies and emerging biosimilar alternatives. Price differentiation hinges on FDA breakthrough designation status and biomarker-driven label breadth, with academic medical centers showing lowest sensitivity due to formulary autonomy. Cost compression in the chemotherapy tier intensifies because of volatile precious metal input costs, while immunotherapy pricing holds firm on clinical data differentiation.
Supply Chain Analysis
Regional distribution centers for radiopharmaceuticals operate on hub-and-spoke patterns radiating from Indianapolis, Basel, and Shanghai production nodes. Supply concentrates in the United States, Switzerland, and China for active pharmaceutical ingredients, with linear accelerator components drawing from specialized German and Japanese machine tool suppliers. Single-source vulnerability in isotope production for diagnostic imaging creates structural risk. Distribution runs through hospital-owned specialty pharmacies and integrated delivery network central fill operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in throat cancer therapeutics rests on biomarker-driven patient segmentation that shifts volume toward premium immunotherapy protocols and away from commodity chemotherapy regimens.
For Market Incumbents: Deploy indication expansion strategies to defend checkpoint inhibitor positioning against dual immunotherapy combinations from Bristol Myers Squibb and AstraZeneca. Deepen relationships with MD Anderson and Memorial Sloan Kettering tumor boards to anchor protocol standardization. Invest in companion diagnostic co-development to lock in PD-L1 testing pathways and delay biosimilar entry. For New Entrants and Emerging Players: The mid-tier pricing gap between branded PD-1 inhibitors and generic platinum agents offers white-space for antibody-drug conjugate developers targeting EGFR-expressing populations with limited combination options. Focus initial penetration on community oncology clinics seeking to retain patients locally rather than referring to academic centers. Pursue FDA breakthrough therapy designation to compress development timelines and command formulary access. For Investors and Strategic Acquirers: Roll-up economics work for regional radiotherapy equipment service providers because hospital networks face extended procurement cycles and prefer outsourced maintenance to capital deployment. Long-term viability favors platforms with software-defined upgrade pathways over hardware-dependent installed bases. Monitor NMPA approval velocity for imported checkpoint inhibitors as inflection indicator for China market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA accelerated review compresses time-to-market for novel biologics in recurrent settings. |
| Companion Diagnostic Co-Development | PD-L1 assay platform integration locks in treatment initiation pathways and biomarker-driven reimbursement. |
| Hypofractionation Protocol Adoption | Compressed radiation schedules free linear accelerator capacity and reduce total treatment duration. |
| Regional Distribution Center Expansion | Hub-and-spoke radiopharmaceutical logistics reduce turnaround times for time-sensitive isotope delivery. |
| Academic Medical Center Partnership | MD Anderson and Sloan Kettering relationships anchor protocol standardization across hospital network affiliations. |
Study Parameters
Multiple input streams — oncology drug development executives, hospital formulary directors, radiation oncology department chairs, and payer access specialists — were reconciled with FDA filings, EMA submission documents, ClinicalTrials.gov records, and hospital procurement database extracts. Bottom-up patient volume modeling across treatment lines and top-down pharmaceutical revenue triangulation were cross-validated to establish market sizing boundaries.
Historical checkpoint inhibitor adoption curves were cross-referenced against expert panel inputs on immunotherapy sequencing evolution across the projection horizon. Segmentation dimensions modeled include treatment modality, disease stage, end-user facility type, and regional regulatory cluster. CAGRs were derived from slope analysis of analogous therapeutic class transitions, with specific weighting applied to biomarker testing penetration rates and radiotherapy equipment replacement cycles.
The model assumes a particular technology adoption path; alternative pathways for AI-powered radiation contouring would alter the outlook if community clinic deployment accelerates beyond academic center diffusion patterns. Forecasts reflect documented assumptions regarding FDA breakthrough designation velocity and EMA priority medicines scheme access expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Australia Cancer Treatment Market
Oncology
Internal Radiation Therapy Market
Oncology
Germany Radiotherapy Market
Oncology
Colorectal Cancer Screening Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Metastatic Breast Cancer Market
Oncology
AI in Oncology Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Global Cancer Treatment Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market