
 Automotive Tire Analytics Market | 2026-2036
Automotive Tire Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tire Analytics Market Outlook
Asset-light leasing models for connected tire fleets is tilting competitive dynamics toward technology-integrated suppliers rather than pure manufacturers. Bridgestone leverages its embedded sensor R&D pipeline to capture recurring software revenue streams. Michelin Group anchors its position through data analytics partnerships with commercial fleet operators across multiple continents. Continental AG competes by combining hardware durability with machine learning algorithms that predict tread wear patterns.
Automotive tire analytics encompasses sensor-based monitoring systems, cloud-connected telematics platforms, and algorithmic prediction engines that process pressure, temperature, tread depth, and road friction data to optimize tire performance and vehicle safety. These systems typically operate through embedded radio-frequency identification tags, accelerometer arrays, and edge computing modules that transmit encrypted telemetry to centralized fleet dashboards. Passenger vehicle applications dominate current deployment volumes, though fleet management represents the fastest-expanding addressable pool as logistics companies prioritize total cost of ownership reduction. Machine learning technology commands disproportionate investment attention because predictive algorithms extract measurable fuel savings from otherwise invisible tire degradation curves.
The EPA enforces rolling resistance standards that directly incentivize analytics-verified efficiency claims, while NHTSA mandates tire pressure monitoring systems that create baseline connectivity infrastructure for advanced analytics layering. ISO 28580 provides internationally recognized measurement protocols for rolling resistance, enabling cross-border product benchmarking that regulators reference in procurement specifications. Stakeholders must weigh embedded sensor durability against aftermarket retrofit economics when allocating capital across OEM and independent service channels.
Market Dynamics
Machine learning algorithms now extract fuel savings from tire degradation curves that fleet operators previously ignored, compressing payback periods for sensor-integrated systems and forcing capital reallocation toward predictive platforms.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated greenhouse gases push tire manufacturers toward sensor-integrated designs that verify low-rolling-resistance claims through real-time telemetry.
- Commercial fleet prioritization of total cost of ownership:Logistics operators deploy tire analytics to cut fuel expenditure and extend asset replacement cycles.
- Embedded RFID and accelerometer arrays:Hardware cost curves enable edge computing modules that transmit encrypted pressure and temperature data to centralized dashboards.
Market Restraints
- Semiconductor supply concentration:Sensor chip fabrication bottlenecks in East Asia create procurement delays for tire-embedded telemetry hardware.
- Aftermarket retrofit economics:Labor-intensive installation of connectivity modules on existing fleets erodes return-on-investment calculations for smaller operators.
- Encrypted data transmission standards:ISO 28580 measurement protocols require compliance investments that independent service channels struggle to absorb.
Strategic Opportunities
- Underpenetrated passenger vehicle aftermarket:Individual car owners in Germany represent untapped demand for tread-wear prediction subscriptions.
- Convergence of tire analytics with autonomous vehicle perception stacks:Road friction data feeds directly into braking algorithms, creating bundled procurement channels.
- India's PLI scheme for automotive components:Domestic manufacturing incentives attract sensor-integrated tire production for export markets.
Industry Challenges
- Cross-functional talent scarcity:Mechatronics engineers who combine rubber compound knowledge with cloud architecture skills command premium compensation.
- Legacy fleet management system integration:Telematics platforms from incumbent providers resist API connectivity with newer predictive analytics engines.
- Multi-jurisdiction certification timelines:NHTSA validation requirements for pressure monitoring system extensions differ from KBA testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tire Analytics Market |
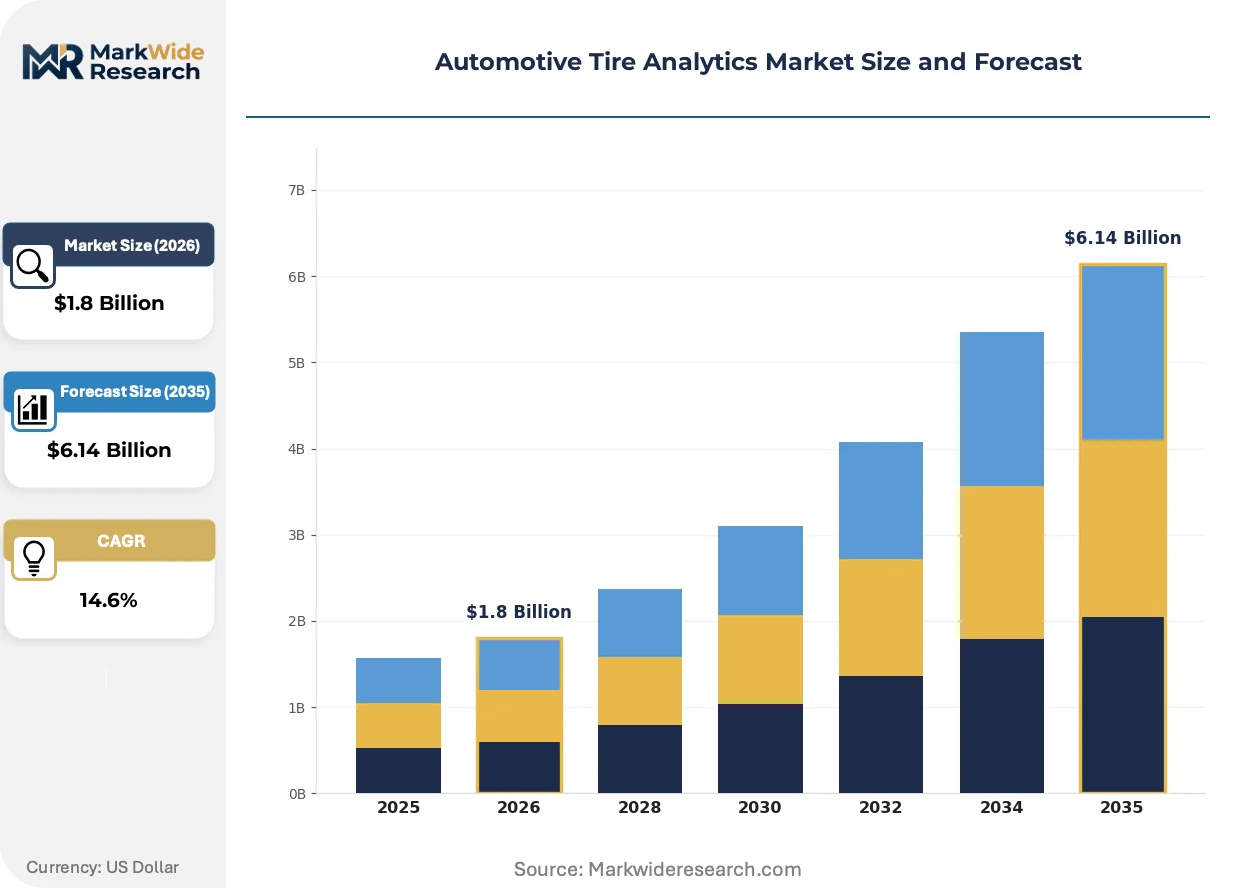
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Run Flat Tires, All-Season Tires, Performance Tires, Off-Road Tires Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Management Technology: Telematics, Embedded Sensors, Data Analytics, Machine Learning End User: OEMs, Aftermarket Providers, Tire Retailers, Logistics Companies |
| Companies Covered | Bridgestone, Michelin Group, Goodyear Tire & Rubber Company, Continental AG, Pirelli & C. SpA, Sumitomo Rubber Industries, Hankook Tire, Yokohama Rubber, Nexen Tire Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tire Analytics Market Strategic Shifts
Sensor-embedded tire architectures are migrating from premium OEM fitments toward mass-market penetration, reshaping how durability data flows through automotive value chains.
Predictive tread-wear algorithms are migrating from laboratory simulation environments to real-time edge computing modules mounted directly on wheel hubs. Commercial fleet operators in Germany adopt these systems fastest, drawn by documented fuel savings. The technology is migrating from hardware-differentiated competition toward software-recurring-revenue models that lock in multi-year service contracts.
REACH chemical disclosure requirements now extend to tire composition data, forcing manufacturers to document polymer formulations through digital product passports. Industrial consequence: supply chain visibility becomes a regulatory compliance function, not merely a procurement efficiency tool. Passenger tire producers targeting EU export markets invest in blockchain-anchored material traceability systems ahead of enforcement deadlines.
Leasing-based procurement for connected tire fleets displaces outright purchase models among logistics operators with asset-light balance sheet strategies. Traditional distribution through independent tire retailers loses volume to direct manufacturer-fleet partnerships. This shift concentrates most visibly in Germany, where automotive OEMs and tier-one suppliers anchor testing and deployment clusters for subscription-based tire performance guarantees.
Automotive Tire Analytics Market Segmentation
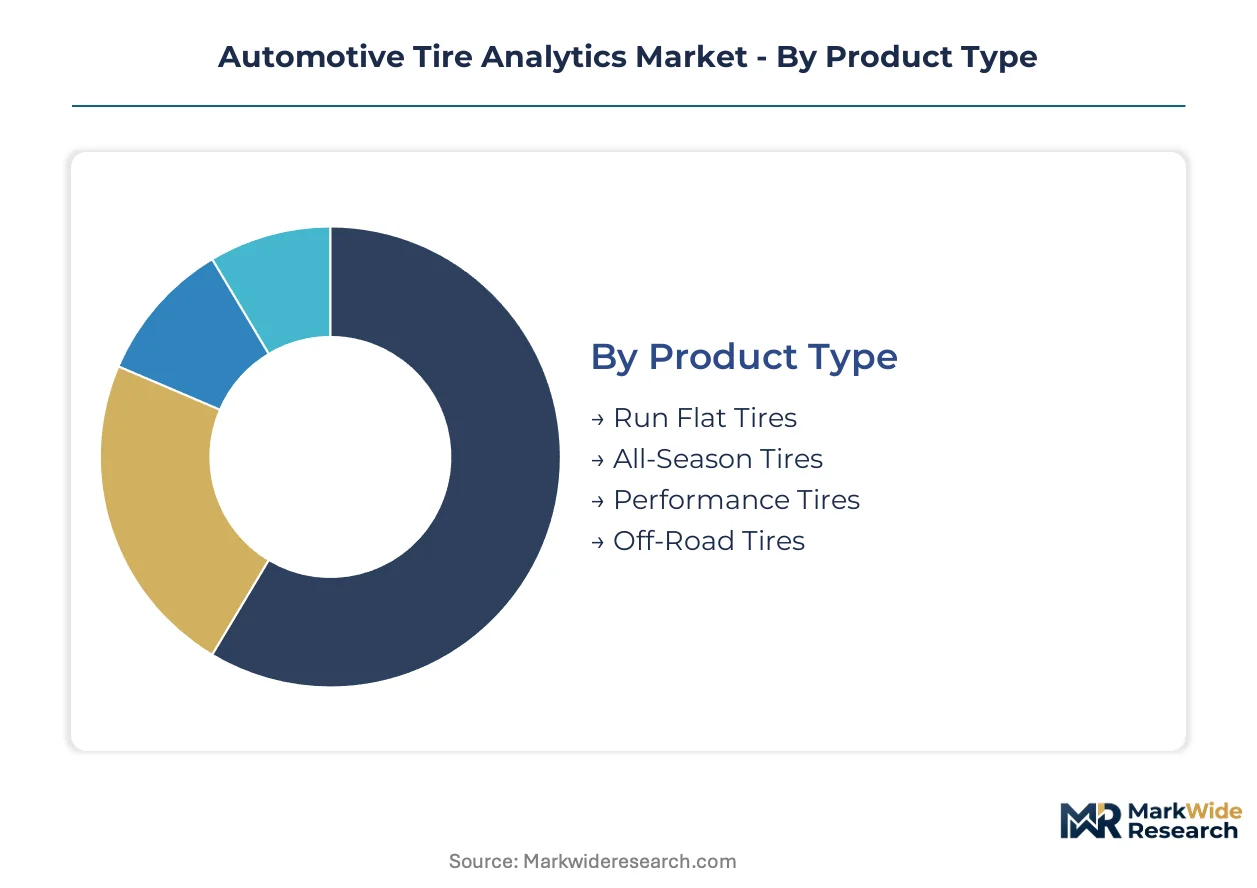
Tire analytics vendors must align product architecture with distinct service intensity requirements across tire categories. Each segment demands differentiated sensor durability specifications and data refresh frequencies that directly impact hardware economics and recurring revenue potential.
Product Type:
After-sales-service intensity varies sharply across tire architectures, with run-flat systems requiring continuous pressure verification and off-road tires demanding ruggedized telemetry modules.
- Run Flat Tires:Self-supporting sidewall constructions integrate pressure-monitoring circuits that transmit real-time structural integrity data. German luxury OEMs specify these systems for executive sedans where roadside service avoidance commands premium pricing.
- All-Season Tires:Tread compound variability across temperature ranges necessitates frequent elasticity telemetry. Fleet operators in temperate climates standardize on these variants to simplify inventory and reduce seasonal changeover labor.
- Performance Tires:Track-day applications drive demand for thermal mapping sensors that capture heat buildup during aggressive cornering.
- Off-Road Tires:Reinforced casings accommodate embedded accelerometers that detect rock impact events and terrain roughness indices.
All-season configurations hold the largest share; momentum sits with run-flat architectures as autonomous vehicle platforms eliminate spare tire provisions.
Application:
Volume concentration and margin profiles diverge meaningfully across vehicle classes, with commercial deployments amortizing sensor costs over higher utilization rates.
- Commercial Vehicles:Heavy-duty trucks operate telematics platforms that correlate tire pressure deviations with immediate fuel consumption penalties. Long-haul operators in Germany document payback periods under eighteen months from predictive replacement scheduling.
- Fleet Management:Asset-light logistics providers subscribe to tire-performance-as-a-service models that transfer capital expenditure to operating budgets. Multi-year contracts bundle hardware, connectivity, and algorithmic maintenance into per-kilometer pricing.
- Passenger Vehicles:Individual owners access tread-wear predictions through mobile applications linked to aftermarket sensor retrofits.
- Two-Wheelers:Motorcycle fleets in urban delivery segments adopt lightweight pressure monitors with Bluetooth Low Energy transmission protocols.
Commercial vehicles hold the largest share; fleet management is expanding most quickly as subscription business models displace outright tire procurement.
Technology:
Customer sophistication and integration depth separate technology tiers, with enterprise buyers demanding edge-computing capabilities that standalone telematics cannot satisfy.
- Machine Learning:Predictive algorithms trained on degradation curves from millions of tire-kilometers identify failure modes invisible to threshold-based monitoring. These systems command annual software license fees that exceed hardware depreciation schedules.
- Embedded Sensors:RFID tags and MEMS accelerometers molded into tire carcasses during vulcanization create factory-integrated data streams. OEM fitments leverage these architectures to validate warranty claims and optimize replacement timing.
- Data Analytics:Cloud platforms aggregate anonymized fleet data to benchmark performance across operating conditions and tire brands.
- Telematics:Vehicle-integrated gateways relay tire-derived telemetry alongside engine and chassis parameters to centralized fleet dashboards.
Embedded sensors hold the largest share; machine learning is gaining share fastest as fuel price volatility intensifies demand for predictive efficiency optimization.
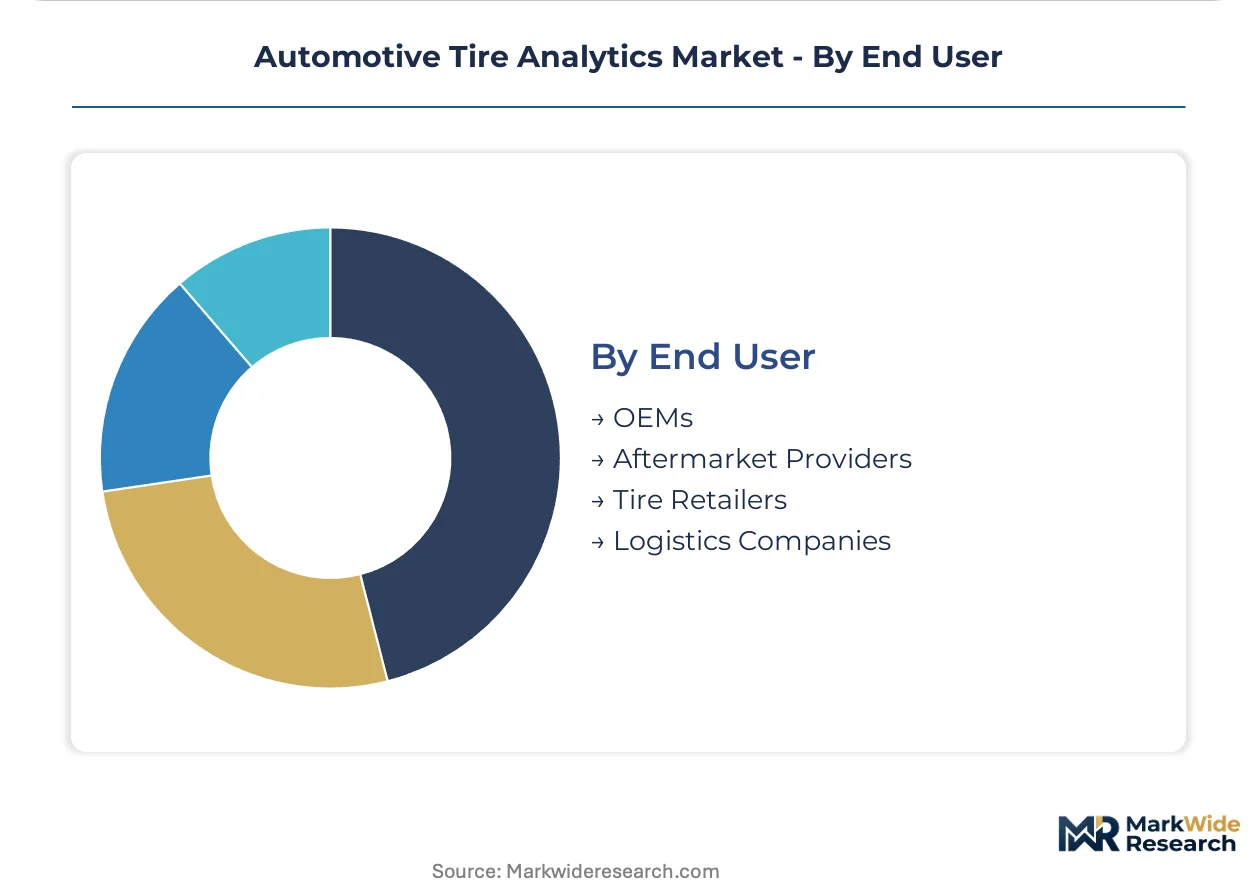
End User:
Procurement authority and technical integration capabilities fragment the buyer landscape, with OEMs specifying embedded architectures that aftermarket channels struggle to replicate.
- OEMs:Vehicle manufacturers mandate sensor-integrated tires as standard equipment on electrified platforms where range sensitivity amplifies rolling resistance concerns. Factory calibration protocols ensure seamless integration with onboard energy management systems.
- Logistics Companies:Asset operators with captive maintenance facilities deploy aftermarket retrofit kits to existing fleets, prioritizing total cost of ownership over upfront capital constraints.
- Aftermarket Providers:Independent service chains install connectivity modules during routine replacement cycles, capturing recurring data subscription revenue.
- Tire Retailers:Point-of-sale networks bundle tread-monitoring applications with replacement purchases to differentiate commoditized product offerings.
OEMs hold the largest share; logistics companies are climbing the fastest as fleet electrification synchronizes tire and battery lifecycle management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany extracts pricing premiums from embedded sensor specifications that US fleet operators resist at equivalent volume scales. This asymmetry reflects divergent regulatory enforcement intensity and OEM integration depth across Atlantic markets.
Germany
KBA testing protocols validate predictive tread-wear algorithms for commercial deployment, creating certification bottlenecks that filter out undercapitalized entrants. The EU F-Gas Regulation mandates real-time rolling resistance verification through sensor-integrated architectures. Stuttgart and Munich anchor OEM-tier-one supplier clusters where Michelin Group and Continental AG operate embedded R&D facilities.
United States
EPA rolling resistance standards incentivize analytics-verified efficiency claims among long-haul operators seeking fuel tax advantages. NHTSA tire pressure monitoring mandates establish baseline connectivity infrastructure for advanced analytics layering. Detroit-area automotive headquarters concentrate fleet procurement authority, though sensor-integrated tire adoption lags German penetration rates by approximately three years.
China
Domestic logistics operators prioritize total cost of ownership reduction through predictive replacement scheduling across high-utilization truck fleets. MIIT smart vehicle guidelines encourage tire-telemetry integration with national connected-car data standards. Yangtze River Delta manufacturing zones host sensor module fabrication facilities serving both domestic OEMs and export markets.
Japan
METI carbon neutrality roadmaps pressure tire manufacturers toward low-rolling-resistance designs verified through continuous telemetry. JIS standards provide measurement protocols that domestic OEMs reference in procurement specifications. Nagoya-area automotive supplier networks test edge-computing wheel hub modules for integration with autonomous vehicle perception stacks.
India
Commercial fleet electrification synchronizes tire and battery lifecycle management demands among logistics operators with captive maintenance facilities. PLI scheme incentives for automotive components attract sensor-integrated tire production for Middle East and African export markets. Tamil Nadu and Gujarat manufacturing corridors concentrate domestic tire production capacity with embedded telemetry capability.
Automotive Tire Analytics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and algorithmic engines to branded assemblers. The vendor base stratifies across three tiers: multinational tire manufacturers with captive software divisions, independent telematics platform providers, and specialized sensor fabricators. Two strategic archetypes dominate competitive positioning—vertically integrated manufacturers capturing recurring service revenue, and technology licensors supplying white-label analytics engines. Consolidation pressure concentrates through OEM exclusive supply agreements and multi-year fleet service contracts that lock out secondary entrants.
Within the vertically integrated tier, Bridgestone, Michelin Group, and Continental AG occupy positions that exemplify divergent technology-commercialization strategies. Bridgestone represents the embedded sensor R&D pathway, with organizational structures designed to internalize hardware-software development cycles. Michelin Group anchors partnership-based deployment across commercial fleet networks spanning multiple continents. Continental AG sits within the durability-algorithm convergence archetype, combining manufacturing scale with machine learning integration. These three entities collectively demonstrate how sensor-integrated tire architectures migrate competitive differentiation from compound chemistry toward predictive platform ownership.
| Leading Market Players |
|---|
| Bridgestone |
| Michelin Group |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli & C. SpA |
| Sumitomo Rubber Industries |
| Hankook Tire |
| Yokohama Rubber |
| Nexen Tire Corporation |
| Others |
Value Chain & Pricing Dynamics
East Asian semiconductor fabrication concentration for MEMS accelerometers and RFID sensor modules anchors margin capture at the tire-embedded hardware tier, while downstream value pools concentrate with fleet operators and OEMs who monetize predictive analytics subscriptions.
Pricing Analysis
Configured-to-order sensor-integrated tire systems command 40-60% premiums over standard aftermarket replacement pricing, reflecting hardware-software bundling and calibration complexity. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified embedded architectures from retrofit telematics kits and basic pressure monitoring hardware. Cost compression in the aftermarket retrofit tier is intensifying because labor-intensive installation erodes return-on-investment for smaller fleet operators. Logistics companies with asset-light strategies exhibit lowest price sensitivity, while independent owner-operators resist subscription models without documented fuel savings guarantees.
Supply Chain Analysis
Contract manufacturing for tire-embedded sensor modules concentrates with Bosch Sensortec, Infineon Technologies, and STMicroelectronics foundries serving automotive qualification requirements. Germany, China, and South Korea anchor sensor module production capacity, while natural rubber sourcing draws from Thailand and Indonesia plantations. Semiconductor fabrication bottlenecks in East Asia create single-source vulnerability for telemetry hardware procurement. Distribution runs through OEM captive supply chains for factory-fitments, and direct manufacturer-fleet partnerships for subscription-based aftermarket deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tire analytics platforms face substitution pressure from autonomous vehicle-native perception systems that bypass tire-derived friction data, forcing incumbents to defend their sensor-telemetry value proposition against integrated vehicle intelligence architectures.
For Market Incumbents: Harden algorithmic differentiation through deeper integration with OEM energy management systems, particularly for electrified platforms where battery range sensitivity amplifies rolling resistance optimization value. Lock in multi-year fleet service contracts before autonomous braking systems mature to reduce reliance on tire-derived road friction inputs. Prioritize backward integration into edge-computing wheel hub module production to capture hardware margins currently flowing to Tier 2 electronics suppliers. For New Entrants and Emerging Players: Mid-market commercial fleets in India and Southeast Asia represent the most penetrable entry point, where PLI scheme incentives and domestic manufacturing capacity lower sensor-integrated tire production costs. Aftermarket retrofit channels for passenger vehicles in Germany offer white-space opportunity given underpenetrated individual owner demand for tread-wear prediction subscriptions. Partner with existing telematics platform providers rather than building proprietary connectivity infrastructure to accelerate time-to-revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telematics platform specialists that lack captive tire manufacturing but hold established fleet customer relationships and API integration depth. Long-term viability hinges on predictive algorithm accuracy differentiation rather than hardware cost curves, favoring targets with proprietary training datasets spanning diverse operating conditions. Watch for inflection signals in autonomous vehicle braking system procurement specifications that omit tire-derived friction data requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Tire Platform Standardization | Bridgestone and Continental AG drive OEM adoption through unified telemetry protocols that reduce fleet integration costs. |
| Predictive Algorithm Licensing Agreements | Michelin Group monetizes tread-wear intelligence across third-party tire brands, expanding addressable data revenue pools. |
| Backward Integration into MEMS Fabrication | Captive sensor production insulates margin structures from East Asian semiconductor supply bottlenecks and tariff exposure. |
| Direct Fleet Partnership Expansion | Manufacturer-to-operator contracts displace independent retailer channels, concentrating pricing power and recurring revenue visibility. |
| Autonomous Vehicle Perception Stack Integration | Road friction data feeds into braking algorithms, creating bundled procurement channels that lock out standalone analytics vendors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distribution executives; and secondary validation against customs trade records, vehicle production databases, SEC filings from listed tire manufacturers, and KBA type-approval documentation. Bottom-up modeling of sensor-embedded tire unit economics triangulated against top-down market sizing from fleet telematics platform deployments.
Forecast inputs span tire category segmentation by product architecture, application intensity by vehicle utilization rates, technology tier by edge-computing capability, and end-user procurement authority across OEM captive and aftermarket channels. CAGRs derive from algorithmic fuel savings documentation, regulatory compliance cost trajectories, and hardware cost curve projections throughout the forecast period. Industry-specific inputs include EU F-Gas Regulation enforcement timelines and NHTSA pressure monitoring system extension pathways.
Macroeconomic conditions sit as an overlay; deviation in commercial fleet capital expenditure cycles, semiconductor pricing volatility, or electrification subsidy durability would shift the trajectory. Forecasts reflect documented assumptions on sensor durability lifecycles and algorithmic accuracy improvement curves. Quarterly review of autonomous vehicle braking system specification releases and OEM exclusive supply agreement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
EV Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Global Automotive Tire Socks Market