
 Tire Carousel Market | 2026-2036
Tire Carousel Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Carousel Market Outlook
German engineering clusters is repositioning the competitive map for tire carousel manufacturing, with specialized producers scaling output to serve automotive logistics hubs across Central Europe. Hanel Storage Systems leverages its vertical lift module heritage to anchor premium automated carousel lines for tire retailers. Kardex Group sustains technology leadership through intensive R&D in shuttle-based retrieval systems. SSI SCHAEFER competes on manufacturing scale, operating integrated production facilities that supply distribution centers across multiple continents.
A tire carousel is a motorized vertical storage system designed to rotate tire inventory on a chain-driven carrier mechanism, typically accommodating passenger, light truck, and commercial tire diameters from 15 to 24 inches with load ratings up to 150 kg per position. Its primary purpose is to maximize storage density in confined workshop or warehouse footprints while reducing manual handling injuries and retrieval cycle times. Automated carousel systems now command the strongest margin pools as tire retailers prioritize labor reduction and throughput velocity. Mobile carousel configurations represent the fastest-expanding segment among fleet management operators requiring flexible deployment across multiple service bays. Manual carousel demand remains structurally mature in smaller automotive workshops where capital constraints limit equipment upgrades.
OSHA workplace safety regulations in the United States mandate ergonomic load-handling thresholds that directly expand demand for powered tire carousels in commercial service environments. CE marking under the EU Machinery Directive and REACH material compliance standards govern market access for European installations, filtering out non-compliant imports. Stakeholders must monitor evolving battery-electric vehicle tire specifications, as heavier EV tire weights and altered wear patterns will reshape capacity requirements and carousel engineering standards.
Market Dynamics
The tire carousel sector faces intensifying pressure from OSHA ergonomic mandates and EU Machinery Directive compliance deadlines, forcing automotive workshops to accelerate replacement of manual storage with powered vertical systems before penalty enforcement windows tighten.
Growth Catalysts
- OSHA Ergonomic Thresholds:United States workplace safety regulators mandate load-handling limits that powered carousels satisfy, compelling commercial tire service bays to automate storage retrieval and eliminate manual lifting injuries.
- Battery-Electric Vehicle Fleet Expansion:Heavier EV tire specifications require reinforced carousel load ratings, creating replacement demand among fleet operators upgrading capacity for 20+ kilogram tire assemblies.
- German Automotive Service Density:The concentrated network of independent workshops and dealer service centers across Bavaria and Baden-Württemberg sustains premium equipment procurement volumes for automated storage systems.
Market Restraints
- Steel and Aluminum Input Volatility:Carousel frame construction depends on structural steel and aluminum extrusion pricing, exposing manufacturers to commodity swings that compress equipment margins or delay customer quotations.
- Electronics Supply Concentration:Motor drives and programmable logic controllers source predominantly from East Asian semiconductor fabricators, concentrating vulnerability to regional logistics disruptions and export licensing delays.
- Manual Carousel Substitution Persistence:Smaller independent workshops with capital constraints continue operating hand-cranked vertical storage, delaying addressable market expansion in the long-tail service segment.
Strategic Opportunities
- India Automotive Aftermarket Formalization:Organized tire retail chains in Mumbai, Delhi, and Bangalore are adopting standardized workshop equipment, opening penetration channels for automated carousel distributors.
- EU Green Deal Circular Economy Mandates:Tire collection and recycling targets incentivize reverse-logistics carousels for seasonal storage and retreadable inventory management at collection depots.
- RFID-Enabled Inventory Convergence:Integration of radio-frequency identification tracking with carousel control systems enables real-time tire location and automated reorder triggers for integrated supply chains.
Industry Challenges
- Certification Timeline Compression:CE marking under the EU Machinery Directive requires extensive third-party testing and documentation, extending product launch cycles for new carousel configurations by six to nine months.
- Legacy Workshop Integration Complexity:Existing automotive service management software platforms lack standardized application programming interfaces, forcing custom middleware development for carousel control integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Carousel Market |
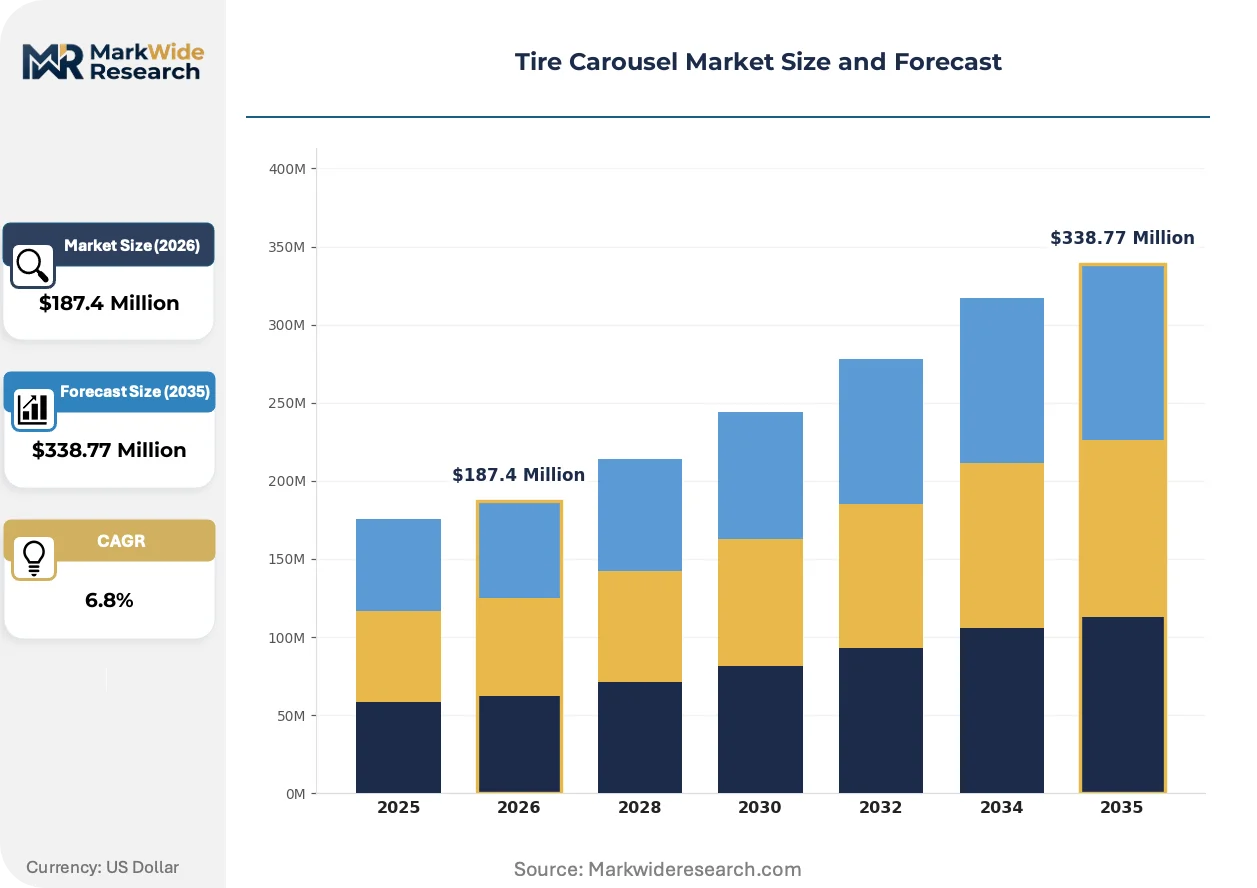
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Carousel, Automated Carousel, Mobile Carousel, Vertical Carousel End User: Automotive Workshops, Tire Retailers, Fleet Management, Distribution Centers Installation: On-Site, Off-Site, Temporary Installation, Permanent Installation Capacity: Low Capacity, Medium Capacity, High Capacity, Customized Capacity |
| Companies Covered | Hanel Storage Systems, Modula Inc., Ferretto Group, Stanley Black & Decker (Lista), Dexion, Vindir (Vertical Storage Solutions), Kardex Group, SSI SCHAEFER, SencorpWhite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Carousel Market Strategic Shifts
Automation architectures are converging with predictive maintenance platforms and lightweight material science, compressing equipment footprints while extending operational uptime guarantees for high-throughput tire distribution centers.
Shuttle-based vertical lift modules are expanding into tire-specific configurations, replacing traditional chain-driven carousels in facilities requiring multi-deep storage and variable tire diameter accommodation. Tier-one automotive logistics providers in Stuttgart and Wolfsburg are piloting these systems for just-in-sequence tire delivery to assembly plants. The technology is expanding into adjacent commercial vehicle segments previously served by static racking, compressing facility space requirements by forty percent versus conventional storage.
REACH material compliance standards are tightening restrictions on lubricants and surface coatings used in carousel mechanisms, forcing manufacturers to reformulate bearing greases and powder-coat chemistries. The regulation's industrial consequence is accelerated supplier qualification timelines and elevated testing costs for European market entry. Tire retailers in France and Italy are responding by consolidating procurement around pre-certified equipment lines to avoid customs detention risks.
Fleet management operators are consolidating tire procurement through integrated service contracts that bundle storage equipment with seasonal changeover labor, displacing transactional equipment sales. Large commercial transport fleets in Texas and California are demanding outcome-based pricing tied to tire availability uptime rather than capital expenditure. This model compresses vendor margins while locking in multi-year maintenance revenue streams for carousel service providers.
Tire Carousel Market Segmentation
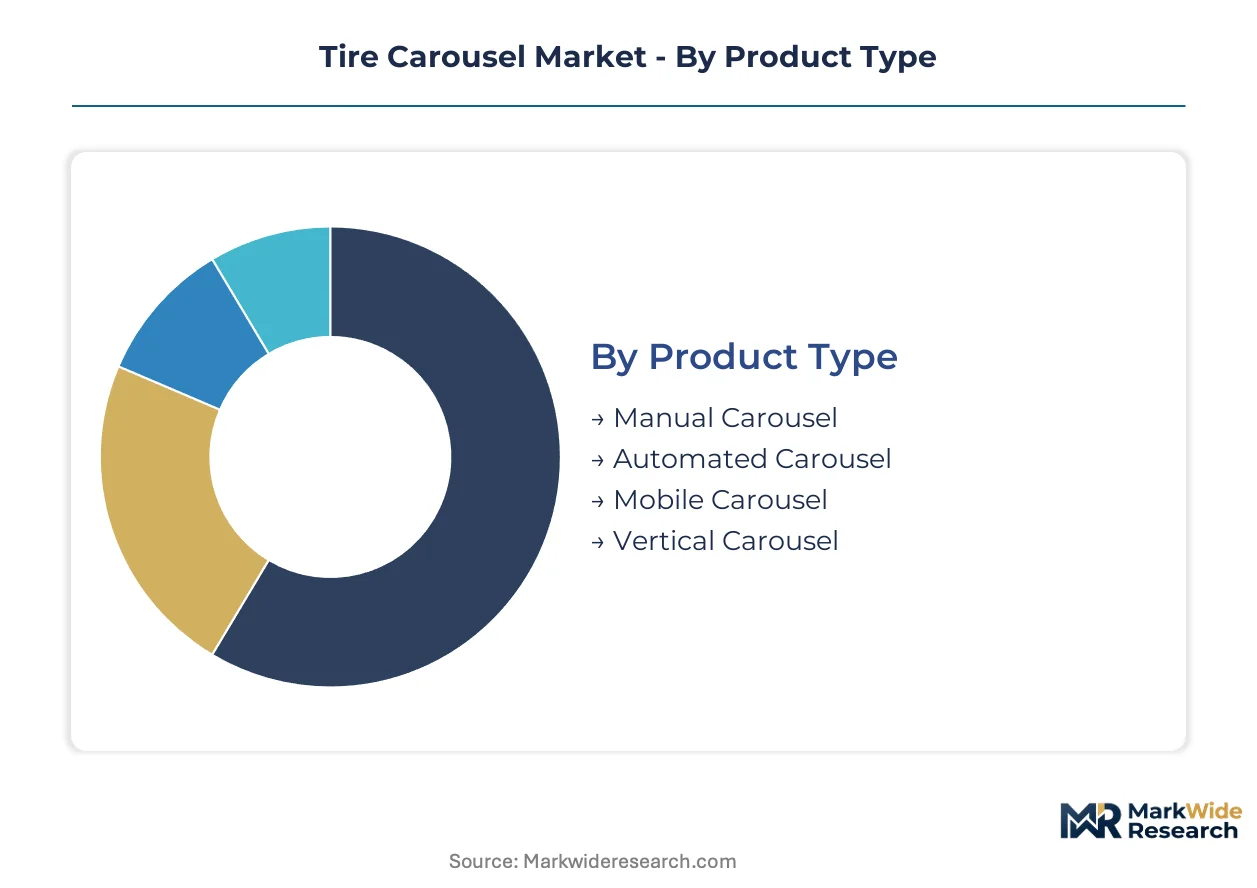
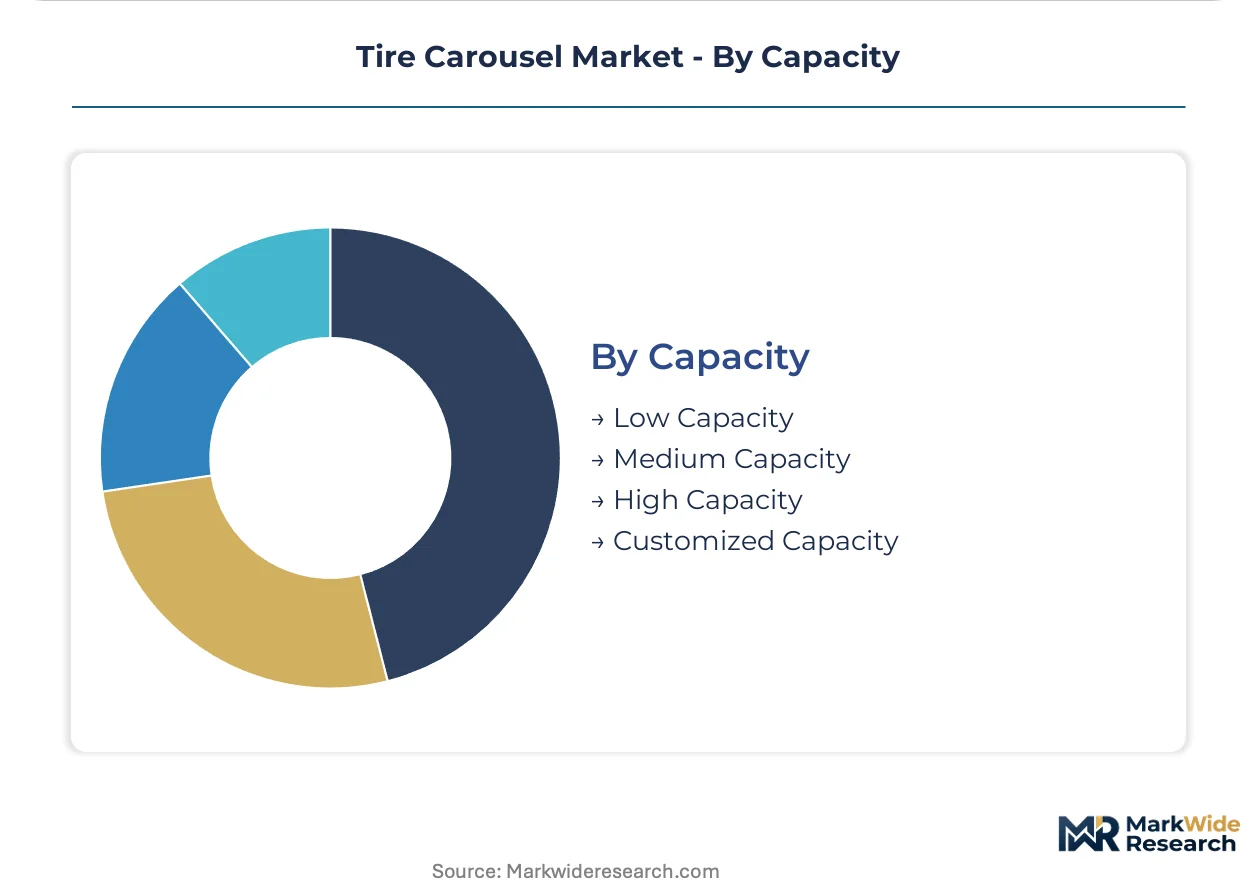
Tire carousel segmentation reveals how equipment specifications align with distinct operational economics across automotive service environments. Product configuration, end-user scale, installation constraints, and load capacity requirements collectively determine procurement patterns and vendor positioning strategies.
Product Type:
Motorization level and structural mobility define the core technology axis, separating capital-intensive automated systems from flexible manual alternatives.
- Automated Carousel:Chain-driven motorized systems with programmable logic controllers deliver sub-30-second retrieval cycles for high-throughput tire retailers. German automotive logistics hubs in Stuttgart and Wolfsburg prioritize these configurations for just-in-sequence assembly plant supply, driven by labor cost compression targets and OSHA ergonomic compliance mandates.
- Mobile Carousel:Castor-mounted frames enable bay-to-bay repositioning across multi-station workshop layouts. Fleet management operators in Texas and California are expanding adoption fastest, requiring flexible deployment for seasonal tire changeover operations without fixed infrastructure investment.
- Manual Carousel:Hand-cranked vertical storage serves capital-constrained independent workshops where powered systems remain economically inaccessible.
- Vertical Carousel:Space-optimized designs maximize cubic utilization in urban distribution centers with severe footprint restrictions.
Automated carousel leads on scale; mobile carousel leads on momentum.
End User:
Customer procurement sophistication spans from standardized workshop equipment to integrated fleet service contracts with outcome-based pricing.
- Tire Retailers:Organized chains in Mumbai, Delhi, and Bangalore are formalizing equipment standards, creating consolidated procurement channels for automated storage vendors. Their demand concentrates on systems with RFID inventory convergence for real-time stock visibility.
- Distribution Centers:Multi-regional tire distributors operate the largest single-facility deployments, requiring shuttle-based vertical lift modules for variable diameter accommodation across passenger, light truck, and commercial segments.
- Automotive Workshops:Independent service bays across Bavaria and Baden-Württemberg sustain premium equipment volumes, though smaller operators delay upgrades due to capital constraints.
- Fleet Management:Commercial transport operators are shifting from equipment purchase to bundled service contracts tying payments to tire availability uptime.
Distribution centers dominate absolute volume; tire retailers in emerging markets show steepest expansion trajectory.
Installation:
Deployment flexibility determines capital commitment timing and facility modification requirements.
- Permanent Installation:Anchored systems with reinforced foundations support maximum load ratings for high-capacity commercial tire operations.
- On-Site:Manufacturer-facilitated assembly at customer locations reduces shipping constraints for oversized carousel frames.
- Off-Site:Pre-assembled modular units enable rapid commissioning for temporary seasonal storage requirements.
- Temporary Installation:Leased configurations serve construction and agriculture fleets with cyclical tire demand patterns.
Permanent installation anchors revenue stability; temporary installation captures event-driven demand spikes.
Capacity:
Load rating specifications are recalibrating around battery-electric vehicle tire weights exceeding 20 kilograms per assembly.
- High Capacity:Reinforced frames with 150 kg per position ratings serve commercial vehicle and EV fleet operators upgrading from legacy specifications.
- Customized Capacity:Engineering-to-order configurations address non-standard tire diameters in specialty agricultural and mining applications.
- Medium Capacity:Standard passenger and light truck segments dominate unit volume in mainstream automotive retail.
- Low Capacity:Entry-level specifications serve motorcycle and small equipment tire storage with minimal structural requirements.
High capacity commands premium pricing; customized capacity captures margin through engineering differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between jurisdictions with divergent compliance costs is redirecting tire carousel manufacturing investment. Producers are relocating assembly capacity toward markets with streamlined machinery certification pathways while maintaining sales presence in high-standard enforcement zones.
United States
OSHA ergonomic mandates and warehouse automation subsidies drive commercial fleet procurement. The Infrastructure Investment and Jobs Act channels federal funding toward logistics modernization in Texas and California. Dallas-Fort Worth distribution clusters are deploying mobile carousel configurations for seasonal tire operations.
Germany
CE marking under the EU Machinery Directive and REACH material standards filter market access for imported equipment. KBA vehicle safety oversight extends to workshop equipment specifications. Stuttgart and Wolfsburg automotive logistics hubs are piloting shuttle-based vertical lift modules for just-in-sequence tire delivery.
China
GB standards for industrial machinery and dual carbon goals reshape domestic manufacturing requirements. MIIT industrial upgrading programs subsidize smart warehouse equipment adoption. Yangtze River Delta logistics operators are integrating automated storage with e-commerce tire distribution networks.
India
BIS machinery safety certification and PLI scheme incentives for automotive components expand formal equipment procurement. Organized tire retail chains in Mumbai, Delhi, and Bangalore are standardizing workshop infrastructure. Maharashtra automotive service clusters are accelerating carousel adoption as foreign franchise networks enter.
Japan
METI energy efficiency standards and JIS industrial machinery specifications govern equipment imports. Aging workforce demographics intensify demand for ergonomic load-handling solutions. Kansai region commercial vehicle fleet operators are retrofitting existing facilities with motorized vertical storage systems.
Tire Carousel Market Competitive Environment
German producers anchor the premium automated systems tier; Italian and Swiss specialists hold mid-market positions through engineering differentiation. The vendor base stratifies across three tiers: integrated conglomerates with multi-continent manufacturing footprints, regional machinery houses with vertical lift module heritage, and emerging Asian fabricators competing on cost-engineered configurations. Dominant competitive moves include backward integration into motor drive and control system production, plus strategic partnerships with tire retail chains for bundled service contracts.
Within the integrated systems tier, Hanel Storage Systems and Kardex Group exemplify archetypes anchored in vertical storage heritage. SSI SCHAEFER occupies a position representing manufacturing scale across multiple continents. These three entities collectively illustrate how European engineering lineage converges with global distribution reach in automated carousel supply.
| Leading Market Players |
|---|
| Hanel Storage Systems |
| Modula Inc. |
| Ferretto Group |
| Stanley Black & Decker (Lista) |
| Dexion |
| Vindir (Vertical Storage Solutions) |
| Kardex Group |
| SSI SCHAEFER |
| SencorpWhite |
| Others |
Value Chain & Pricing Dynamics
Family-owned German engineering specialists anchor premium automated carousel production, concentrating supply discipline around CE-certified manufacturing clusters while pricing power flows from captive control over motor-drive assembly and vertical lift module heritage.
Pricing Analysis
Distributor margins compress pricing by twelve to eighteen percent before retailer markup, creating a three-tier pricing structure across premium CE-marked automated systems, mid-market mobile configurations, and economy manual carousels. Price differentiation hinges on OSHA compliance certification and after-sales service bundling. Cost compression in the manual tier is intensifying because steel input volatility forces fabricators to absorb commodity swings or lose fleet-operator volume tenders. Tire retailers in organized Indian chains show highest price sensitivity; German automotive logistics hubs show lowest sensitivity due to just-in-sequence uptime requirements.
Supply Chain Analysis
Freight costs from East Asian semiconductor fabricators to European assembly plants add seven to twelve percent to programmable logic controller landed costs, concentrating margin pressure on motor-drive sourcing. Manufacturing draws from Germany, Italy, and China for frame fabrication, control electronics, and precision machining respectively. Raw material dependencies rest on structural steel, aluminum extrusions, and rare-earth magnet motors. Single-source vulnerability concentrates in Taiwanese semiconductor fabricators supplying motor drives. Distribution runs through authorized equipment distributors serving automotive workshop networks and direct OEM supply contracts for tire retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in tire carousels rests on EV tire weight upgrades driving high-capacity system replacement cycles, while software-enabled predictive maintenance bundles capture recurring service revenue.
For Market Incumbents: Extend shuttle-based vertical lift module lines into tire-specific configurations before emerging Asian fabricators achieve CE marking compliance. Defend position by deepening backward integration into motor-drive production to offset East Asian semiconductor supply risk. Prioritize RFID-enabled inventory convergence R&D to lock tire retailer upgrade cycles. For New Entrants and Emerging Players: Launch via mobile carousel leasing models targeting Texas and California fleet operators seeking seasonal flexibility without capital commitment. White-space sits in temporary installation configurations for construction and agriculture cyclical demand. Target organized tire retail chains in Mumbai, Delhi, and Bangalore through BIS-certified economy automated lines with localized service partnerships. For Investors and Strategic Acquirers: Tier-one automotive logistics providers are the most active acquirer in this space, seeking captive tire storage equipment supply for just-in-sequence assembly plant integration. Long-term viability frames around EV fleet penetration sustaining high-capacity replacement demand. Watch for CE marking timeline compression signaling regulatory barrier elevation that favors pre-certified European incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Shuttle-Based Vertical Lift Module Expansion | Stuttgart and Wolfsburg logistics hubs pilot multi-deep storage for just-in-sequence tire delivery. |
| Backward Integration into Motor-Drive Production | Hanel and Kardex reduce semiconductor supply risk through captive control over programmable logic controllers. |
| RFID-Enabled Inventory Convergence | Real-time tire location tracking enables automated reorder triggers for integrated Mumbai retail chains. |
| Mobile Carousel Leasing Models | Texas fleet operators adopt outcome-based pricing tied to tire availability uptime rather than capital expenditure. |
| REACH-Compliant Material Reformulation | European manufacturers reformulate bearing greases to avoid customs detention under tightened coating standards. |
Study Parameters
Bottom-up automotive service modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with tire retailer procurement directors, automotive workshop maintenance managers, fleet operator logistics heads, and carousel distributor sales executives combined with secondary validation against customs trade data, OSHA enforcement records, CE marking registration databases, and automotive production statistics. Triangulation across stakeholder inputs and documentary sources grounds segmentation-level estimates.
Input-output matrices map motorization tier, end-user scale, installation type, and load capacity specifications against regional regulatory clusters. CAGRs derive from equipment replacement cycle analysis and EV fleet penetration assumptions across the projection horizon. Industry-specific forecast inputs include battery-electric vehicle tire weight specifications and EU Machinery Directive compliance deadline schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor export licensing disruptions or steel tariff escalations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Racing Tires Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Wheel Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Tire & Wheel Cleaners Market