
 Europe Two-Wheeler Tire Market | 2026-2036
Europe Two-Wheeler Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Two-Wheeler Tire Market Foresight
Skilled rubber compound formulation expertise is bifurcating the competitive landscape, separating legacy manufacturers with in-house polymer labs from assemblers dependent on external feedstock. Michelin SCA leverages its captive R&D infrastructure in Clermont-Ferrand to sustain premium positioning across radial motorcycle tires. Continental AG anchors its volume strategy through OEM supply contracts with German and Austrian motorcycle producers. Pirelli & C S p A dominates the high-performance segment through motorsport-derived compound technology.
Europe two-wheeler tires are pneumatic structures comprising vulcanized rubber layers, textile or steel cord reinforcement belts, and tread compounds engineered for grip, wear resistance, and rolling efficiency across varying road surfaces and weather conditions. Motorcycle tires command the largest product type share, reflecting sustained internal combustion and electric powertrain demand across Mediterranean member states. Scooter tires represent the fastest-growing product type, driven by electrified urban mobility fleets in France, Spain, and the Netherlands. By end user, aftermarket providers capture margin-rich replacement cycles, while OEMs lock in multi-year supply agreements with volume producers.
REACH regulation and the EU F-Gas framework constrain petrochemical-derived rubber inputs, compelling reformulation toward sustainable alternatives. ECHA chemical restrictions on polycyclic aromatic hydrocarbons in tire oils directly elevate compliance costs for compounders serving the European market. CE marking requirements under the EU type-approval system govern noise, wet grip, and rolling resistance thresholds for tires sold across member states. Stakeholders must monitor the interplay between bio-based material mandates and performance parity benchmarks as regulatory timelines compress development cycles.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are compressing compound development cycles, forcing manufacturers to reformulate rubber matrices around bio-based feedstocks while maintaining wet-grip and wear-performance parity against petrochemical benchmarks.
Growth Catalysts
- Electrified urban mobility fleets:Last-mile delivery operators in France, Spain, and the Netherlands are accelerating scooter tire replacement frequency as electric vehicle utilization rates climb.
- REACH-compliant bio-rubber formulations:ECHA restrictions on polycyclic aromatic hydrocarbons in tire oils are creating first-mover advantages for compounders with captive polymer laboratories.
- Mediterranean motorcycle culture:Sustained internal combustion and electric powertrain demand across Italy sustains premium radial tire consumption and aftermarket service intensity.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply concentration exposes European compounders to weather-driven feedstock cost swings and currency fluctuation.
- CE marking compliance burden:EU type-approval testing for noise, wet grip, and rolling resistance thresholds extends product launch timelines by 8-14 months.
- Petrochemical formulation lock-in:Legacy production lines optimized for synthetic rubber matrices require capital-intensive retooling to process bio-based alternatives at scale.
Strategic Opportunities
- Netherlands circular tire recovery:Extended producer responsibility frameworks under Dutch national implementation of EU waste directives create closed-loop material recovery revenue streams.
- Motorsport-derived compound licensing:Premium manufacturers can monetize track-validated silica-silane technologies through tiered licensing to mid-market assemblers.
- Direct-to-fleet digital distribution:Urban delivery operators are bypassing traditional wholesale channels through integrated tire management platforms with predictive wear monitoring.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in bio-based vulcanization chemistry is concentrating among legacy manufacturers, constraining mid-tier compounder R&D throughput.
- Dual certification complexity:Parallel ECE R75 motorcycle tire approval and UN ECE R117 commercial vehicle standards create testing redundancy for crossover scooter-motorcycle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Two-Wheeler Tire Market |
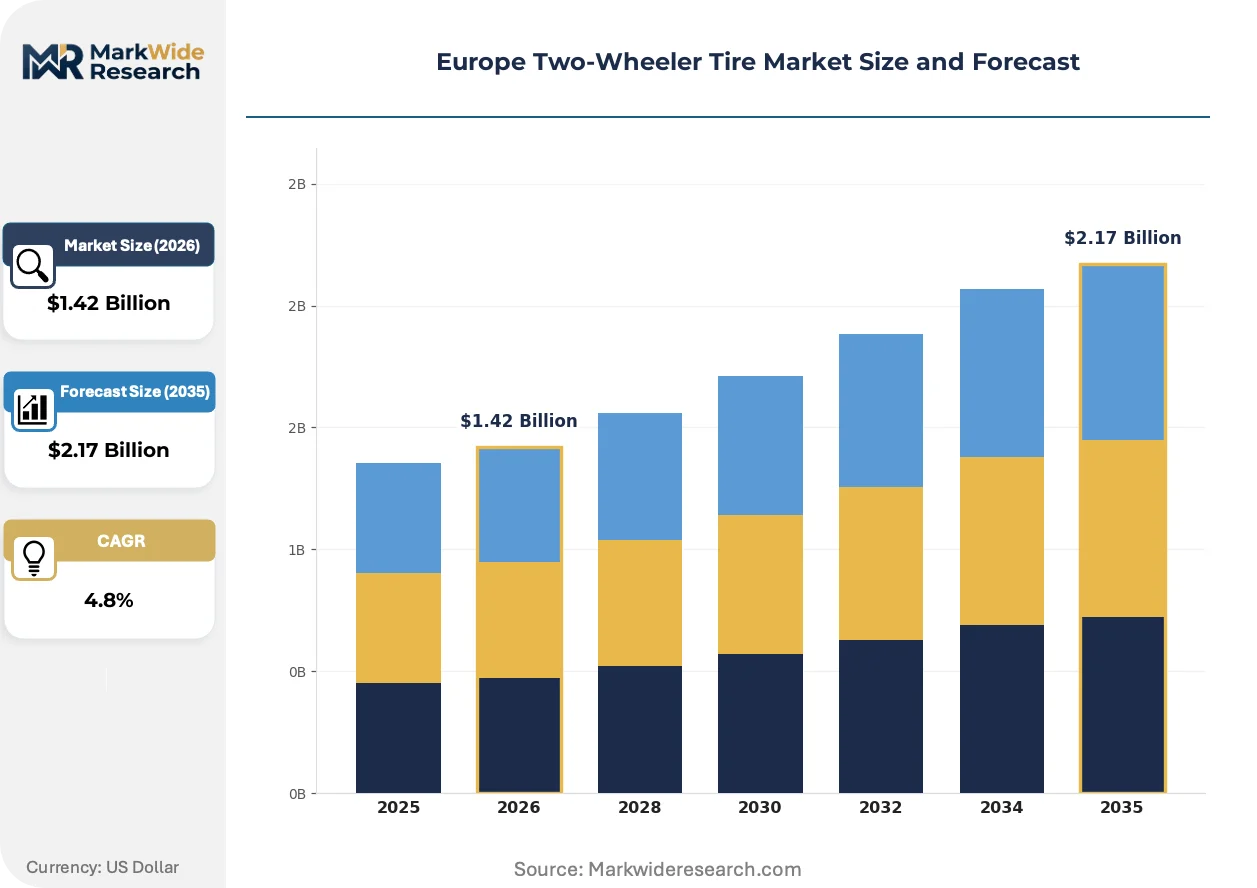
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorcycle Tires, Scooter Tires, Moped Tires, Bicycle Tires End User: OEMs, Aftermarket Providers, Retailers, Distributors Material: Rubber, Synthetic, Natural, Composite Size: Small, Medium, Large, Extra Large |
| Companies Covered | Michelin SCA, Continental AG, Pirelli & C S p A, Bridgestone Corporation, Goodyear Tire & Rubber Company, Apollo Tires Ltd, Dunlop, Nokian Tyres plc, Hankook Tire & Technology Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Two-Wheeler Tire Market Shifts & Advancements
Bio-based rubber matrices and predictive fleet management systems are restructuring how tires are formulated, sold, and replaced across European two-wheeler applications.
Silica-silane tread compounds derived from rice husk ash are displacing conventional carbon black reinforcement in premium scooter and motorcycle tires. Urban delivery fleet operators are specifying these formulations for reduced rolling resistance and extended service intervals. The shift is compressing replacement revenue per vehicle while expanding total addressable fleet volume through improved asset utilization.
ECHA's 2025 enforcement timeline for polycyclic aromatic hydrocarbon limits in extender oils is accelerating compound reformulation programs. Tire manufacturers serving the European market must validate alternative bio-circular feedstocks through accelerated aging protocols. High-performance radial segments face the steepest compliance cost escalation due to stricter wet-grip coefficient maintenance requirements.
Subscription-based tire lifecycle management is displacing transactional wholesale purchasing among electrified fleet operators. Integrated pressure monitoring and tread depth telemetry enable predictive replacement scheduling, unbundling the traditional dealer service relationship. France and the Netherlands exhibit the highest penetration of fleet-managed tire contracts, driven by dense urban delivery route optimization.
Europe Two-Wheeler Tire Market Segmentation
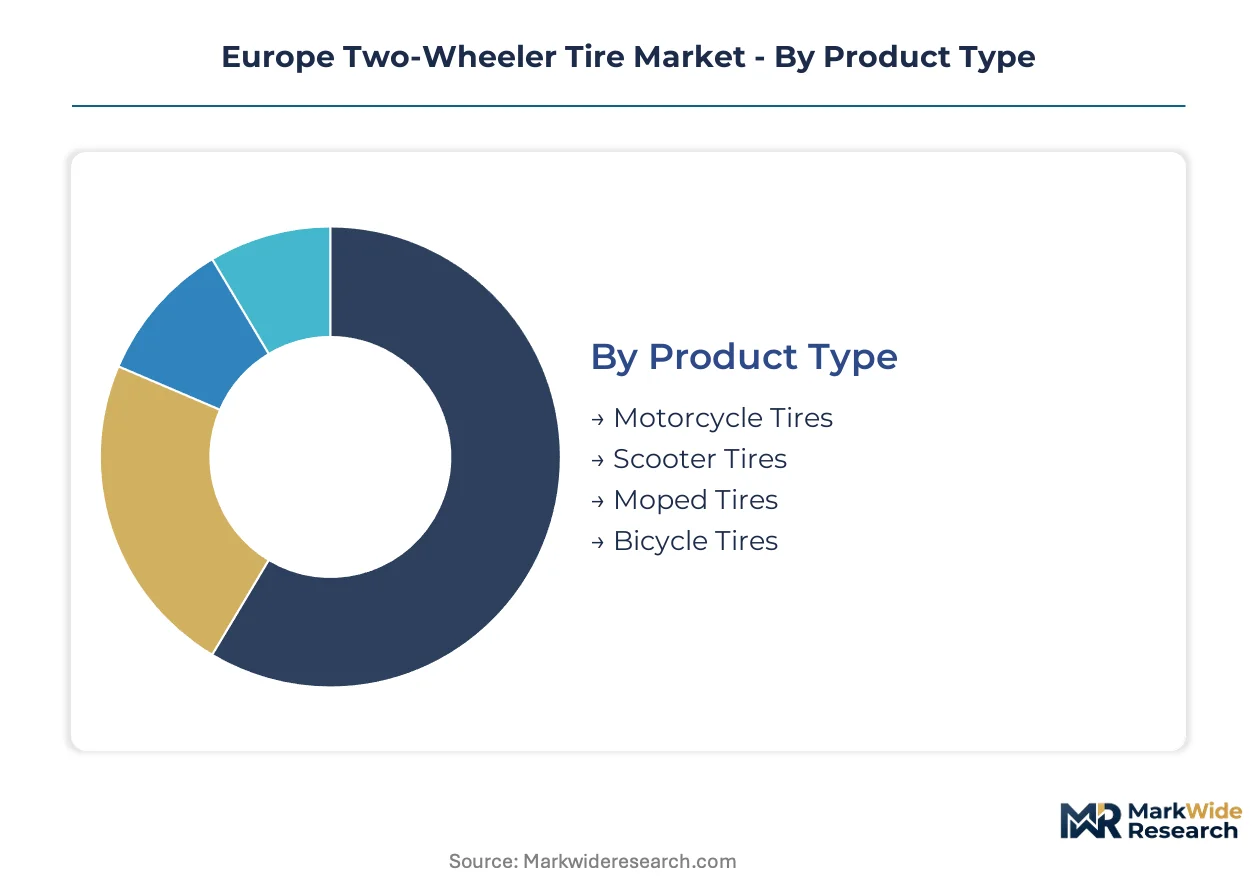
Segmentation in the Europe Two-Wheeler Tire Market reveals how margin pools concentrate around electrification trends, regulatory compliance tiers, and replacement cycle intensity. Understanding these fault lines helps stakeholders allocate R&D and distribution resources across diverging growth trajectories.
Product Type:
Motorcycle tires command the deepest margin pools through premium radial constructions and motorsport-derived compound technologies, while electrified urban mobility is redistributing volume toward scooter platforms.
- Motorcycle Tires:Radial and bias-ply constructions reinforced with steel or aramid belts serve internal combustion and electric powertrains across Mediterranean member states. Italy sustains premium consumption through sustained enthusiast culture and high-performance aftermarket service intensity.
- Scooter Tires:Smaller-diameter pneumatic structures optimized for urban stop-start duty cycles and curb abrasion resistance. France, Spain, and the Netherlands concentrate replacement demand as electrified last-mile delivery fleets accelerate utilization rates.
- Moped Tires:Lightweight bias-ply designs balancing rolling efficiency with puncture resistance for sub-50cc urban commuters. German and Austrian OEM supply contracts anchor volume production for this segment.
- Bicycle Tires:Clincher and tubeless variants spanning road, gravel, and e-bike applications with compound formulations tuned for rolling resistance versus grip trade-offs.
The dominant share belongs to Motorcycle Tires, while Scooter Tires is closing the gap fastest.
End User:
Channel economics diverge sharply between long-cycle OEM supply agreements and high-margin aftermarket replacement services.
- OEMs:Motorcycle and scooter manufacturers in Germany, Austria, and Italy lock in multi-year supply contracts with volume tire producers. CE marking and EU type-approval compliance requirements extend onboarding timelines but secure predictable offtake.
- Aftermarket Providers:Independent dealers and service networks capture replacement cycles with premium positioning on radial motorcycle tires and rapid-turn scooter fitments. Mediterranean markets sustain the highest service revenue per vehicle.
- Retailers:Mass-market channels including automotive parts chains and hypermarkets stock economy-tier bias-ply tires for price-sensitive moped and bicycle segments.
- Distributors:Regional wholesalers bridge manufacturers to fragmented dealer networks across Eastern European markets with lower direct penetration.
Aftermarket Providers hold the margin advantage, though OEMs deliver superior volume stability.
Material:
REACH chemical restrictions and the EU Green Deal are compressing formulation economics around bio-based feedstock validation.
- Rubber:Vulcanized natural and synthetic polymer matrices forming the base elastomer compound. ECHA polycyclic aromatic hydrocarbon limits in extender oils are elevating compliance costs for conventional formulations.
- Synthetic:Petrochemical-derived styrene-butadiene and polybutadiene rubbers optimized for wear resistance and wet-grip performance in premium radial constructions.
- Natural:Hevea brasiliensis latex sourced predominantly from Southeast Asian plantations. Weather-driven supply volatility exposes European compounders to feedstock cost swings.
- Composite:Silica-silane reinforced tread compounds and rice husk ash derivatives displacing carbon black in rolling resistance-optimized scooter and e-bike tires.
Rubber maintains volume leadership, while Composite formulations are expanding most quickly on regulatory tailwinds.
Size:
Rim diameter and section width specifications segment production tooling and inventory requirements across manufacturing footprints.
- Small:10-12 inch rim diameters for urban scooters and mopeds with narrow section profiles optimized for maneuverability and curb clearance.
- Medium:13-16 inch configurations spanning commuter motorcycles and maxi-scooters with balanced load capacity and handling characteristics.
- Large:17-18 inch sport-touring and naked bike fitments requiring advanced radial construction and multi-compound tread zones.
- Extra Large:19+ inch adventure and cruiser motorcycle tires with reinforced sidewalls for heavy-load touring applications.
Medium sizes dominate unit economics, while Small sizes are gaining share fastest on electrified fleet penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy consumes premium radial motorcycle tires at rates unmatched elsewhere in Europe, while Dutch and Spanish fleet operators burn through scooter rubber on electrified last-mile routes. This consumption-mix differential splits regional demand between enthusiast-driven premium replacement and utilitarian fleet turnover.
Italy
Motorcycle culture sustains Europe's densest premium tire aftermarket, with radial constructions dominating sport-touring and naked bike fitments. REACH chemical restrictions on polycyclic aromatic hydrocarbons compound reformulation costs for suppliers serving this high-performance segment. The Po Valley industrial corridor hosts compound blending facilities optimized for motorsport-derived silica-silane technologies.
Germany
OEM supply contracts with Bavarian and Baden-Württemberg motorcycle manufacturers anchor volume production of bias-ply and radial constructions. CE marking requirements under EU type-approval extend product launch timelines for compounders seeking multi-year supply agreements. The Stuttgart-Munich manufacturing axis concentrates R&D investment in rolling resistance optimization for electric powertrains.
France
Electrified urban delivery fleets in Paris and Lyon accelerate scooter tire replacement cycles beyond traditional consumer patterns. ECHA enforcement timelines for 2025 are compressing development schedules for bio-based rubber formulations serving this high-utilization segment. The Île-de-France logistics cluster drives specification of predictive tire management platforms among fleet operators.
Netherlands
Extended producer responsibility frameworks under Dutch national implementation of EU waste directives create closed-loop material recovery revenue streams. Circular tire recovery infrastructure in the Randstad metropolitan region enables compounders to source regenerated rubber feedstocks. Amsterdam and Rotterdam fleet operators specify subscription-based lifecycle management contracts unbundling traditional dealer relationships.
Spain
Barcelona and Madrid delivery cooperatives electrify scooter fleets at rates matching French and Dutch urban centers. EU Green Deal bio-based material mandates intersect with Mediterranean climate conditions demanding wet-grip performance parity against petrochemical benchmarks. The Catalonia automotive supplier ecosystem is adapting compounding lines for rice husk ash-derived silica reinforcement.
Europe Two-Wheeler Tire Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive polymer laboratories separating compound formulation experts from feedstock-dependent assemblers. The upper tier commands premium positioning through motorsport-validated technologies and multi-year OEM supply agreements. Mid-market specialists compete on rapid-turn scooter fitments and fleet service contracts. Dominant competitive moves include strategic partnerships for bio-based feedstock security and technology licensing of silica-silane compound systems.
Within the integrated leader tier, Michelin SCA and Continental AG exemplify divergent strategic postures: the Clermont-Ferrand-based entity anchors premium radial development through captive R&D infrastructure, while the Hanover-structured manufacturer locks in volume stability through German and Austrian OEM supply relationships. Pirelli & C S p A occupies a distinctive position in high-performance segments, with Milan-originated motorsport expertise translating into compound technology differentiation.
| Leading Market Players |
|---|
| Michelin SCA |
| Continental AG |
| Pirelli & C S p A |
| Bridgestone Corporation |
| Goodyear Tire & Rubber Company |
| Apollo Tires Ltd |
| Dunlop |
| Nokian Tyres plc |
| Hankook Tire & Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
CE marking requirements under the EU type-approval system gate both supply qualification and price differentiation across European two-wheeler tire markets. Manufacturers must clear noise, wet grip, and rolling resistance thresholds before market entry, while certification tier separates premium radial constructions from economy bias-ply alternatives.
Pricing Analysis
Long-term offtake contracts dominate OEM supply relationships with German and Austrian motorcycle producers, locking in volume stability at compressed margins. Three-tier pricing structure across premium, standard, and economy levels reflects radial construction complexity, motorsport-derived compound pedigree, and aftermarket service bundling. Pricing pressure stems from REACH-compliant bio-rubber reformulation costs elevating compound production expenses. Fleet operators exhibit lowest price sensitivity through subscription-based lifecycle contracts, while independent retailers serving moped segments face acute margin compression.
Supply Chain Analysis
Thailand and Indonesia anchor natural rubber feedstock production for European compounders, with synthetic styrene-butadiene rubber concentrated in German and Belgian petrochemical corridors. Vulcanized rubber matrices draw from Southeast Asian latex plantations, steel cord reinforcement from Luxembourg and Belgian mills, and silica-silane additives from specialized chemical producers. Single-source vulnerability concentrates in Hevea brasiliensis supply exposed to weather-driven harvest volatility. Distribution runs through regional wholesalers bridging manufacturers to fragmented dealer networks across Eastern European markets with lower direct penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based tire lifecycle management platforms are restructuring the Europe Two-Wheeler Tire Market toward ecosystem economics, unbundling traditional dealer relationships through predictive wear telemetry and integrated fleet service contracts.
For Market Incumbents: Secure captive polymer laboratory capacity to maintain formulation expertise as bio-based vulcanization chemistry concentrates among legacy manufacturers. Defend against mid-tier compounder encroachment by locking multi-year OEM supply agreements with electric powertrain producers in Germany and Austria. Channel control through direct-to-fleet digital distribution represents the critical defensive lever. For New Entrants and Emerging Players: Anchor in Netherlands circular tire recovery infrastructure under extended producer responsibility frameworks, where regenerated rubber feedstocks create closed-loop material recovery revenue streams. The most penetrable white space sits in predictive fleet management platforms for French and Dutch urban delivery operators. A software-first go-to-market angle unbundles traditional wholesale relationships through telemetry-enabled replacement scheduling. For Investors and Strategic Acquirers: ECHA's 2025 enforcement timeline for polycyclic aromatic hydrocarbon limits reshapes the acquisition landscape toward compounders with validated bio-circular feedstock programs. Long-term viability over a five-to-ten-year window favors targets with captive R&D infrastructure and motorsport-derived technology licensing portfolios. The signal to monitor is tiered licensing revenue from silica-silane compound systems to mid-market assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive supply of rice husk ash-derived silica reduces REACH compliance cost exposure for premium radial producers. |
| Direct-to-Fleet Digital Platform Launch | Amsterdam and Rotterdam operators bypass wholesalers through predictive tire management with integrated wear monitoring. |
| Motorsport Compound Technology Licensing | Milan-originated silica-silane expertise monetizes track-validated formulations through tiered agreements with mid-tier assemblers. |
| Circular Tire Recovery Infrastructure Buildout | Dutch national implementation of EU waste directives enables closed-loop material recovery revenue streams in the Randstad cluster. |
| Electric Powertrain OEM Supply Agreement | Stuttgart-Munich manufacturing axis locks in multi-year offtake for rolling resistance-optimized radial constructions. |
Research Methodology
Desk research of customs and trade data, ECHA regulatory filings, and EU type-approval documentation preceded structured interviews with tire compound R&D directors, fleet procurement managers at urban delivery operators, aftermarket dealer network heads, and OEM supply chain executives. Primary fieldwork across Clermont-Ferrand, Milan, Hanover, and Amsterdam manufacturing clusters combined with secondary validation from SEC filings of listed tire producers and ACC industry reports. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the European two-wheeler ecosystem.
Variance decomposition across product type, end-user channel, material formulation, and rim diameter specifications structured the analytical framework throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to electrified fleet penetration rates and replacement cycle compression patterns. Modeled inputs incorporated REACH compliance cost trajectories, natural rubber futures volatility indices, and urban delivery fleet utilization telemetry.
Material uncertainties — Southeast Asian supply disruptions, ECHA enforcement intensity variations, and electric powertrain adoption acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around bio-based formulation performance parity maintenance and circular recovery infrastructure scaling. Recalibration cycles align with material shifts in regulatory enforcement timelines and fleet electrification subsidies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Global Automotive Tire Socks Market