
 Smart Tire Market | 2026-2036
Smart Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Tire Market Analytics
The capital-intensity divergence between sensor-integrated manufacturing and conventional tire production is redrawing competitive boundaries in the smart tire sector. Bridgestone Corporation leverages its embedded sensor R&D pipeline to sustain technology leadership in pressure monitoring systems. Continental AG anchors its position through backward integration into semiconductor packaging for tire-mounted IoT modules.
Smart tires integrate microelectromechanical sensors, RFID tags, and Bluetooth-enabled transmitters directly into tire carcasses to relay real-time pressure, temperature, and tread-wear data to vehicle telematics units. Pressure monitoring systems currently dominate product type revenue, while IoT-enabled connectivity architectures represent the fastest-expanding technology segment as fleet telematics platforms standardize on over-the-air data ingestion. OEMs command the largest end-user value pool, though aftermarket providers are capturing margin growth through retrofit sensor kits for existing commercial vehicle parc.
NHTSA, ECHA under REACH frameworks, and China's MIIT collectively shape material safety, radio-frequency emission standards, and data governance requirements for smart tire deployments. The EU Green Deal's embedded carbon accounting rules are forcing manufacturers to document sensor supply chain emissions for CE marking eligibility. Stakeholders must monitor evolving cross-border data localization mandates that could fragment cloud-based tire analytics architectures.
Market Dynamics
The embedded sensor integration mandate from NHTSA and parallel EU Green Deal compliance requirements are forcing tire manufacturers to restructure production lines around semiconductor packaging capabilities, fundamentally altering capital allocation patterns across the supply chain.
Growth Catalysts
- Commercial Fleet Telematics:Logistics operators in China are deploying connected tire systems at scale to optimize fuel consumption and predictive maintenance schedules for heavy-duty vehicle parc.
- EU Green Deal Embedded Carbon Accounting:CE marking eligibility now requires documented sensor supply chain emissions, compelling manufacturers to upgrade traceability infrastructure.
- Bluetooth-Enabled Data Transmission:Low-energy wireless protocols are standardizing over-the-air tire analytics integration with fleet management platforms.
Market Restraints
- Semiconductor Packaging Concentration:Backward integration into tire-mounted IoT modules requires specialized cleanroom facilities concentrated in East Asian manufacturing clusters.
- RF Emission Compliance Costs:FCC certification for tire-integrated transmitters adds 12-18 month pre-market timelines and specialized testing expenditure.
- Legacy Fleet Retrofit Economics:Existing commercial vehicle parc lacks standardized OBD interfaces for aftermarket sensor kit integration.
Strategic Opportunities
- India Commercial Vehicle Aftermarket:Domestic logistics fleet expansion under PLI scheme incentives creates first-mover positioning for retrofit sensor providers.
- Predictive Tread-Wear Analytics:Machine learning models trained on pressure-temperature-tread data streams enable usage-based tire subscription models.
- Cross-Border Data Localization Gaps:Fragmented cloud governance between EU GDPR and China's MIIT data residency rules favors edge-computing tire gateway architectures.
Industry Challenges
- MEMS Sensor Calibration Talent:Microelectromechanical systems integration requires rare combinations of automotive and semiconductor process engineering expertise.
- Multi-Standard Certification Parallelism:Simultaneous NHTSA, ECHA REACH, and MIIT radio-frequency approvals strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Tire Market |
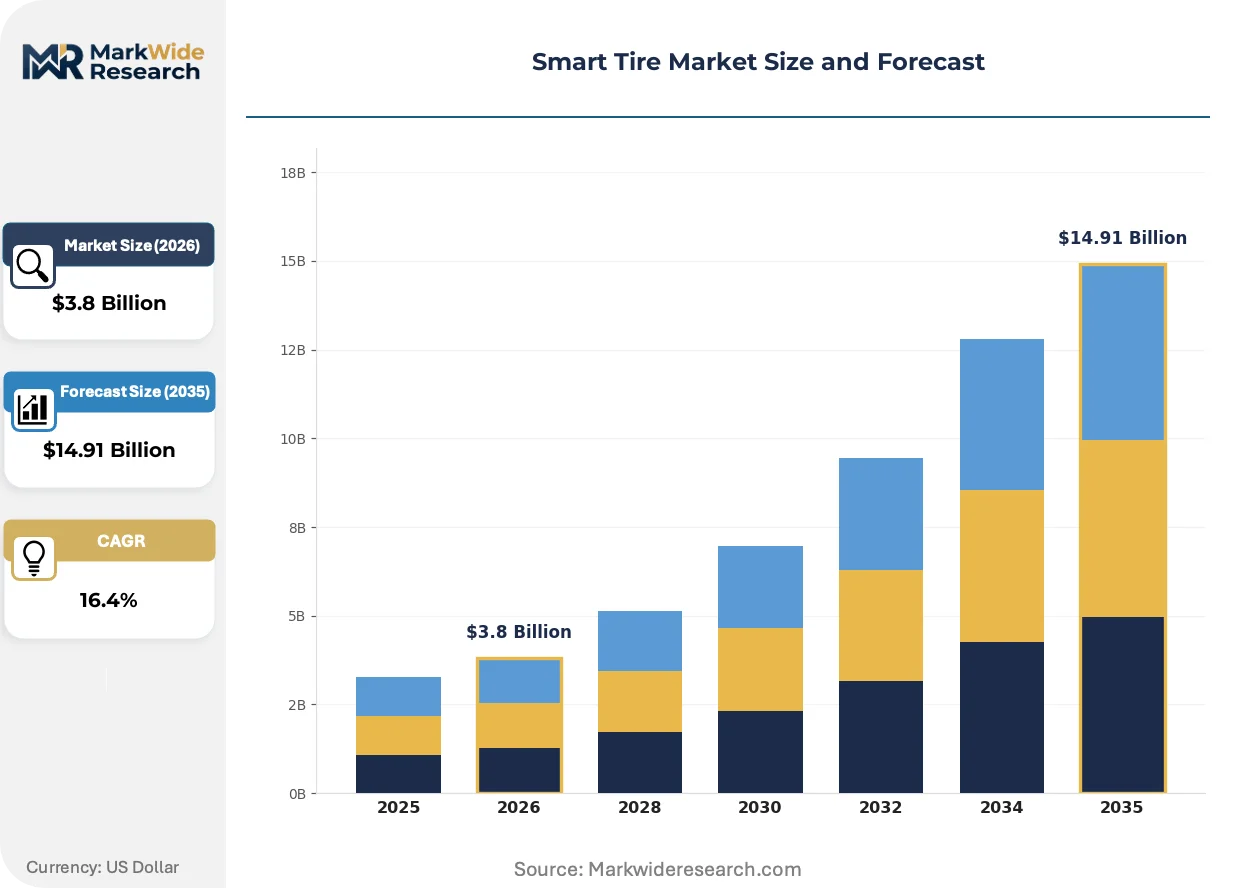
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Monitoring Systems, Temperature Sensors, Tread Depth Sensors, Wear Indicators End User: OEMs, Fleet Operators, Aftermarket Providers, Vehicle Owners Technology: TPMS, RFID, IoT, Bluetooth Application: Passenger Vehicles, Commercial Vehicles, Motorsport, Agricultural Equipment |
| Companies Covered | Bridgestone Corporation, Michelin Group, Goodyear Tire & Rubber Company, Continental AG, Pirelli & C. S.p.A., Sumitomo Rubber Industries, Nexen Tire Corporation, Hankook Tire & Technology, The Yokohama Rubber Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Tire Market Evolving Landscape
RFID-to-Bluetooth connectivity migration is compressing hardware margins while expanding recurring software revenue pools across tire lifecycle management platforms.
Energy-harvesting piezoelectric sensors embedded in tire sidewalls are fragmenting the power architecture for connected tire systems. Commercial fleet operators in Germany are piloting battery-free pressure monitoring to eliminate maintenance cycles. This displacement of conventional battery-powered TPMS is fragmenting supplier tiers between energy-harvesting specialists and legacy electronics houses.
REACH framework amendments under ECHA jurisdiction are mandating full material disclosure for tire-embedded electronics, including conflict mineral tracing for sensor substrates. Tire manufacturers must now document tantalum and tin supply chains through smelter verification programs. OEM procurement teams in France and Italy are prioritizing suppliers with pre-validated ECHA dossiers.
Usage-based tire procurement is displacing unit-volume purchasing among North American long-haul fleet operators. Michelin and Bridgestone are responding with per-mile billing platforms that bundle hardware, installation, and predictive replacement. This model compresses distributor margins while capturing lifetime value through data monetization in the US Great Lakes freight corridor.
Smart Tire Market Segmentation
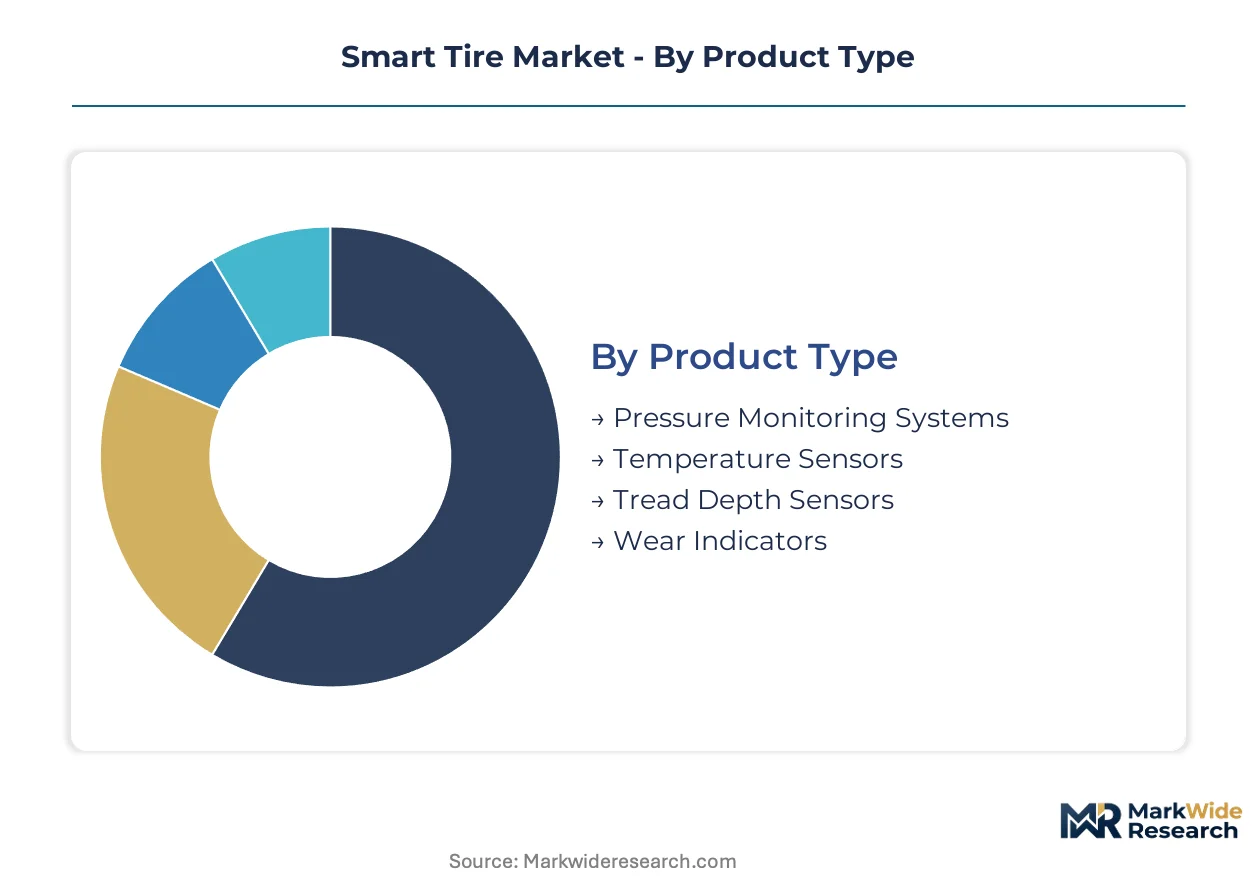
Segmentation in the smart tire market reflects divergent compliance burdens and hardware cost structures across regulatory jurisdictions. NHTSA mandates in the United States, EU Green Deal carbon accounting rules, and MIIT data governance standards in China each favor different sensor configurations and connectivity architectures.
Product Type:
NHTSA's TPMS mandate for passenger vehicles and the EU's embedded carbon disclosure requirements under REACH create divergent certification pathways for sensor-integrated tire products.
- Pressure Monitoring Systems:Direct TPMS embeds battery-powered sensors within tire valve stems or carcass walls to transmit real-time pressure data to vehicle ECUs. Fleet operators in China deploy these systems at scale for heavy-duty commercial vehicle parc to optimize fuel consumption and reduce unscheduled maintenance.
- Temperature Sensors:Thermocouple and infrared sensing elements monitor tire casing thermal profiles to predict blowout risk and optimize retread cycles. Motorsport applications in Germany and Italy concentrate demand for high-sampling-rate thermal monitoring where tire degradation windows determine race strategy.
- Tread Depth Sensors:Ultrasonic and capacitive measurement elements track remaining tread volume to trigger replacement scheduling. Aftermarket retrofit kits serve legacy commercial vehicle fleets lacking factory-installed monitoring infrastructure.
- Wear Indicators:Mechanical and electronic indicators signal tread exhaustion thresholds. Budget passenger vehicle segments in India prioritize simple mechanical indicators over electronic alternatives to minimize unit cost.
Established volume favors Pressure Monitoring Systems; emerging adoption favors Temperature Sensors.
End User:
Procurement authority and data ownership models fragment the customer base across captive OEM supply, fleet-scale telematics integration, and fragmented aftermarket service channels.
- OEMs:Vehicle manufacturers specify embedded sensor architectures during tire homologation to satisfy type-approval requirements across multiple jurisdictions. German and Japanese OEMs lead integration of Bluetooth-enabled tire data streams into centralized vehicle telematics gateways.
- Fleet Operators:Logistics companies purchase tires as a service with per-mile billing that bundles hardware, installation, and predictive replacement. North American long-haul freight corridors see rapid uptake of usage-based procurement models that compress traditional distributor margins.
- Aftermarket Providers:Independent tire dealers and service chains retrofit sensor kits to existing vehicle parc. India's commercial vehicle expansion under PLI scheme incentives creates first-mover positioning for domestic retrofit specialists.
- Vehicle Owners:Individual consumers purchase replacement smart tires through retail channels with limited telematics integration. Price sensitivity in mass-market passenger segments slows adoption relative to fleet-driven deployment.
Revenue concentration sits with OEMs; margin expansion favors Fleet Operators.
Technology:
Radio-frequency certification timelines and power architecture choices determine competitive positioning across connectivity standards.
- TPMS:Proprietary low-frequency and ultra-high-frequency protocols dominate regulatory-mandated pressure monitoring with mature supply chains and established FCC and ETSI certification pathways. Battery replacement cycles and signal interference in multi-axle commercial vehicles present persistent operational constraints.
- Bluetooth:Low-energy wireless protocols standardize over-the-air tire analytics integration with fleet management platforms and smartphone applications. German commercial fleet pilots demonstrate battery-free piezoelectric harvesting to eliminate maintenance cycles entirely.
- RFID:Passive radio-frequency identification enables tire lifecycle tracking from manufacturing through retreading and recycling without onboard power. ECHA REACH material disclosure mandates drive adoption for supply chain traceability and conflict mineral documentation.
- IoT:Cellular and satellite-connected modules enable cloud-native tire analytics independent of vehicle telematics infrastructure. Cross-border data localization requirements between EU GDPR and China's MIIT rules favor edge-computing gateway architectures over direct cloud transmission.
Regulatory compliance anchors TPMS deployment; connectivity innovation expands fastest through Bluetooth.
Application:
Vehicle duty cycles and operating cost structures determine sensor value capture potential across mobility segments.
- Commercial Vehicles:Heavy-duty trucks and buses generate highest returns on tire monitoring investment through fuel optimization and downtime reduction. Chinese logistics fleets under domestic OEM supply agreements scale connected tire deployments fastest among global markets.
- Passenger Vehicles:Light-duty cars and SUVs represent largest unit volume with NHTSA-mandated TPMS as baseline equipment. Premium segments in Germany and the United States adopt full IoT connectivity while economy tiers retain basic pressure warning functionality.
- Motorsport:Formula and endurance racing applications demand millisecond-latency telemetry for real-time strategy optimization. Specialized thermal and pressure sensing commands price premiums an order of magnitude above commercial vehicle equivalents.
- Agricultural Equipment:Tractors and harvesters operate at variable pressures across field and road surfaces requiring robustized sensor housings. Seasonal usage patterns and dealer service networks slow adoption relative to continuous-duty commercial applications.
Unit economics favor Commercial Vehicles; technology premium concentrates in Motorsport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in China absorb premium pricing for connected tire systems without volume elasticity, while Indian aftermarket buyers demand steep per-unit discounts that compress retrofit sensor margins.
United States
Long-haul freight operators across the Great Lakes corridor deploy usage-based tire procurement models with per-mile billing. NHTSA TPMS mandates for passenger vehicles create baseline demand, while FCC certification timelines for Bluetooth-enabled transmitters extend pre-market entry by 12-18 months. Detroit-Windsor automotive cluster anchors embedded sensor R&D for commercial vehicle telematics integration.
Germany
Commercial fleet operators pilot battery-free piezoelectric pressure monitoring to eliminate maintenance cycles entirely. ECHA REACH framework amendments mandate full material disclosure for tire-embedded electronics, including conflict mineral tracing through smelter verification. Stuttgart and Munich automotive engineering clusters concentrate MEMS sensor calibration talent for motorsport and premium passenger applications.
China
Domestic OEMs and logistics fleets scale smart tire deployments for heavy-duty commercial vehicle parc under MIIT data governance standards. Dual carbon goals accelerate adoption of connected tire systems for fuel optimization and predictive maintenance scheduling. Yangtze River Delta manufacturing clusters house specialized cleanroom facilities for semiconductor packaging into tire-mounted IoT modules.
India
Domestic logistics fleet expansion under PLI scheme incentives creates first-mover positioning for retrofit sensor providers serving legacy commercial vehicle parc. BIS certification requirements for automotive electronics slow import-dependent supply chains while favoring domestic assembly. Maharashtra and Gujarat industrial corridors concentrate aftermarket distribution networks for budget-conscious fleet operators.
Japan
Automotive OEMs integrate Bluetooth-enabled tire data streams into centralized vehicle telematics gateways for premium passenger and light commercial segments. METI standards for radio-frequency emission shape sensor design specifications for export-oriented production. Kanto and Kansai manufacturing belts anchor precision MEMS fabrication for tire-integrated pressure and temperature monitoring systems.
Smart Tire Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the smart tire sector. Bridgestone Corporation and Continental AG anchor the upper tier through captive semiconductor packaging capabilities and embedded sensor R&D pipelines. The mid-tier fragments between energy-harvesting sensor specialists and legacy electronics houses adapting to battery-free architectures. Dominant competitive moves include backward integration into tire-mounted IoT module production and strategic partnerships with fleet telematics platforms for over-the-air data standardization.
Within the integrated multinational tier, Bridgestone Corporation represents technology leadership in pressure monitoring system architectures, while Continental AG exemplifies backward integration into semiconductor packaging for tire-mounted connectivity modules. Michelin Group occupies a position bridging premium tire manufacturing with usage-based subscription models. Among East Asian tire specialists, Sumitomo Rubber Industries and Hankook Tire & Technology sit within the competitive set pursuing fleet-scale telematics integration through Bluetooth-enabled data transmission protocols.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Pirelli & C. S.p.A. |
| Sumitomo Rubber Industries |
| Nexen Tire Corporation |
| Hankook Tire & Technology |
| The Yokohama Rubber Co. |
| Others |
Value Network & Pricing Analysis
Energy-harvesting piezoelectric sensors displacing battery-powered TPMS modules simultaneously redraws manufacturing geography toward Yangtze River Delta cleanroom clusters and compresses hardware margins while expanding recurring software revenue pools.
Pricing Analysis
After-sales data monetization and predictive maintenance subscriptions now drive lifetime value capture across tire lifecycle management platforms. Pricing stratifies across premium IoT-enabled architectures, standard Bluetooth-integrated systems, and economy-grade basic pressure monitoring tiers. Cost compression in the retrofit sensor segment intensifies because Indian aftermarket buyers demand steep per-unit discounts that strain import-dependent supply chains. Fleet operators in China absorb premium pricing without volume elasticity, while individual vehicle owners in mass-market segments exhibit highest price sensitivity.
Supply Chain Analysis
Inventory lead times for MEMS sensor calibration equipment stretch across 12-18 month FCC certification windows for tire-integrated transmitters. Semiconductor packaging capacity concentrates in China, South Korea, and Taiwan, with specialized cleanroom facilities feeding tire-mounted IoT module assembly. The supply chain draws from tantalum and tin substrates subject to ECHA REACH conflict mineral tracing mandates. Single-source vulnerability sits with East Asian semiconductor packaging concentration. Distribution runs through captive OEM supply agreements, fleet-scale telematics integrators, and fragmented aftermarket service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart tire market tracks a cyclical recovery anchored to commercial fleet replacement cycles following logistics capacity expansion under China's dual carbon goals.
For Market Incumbents: Shield embedded sensor R&D pipelines from margin erosion by accelerating backward integration into semiconductor packaging capabilities. Consolidate regulatory affairs bandwidth against multi-standard certification parallelism across NHTSA, ECHA REACH, and MIIT radio-frequency approval pathways. Prioritize captive supply of tire-mounted IoT modules to defend technology leadership positions.
For New Entrants and Emerging Players: ECHA REACH pre-validated dossiers offer a certification fast-track into French and Italian OEM procurement queues. White-space targets include India's PLI scheme-favored commercial vehicle retrofit segment and battery-free piezoelectric sensor architectures for German fleet pilots. A go-to-market angle through fleet telematics platform partnerships enables over-the-air data standardization without direct OEM supply chain penetration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed energy-harvesting sensor specialists holding cleanroom-adjacent MEMS fabrication capabilities. Long-term viability over a 5-10 year window favors targets with pre-validated ECHA dossiers and established smelter verification programs for conflict mineral tracing. The signal to watch is cross-border data localization mandate fragmentation between EU GDPR and China's MIIT rules favoring edge-computing gateway architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Packaging | Captive cleanroom capacity in Yangtze River Delta clusters reduces dependency on East Asian packaging houses. |
| Battery-Free Piezoelectric Sensor Development | Eliminates maintenance cycles for German commercial fleet operators piloting energy-harvesting architectures. |
| ECHA REACH Dossier Pre-Validation | Secures French and Italian OEM procurement priority for conflict mineral tracing compliance. |
| Fleet Telematics Platform Partnership | Standardizes Bluetooth-enabled over-the-air data ingestion for North American long-haul freight corridors. |
| Edge-Computing Gateway Architecture Deployment | Navigates fragmented cloud governance between EU GDPR and China's MIIT data residency requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet telematics directors, tire OEM platform engineers, aftermarket distribution heads, and semiconductor packaging specialists. Secondary validation drew from NHTSA regulatory filings, ECHA REACH dossier databases, MIIT standard publications, and vehicle production registration data. Bottom-up unit economics modeling triangulated against top-down market sizing across sensor configuration and connectivity architecture segments.
Across the analysis window, forecasts employed a structured analytical framework modeling product type, end-user procurement authority, technology connectivity standard, and application duty cycle dimensions. CAGRs were derived from segment-level growth trajectory blending. Key inputs included fleet telematics platform adoption curves, regulatory mandate implementation schedules, and semiconductor packaging capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained commercial fleet replacement demand or stable cross-border data governance frameworks would require recalibration. Forecasts reflect documented assumptions around sensor cost reduction curves and certification timeline standardization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
North Commercial Vehicle Tire Pressure Monitoring Systems Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Europe Tire Market