
 Hazardous Chemicals Transportation Solution Market | 2026-2036
Hazardous Chemicals Transportation Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Chemicals Transportation Solution Market Insights
Gulf Coast petrochemical corridor expansion is reconfiguring fleet deployment patterns across North America. Kenan Advantage Group leverages its tanker scale to dominate regional liquid chemical movements, while DB SCHENKER anchors European hazardous cargo flows through integrated rail-road networks. DHL Group competes on temperature-controlled and time-critical pharmaceutical-hazardous shipments, extending its pharma logistics expertise into regulated chemical transport.
Hazardous chemicals transportation solutions encompass specialized logistics services, equipment, and compliance systems engineered to move substances classified under UN dangerous goods codes, typically requiring pressure-rated tankers, corrosion-resistant containers, or temperature-controlled IBCs with sealed venting systems. These solutions prevent release incidents, protect handlers, and satisfy chain-of-custody documentation from origin to end-use facility. Road transport occupies the largest service volume share due to last-mile flexibility and point-to-point routing for mid-sized chemical producers, while sea transport sustains the longest-haul intercontinental movements of bulk petrochemicals and industrial gases. Tank containers capture premium margin pools where pressurized or cryogenic specifications demand stainless-steel construction and periodic hydrostatic testing certification.
US DOT Pipeline and Hazardous Materials Safety Administration regulations mandate specific packaging, labeling, and routing for highway movements, while IMDG codes govern international maritime chemical stowage and segregation. EPA Risk Management Plan requirements and OSHA Process Safety Management standards further shape carrier qualification and emergency response preparedness for facilities handling threshold quantities of regulated substances. Stakeholders must monitor evolving lithium battery classification debates and hydrogen transport rulemakings, as these emerging chemistries test existing regulatory frameworks and equipment certification boundaries.
Market Dynamics
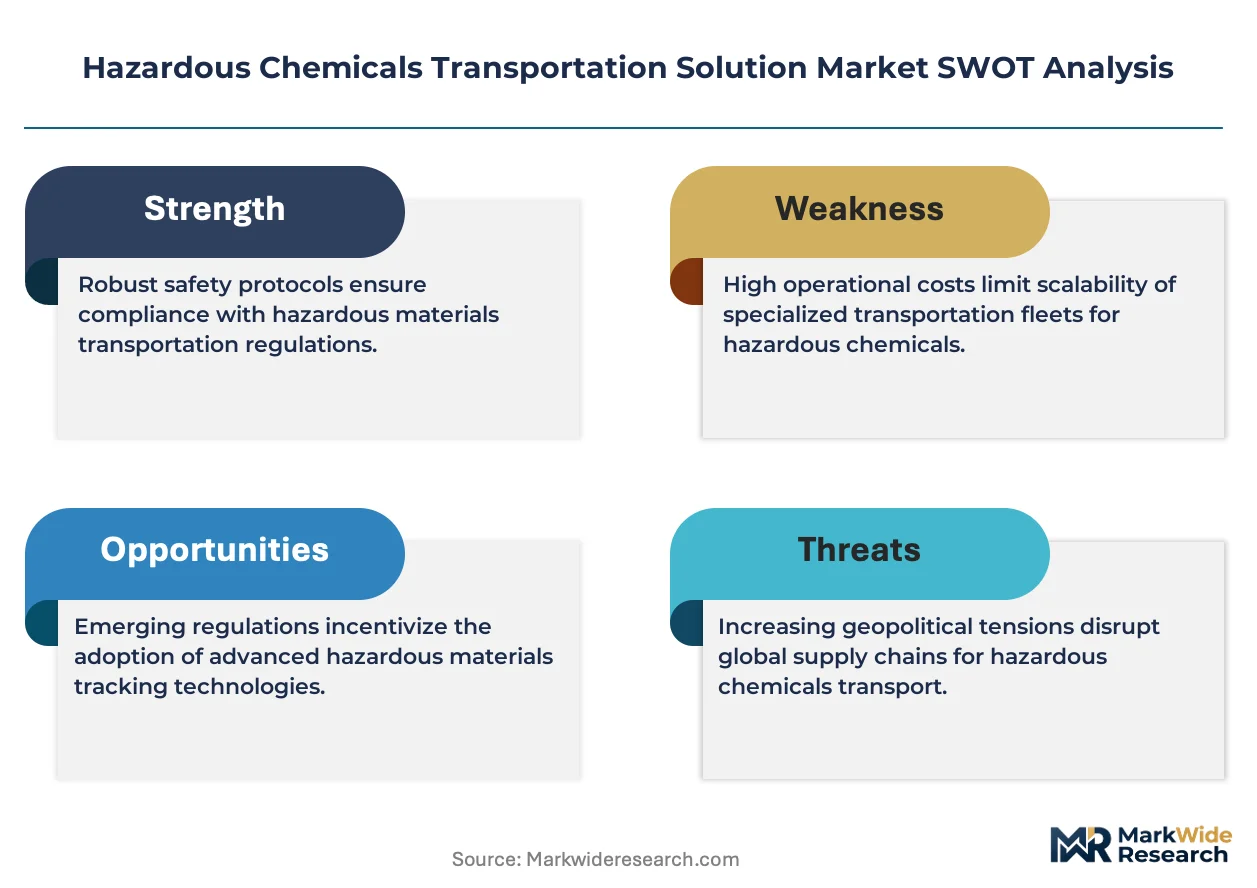
EPA and OSHA enforcement tightening around chlorine and ammonia movements is forcing petrochemical manufacturers across Texas and Louisiana to abandon generalist carriers in favor of specialized hazardous logistics providers with certified emergency response capabilities.
Growth Catalysts
- US Gulf Coast corridor expansion:Port infrastructure investments in Houston and Corpus Christi are generating dense multimodal requirements for pressurized tanker movements between refineries and export terminals.
- REACH compliance complexity in Europe:Chemical manufacturers are outsourcing transport documentation and chain-of-custody verification to specialized carriers capable of managing Safety Data Sheet harmonization across member states.
- Hydrogen transport rulemakings:Cryogenic tanker specifications for liquid hydrogen are creating equipment upgrade cycles as industrial gas producers prepare for ammonia cracking and fuel cell supply chains.
Market Restraints
- Stainless steel input cost volatility:Tank container manufacturers face margin compression from nickel and chromium price swings, delaying fleet replacement schedules for corrosion-resistant IBCs.
- Specialized driver shortage:Hazmat endorsement requirements and CDL training backlogs constrain carrier capacity expansion in the US, particularly for cryogenic and radioactive cargo categories.
- IMDG code amendment lag:Maritime classification updates for lithium battery chemistries create stowage uncertainty, forcing shippers to absorb demurrage costs while awaiting port authority clarification.
Strategic Opportunities
- India petrochemical corridor development:Dahej and Hazira manufacturing clusters lack integrated hazardous logistics networks, opening greenfield opportunities for temperature-controlled IBC deployment.
- Pharmaceutical-hazardous convergence:Cytotoxic drug distribution requires cold chain integrity combined with UN dangerous goods compliance, rewarding carriers with dual certification capabilities.
- EU Green Deal transport modality shifts:Inland waterway preference for bulk chemical movements between Antwerp and Ludwigshafen favors barge-tanker operators over road-dependent competitors.
Industry Challenges
- DOT PHMSA emergency response plan certification:Carriers must maintain 24-hour incident command capabilities with documented hazardous materials technician deployment, straining smaller regional operators.
- Legacy telematics integration:Real-time pressure monitoring and geofencing systems require retrofitting older tanker fleets, creating downtime conflicts with just-in-time chemical plant supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Chemicals Transportation Solution Market |
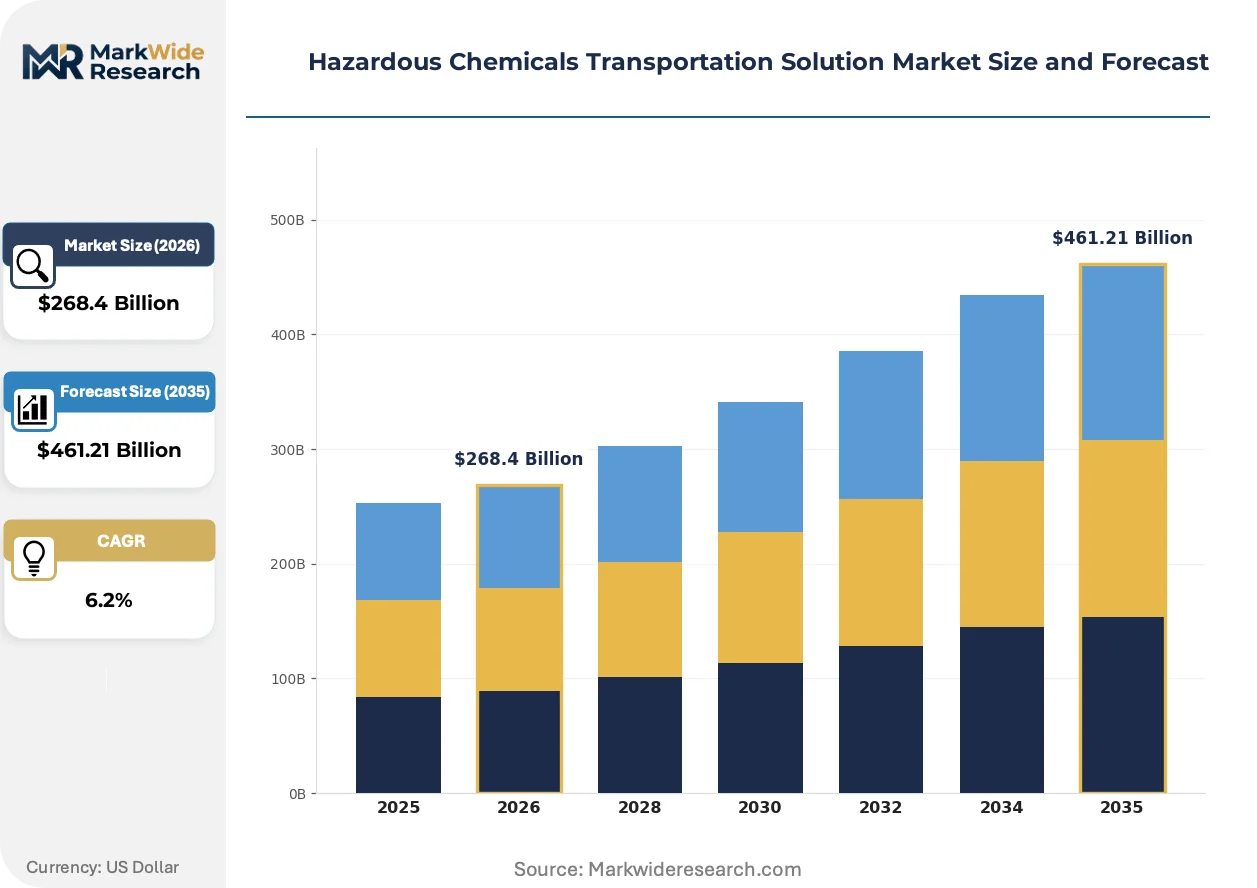
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $461.21 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Transport, Rail Transport, Sea Transport, Air Transport Container Type: Drums, Tanks, IBCs, Bulk Containers Regulation Compliance: DOT, IMDG, ADR, HMR Delivery Mode: Direct Delivery, Consolidated Delivery, Scheduled Delivery, On-Demand Delivery |
| Companies Covered | Kenan Advantage Group, Eagle Transport, Highway Transport, Modern Transportation, Rinchem, CMA CGM Group, DB SCHENKER, DHL Group, DSV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Chemicals Transportation Solution Market Trends and Innovations
Digital chain-of-custody verification and predictive maintenance systems are compressing insurance premiums and liability exposure for hazardous cargo movements. Equipment manufacturers and software providers are converging on integrated platforms that combine sensor telemetry with regulatory documentation automation.
Autonomous tanker telematics with continuous pressure and temperature monitoring is rendering obsolete manual gauge reading protocols and paper-based custody transfer records. Chemical producers in the US Gulf Coast are mandating these systems for carrier qualification, compressing allowable response windows for thermal excursion events from hours to minutes. Insurance underwriters are pricing coverage based on real-time data availability, widening cost spreads between digitized and legacy fleets.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transport classification changes for fluorinated gas cylinders. Industrial gas distributors must retrofit tank containers for lower-GWP alternatives while maintaining compatibility with existing filling infrastructure. German KBA type-approval processes for modified pressure equipment are creating six-to-nine-month certification bottlenecks, favoring carriers with pre-approved modular tank designs.
Consolidated procurement by integrated oil companies is displacing fragmented shipper-carrier relationships with multi-year framework agreements bundling transport, storage, and emergency response. Refinery operators in Rotterdam and Singapore are centralizing vendor pools, demanding ISO 9001 and CDI-M certification as minimum qualifiers. Smaller specialty chemical producers face exclusion from preferred supplier lists, forcing alliance formations to meet volume and compliance thresholds.
Hazardous Chemicals Transportation Solution Market Segmentation
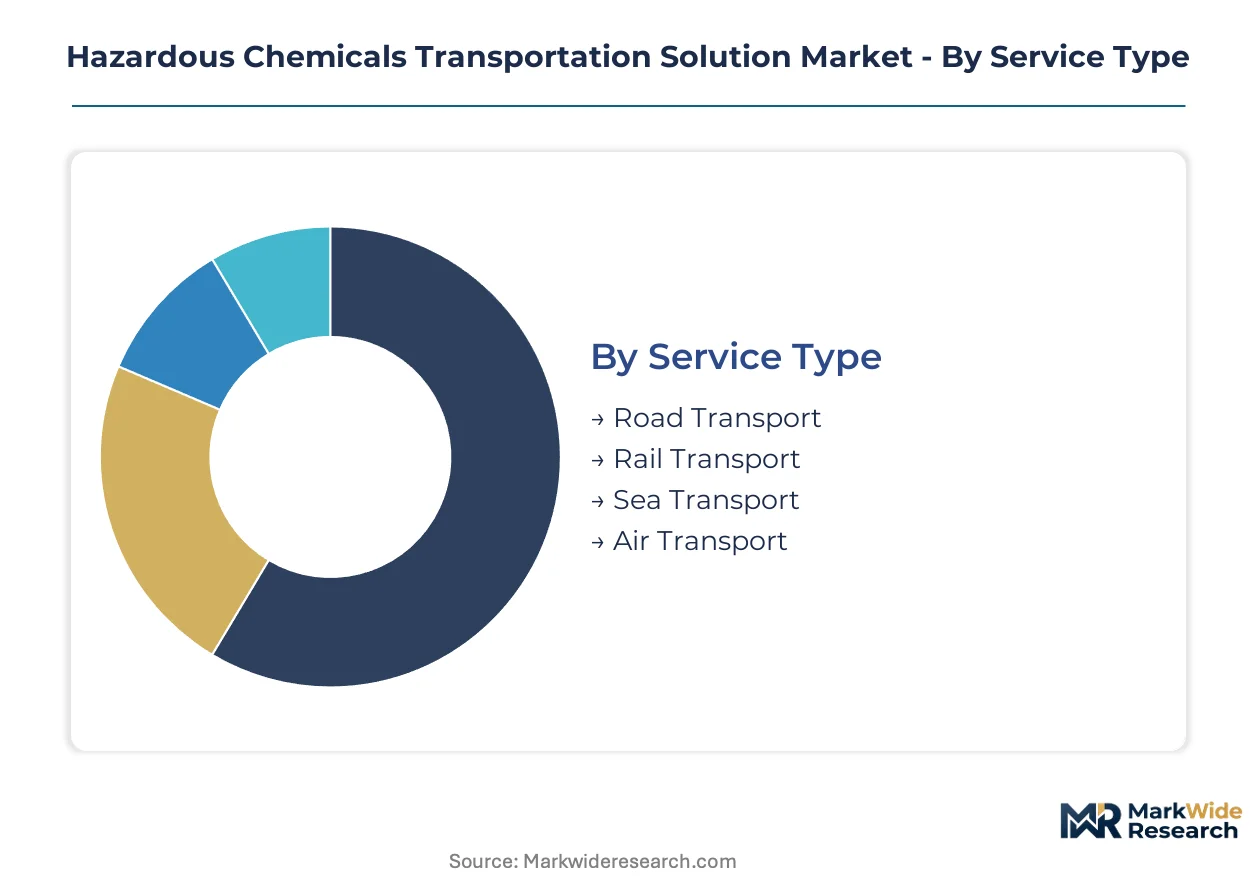
Hazardous chemicals transportation solutions fragment across four operational dimensions that determine equipment specifications, regulatory documentation burdens, and carrier qualification requirements. Each segmentation axis carries distinct margin profiles and capital intensity thresholds that shape competitive positioning across regional markets.
Service Type:
Road, rail, sea, and air modalities span a use-case spectrum from last-mile flexibility to intercontinental bulk movement, with each channel commanding specialized fleet assets and crew certifications.
- Road Transport:Tanker trucks and hazmat-certified trailers handle point-to-point routing for mid-sized chemical producers requiring schedule flexibility. Demand concentrates in the US Gulf Coast corridor where refinery-to-terminal movements require CDL hazmat endorsements and real-time GPS tracking mandated by DOT PHMSA.
- Sea Transport:Specialized chemical tankers and gas carriers sustain long-haul bulk movements of petrochemicals and industrial gases across ocean lanes. Rotterdam and Singapore port operators drive specifications for double-hull construction and vapor recovery systems under IMDG code compliance windows.
- Rail Transport:Pressure-rated tank cars and cryogenic railcars move chlorine, ammonia, and liquefied gases across continental networks. BNSF and Union Pacific dominate North American chemical rail with dedicated hazmat response teams positioned along high-volume corridors.
- Air Transport:Cargo aircraft with fire-suppression holds and limited quantity packaging handle time-critical pharmaceutical-hazardous shipments. Frankfurt and Memphis hubs process temperature-controlled dangerous goods under IATA DGR protocols with 24-hour emergency hotlines.
Established volume favors road transport; emerging adoption favors sea transport as Gulf Coast export terminal capacity expands.
Container Type:
Cost tier differentiation separates commodity packaging from engineered containment systems requiring periodic recertification and corrosion-resistant alloys.
- Tanks:Stainless-steel pressure vessels and cryogenic tank containers handle gases and liquids requiring sealed venting or thermal insulation. German KBA type-approval processes for modified pressure equipment create certification bottlenecks favoring carriers with pre-approved modular designs.
- IBCs:Intermediate bulk containers with UN certification manage mid-volume chemical movements where forklift handling and stackability reduce per-unit logistics costs. REACH compliance complexity in Europe drives outsourcing of Safety Data Sheet harmonization to IBC fleet operators with integrated documentation systems.
- Drums:Steel and fiber drums with tight-head or open-head configurations package solid and liquid hazardous materials for smaller shipment sizes. Generalist drum suppliers face margin compression as integrated oil companies consolidate procurement into multi-year framework agreements.
- Bulk Containers:ISO tank containers and flexitanks handle high-volume liquid movements between manufacturing clusters and port terminals. Dahej and Hazira petrochemical corridors in India lack integrated bulk container networks, opening greenfield deployment opportunities.
Capital intensity favors tanks; flexibility favors IBCs in fragmented specialty chemical distribution.
Regulation Compliance:
Geographic jurisdiction determines documentation protocols, with each regulatory framework imposing distinct packaging, labeling, and routing mandates.
- DOT:US Department of Transportation Pipeline and Hazardous Materials Safety Administration rules govern highway movements with specific emergency response plan certification requirements. Carriers must maintain 24-hour incident command capabilities with documented hazardous materials technician deployment.
- IMDG:International Maritime Dangerous Goods code stowage and segregation rules prevent incompatible chemical reactions during ocean transit. Amendment lags for lithium battery chemistries create stowage uncertainty forcing shippers to absorb demurrage costs.
- ADR:European Agreement concerning the International Carriage of Dangerous Goods by Road harmonizes cross-border truck movements through EU member states. German authorities enforce tunnel restriction codes and driver training certificates with roadside inspection protocols.
- HMR:Hazardous Materials Regulations align US rail, air, and vessel movements with modal-specific packaging standards and incident reporting thresholds. FRA and USCG coordinate enforcement with PHMSA for multimodal shipments.
Enforcement stringency favors DOT; harmonization complexity favors ADR for pan-European routing.
Delivery Mode:
Customer operational rhythm separates just-in-time chemical plant supply from inventory-buffered distribution models.
- Direct Delivery:Dedicated tanker movements from producer to end-use facility eliminate intermediate handling and custody transfer points. Refinery operators in Rotterdam centralize vendor pools demanding ISO 9001 and CDI-M certification as minimum qualifiers.
- Scheduled Delivery:Recurring route circuits with predetermined pickup and delivery windows optimize fleet utilization for steady-volume chemical producers. Legacy telematics integration challenges create downtime conflicts with just-in-time supply contracts.
- Consolidated Delivery:Multi-shipment container sharing reduces per-unit transport costs for smaller chemical producers below full-truckload thresholds. Alliance formations help specialty chemical producers meet volume and compliance thresholds for preferred supplier lists.
- On-Demand Delivery:Emergency response and spot-market movements address supply disruptions or unplanned production spikes. Specialized driver shortages constrain capacity expansion particularly for cryogenic and radioactive cargo categories.
Contract reliability favors scheduled delivery; margin expansion favors on-demand for certified emergency response carriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized tanker capacity concentrates along coastal refining corridors where chlorine, ammonia, and cryogenic movements face tightening enforcement. Port infrastructure investments and multimodal connectivity determine carrier deployment patterns across major chemical production zones.
United States
Gulf Coast petrochemical expansion drives demand for pressurized tankers between Houston refineries and Corpus Christi export terminals. DOT PHMSA mandates 24-hour incident command capabilities with certified hazardous materials technician deployment for highway movements. Texas and Louisiana manufacturing clusters are abandoning generalist carriers in favor of specialized providers with documented emergency response systems.
Germany
Industrial gas distributors retrofit tank containers for lower-GWP refrigerant alternatives under EU F-Gas Regulation phase-down schedules. German KBA type-approval processes for modified pressure equipment create six-to-nine-month certification bottlenecks. The Ludwigshafen chemical complex favors barge-tanker operators over road-dependent competitors for bulk movements from Antwerp.
India
Dahej and Hazira manufacturing clusters lack integrated hazardous logistics networks, opening greenfield opportunities for temperature-controlled IBC deployment. The country's national chemical regulator enforces UN dangerous goods packaging standards with increasing stringency for import-export corridors. Gujarat petrochemical zones are attracting specialized carriers to fill multimodal infrastructure gaps between port terminals and inland processing facilities.
China
Yangtze River Delta chemical producers are scaling cryogenic tanker specifications for liquid hydrogen transport ahead of fuel cell supply chain expansion. The Ministry of Ecology and Environment is tightening emissions and safety protocols for chlorine movements through dense population corridors. Shanghai port authorities are mandating double-hull construction and vapor recovery systems for chemical tanker berthing.
Netherlands
Rotterdam refinery operators centralize vendor pools with ISO 9001 and CDI-M certification as minimum qualifiers for framework agreements. REACH compliance complexity drives outsourcing of Safety Data Sheet harmonization to specialized carriers managing cross-border documentation. The Randstad logistics hub anchors European hazardous cargo flows through integrated rail-road networks serving Antwerp-Rotterdam chemical corridors.
Hazardous Chemicals Transportation Solution Market Competitive Landscape
Asset-heavy tanker operators and integrated logistics networks split the market between regional scale and multimodal reach. Consolidation pressures favor carriers with certified emergency response capabilities and real-time telemetry systems. Two strategic archetypes dominate: specialized liquid chemical haulers with Gulf Coast density, and global freight forwarders with dangerous goods compliance infrastructure. Competitive moves center on fleet telematics retrofitting and multi-year framework agreement pursuit.
Within the specialized hauler tier, Kenan Advantage Group exemplifies tanker-scale dominance through regional liquid chemical movements, while DB SCHENKER anchors European hazardous cargo flows through integrated rail-road networks. DHL Group occupies a position at the pharmaceutical-hazardous convergence point, extending temperature-controlled expertise into regulated chemical transport. These three entities represent distinct strategic positions: regional density, continental multimodal integration, and pharma-cold-chain crossover capability.
| Leading Market Players |
|---|
| Kenan Advantage Group |
| Eagle Transport |
| Highway Transport |
| Modern Transportation |
| Rinchem |
| CMA CGM Group |
| DB SCHENKER |
| DHL Group |
| DSV |
| Others |
Pricing and Supply Chain Analysis
Stainless steel mill concentration in China and Indonesia directly determines where margin pools accumulate across tank container manufacturing, with nickel price volatility transmitted downstream through corrosion-resistant IBC fleet operators serving Gulf Coast petrochemical corridors.
Pricing Analysis
DOT PHMSA certification requirements dictate the pricing tier structure across hazardous logistics services, with three-tier pricing structure across premium, standard, and economy levels separating 24-hour emergency response carriers from generalist haulers. Price differentiation hinges on real-time telemetry integration and ISO 9001 certification grade. Cost compression in standard-tier road transport is intensifying because CDL hazmat endorsement backlogs constrain qualified driver supply. Smaller specialty chemical producers exhibit highest price sensitivity, while integrated oil companies with multi-year framework agreements demonstrate lowest.
Supply Chain Analysis
Extended payment terms from German KBA type-approval processes strain working capital for tank container manufacturers retrofitting fleets for EU F-Gas Regulation compliance. Equipment sourcing draws from China, Germany, and South Korea for pressure-rated stainless steel components. Supply chain risk centers on nickel and chromium commodity price volatility transmitted through corrosion-resistant alloy dependencies. Distribution runs through Rotterdam and Singapore port hubs anchoring intercontinental chemical tanker movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hazardous chemicals transportation functions as a service-attach market where predictive maintenance subscriptions and emergency response retainers expand faster than base tanker hardware procurement.
For Market Incumbents: Harden fleet telematics integration to compress insurance premium spreads between digitized and legacy assets. Pursue backward integration into stainless steel tank fabrication to offset nickel price volatility exposure. Consolidate regional emergency response capabilities ahead of DOT PHMSA enforcement tightening around chlorine and ammonia corridors. For New Entrants and Emerging Players: Establish a beachhead in India's Dahej and Hazira petrochemical corridors where integrated hazardous logistics networks remain underdeveloped. Target temperature-controlled IBC deployment for pharmaceutical-hazardous convergence applications. Lead with dual cold chain and UN dangerous goods certification as differentiated qualification for cytotoxic drug distribution. For Investors and Strategic Acquirers: Capital is best deployed toward specialized carriers with pre-approved modular tank designs navigating German KBA certification bottlenecks. Long-term viability favors asset-heavy operators with real-time telemetry infrastructure and documented 24-hour incident command capabilities. Watch hydrogen transport rulemaking acceleration as inflection indicator for cryogenic tanker specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Telematics Retrofit | Real-time pressure monitoring satisfies Gulf Coast refinery carrier qualification mandates. |
| Backward Integration into Tank Fabrication | In-house stainless steel construction hedges nickel price volatility exposure. |
| Emergency Response Capability Certification | DOT PHMSA 24-hour incident command requirements displace generalist competitors. |
| Multi-year Framework Agreement Pursuit | Rotterdam refinery vendor pool centralization rewards ISO 9001 and CDI-M certification. |
| Cryogenic Tanker Specification Upgrade | Liquid hydrogen transport rulemakings drive equipment replacement cycles ahead of fuel cell supply chain expansion. |
Research Methodology
The analysis maps road, rail, sea, and air transport modalities alongside tank, IBC, drum, and bulk container formats, each validated through fleet operations directors, hazmat safety officers, chemical plant procurement managers, and insurance underwriters. Primary interview intelligence triangulates against customs trade data, DOT PHMSA incident reports, SEC carrier filings, and EU Cefic chemical logistics surveys. Bottom-up equipment deployment counts reconcile with top-down regional production hub estimates.
Modeling assumptions hold fixed current DOT, IMDG, ADR, and HMR regulatory frameworks while varying hydrogen transport rulemaking adoption rates and stainless steel input cost trajectories across the projection horizon. Segmentation dimensions include service type, container format, compliance jurisdiction, and delivery mode. CAGRs derive from equipment replacement cycle analysis and petrochemical capacity expansion pipelines. Forecast inputs incorporate driver certification backlog projections and port infrastructure investment schedules.
Sensitivities concentrate around EPA and OSHA enforcement intensity, nickel price volatility, and lithium battery classification amendment timing. Forecasts reflect documented assumptions regarding Gulf Coast corridor expansion rates and EU F-Gas Regulation phase-down adherence. Macroeconomic contraction, regulatory rollback, or breakthrough hydrogen transport technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
ASEAN Road Freight Transport Market