
 Faba Beans Flour Market | 2026-2036
Faba Beans Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Faba Beans Flour Market Analytics
Food-grade pulse milling expertise is rotating toward specialized protein extraction, constraining capacity for traditional whole-bean flour output. Roquette Frères leverages its decades of European pea and bean processing infrastructure to sustain supply continuity for industrial buyers. BENEO GmbH anchors its position through deep backward integration into Belgian chicory and pulse supply chains. AGT Food & Ingredients dominates North American origination with direct farmer contracting across the Canadian prairies.
Faba bean flour consists of milled cotyledons from Vicia faba L., typically containing 25-30% protein and 40-50% starch by dry weight, produced through dehulling, splitting, and impact or roller milling to achieve particle sizes between 80 and 200 microns for baking and extrusion applications. The organic flour segment leads premium pricing due to certification costs and limited acreage, while gluten-free flour is accelerating fastest as celiac-safe formulations displace wheat in European pasta production. Conventional flour occupies the volume base, with margin pools concentrating in nutrient-enriched variants targeting sports nutrition and senior dietary applications.
EU REACH and EFSA novel food frameworks govern protein ingredient introductions, while FDA GRAS self-affirmation shapes US market entry pathways for new suppliers. Organic certification under USDA National Organic Program and EU Organic Regulation creates dual compliance burdens that filter out smaller millers. Stakeholders must monitor evolving protein content threshold definitions in front-of-pack labeling rules across multiple jurisdictions to anticipate reformulation cycles and specification shifts.
Market Dynamics
Protein fractionation technology is splitting faba bean processing capacity between whole-flour milling and isolate extraction, creating supply bottlenecks for traditional bakery-grade flour buyers.
Growth Catalysts
- EU Novel Food Framework:EFSA approval pathways for protein ingredients are streamlining market entry for concentrated faba bean products across member states.
- Gluten-free pasta manufacturing:Italian and German extrusion facilities are reformulating durum wheat lines to incorporate faba bean flour for celiac-safe product ranges.
- Plant protein clustering in Lower Saxony:Dense supplier networks around ingredient technology hubs are reducing logistics costs for industrial flour procurement.
Market Restraints
- Pulse crop price volatility:Canadian prairie weather variability and acreage competition with canola are destabilizing raw material costs for millers.
- Specialized dehulling equipment scarcity:Limited European manufacturers of cotyledon-splitting machinery are extending lead times for capacity expansion projects.
- Soy protein isolate substitution:Established supply chains and lower unit economics for soy are pressuring faba bean flour pricing power in sports nutrition applications.
Strategic Opportunities
- Underpenetrated Spanish market:Limited domestic pulse processing infrastructure creates import-dependent gaps for organic flour distribution.
- Cell-cultured meat binder applications:Hybrid protein scaffolds combining faba bean flour with novel fermentation-derived ingredients are emerging in alternative protein R&D pipelines.
- French Agri-Environmental Policy:CAP eco-scheme incentives for protein crop rotation are expanding contracted acreage for food-grade faba bean cultivation.
Industry Challenges
- Food-grade milling expertise scarcity:Retiring European millers and limited vocational training programs are constraining operational scale-up for precision particle-size production.
- Dual organic certification complexity:Simultaneous USDA National Organic Program and EU Organic Regulation compliance is extending product launch timelines by 8-14 months for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faba Beans Flour Market |
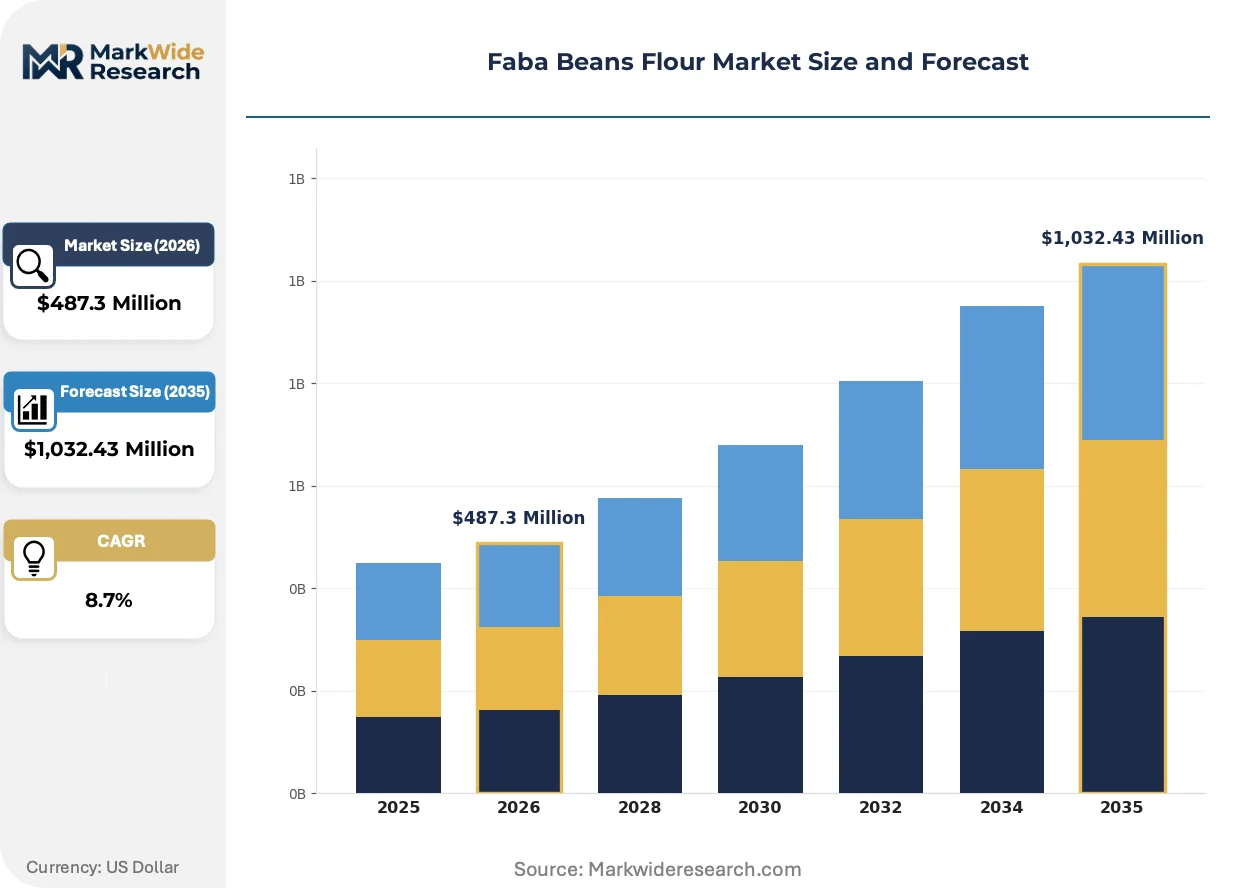
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Flour, Conventional Flour, Gluten-Free Flour, Nutrient-Enriched Flour End User: Food Industry, Bakery, Snack Manufacturers, Health Food Stores Application: Baking, Pasta Production, Snack Food, Nutritional Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Roquette Frères, BENEO GmbH, AGT Food & Ingredients, Ingredion Incorporated, Puris Foods, Bunge, The Scoular Company, Vestkorn Milling AS, Puratos Group SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faba Beans Flour Market Evolving Landscape
Processing technology and regulatory frameworks are diverging the faba bean flour market into distinct quality tiers and application-specific specifications.
Air classification systems for protein-starch separation are bifurcating the traditional flour market into premium protein concentrate streams and residual starch fractions. German bakery ingredient divisions at major millers are adopting these systems fastest, converting whole-bean capacity into isolate production. The structural consequence is compressing availability of standard bakery-grade flour for mid-market pasta and bread manufacturers.
REACH registration requirements for novel protein fractions are tightening purity and contaminant documentation standards across EU member states. Industrial buyers are now demanding batch-level vicine-convicine testing protocols that exceed baseline food safety thresholds. Italian organic pasta producers are responding by qualifying dedicated supply chains with integrated dehulling and testing capabilities.
Direct contracting between food manufacturers and prairie farm cooperatives is shortening procurement cycles and bypassing traditional grain merchant intermediaries. Large European bakery groups are establishing multi-year offtake agreements with Saskatchewan-based pulse growers. This pattern is most visible in Germany, where clean-label manufacturing clusters prioritize supply chain transparency for front-of-pack marketing claims.
Faba Beans Flour Market Segmentation
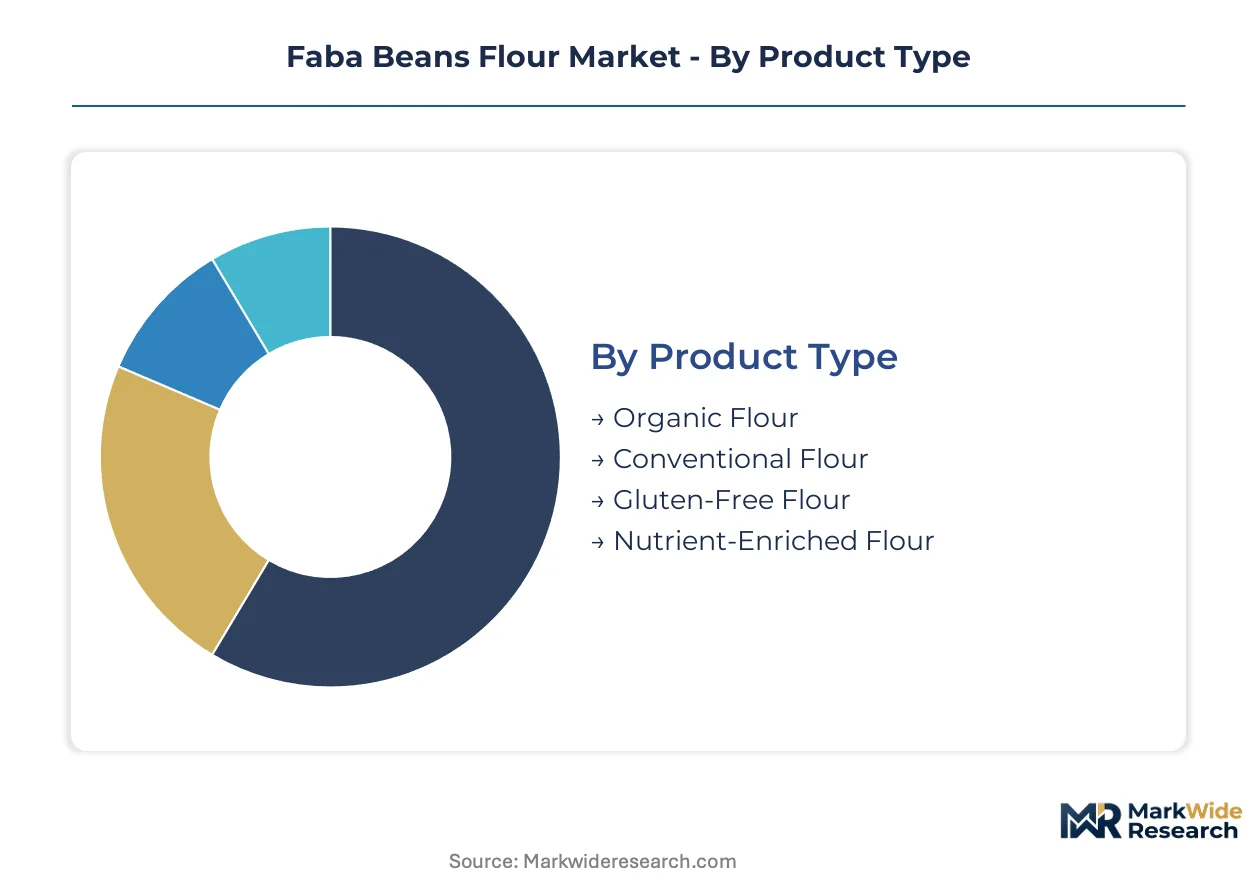
Segmentation in faba bean flour markets separates certification-grade premiums from commodity volume plays, with regulatory thresholds determining which tiers command sustainable margin structures versus price-sensitive bulk positioning.
Product Type:
EU Organic Regulation and USDA National Organic Program create the steepest compliance gradients between certified and conventional grades, with dual-certification requirements filtering supplier participation most aggressively at the premium tier.
- Organic Flour:Certification under EU Organic Regulation and USDA National Organic Program mandates segregated supply chains from field to mill. German clean-label manufacturers in Lower Saxony concentrate procurement here, absorbing 15-20% price premiums for front-of-pack marketing claims and supply chain transparency documentation.
- Gluten-Free Flour:Celiac-safe formulations meeting EFSA thresholds for gluten content below 20 ppm are displacing wheat in Italian extrusion facilities. Vicine-convicine batch testing protocols now exceed baseline food safety requirements, extending qualification timelines for new suppliers.
- Conventional Flour:Volume base for industrial bakery and pasta applications with minimal certification overhead.
- Nutrient-Enriched Flour:Targeted fortification for sports nutrition and senior dietary segments with protein concentrate additions.
Conventional flour handles the majority of throughput; gluten-free flour is expanding most quickly on share.
End User:
Customer scale and formulation sophistication create divergent procurement patterns, with large industrial buyers extracting supply chain transparency concessions unavailable to fragmented retail channels.
- Food Industry:Industrial pasta and extruded product manufacturers dominate volume offtake, with German and Italian facilities reformulating durum wheat lines for protein-enriched and gluten-free ranges. Direct contracting with Saskatchewan prairie cooperatives is shortening procurement cycles and bypassing traditional grain merchants.
- Bakery:Artisan and industrial bakers utilize 80-200 micron particle sizes for bread and pastry applications, with air classification systems bifurcating supply into protein concentrate streams and residual starch fractions.
- Snack Manufacturers:Extruded and baked snack applications requiring consistent hydration properties and clean-label ingredient declarations.
- Health Food Stores:Small-format retail with certified organic and allergen-free positioning for consumer-direct sales.
Food industry buyers capture the deepest volume discounts; bakery segment is climbing the fastest on reformulation activity.
Application:
Processing technology requirements and finished-product protein targets determine specification granularity, with pasta and baking applications demanding tighter particle-size distributions than nutritional supplements.
- Baking:Bread and pastry formulations requiring 25-30% protein content and controlled starch gelatinization properties during thermal processing.
- Pasta Production:Italian extrusion facilities in Emilia-Romagna and Puglia are converting durum wheat capacity to faba bean-durum blends, with EFSA novel food frameworks streamlining concentrated protein product introductions.
- Snack Food:Extruded and sheeted products leveraging faba bean flour for protein fortification and clean-label positioning.
- Nutritional Supplements:Protein concentrate and isolate applications competing with established soy protein isolate supply chains on unit economics.
Baking absorbs the largest volume base; pasta production is gaining share fastest on celiac-safe product line expansion.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with industrial direct sales commanding integrated testing protocols and retail channels handling standardized grades.
- Direct Sales:Multi-year offtake agreements between European bakery groups and prairie farm cooperatives, with batch-level vicine-convicine documentation and integrated dehulling capabilities.
- Supermarkets:Packaged consumer flour for home baking with organic and gluten-free shelf positioning.
- Specialty Stores:Premium organic and allergen-free grades with supply chain transparency marketing.
- Online Retail:Direct-to-consumer niche positioning for specialty diet segments and regional market access.
Direct sales channels move the heaviest volume; online retail is expanding most quickly on geographic reach extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes faba bean flour primarily through clean-label bakery clusters, while Italy channels volumes into gluten-free pasta extrusion. Canadian prairie origination feeds North American and European industrial buyers through direct cooperative contracting. Spanish demand outstrips domestic milling capacity, creating import-dependent supply gaps.
Germany
Lower Saxony hosts Europe's densest plant-protein ingredient cluster, with industrial buyers prioritizing supply chain transparency documentation. EFSA novel food frameworks streamline concentrated protein product introductions for German manufacturers. Clean-label manufacturing infrastructure in Hamburg and Bremen is absorbing 15-20% organic flour price premiums for front-of-pack marketing claims.
Italy
Emilia-Romagna and Puglia extrusion facilities are converting durum wheat capacity to faba bean-durum blends for celiac-safe product ranges. REACH registration requirements tighten purity and contaminant documentation standards for Italian organic pasta producers. Integrated dehulling and vicine-convicine testing capabilities are qualifying dedicated supply chains in northern processing hubs.
Canada
Saskatchewan prairie farm cooperatives are executing multi-year offtake agreements with European bakery groups, bypassing traditional grain merchant intermediaries. Canadian prairie weather variability and canola acreage competition destabilize raw material costs for export-oriented millers. Direct contracting patterns concentrate in Alberta and Manitoba pulse-growing regions.
Spain
Limited domestic pulse processing infrastructure creates import-dependent gaps for organic flour distribution across Castile-León and Aragón growing regions. CAP eco-scheme incentives for protein crop rotation are expanding contracted acreage, yet milling capacity lags cultivation growth. Barcelona and Madrid distribution hubs handle majority import volumes from French and Belgian suppliers.
France
Hauts-de-France and Grand Est protein crop rotations are expanding under Agri-Environmental Policy incentives, though food-grade milling expertise scarcity constrains operational scale-up. ANSM batch-level documentation requirements exceed baseline food safety thresholds for vicine-convicine testing. Lille and Strasbourg ingredient technology clusters are reducing logistics costs for industrial flour procurement.
Faba Beans Flour Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the faba bean flour market. Roquette Frères and BENEO GmbH anchor the upper tier through decades of European pulse processing infrastructure and deep backward integration into regional supply chains. Mid-cap specialists concentrate on organic certification and gluten-free qualification protocols. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as protein fractionation technology splits processing capacity between whole-flour milling and isolate extraction.
Within the integrated processor archetype, Roquette Frères exemplifies sustained supply continuity for industrial buyers through established European infrastructure. BENEO GmbH occupies a position anchored by Belgian chicory and pulse supply chain integration. AGT Food & Ingredients represents the North American origination tier with prairie farm cooperative contracting networks. These three entities illustrate how geographic supply chain control and certification-grade positioning separate premium-tier participants from commodity-volume competitors.
| Leading Market Players |
|---|
| Roquette Frères |
| BENEO GmbH |
| AGT Food & Ingredients |
| Ingredion Incorporated |
| Puris Foods |
| Bunge |
| The Scoular Company |
| Vestkorn Milling AS |
| Puratos Group SA |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for specialized cotyledon-splitting machinery from limited European manufacturers compress pricing power for capacity-constrained millers while amplifying premiums for organic-certified output. Food-grade pulse milling expertise scarcity tightens supply availability for standard bakery-grade flour, pushing industrial buyers toward multi-year offtake structures that lock in volume but sacrifice price flexibility.
Pricing Analysis
Long-term offtake agreements dominate procurement between European bakery groups and prairie farm cooperatives, displacing spot-market transactions for industrial volumes. Pricing stratifies across premium, standard, and economy tiers with certification grade and volume scale as primary differentiation drivers. Cost compression in conventional flour is intensifying because soy protein isolate substitution pressures unit economics in sports nutrition applications. Snack manufacturers exhibit highest price sensitivity due to thin formulation margins, while organic pasta producers absorb 15-20% premiums for supply chain transparency documentation.
Supply Chain Analysis
Specialized dehulling equipment scarcity in Germany and France constrains European milling capacity expansion despite rising cultivation acreage. Raw material flows draw from Canadian prairie origination, Belgian chicory-pulse integration zones, and Lower Saxony plant-protein clusters. Single-source vulnerability concentrates in Saskatchewan cooperative contracting networks exposed to prairie weather variability. Distribution runs through direct sales channels with integrated testing capabilities, bypassing traditional grain merchant intermediaries for qualified industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
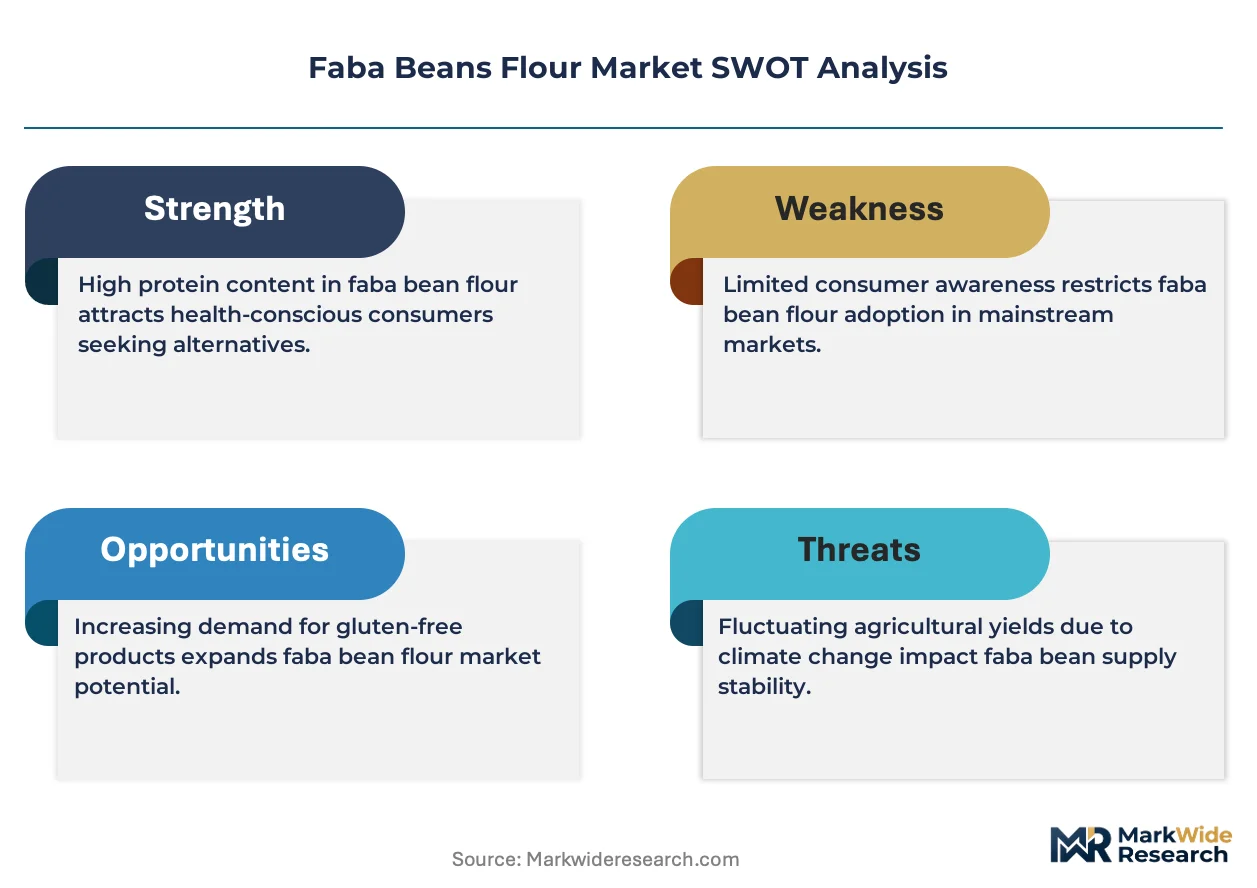
Protein fractionation technology is disrupting traditional whole-bean flour economics, with EFSA novel food frameworks accelerating concentrated product introductions that split processing capacity between milling and isolate extraction.
For Market Incumbents: Compound backward integration into prairie farm cooperative networks to secure origination control against direct-contracting competition from European bakery groups. Add dedicated dehulling and vicine-convicine testing capabilities in northern Italian processing hubs to qualify supply chains for organic pasta producers facing REACH registration tightening. For New Entrants and Emerging Players: Gluten-free certification service gaps in Spanish import-dependent markets offer white-space entry where domestic milling capacity lags cultivation growth. Target Castile-León and Aragón growing regions with Barcelona distribution hub partnerships, positioning on rapid EFSA novel food approval navigation for celiac-safe product ranges. For Investors and Strategic Acquirers: Long-term, this sits as a protein-transition infrastructure play because plant-based ingredient clustering in EU clean-label manufacturing zones creates durable demand for certified supply chain assets. Acquire mid-cap specialists with dual USDA-EU organic certification capabilities and integrated dehulling infrastructure. Watch CAP eco-scheme incentive adjustments as acreage expansion inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Cooperatives | Saskatchewan prairie contracting networks bypass grain merchants and secure supply chain transparency documentation for German clean-label manufacturers. |
| Integrated Dehulling Capacity Expansion | Northern Italian processing hubs with batch-level vicine-convicine testing qualify dedicated supply chains for REACH-registered organic pasta producers. |
| Dual Organic Certification Investment | Simultaneous USDA National Organic Program and EU Organic Regulation compliance filters smaller competitors and extends product launch timelines for cross-Atlantic suppliers. |
| Protein Fractionation Technology Adoption | Air classification systems bifurcate traditional flour markets into premium concentrate streams, compressing standard bakery-grade availability for mid-market manufacturers. |
| Direct Sales Channel Development | Multi-year offtake agreements with integrated testing protocols capture industrial volume discounts unavailable through fragmented retail channels. |
Research Methodology
Operator-level perspectives from pulse mill operations managers, food industry procurement directors, organic certification auditors, and specialty dehulling equipment manufacturers anchored the qualitative base. Secondary validation drew from EFSA novel food submission databases, EU Organic Regulation compliance registries, USDA National Organic Program operator lists, and Canadian prairie agricultural statistics. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Sensitivity analysis tested demand elasticity across certification grade, particle size specification, and end-use application dimensions throughout the forecast period. CAGRs derived from segmented growth trajectory analysis incorporating protein content threshold evolution in front-of-pack labeling rules and air classification technology adoption curves. Modeled inputs included prairie acreage competition with canola, EFSA approval pathway duration distributions, and clean-label manufacturing cluster expansion patterns.
Material uncertainties — regulatory threshold redefinitions, pulse crop yield volatility, and protein fractionation capacity allocation shifts — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EFSA novel food framework implementation and CAP eco-scheme incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Forage Feed Market