
 Sudan Alfalfa Market | 2026-2036
Sudan Alfalfa Market Size, Share, and Industry Trends Forecast 2026-2036
Sudan Alfalfa Market Analytics
Buyer concentration among large dairy and export operations is hardening across Sudan's alfalfa value chain. Syngenta leverages its global germplasm library to supply heat-tolerant alfalfa varieties suited to Sudan's irrigated schemes. DLF Seeds anchors its position through forage breeding programs calibrated for arid-zone production. Forage Genetics competes by emphasizing yield stability under extended drought cycles common to Sudan's central belt.
Alfalfa (Medicago sativa) is a perennial legume forage crop containing 15-22% crude protein on a dry-matter basis, cultivated under flood or pivot irrigation for repeated cuttings across Sudan's long growing season. Its primary purpose is high-protein animal feed for dairy cattle, sheep, and camels in domestic and export markets. Dehydrated alfalfa occupies the dominant value share due to longer shelf life and suitability for containerized export to Gulf buyers. Alfalfa pellets represent the fastest-expanding format as mechanized dairies seek standardized ration components with reduced storage losses. Premium quality grade commands disproportionate margin pools where RFV scores exceed 160 and leaf retention meets Saudi and UAE import specifications.
Sudan's Seed Administration under the Ministry of Agriculture enforces variety registration and field inspection protocols that determine which cultivars enter commercial multiplication. The country's national standards body applies moisture and foreign-matter thresholds that shape post-harvest handling investments by processors and exporters. Sudan's customs and quarantine frameworks coordinate with Gulf Cooperation Council veterinary authorities to align phytosanitary certificates with destination-market entry requirements. Stakeholders must monitor how irrigation water allocation policies along the Nile reshape plantable hectare forecasts and contract farming structures.
Market Dynamics
Buyer consolidation among River Nile dairy cooperatives and Port Sudan export houses is compressing supplier margins while elevating quality certification requirements across Sudan's alfalfa value chain. This concentration dynamic favors processors capable of meeting Gulf Cooperation Council phytosanitary standards.
Growth Catalysts
- Seed Certification Mandates:Sudan's Seed Administration under the Ministry of Agriculture enforces variety registration protocols that displace landrace cultivation with certified heat-tolerant germplasm, lifting yields in irrigated schemes.
- Gulf Livestock Import Demand:Saudi and UAE veterinary authorities sustain containerized dehydrated alfalfa purchases, pulling Sudanese export volumes toward RFV-160+ premium grades.
- Pivot Irrigation Expansion:Mechanized flood-to-pivot conversions in Gezira and White Nile states enable repeated cuttings across Sudan's extended growing season, boosting annual tonnage per hectare.
Market Restraints
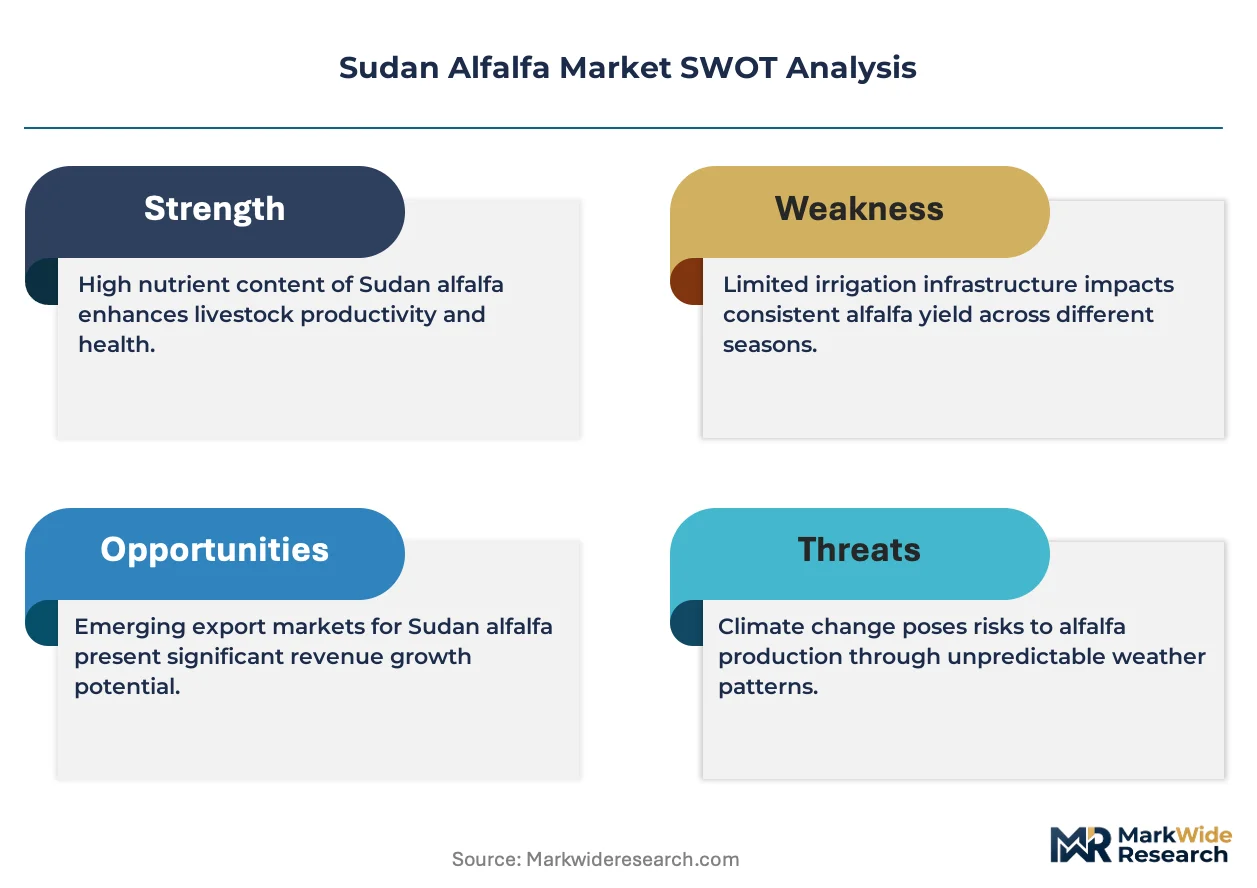
- Nile Water Allocation Constraints:Sudan's irrigation water licensing framework restricts plantable hectare expansion during low-flow years, capping upstream supply elasticity.
- Input Cost Volatility:Diesel pump irrigation and imported fertilizer expose growers to Sudanese pound exchange-rate swings, eroding margin predictability.
- Phytosanitary Rejection Risk:Gulf Cooperation Council quarantine authorities enforce moisture and foreign-matter thresholds that trigger container rejections at Port Sudan loading.
Strategic Opportunities
- Pellet Format Penetration:Mechanized dairies in Khartoum and River Nile states seek standardized ration components with reduced storage losses, opening conversion investment at processing facilities.
- Sub-National Irrigation Zones:White Nile and Sennar states harbor underdeveloped flood-irrigation acreage suitable for certified alfalfa expansion under contract farming structures.
- Dual-Crop Certification Pathways:Sudan's national standards body alignment with ISO forage quality protocols creates export-grade credibility for domestic processors.
Industry Challenges
- Field Inspection Bottlenecks:Sudan's Seed Administration variety registration queues delay commercial multiplication timelines for new heat-tolerant cultivars.
- Phytosanitary Certificate Coordination:Customs and quarantine documentation alignment with Saudi SFDA and UAE MOHAP veterinary authorities consumes working capital through extended inspection holds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sudan Alfalfa Market |
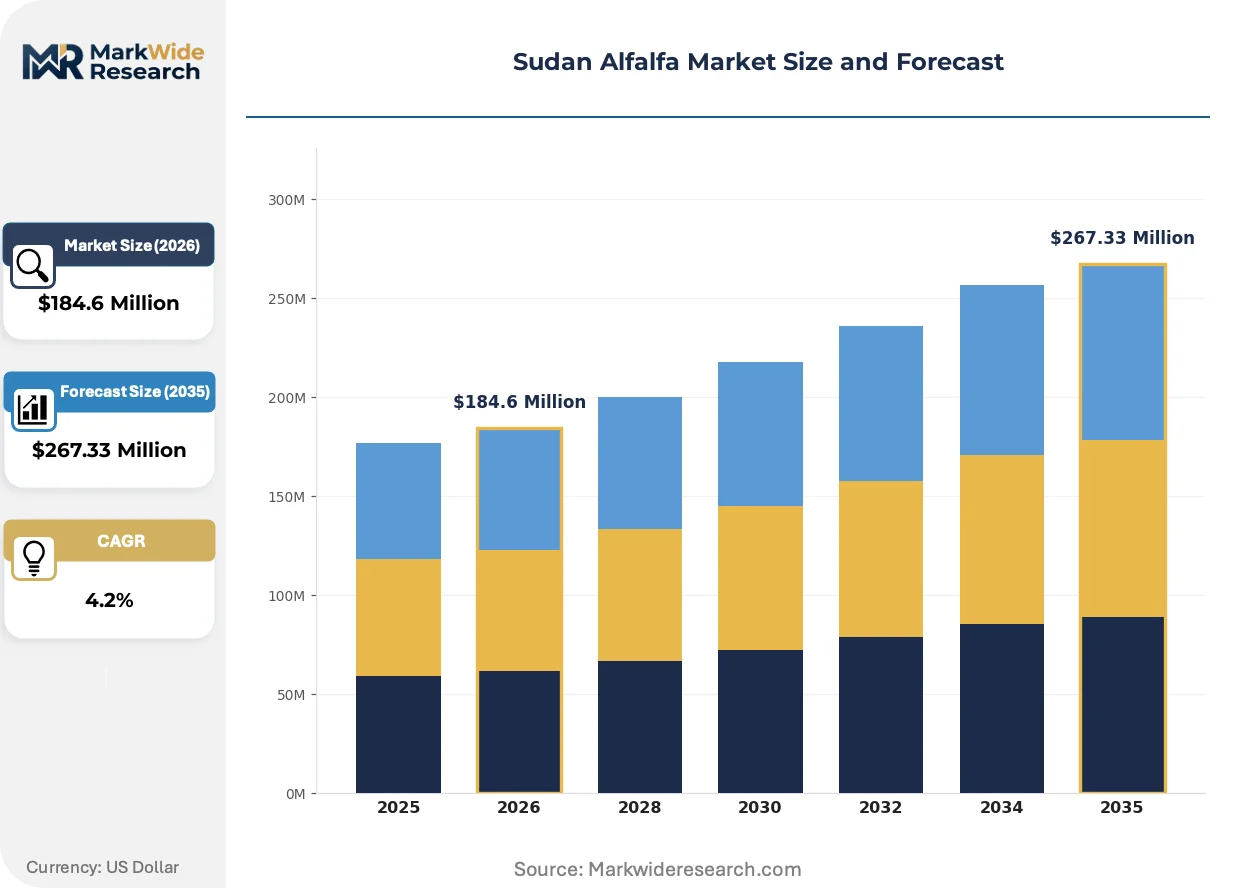
| Market Size in 2026 | $184.6 Million |
| Market Size in 2035 | $267.33 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Alfalfa, Alfalfa Cubes, Alfalfa Pellets, Fresh Alfalfa End User: Dairy Farms, Poultry Farms, Livestock Feed, Exporters Distribution Channel: Direct Sales, Retail, Online Platforms, Wholesale Quality Grade: Premium, Standard, Organic, Conventional |
| Companies Covered | Syngenta, Forage Genetics, DLF Seeds, Limagrain, Barenbrug, GLB Invest, ICS Agri, Amtar, Amtaar Investment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sudan Alfalfa Market Evolving Landscape
Mechanization and quality standardization are displacing manual harvesting and informal trading networks across Sudan's alfalfa sector. These shifts concentrate value capture among capitalized processors capable of meeting Gulf export specifications.
Center-pivot irrigation systems equipped with soil-moisture sensors are automating water application timing across Gezira scheme operations. Large dairy cooperatives in River Nile state are retrofitting flood-irrigated blocks with automated pivot infrastructure. This technology diffusion is automating labor scheduling while compressing seasonal yield variance for repeat-cutting regimes.
Sudan's Seed Administration variety registration protocols now require field inspection documentation and germplasm provenance tracing for commercial multiplication licenses. This regulatory tightening elevates entry barriers for uncertified seed traders while redirecting farmer procurement toward registered suppliers. Export-oriented operations near Port Sudan are responding by locking multi-year certified seed contracts to secure phytosanitary compliance.
Gulf livestock importers are consolidating procurement through direct processor relationships, bypassing traditional Khartoum-based trading intermediaries. This channel compression concentrates volume commitments among three to four large dehydration facilities with Saudi SFDA pre-clearance status. The shift is most visible in Red Sea state, where containerized pellet exports now bypass domestic spot markets entirely.
Sudan Alfalfa Market Segmentation
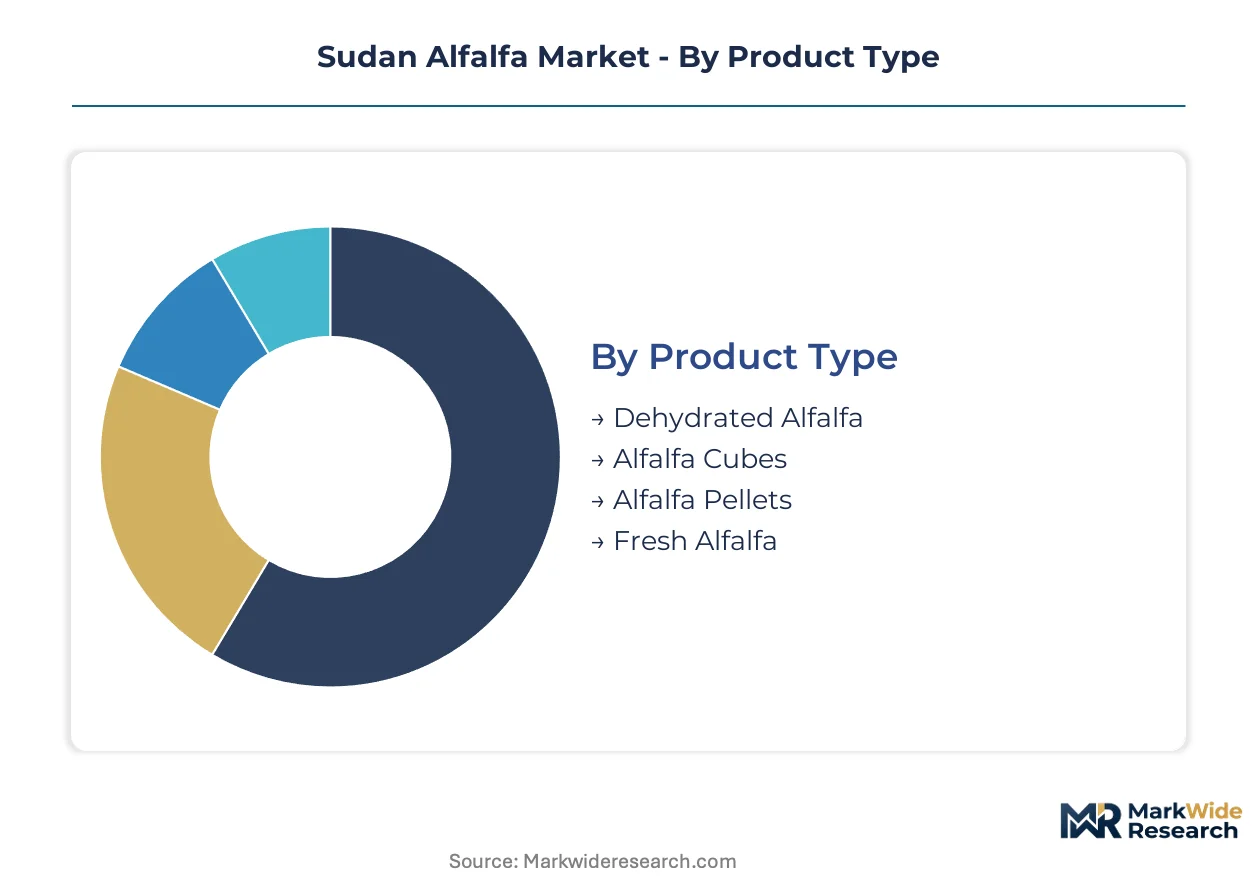
Alfalfa processors in Sudan face divergent capital requirements across product formats, with dehydration infrastructure demanding heavy upfront investment while fresh-cut operations run on minimal fixed assets. Segmentation by product type, end user, distribution channel, and quality grade reveals where capital deployment concentrates and where margin pools form.
Product Type:
Capital intensity varies sharply across processing formats, with thermal dehydration requiring the heaviest machinery investment and fresh-cut operations running on minimal equipment.
- Dehydrated Alfalfa:Field-cured and mechanically dried hay with 10-12% moisture content, processed through rotary drum or solar dehydration lines. River Nile dairy cooperatives and Port Sudan export houses dominate procurement, drawn by 18-month shelf life and Gulf Cooperation Council phytosanitary compliance. Sudan's customs and quarantine frameworks coordinate moisture certification with Saudi SFDA and UAE MOHAP veterinary authorities, making dehydration infrastructure a prerequisite for premium export access.
- Alfalfa Pellets:Compressed dehydrated material extruded into standardized 6-8mm cylinders, requiring pellet mills, cooling towers, and bagging lines. Mechanized dairies in Khartoum and Gezira states are shifting procurement toward this format to reduce storage losses and enable automated ration mixing. The format's density advantages lower container shipping costs for Red Sea state exporters serving Gulf livestock importers.
- Alfalfa Cubes:Larger compressed blocks (25-50mm) produced through high-pressure extrusion, favored by camel and sheep operations for reduced feed waste.
- Fresh Alfalfa:Direct-cut green material with 75-80% moisture, distributed within 48 hours to nearby livestock operations along the Nile corridor.
Most installed capacity flows through Dehydrated Alfalfa. Expansion is steepest in Alfalfa Pellets.
End User:
Customer scale determines procurement patterns, with large integrated operations driving contract structures while fragmented smallholders rely on spot markets.
- Dairy Farms:River Nile state cooperatives and Gezira scheme operations purchasing dehydrated and pelleted formats for high-protein ration formulation. These buyers are consolidating feed procurement through direct processor relationships, bypassing Khartoum-based trading intermediaries and locking multi-year supply contracts to secure phytosanitary compliance for downstream milk export certifications.
- Exporters:Port Sudan-based dehydration facilities and containerized pellet operations serving Saudi and UAE veterinary authority specifications. Gulf livestock importers are consolidating procurement through three to four large processors with Saudi SFDA pre-clearance status, concentrating volume commitments and compressing margins for non-certified suppliers.
- Livestock Feed:Sheep, camel, and beef cattle operations in White Nile and Sennar states consuming fresh-cut and cube formats through informal trading networks.
- Poultry Farms:Smaller-volume buyers of dehydrated leaf meal for protein supplementation in broiler and layer rations.
Dairy Farms absorb the largest tonnage volumes. Exporters are gaining share fastest on value terms.
Distribution Channel:
Channel selection tracks buyer scale and quality requirements, with large operations bypassing intermediaries while smallholders depend on layered distribution.
- Direct Sales:Processor-to-farm contracts for dehydrated and pelleted volumes, prevalent among River Nile dairy cooperatives and Port Sudan export houses. These arrangements lock pricing through growing seasons and embed quality certification obligations that satisfy Sudan's Seed Administration variety registration protocols and Gulf Cooperation Council phytosanitary standards.
- Wholesale:Khartoum-based traders aggregating fresh-cut volumes from White Nile and Sennar state growers for redistribution to livestock operations along the Nile corridor.
- Retail:Bagged dehydrated products through agricultural supply shops serving small-scale dairy and poultry operations.
- Online Platforms:Emerging digital procurement channels for standardized pellet orders by urban mechanized dairies.
Direct Sales channel the majority of export-grade volume. Wholesale retains dominance in fresh-cut distribution.
Quality Grade:
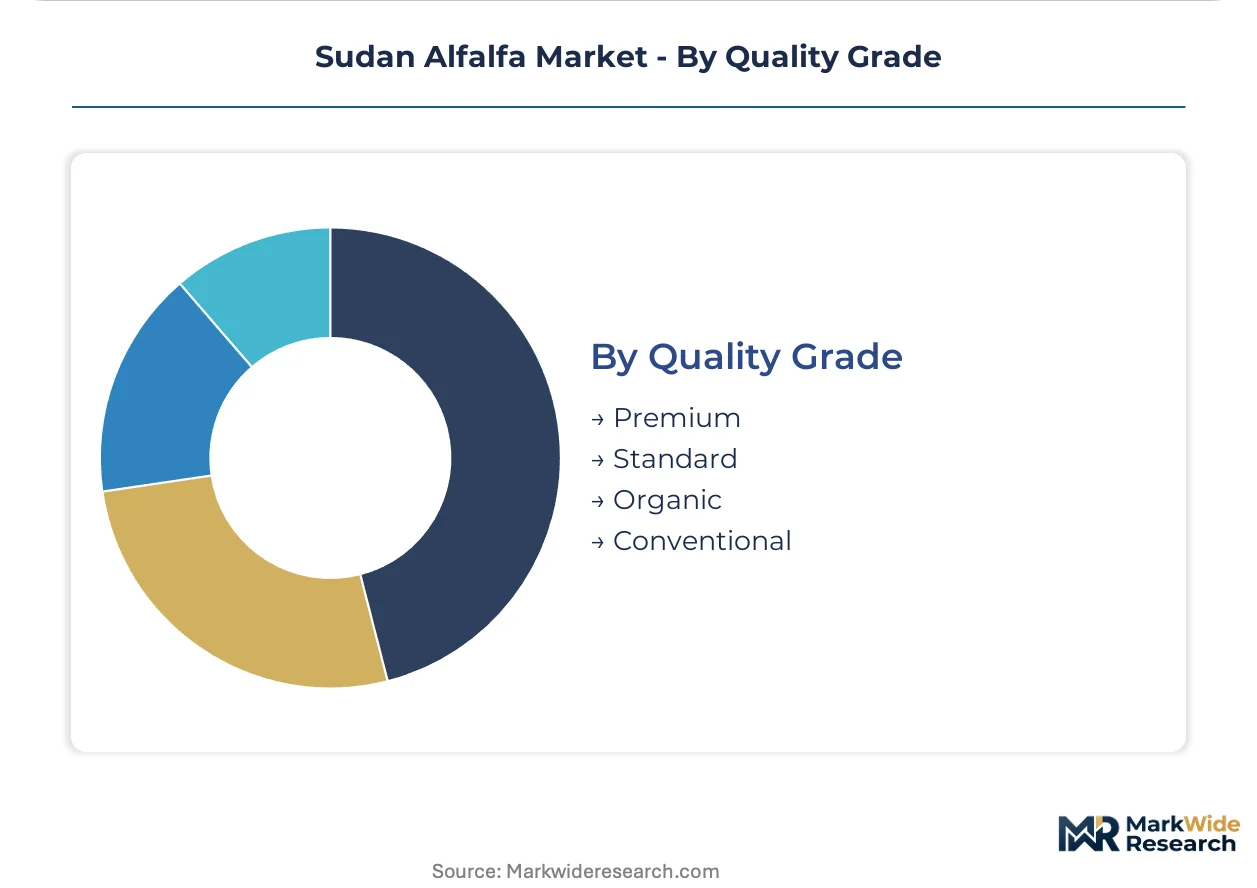
Grade stratification aligns with end-market regulatory thresholds, with premium grades commanding disproportionate margins where certification opens Gulf export access.
- Premium:RFV scores exceeding 160, leaf retention above 75%, and moisture content below 12%, meeting Saudi SFDA and UAE MOHAP import specifications. Port Sudan export houses concentrate procurement in this tier, where phytosanitary pre-clearance status enables containerized shipments to bypass extended inspection holds.
- Standard:RFV 130-160, acceptable for domestic dairy and feedlot operations without export certification requirements.
- Conventional:Uncertified field-cured material from landrace varieties, facing displacement as Sudan's Seed Administration enforces variety registration protocols favoring certified germplasm.
- Organic:Certified chemical-free production, nascent in Sudan's irrigated schemes due to input cost premiums and limited certification infrastructure.
Premium grade captures the dominant value share. Conventional grade is contracting fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE sustain the largest import volumes from Sudan, while domestic production clusters concentrate along the Nile corridor where irrigation access determines plantable acreage.
River Nile State
Dairy cooperatives in River Nile state are expanding alfalfa procurement as feed rations improve for milk export certification. Sudan's Seed Administration enforces variety registration protocols that displace landrace cultivation with certified heat-tolerant germplasm. Large integrated operations near Ed-Damer are locking multi-year supply contracts to secure phytosanitary compliance for downstream dairy exports.
Red Sea State
Port Sudan dehydration facilities are consolidating containerized pellet exports to Gulf livestock importers. Sudan's customs and quarantine frameworks coordinate moisture certification with Saudi SFDA and UAE MOHAP veterinary authorities. Export houses near the port are bypassing Khartoum-based trading intermediaries through direct processor relationships with three to four large dehydration facilities.
Gezira State
Mechanized flood-to-pivot irrigation conversions are enabling repeated cuttings across extended growing seasons. Sudan's national agricultural regulator applies field inspection protocols that determine which cultivars enter commercial multiplication. Large scheme operations near Wad Madani are retrofitting flood-irrigated blocks with automated pivot infrastructure.
White Nile State
Underdeveloped flood-irrigation acreage is attracting contract farming structures for certified alfalfa expansion. Sudan's irrigation water licensing framework restricts plantable hectare expansion during low-flow years. Grower-processor arrangements near Kosti are forming to supply dehydration facilities in neighboring states.
Sudan Alfalfa Market Competitive Landscape
European seed houses anchor the premium germplasm tier; Sudanese processors and Gulf-facing traders hold the export logistics tier. Supplier concentration is hardening around certified seed distributors capable of meeting Sudan's Seed Administration field inspection requirements and dehydration operators with Saudi SFDA pre-clearance status. Two strategic archetypes dominate: multinational breeders supplying heat-tolerant varieties and integrated processors controlling containerized export channels. Competitive moves center on multi-year certified seed contracts and direct procurement relationships that bypass traditional trading intermediaries.
Within the multinational breeder tier, Syngenta, DLF Seeds, and Forage Genetics exemplify divergent positioning archetypes. Syngenta leverages its global germplasm library to supply heat-tolerant varieties suited to Sudan's irrigated schemes. DLF Seeds anchors its position through forage breeding programs calibrated for arid-zone production. Forage Genetics occupies a position emphasizing yield stability under extended drought cycles common to Sudan's central belt. These three represent the primary certified seed sourcing options for export-oriented operations seeking phytosanitary compliance.
| Leading Market Players |
|---|
| Syngenta |
| Forage Genetics |
| DLF Seeds |
| Limagrain |
| Barenbrug |
| GLB Invest |
| ICS Agri |
| Amtar |
| Amtaar Investment |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap processors dominate Sudan's alfalfa dehydration infrastructure, concentrating supply-side discipline around Port Sudan export corridors while anchoring premium-grade pricing power through Saudi SFDA pre-clearance relationships. Their capital-light expansion relative to multinational agribusinesses lets them absorb Nile water allocation volatility without destabilizing contract pricing structures.
Pricing Analysis
Capacity additions in Gezira and White Nile states are reshaping price floors for standard-grade dehydrated alfalfa. Pricing stratifies across premium, standard, and economy tiers, with RFV-160+ certification and Saudi SFDA pre-clearance driving the premium tier. Cost compression in the standard tier is intensifying because diesel pump irrigation and imported fertilizer expose growers to Sudanese pound exchange-rate swings. Smallholder livestock operations in Sennar state exhibit the highest price sensitivity, while Port Sudan export houses with direct Gulf importer relationships show the least.
Supply Chain Analysis
Single-source vulnerability sits with Egyptian urea suppliers and UAE-based diesel traders feeding Sudan's pump irrigation networks. Geographic supply concentration centers on Sudan's Nile corridor, with secondary dependencies on Saudi and UAE veterinary certification authorities for export clearance. Raw material inputs draw from heat-tolerant certified seed varieties, diesel fuel for pump stations, and Egyptian nitrogen fertilizer. Logistics chokepoints at Port Sudan container terminals constitute the dominant supply chain risk. Distribution runs through processor-to-farm direct contracts for export-grade volumes and Khartoum-based wholesale networks for fresh-cut domestic supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sudan's alfalfa market represents a late-cycle quality story as Gulf livestock importers consolidate procurement around RFV-160+ specifications and phytosanitary pre-clearance status, displacing informal trading networks and uncertified landrace supply.
For Market Incumbents: To counter buyer consolidation among River Nile dairy cooperatives and Port Sudan export houses, dehydration operators should lock multi-year certified seed contracts with Syngenta and DLF Seeds to secure germplasm provenance tracing, while retrofitting flood-irrigated blocks with automated pivot infrastructure to compress seasonal yield variance. For New Entrants and Emerging Players: Begin with underdeveloped flood-irrigation acreage in White Nile and Sennar states, where contract farming structures for certified alfalfa expansion face limited incumbent saturation. Pellet format penetration among mechanized Khartoum dairies offers the most penetrable segment, with go-to-market anchored through direct processor relationships bypassing Khartoum trading intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap dehydration facilities lacking Saudi SFDA pre-clearance status but possessing pivot irrigation infrastructure and Nile water licenses. Long-term viability over a multi-year horizon hinges on Gulf import demand durability and Sudan's Seed Administration enforcement trajectory. The signal to watch is container rejection rates at Port Sudan loading, as sustained phytosanitary compliance failures would trigger Gulf importer sourcing diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Seed Contract Lock | Secures germplasm provenance tracing required by Sudan's Seed Administration field inspection protocols. |
| Pivot Irrigation Retrofit | Automates water application timing across Gezira scheme operations for repeated cutting regimes. |
| Saudi SFDA Pre-clearance Pursuit | Eliminates extended inspection holds at Port Sudan loading for containerized pellet exports. |
| Pellet Mill Capacity Addition | Captures mechanized dairy demand for standardized ration components with reduced storage losses. |
| Direct Processor Relationship | Bypasses Khartoum-based trading intermediaries consolidating Gulf livestock importer procurement. |
Research Methodology
Coverage spans Sudan's Nile corridor states and Gulf Cooperation Council import markets, with primary inputs from each. The analysis combines interviews with River Nile dairy cooperative procurement managers, Port Sudan export house operations directors, Sudan's Seed Administration field inspectors, and Gezira scheme irrigation engineers with secondary validation from Sudanese customs records, Saudi SFDA import notifications, UAE MOHAP veterinary certificates, and irrigation water licensing disclosures. Bottom-up acreage and yield estimates triangulate against top-down export volume data from Port Sudan container terminals.
Granularity-level modeling extends to product format, end user archetype, distribution channel, and quality grade certification tier. Volume and value outputs were derived through segment-level growth rate application across the projection horizon, with CAGRs anchored in certified seed adoption curves, pivot irrigation conversion rates, and Gulf importer specification tightening. Industry-specific forecast inputs include Nile flow variability indices and Sudanese pound exchange-rate sensitivity for diesel and fertilizer import costs.
Caveats apply where Nile water allocation restrictions during low-flow years, phytosanitary rejection spikes at Port Sudan, or Gulf importer sourcing diversification could materially shift the outlook. Forecasts reflect documented assumptions around regulatory enforcement continuity and import demand durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Australia Compound Feed Market