
 Saudi Arabia Poultry Meat Market | 2026-2036
Saudi Arabia Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Poultry Meat Market Analytics
The gap between premium chilled cuts and frozen commodity poultry is shifting as Saudi consumers trade up for convenience and perceived freshness. Almarai Company leverages its dairy-cold-chain infrastructure to dominate chilled distribution in Riyadh and the Eastern Province. Tanmiah Food Company anchors its position through backward integration into feed milling and hatchery operations, controlling cost volatility. Al Watania Poultry differentiates via scale, operating one of the Kingdom's largest slaughter and processing complexes near Buraydah.
Saudi Arabia poultry meat encompasses chicken products raised, slaughtered, and processed under halal standards, with carcasses typically chilled to 0-4°C within two hours of slaughter to preserve shelf life and comply with religious and food safety protocols. The category serves household cooking, restaurant supply, and industrial food manufacturing across the Kingdom. Whole chicken and chicken breasts lead volume due to their centrality in traditional Saudi cuisine and QSR menu engineering, while vacuum packs capture margin pools among health-conscious urban shoppers seeking extended freshness. Online stores represent the fastest-growing distribution channel, though modern trade still controls the bulk of value throughput through hypermarket chains.
The Saudi Food and Drug Authority enforces halal slaughter and cold-chain integrity standards that raise compliance costs but also consolidate market access toward certified operators. SFDA alignment with Gulf Standards Organization meat safety protocols further harmonizes cross-border trade within GCC markets. Stakeholders must monitor feed grain import policies and domestic wheat substitution programs, as these directly reshape production economics and regional competitive balance.
Market Dynamics
The Saudi Food and Drug Authority's tightened halal certification protocols are consolidating processing capacity toward certified operators while raising compliance barriers for smaller slaughterhouses. This regulatory compression is reshaping competitive positioning across the Kingdom's poultry value chain.
Growth Catalysts
- SFDA Halal Protocol Harmonization:The Saudi Food and Drug Authority's alignment with Gulf Standards Organization meat safety protocols is streamlining cross-border trade within GCC markets and opening export channels for certified processors.
- Quick-Service Restaurant Expansion:Hotel chains and fast-casual dining concepts are scaling poultry procurement as domestic tourism and dining-out frequency rise in Riyadh and Jeddah.
- Retail Cold-Chain Modernization:Chilled distribution infrastructure investment is extending shelf-life windows for vacuum-packed premium cuts, capturing margin pools among urban health-conscious shoppers.
Market Restraints
- Feed Grain Import Dependency:Domestic production economics hinge on imported soybean and corn, exposing margins to currency volatility and international commodity price swings.
- Slaughterhouse Concentration:Processing capacity clusters around Buraydah and Riyadh, creating geographic supply vulnerability and transport-cost penalties for distant retail markets.
- Water Scarcity Constraints:Poultry farming's water intensity faces pressure from the Kingdom's groundwater depletion policies, limiting flock expansion in traditional production zones.
Strategic Opportunities
- Eastern Province Underpenetration:Dammam and Khobar retail modernization lags Riyadh and Jeddah, creating whitespace for chilled distribution network expansion.
- Online Grocery Acceleration:E-commerce platforms are capturing share from traditional wet markets, enabling direct-to-consumer premium positioning bypassing wholesale layers.
- Wheat Substitution Programs:Government initiatives promoting domestic barley and sorghum cultivation offer feed-cost hedging for vertically integrated operators securing offtake agreements.
Industry Challenges
- Halal Certification Timeline Compression:SFDA's two-hour post-slaughter chilling mandate requires capital-intensive blast-chiller deployment, straining smaller processors' balance sheets.
- Veterinary Specialist Scarcity:The Kingdom's limited pool of qualified avian health professionals constrains flock biosecurity management at expanding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Poultry Meat Market |
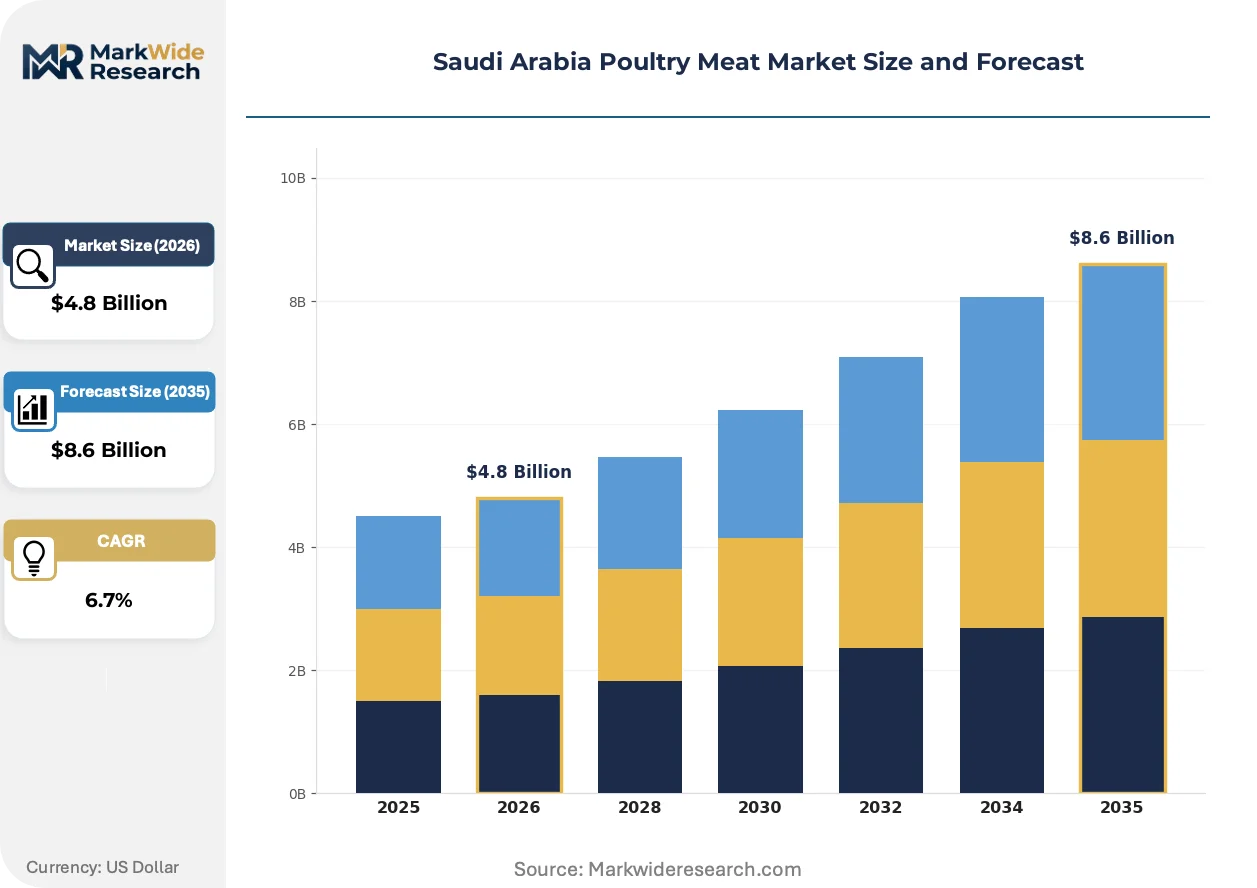
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Wings, Chicken Breasts, Chicken Thighs Distribution Channel: Modern Trade, Traditional Retail, Online Stores, Food Service Packaging Type: Tray Packs, Vacuum Packs, Canned, Bulk Packaging End Use: Household, Restaurants, Food Processing, Catering Services |
| Companies Covered | Americana Group Inc., ARASCO Foods, Al Watania Poultry, Almunajem Foods Co., Al Kabeer Group, Almarai Company, Sunbulah Group, JBS, Tanmiah Food Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Poultry Meat Market Evolving Landscape
Automation and digital traceability are penetrating Saudi poultry operations from hatchery to retail shelf. These shifts are compressing labor dependence while elevating compliance documentation standards.
Robotic deboning systems are automating labor-intensive breast and thigh processing tasks previously requiring skilled manual labor. Major processors are piloting these installations in Riyadh-area facilities to offset workforce constraints. The technology is automating throughput scaling without proportional headcount expansion, reshaping unit economics for high-volume operators.
SFDA's electronic halal traceability mandate requires real-time temperature logging and blockchain-verified chain-of-custody records from slaughter to point of sale. Processors must retrofit legacy cold-chain infrastructure with IoT sensors and cloud-based compliance dashboards. Chilled distribution specialists face the steepest adaptation costs, while frozen commodity handlers confront margin compression from delayed certification timelines.
Urban Saudi households are migrating from daily wet-market purchases toward weekly hypermarket stock-ups of vacuum-packed chilled cuts. This behavioral pivot favors products with fourteen-day shelf-life windows over traditional same-day slaughter consumption patterns. Jeddah's affluent districts exhibit the fastest adoption velocity, driving SKU proliferation in premium packaging formats.
Saudi Arabia Poultry Meat Market Segmentation
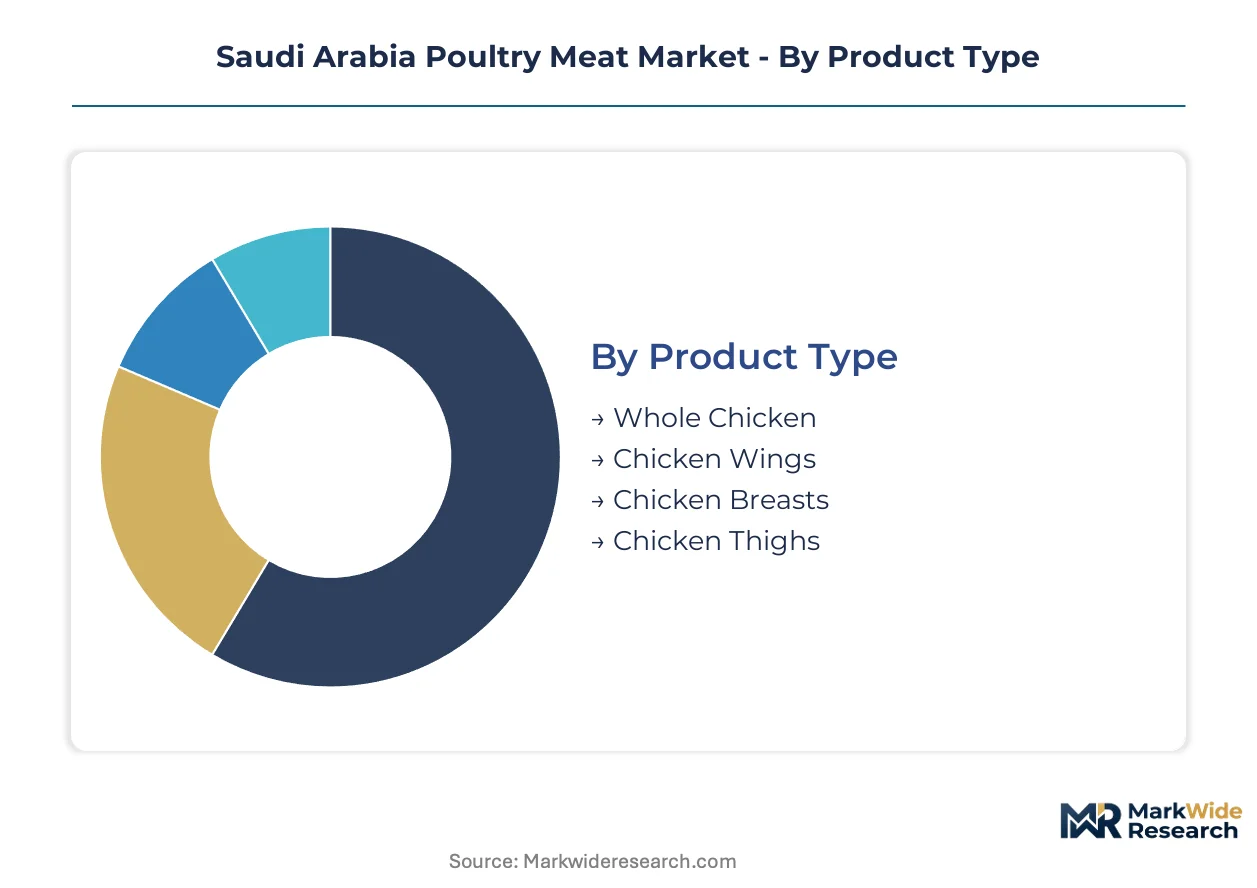
Saudi Arabia's poultry market segments reflect divergent cold-chain capabilities and consumer purchasing rhythms. Each dimension—product cut, channel, packaging, and end-use—carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning across Riyadh, Jeddah, and the Eastern Province.
Product Type:
Supply concentration in whole chicken and breast processing dominates Riyadh-area slaughterhouse output, while specialty cuts remain import-dependent.
- Whole Chicken:Carcasses chilled to 0-4°C within SFDA-mandated two-hour windows constitute the volume foundation of domestic slaughter operations. Riyadh and Buraydah processors prioritize whole bird throughput to maximize line efficiency, though retail margin compression limits differentiation.
- Chicken Breasts:Deboned breast meat commands premium positioning in hypermarket chilled cases and QSR procurement contracts. Jeddah's affluent districts drive fastest adoption of vacuum-packed fourteen-day shelf-life formats, displacing traditional same-day slaughter purchases.
- Chicken Wings:Secondary cut aggregation supports food service and casual dining segments with lower per-kilogram pricing.
- Chicken Thighs:Dark meat preference in traditional Saudi cuisine sustains steady household demand through wet market channels.
Today's leader: Whole Chicken. Tomorrow's challenger: Chicken Breasts.
Distribution Channel:
Channel economics stratify sharply between capital-intensive cold-chain operators and fragmented traditional retail.
- Modern Trade:Hypermarket chains control value throughput through temperature-controlled distribution centers and private label programs. Riyadh-based retailers anchor chilled poultry procurement, while Eastern Province modernization lags create whitespace for network expansion.
- Online Stores:E-commerce platforms bypass wholesale layers with direct-to-consumer fulfillment, climbing fastest among health-conscious urban shoppers seeking premium vacuum-packed SKUs.
- Traditional Retail:Wet markets retain volume in peripheral provinces but face margin erosion from SFDA traceability mandates.
- Food Service:Hotel chains and fast-casual concepts scale procurement through centralized contracts with certified processors.
Modern Trade captures present value. Online Stores are expanding most quickly.
Packaging Type:
Packaging investment separates premium positioning from commodity throughput.
- Vacuum Packs:Modified atmosphere packaging extends shelf life to fourteen days, enabling weekly stock-up behavior among Jeddah households. Chilled distribution specialists deploy blast-chiller infrastructure to meet SFDA cold-chain integrity standards.
- Tray Packs:Overwrapped foam trays dominate everyday retail through cost efficiency and familiar presentation.
- Bulk Packaging:Food service and industrial processors procure institutional volumes with minimal handling overhead.
- Canned:Shelf-stable formats serve emergency stockpiling and remote consumption with limited domestic production.
Vacuum Packs command margin expansion. Tray Packs defend volume position.
End Use:
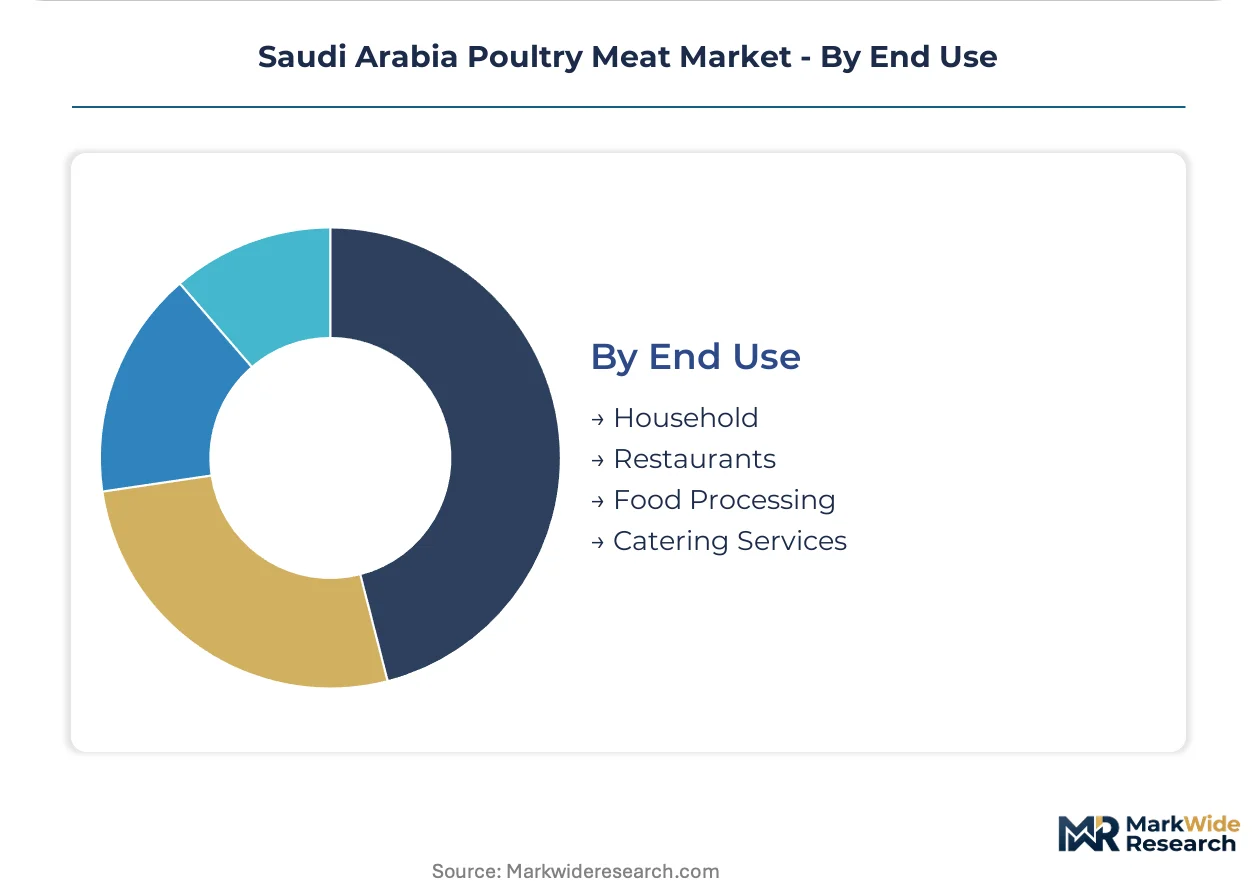
End-use concentration in household cooking is shifting as commercial channels professionalize procurement.
- Household:Weekly hypermarket stock-ups are displacing daily wet-market visits among urban Saudi families, favoring chilled convenience formats.
- Restaurants:QSR chains and hotel dining concepts in Riyadh and Jeddah drive standardized cut specifications and halal certification compliance.
- Food Processing:Industrial manufacturers source mechanically separated meat and standardized portions for further processing applications.
- Catering Services:Institutional feeding operations prioritize cost-controlled bulk supply with consistent portion weights.
Household consumption anchors volume. Restaurants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing specialists and cold-chain technicians cluster in Riyadh and the Eastern Province, anchoring the Kingdom's slaughterhouse capacity and distribution networks.
Riyadh
Urban household demand for vacuum-packed chilled cuts drives weekly hypermarket stock-up behavior across the capital's affluent districts. SFDA halal certification mandates concentrate compliant processing capacity within city limits. Al Watania Poultry operates one of the Kingdom's largest slaughter complexes on Riyadh's periphery, supplying standardized whole birds and deboned portions to modern trade channels.
Eastern Province
Dammam and Khobar retail modernization lags behind Riyadh and Jeddah, creating whitespace for chilled distribution network expansion. Government wheat substitution programs promoting domestic barley cultivation offer feed-cost hedging for operators securing offtake agreements. Almarai Company leverages its dairy-cold-chain infrastructure to dominate chilled poultry distribution across Dammam metropolitan zones.
Western Region
Jeddah's affluent districts exhibit the fastest adoption velocity for fourteen-day shelf-life vacuum packs, displacing traditional same-day slaughter consumption patterns. SFDA electronic halal traceability mandates require real-time temperature logging from slaughter to point of sale. Hotel chains and fast-casual dining concepts scale procurement through centralized contracts with Jeddah-area certified processors.
Qassim Region
Traditional poultry farming clusters around Buraydah face water scarcity constraints from Kingdom groundwater depletion policies. Tanmiah Food Company anchors regional supply through backward integration into feed milling and hatchery operations, controlling cost volatility. Slaughterhouse concentration near Buraydah creates geographic supply vulnerability and transport-cost penalties for distant retail markets.
Saudi Arabia Poultry Meat Market Competitive Landscape
Top-tier vendors anchor chilled distribution and QSR supply contracts, while mid-scale processors compete on frozen commodity throughput and wet-market penetration. The vendor base stratifies sharply between capital-intensive cold-chain operators and fragmented traditional slaughterhouses. Three archetypes dominate: vertically integrated feed-to-retail conglomerates, chilled distribution specialists leveraging dairy infrastructure, and scale-driven processors optimizing line efficiency. Competitive moves concentrate on M&A consolidation of compliant capacity and strategic partnerships with e-commerce platforms for direct-to-consumer fulfillment.
Within the integrated conglomerate tier, Almarai Company and Tanmiah Food Company exemplify divergent paths to market position. Almarai occupies a position as a chilled distribution specialist repurposing dairy cold-chain assets for poultry logistics. Tanmiah Food Company sits within the backward-integrated archetype, controlling production economics through captive feed milling and hatchery operations. Among scale-driven processors, Al Watania Poultry represents the high-volume slaughter complex model.
| Leading Market Players |
|---|
| Americana Group Inc. |
| ARASCO Foods |
| Al Watania Poultry |
| Almunajem Foods Co. |
| Al Kabeer Group |
| Almarai Company |
| Sunbulah Group |
| JBS |
| Tanmiah Food Company |
| Others |
Value Network & Pricing Analysis
Blast-chiller retrofitting across Buraydah and Riyadh processing complexes simultaneously compresses per-unit compliance costs and consolidates slaughter capacity toward SFDA-certified operators. This capital-intensive transition rewards scale players with pricing power over fragmented wet-market competitors while penalizing smaller facilities with margin-erosive upgrade timelines.
Pricing Analysis
Chilled distribution services bundle blast-chiller deployment, real-time temperature logging, and blockchain-verified halal traceability into premium per-kilogram rates, while frozen commodity poultry trades on unbundled spot pricing with minimal certification overhead. Price differentiation rests on SFDA compliance tier and cold-chain integrity grade, with vacuum-packed fourteen-day shelf-life formats commanding substantial premiums over tray-pack alternatives. Pricing pressure stems from feed grain import volatility and currency exposure, compressing margins at the economy tier. Quick-service restaurant procurement teams exhibit lowest price sensitivity due to halal certification non-negotiability, while traditional wet-market shoppers remain most responsive to per-kilogram fluctuations.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised chilled poultry—requiring immediate diversion to frozen processing or rendering—create complexity layers absent in ambient supply chains. Geographic supply concentration clusters in Saudi Arabia's Buraydah-Riyadh corridor and Brazil's southern poultry belt, with secondary flows from Thailand and France for specialty cuts. Raw material dependencies center on imported soybean and corn feedstock, alongside domestic barley substitution programs and veterinary pharmaceutical inputs. Supply chain risk manifests in single-source vulnerability for blast-chiller equipment and IoT sensor hardware. Distribution runs through hypermarket-controlled cold-chain distribution centers, with e-commerce platforms building parallel last-mile chilled fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia poultry meat offers margin-expansion pathways through chilled distribution premiumization and feed-cost hedging via domestic barley offtake agreements. The shift from daily wet-market purchases toward weekly vacuum-packed stock-ups creates pricing power for cold-chain specialists.
For Market Incumbents: Acquire blast-chiller infrastructure and IoT-enabled cold-chain assets to consolidate SFDA-compliant processing capacity before regulatory timeline compression eliminates smaller competitors. Defend market position by securing exclusive QSR supply contracts with Riyadh and Jeddah hotel chains, while deepening backward integration into domestic barley cultivation through government substitution program partnerships. For New Entrants and Emerging Players: The premium-economy price-point gap in Eastern Province chilled distribution offers white-space entry with lower competitive density than Riyadh or Jeddah. Target Dammam and Khobar retail modernization lag with direct-to-consumer e-commerce fulfillment, bypassing entrenched hypermarket wholesale layers. Pursue specialty cut import partnerships for wings and thighs underserved by domestic whole-bird processors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Buraydah processors facing water scarcity constraints and SFDA compliance cost burdens, creating distressed acquisition opportunities for well-capitalized consolidators. Long-term viability favors operators with captive feed milling and hatchery control across a five-to-ten-year horizon. Monitor SFDA electronic traceability mandate enforcement intensity as the signal for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Blast-chiller deployment in Eastern Province captures whitespace before retail modernization accelerates. |
| Backward Integration into Feed Milling | Captive barley offtake agreements hedge currency exposure from imported soybean and corn. |
| QSR Supply Contract Consolidation | Exclusive procurement relationships with Riyadh hotel chains lock in volume through certification stickiness. |
| E-Commerce Platform Partnership | Direct-to-consumer chilled fulfillment bypasses wholesale margin layers in Jeddah affluent districts. |
| SFDA Compliance Certification | Electronic halal traceability mandates create regulatory moats against non-compliant wet-market competitors. |
Research Methodology
Coverage spans Saudi Arabia's Riyadh, Jeddah, Eastern Province, and Qassim regions, with primary inputs from each market cluster. The analysis combines structured interviews with poultry processing executives, SFDA regulatory affairs specialists, hypermarket category buyers, and QSR procurement directors with secondary validation from SFDA halal certification filings, Saudi Customs import data, and Gulf Standards Organization meat safety protocol documentation. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Granularity-level framing applies country-level macro assumptions, regional cold-chain penetration rates, and product-format shelf-life economics across the projection horizon. Segmentation dimensions include product cut, distribution channel, packaging type, and end-use application, with additional modeling for halal certification tier and chilled-frozen format split. CAGRs derive from trend-line extrapolation adjusted for regulatory inflection points and feed grain price scenario analysis. Key forecast inputs incorporate SFDA compliance timeline enforcement and domestic barley substitution program uptake curves.
Caveats apply where SFDA regulatory acceleration, feed grain import policy shifts, or groundwater destriction enforcement could materially shift the outlook. Forecasts reflect assumptions about halal certification adoption rates and cold-chain infrastructure investment continuity. Practitioners should monitor SFDA electronic traceability mandate rollout pace and Brazil-Thailand import quota adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market