
 Mexico Compound Feed Market | 2026-2036
Mexico Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Compound Feed Market Foresight
Formulation-as-a-service is pivoting how compound feed producers monetize nutrition programs, shifting transactions from bulk commodity sales to precision diet subscriptions. Cargill leverages its vertically integrated supply chain to lock in large-scale poultry contracts across central Mexico. Nutreco anchors its position through advanced premix R&D facilities in Guanajuato. Alltech differentiates via yeast-based additive portfolios that command premium positioning.
Compound feed comprises blended nutritional formulations containing cereals, protein meals, fats, oils, and vitamins, manufactured through grinding, mixing, pelleting, and extrusion processes to deliver standardized metabolizable energy and digestible amino acid profiles for livestock production. Poultry formulations occupy the dominant volume share due to the vertical integration of Mexico's broiler industry, while aquaculture feed represents the fastest-expanding category as shrimp and tilapia producers intensify pond operations. Complete feed commands the largest revenue pool, though specialty feed for organic and antibiotic-free programs captures disproportionate margin concentration.
SADER enforces feed safety protocols through NOM-012-ZOO-1993, mandating contaminant thresholds and labeling standards that elevate compliance costs for smaller millers. BIS-equivalent voluntary standards for amino acid testing create additional quality benchmarks for exporters targeting premium livestock channels. Stakeholders must monitor pending amendments to Mexico's biosafety framework for genetically modified grain approvals, as import dependency for corn and soybeans amplifies exposure to regulatory delays.
Market Dynamics
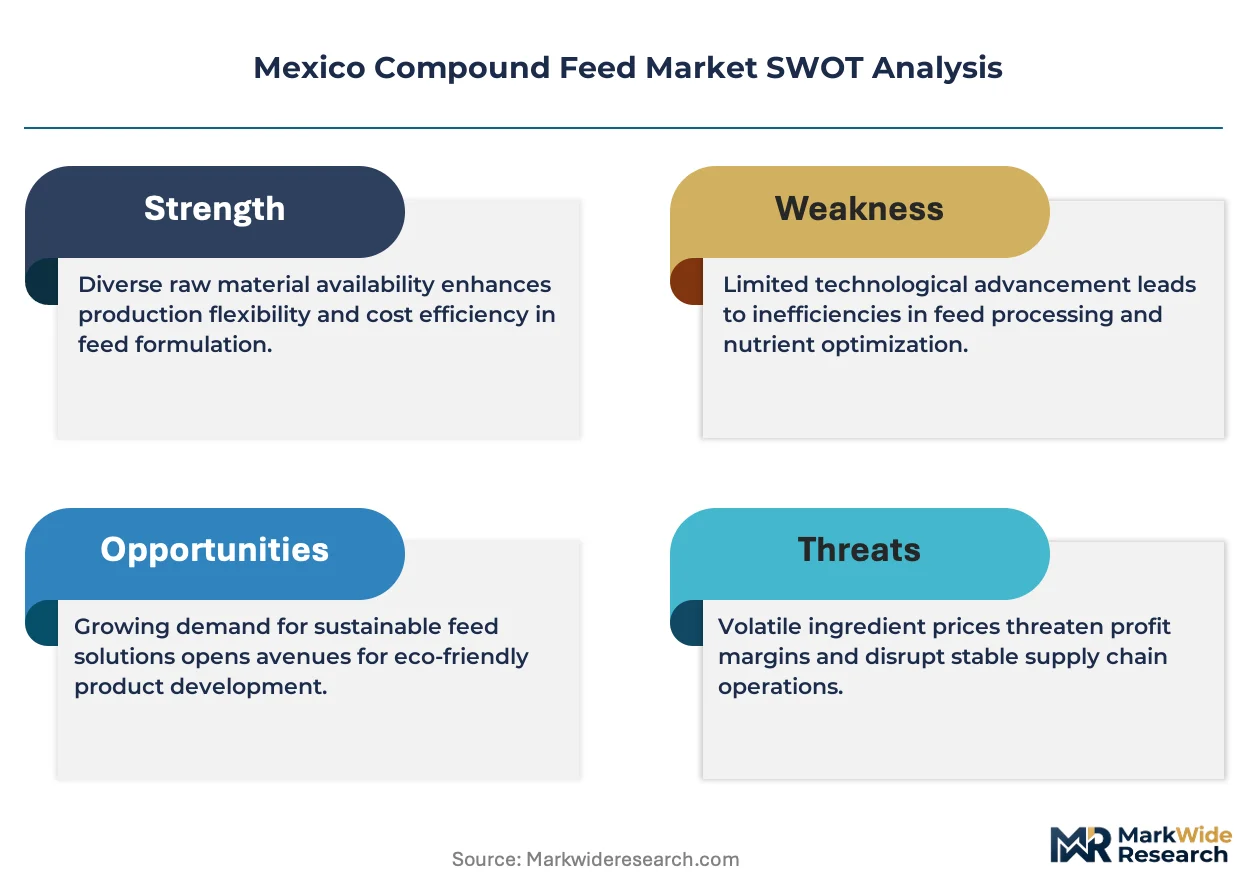
Poultry integrators in Jalisco and Guanajuato are compressing procurement cycles through captive nutrition programs, forcing independent millers to pivot toward subscription-based formulation services or exit volume markets entirely.
Growth Catalysts
- NOM-012-ZOO-1993:SADER's contaminant thresholds and mandatory labeling standards professionalize quality tiers, creating upgrade revenue for compliant producers serving export-oriented livestock channels.
- Shrimp and tilapia pond intensification:Aquaculture feed demand accelerates as producers in Sinaloa and Sonora expand stocking densities beyond traditional extensive systems.
- Jalisco livestock corridor concentration:Geographic clustering of broiler operations enables dedicated feed mill investments with dedicated logistics infrastructure and just-in-time delivery contracts.
Market Restraints
- Corn and soybean import dependency:Mexico's grain deficit exposes formulation costs to US Gulf basis volatility and peso-dollar exchange rate swings.
- Smallholder miller capital constraints:Compliance investments for SADER traceability systems and amino acid testing equipment exceed balance sheet capacity for sub-scale regional operators.
- Non-GMO certification complexity:Pending biosafety framework amendments for genetically modified grain approvals create formulation uncertainty for organic and antibiotic-free program suppliers.
Strategic Opportunities
- Yucatán Peninsula aquaculture expansion:Underdeveloped shrimp farming infrastructure offers first-mover positioning for extruded feed producers with technical service capabilities.
- Precision nutrition subscriptions:Formulation-as-a-service models monetize real-time diet optimization through sensor-enabled feed intake monitoring and algorithmic ration adjustment.
- BIS-equivalent amino acid testing:Voluntary quality benchmarks for premium livestock channels enable margin capture through certified metabolizable energy guarantees.
Industry Challenges
- Qualified nutritionist scarcity:Formulation expertise gaps constrain miller ability to execute precision diet programs for antibiotic-free and organic certification requirements.
- Extrusion equipment lead times:Aquaculture feed capacity expansion faces 18-24 month delivery cycles for twin-screw extruders, compressing investment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Compound Feed Market |
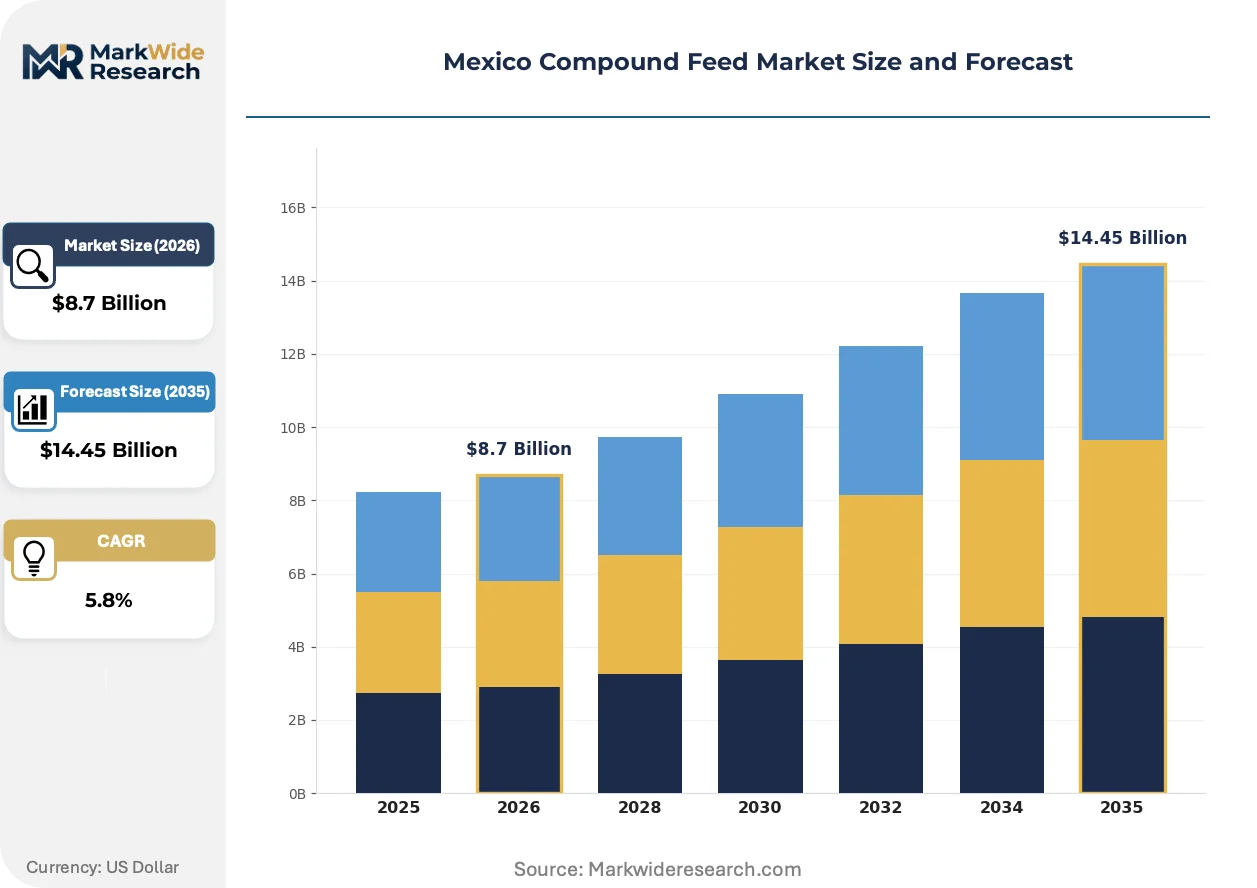
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Cereals, Protein Meals, Fats/Oils, Vitamins Animal Type: Poultry, Swine, Ruminants, Aquaculture Formulation Type: Complete Feed, Supplementary Feed, Medicated Feed, Specialty Feed Distribution Channel: Direct Sales, Retail, Online, Distributor |
| Companies Covered | Land O'Lakes, Kemin Industries, Cargill, Nutreco, Helm de Mexico, Archer Daniels Midland Company, United Animal Health, Neovia Group, Alltech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Compound Feed Market Shifts & Advancements
Digital ration optimization and alternative protein sourcing are restructuring how Mexican compound feed producers capture value, shifting competitive advantage from commodity scale to nutritional precision and ingredient flexibility.
Enzyme-supplemented formulations is consolidating cost structures across poultry operations by improving digestible amino acid extraction from conventional soybean meal. Large integrators in Guanajuato deploy these programs at commercial scale, reducing dependence on imported protein concentrates. The technology is consolidating procurement leverage for vertically coordinated supply chains while squeezing margin recovery for standard-formulation competitors.
SADER's pending amendments to Mexico's biosafety framework for genetically modified grain approvals are forcing reformulation strategies among import-dependent millers. The regulatory friction elevates non-GMO certification premiums and accelerates domestic sorghum and alternative starch sourcing investments. Organic and antibiotic-free program suppliers face the steepest compliance timeline compression as approval delays threaten consistent ingredient supply.
Buyer concentration among Jalisco-based poultry integrators is compressing contracting structures from spot commodity purchases toward multi-year nutrition service agreements. Independent producers lose volume access as captive supply chains absorb regional grinding capacity. The behavioral shift is most visible in central Mexico's broiler corridor, where integrators now specify metabolizable energy guarantees rather than ingredient composition in procurement tenders.
Mexico Compound Feed Market Segmentation
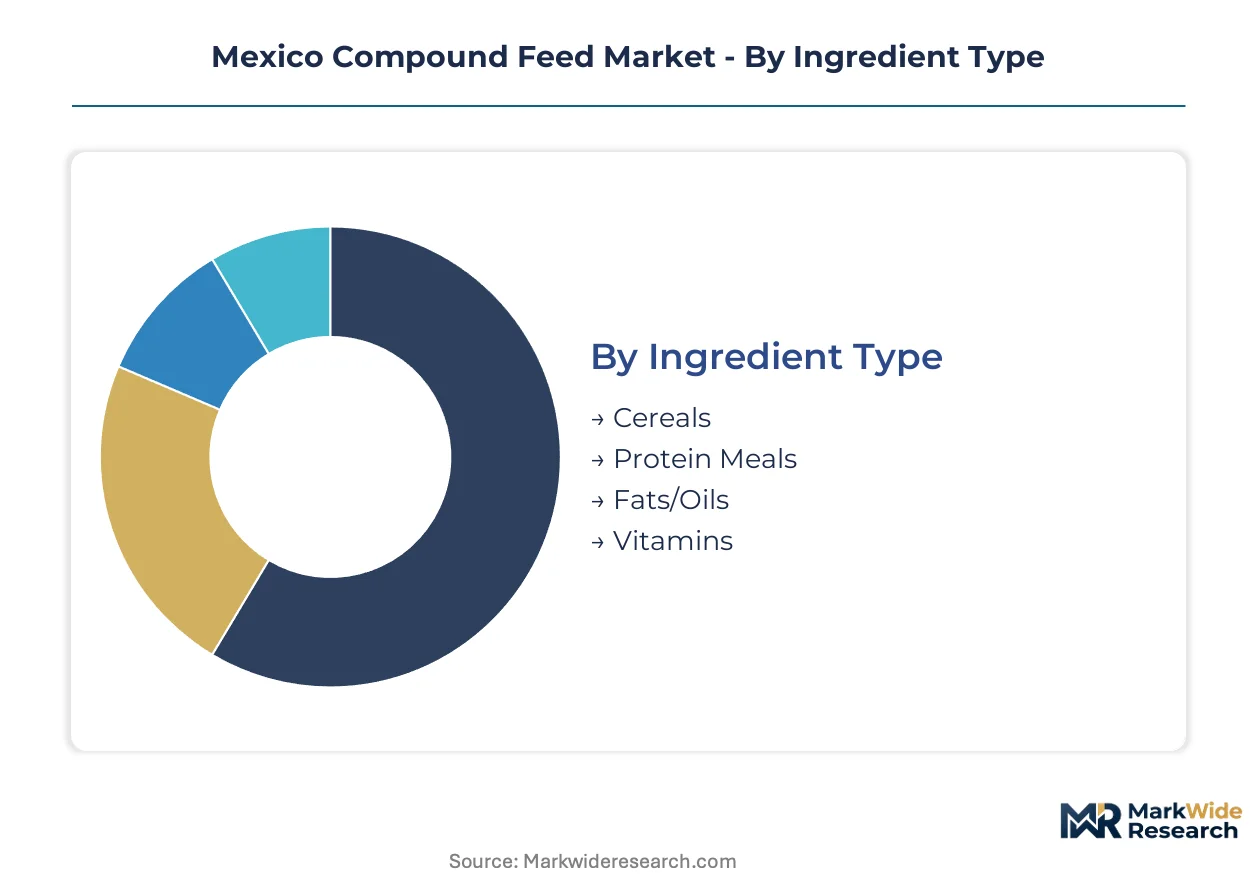
Ingredient composition, animal physiology requirements, and distribution logistics create distinct margin profiles across Mexico's compound feed landscape. SADER's NOM-012-ZOO-1993 mandates differential contaminant thresholds by formulation type, elevating compliance complexity for specialty and medicated categories.
Ingredient Type:
Cereals and protein meals carry the heaviest SADER certification burden under NOM-012-ZOO-1993 contaminant protocols, while vitamin premixes face additional BIS-equivalent amino acid testing requirements for export-channel eligibility.
- Cereals:Corn and sorghum constitute the primary energy base, with formulation costs exposed to US Gulf basis volatility and peso-dollar exchange rate swings. Jalisco's poultry integrators concentrate demand through captive procurement programs that lock in volume commitments twelve months forward.
- Protein Meals:Soybean meal dominates amino acid profiles, though enzyme-supplemented formulations are displacing imported concentrates in Guanajuato operations. Large integrators deploy phytase and protease programs at commercial scale, extracting digestible lysine from conventional meal rather than premium isolates.
- Fats/Oils:Vegetable and animal lipid sources standardize metabolizable energy density across thermal pelleted formulations.
- Vitamins:Premix R&D facilities in Guanajuato anchor micronutrient precision for antibiotic-free certification programs.
Cereals sit at the top of the volume ranking, with protein meals climbing the fastest as enzyme technology expands amino acid extraction efficiency.
Animal Type:
Species-specific nutritional specifications divide procurement patterns, with aquaculture feed commanding premium positioning due to extrusion complexity and water stability requirements.
- Poultry:Broiler and layer formulations absorb the dominant grinding capacity across central Mexico's vertically integrated supply chains. Jalisco-based integrators compress contracting structures toward multi-year nutrition service agreements that specify metabolizable energy guarantees rather than ingredient composition.
- Aquaculture:Shrimp and tilapia feed demands twin-screw extrusion for pond stability, with Sinaloa and Sonora producers intensifying stocking densities beyond traditional extensive systems. Yucatán Peninsula infrastructure gaps create first-mover positioning for technical service-capable suppliers.
- Swine:Grower-finisher diets adjust amino acid density by growth phase under SADER traceability mandates.
- Ruminants:Beef and dairy operations in northern states utilize bypass protein formulations for high-production lactation cycles.
Poultry sits at the top of the volume ranking, with aquaculture expanding most quickly as pond intensification accelerates feed conversion ratio optimization.
Formulation Type:
Regulatory tiering separates complete feed commodity sales from specialty margin capture, with medicated categories facing veterinary prescription requirements and organic programs demanding non-GMO certification complexity.
- Complete Feed:Fully balanced rations deliver standardized metabolizable energy and digestible amino acid profiles through grinding, mixing, pelleting, and extrusion processes. Jalisco's livestock corridor enables dedicated mill investments with just-in-time delivery infrastructure.
- Specialty Feed:Organic and antibiotic-free programs capture disproportionate margin concentration through certified metabolizable energy guarantees and BIS-equivalent amino acid testing. Pending biosafety framework amendments for genetically modified grain approvals threaten consistent ingredient supply for these suppliers.
- Supplementary Feed:Concentrates and premixes require on-farm blending with farm-grown grains.
- Medicated Feed:Veterinary feed directive protocols limit distribution to licensed prescription channels under SADER oversight.
Complete feed sits at the top of the volume ranking, with specialty feed gaining share fastest as export-oriented livestock channels professionalize quality tiers.
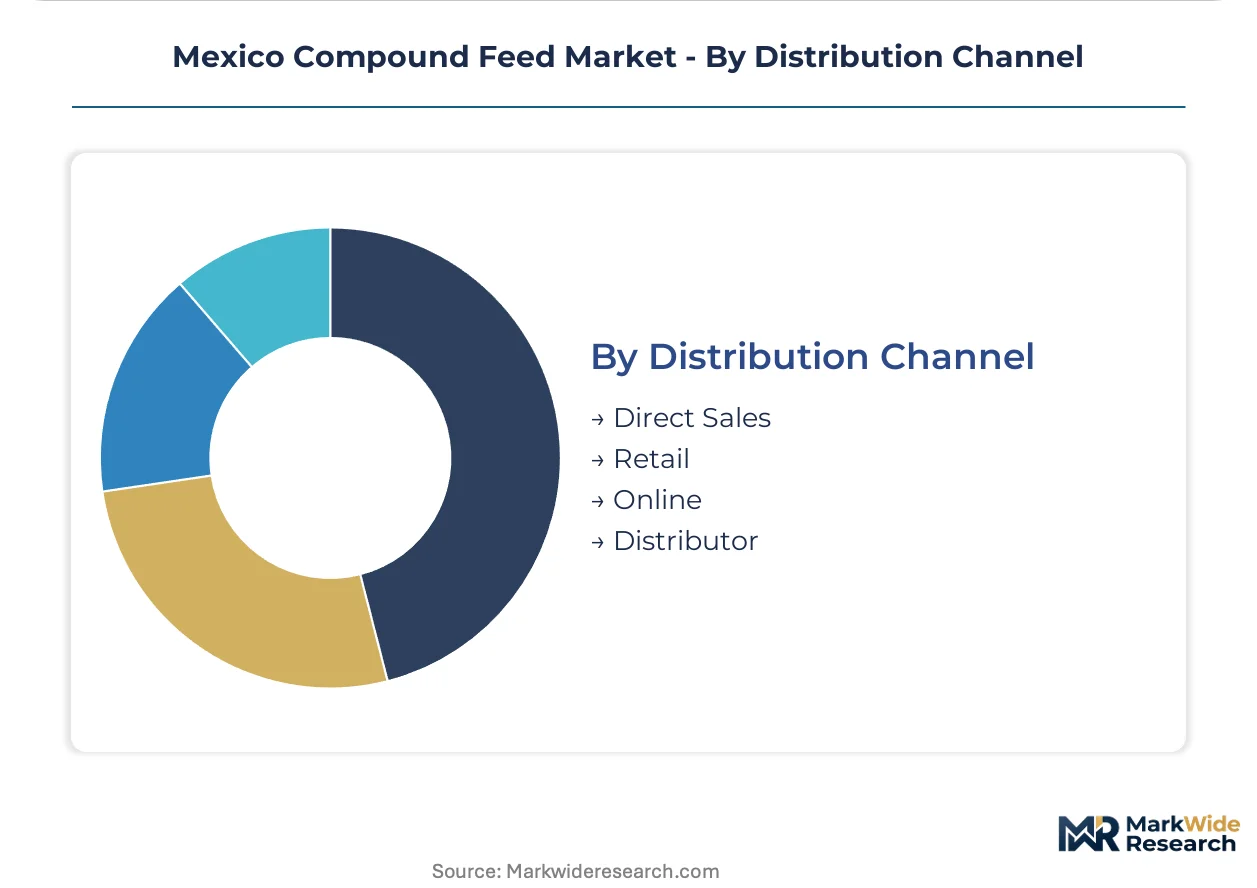
Distribution Channel:
Buyer concentration among poultry integrators is restructuring channel economics, compressing spot commodity purchases toward subscription-based formulation services with sensor-enabled intake monitoring.
- Direct Sales:Captive nutrition programs lock in large-scale contracts across central Mexico, with integrators specifying performance guarantees rather than ingredient inputs. Cargill leverages vertically integrated supply chain control to anchor these relationships.
- Distributor:Regional millers without formulation expertise rely on independent networks for smallholder access, though qualified nutritionist scarcity constrains precision diet program execution.
- Retail:Farm supply stores serve hobby and small-scale livestock operations with bagged complete feeds.
- Online:Digital platforms emerging for premix and additive procurement among mid-scale independent producers.
Direct sales sits at the top of the volume ranking, with distributor channels facing steepest compression as captive supply chains absorb regional grinding capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's compound feed market outpaces Brazilian growth in aquaculture feed adoption, while trailing US Midwest grain origination efficiency. Jalisco's poultry corridor concentrates domestic demand, with northern states and the Yucatán Peninsula emerging as distinct expansion zones.
Jalisco
Vertical broiler integration drives captive nutrition program adoption across the Guadalajara-Tequila livestock belt. SADER's NOM-012-ZOO-1993 traceability mandates force millers to upgrade grinding facilities for antibiotic-free certification compliance. Guanajuato-adjacent feed clusters absorb excess capacity as integrators consolidate procurement under multi-year performance contracts.
Nuevo León
Monterrey-based cattle feedlots expand bypass protein formulations for high-production dairy cycles. The state's industrial regulator enforces wastewater discharge standards that elevate extrusion equipment investment thresholds. Apodaca's logistics corridor enables just-in-time delivery contracts linking Sonora grain receipts to northern livestock operations.
Sinaloa and Sonora
Shrimp pond intensification accelerates extruded aquafeed demand across the Gulf of California rim. Federal biosafety framework uncertainty for genetically modified grain imports threatens consistent soybean meal supply for organic certification programs. Obregón's agricultural machinery cluster supports technical service capabilities for feed conversion ratio optimization.
Yucatán Peninsula
Underdeveloped shrimp farming infrastructure creates first-mover positioning for extruded feed producers with pond management expertise. State environmental authorities enforce mangrove protection buffers that constrain coastal pond expansion. Mérida's emerging logistics hub connects Campeche aquaculture operations to Gulf Coast ingredient suppliers.
Northern Border States
Chihuahua and Tamaulipas feed mills leverage US Gulf grain basis arbitrage for cost-competitive poultry formulations. Customs documentation requirements for cross-border corn shipments create inventory management complexity during peso volatility. Ciudad Juárez manufacturing parks attract premix R&D satellite facilities serving dual-market certification programs.
Mexico Compound Feed Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive nutrition programs concentrating volume among vertically integrated operators while independent millers retreat to distributor channels. The market structure favors scale-driven consolidation, as SADER compliance costs exceed sub-scale balance sheet capacity. Three archetypes dominate: multinational nutrition platforms with captive supply chains, regional premix specialists with R&D anchoring, and commodity millers pivoting toward formulation-as-a-service subscriptions. M&A activity targets amino acid testing capabilities, while capacity expansion concentrates in Jalisco's logistics corridor.
Within the multinational tier, Cargill, Nutreco, and Alltech occupy positions defined by supply chain control rather than product differentiation. Cargill's vertically integrated grain origination anchors large-scale poultry contracts across central Mexico. Nutreco's Guanajuato premix facilities exemplify R&D-driven positioning for antibiotic-free certification programs. Alltech represents yeast-based additive portfolios that command premium positioning through metabolizable energy guarantees rather than commodity volume competition.
| Leading Market Players |
|---|
| Land O'Lakes |
| Kemin Industries |
| Cargill |
| Nutreco |
| Helm de Mexico |
| Archer Daniels Midland Company |
| United Animal Health |
| Neovia Group |
| Alltech |
| Others |
Supply & Pricing Matrix
Jalisco-based poultry integrators command disproportionate pricing leverage through captive nutrition programs, compressing procurement toward multi-year performance contracts that specify metabolizable energy guarantees rather than ingredient composition. This buyer concentration forces independent millers into subscription-based formulation services or exit from volume markets entirely.
Pricing Analysis
Capacity additions in Guanajuato are reshaping price floors as enzyme-supplemented formulations displace imported protein concentrates. Three-tier pricing structure across premium, standard, and economy levels separates antibiotic-free certified programs from conventional formulations and commodity spot purchases. Pricing pressure stems from qualified nutritionist scarcity constraining precision diet execution. Smallholder millers exhibit highest price sensitivity as SADER compliance investments exceed balance sheet capacity.
Supply Chain Analysis
SADER's NOM-012-ZOO-1993 certification gates ingredient sourcing, with corn and soybean meal drawing from US Gulf origins and domestic sorghum alternatives. Vitamin premixes hinge on Guanajuato R&D facility output, while extrusion equipment feeds from European and Asian manufacturers. Single-source vulnerability concentrates in genetically modified grain import approvals pending biosafety framework amendments. Distribution runs through captive direct sales channels anchored by vertically integrated poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's compound feed market functions as a geographic-arbitrage play between US Gulf grain basis efficiency and SADER regulatory compliance costs that elevate domestic formulation premiums.
For Market Incumbents: Anchor backward integration into Guanajuato premix R&D capabilities to defend against enzyme-supplemented formulation displacement. Lock in Jalisco integrator relationships through sensor-enabled intake monitoring subscriptions that create switching costs. Prioritize amino acid testing certification investments ahead of pending biosafety framework amendments. For New Entrants and Emerging Players: Distributor networks in Yucatán Peninsula aquaculture corridors offer lowest penetration resistance against established Jalisco-centric competitors. Target shrimp pond intensification zones with technical service bundles combining extruded feed supply and pond management expertise. Lead with formulation-as-a-service positioning rather than commodity volume competition. For Investors and Strategic Acquirers: Multinational nutrition platforms with captive supply chains are the most active acquirers in this space, consolidating regional premix specialists for antibiotic-free certification capabilities. Five-to-ten year viability rests on SADER compliance cost escalation favoring scale over fragmentation. Watch for biosafety framework amendment timing as inflection trigger for non-GMO certification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix R&D | Guanajuato facilities anchor antibiotic-free certification programs for Jalisco integrators. |
| Sensor-Enabled Formulation Subscriptions | Real-time intake monitoring creates multi-year contract lock-in with poultry operations. |
| Yucatán Aquaculture Technical Service Expansion | Pond management expertise captures first-mover positioning in underdeveloped shrimp zones. |
| Enzyme-Supplemented Formulation Scale-Up | Phytase programs reduce dependence on imported protein concentrates in Guanajuato. |
| SADER Compliance Certification Investment | NOM-012-ZOO-1993 traceability systems professionalize quality tiers for export channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feed mill operations directors, poultry integrator procurement leads, SADER regulatory affairs specialists, and aquaculture pond managers with secondary validation against customs grain import records, SADER enforcement bulletins, SEC filings of listed nutrition companies, and regional agricultural machinery deployment data. Bottom-up capacity assessments triangulated against top-down consumption estimates.
Segment-weighting applied animal type, formulation category, and distribution channel dimensions across the projection horizon, with CAGRs derived from trend extrapolation moderated by regulatory event probability. Modeled inputs included enzyme adoption curves in Guanajuato operations, shrimp pond stocking density trajectories in Sinaloa, and peso-dollar exchange rate sensitivity for import-dependent formulations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosafety framework amendment timing and qualified nutritionist pipeline expansion. A model refresh is warranted upon material change in SADER enforcement intensity or genetically modified grain approval status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Middle East and Africa Bonsai Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Africa Olive Market