
 Rice Straw Market | 2026-2036
Rice Straw Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Straw Market Outlook
Animal feed formulation is shifting toward processed rice straw as dairy cooperatives in South Asia seek cost-effective roughage alternatives. Bee Chems leverages its chemical processing expertise to refine silica extraction from rice straw ash for industrial applications. Gia Gia Nguyen Co., Ltd. anchors supply chains across Mekong Delta farming networks, sustaining consistent raw material flows despite seasonal harvest variability. AGI MILLTEC competes on mechanized baling and densification systems that reduce transport costs for dispersed biomass collection.
Rice straw consists of lignocellulosic agricultural residue containing approximately 35-40% cellulose, 20-25% hemicellulose, and 15-20% silica by dry weight, generated after grain threshing and primarily valorized as feedstock for energy, materials, or soil amendment. Processed rice straw leads value capture through pelletization and chemical fractionation, while rice straw pellets represent the fastest-growing product type as power utilities in Vietnam and Indonesia adopt co-firing mandates. Raw rice straw bales dominate volume but command thinner margins due to bulk handling inefficiencies and seasonal price swings.
India's Central Pollution Control Board enforces the Graded Response Action Plan, which bans crop residue burning in northern states and mechanically redirects straw toward approved offtake channels. The EU Renewable Energy Directive II classifies agricultural residues as advanced biofuels feedstock, enabling compliance pathways for European energy producers sourcing certified Asian biomass. Stakeholders must monitor evolving carbon accounting methodologies under ISO 14064 and national biogenic CO2 frameworks, as these will determine which straw valorization routes secure premium offtake contracts.
Market Dynamics
India's Graded Response Action Plan mechanically redirects rice straw from field burning toward approved offtake channels, compressing supply windows and forcing rapid infrastructure buildout across the Indo-Gangetic Plain.
Growth Catalysts
- EU Renewable Energy Directive II:The classification of agricultural residues as advanced biofuels feedstock creates compliance pathways for European energy producers sourcing certified Asian biomass.
- Vietnam and Indonesia co-firing mandates:Power utilities in these markets are scaling pellet procurement, pulling processed straw into formal energy supply chains.
- Silica extraction chemistry:Industrial applications for rice straw ash are expanding as refiners develop higher-purity extraction protocols for rubber and coatings sectors.
Market Restraints
- Seasonal supply concentration:Harvest windows in Punjab, Haryana, and Uttar Pradesh create six-month procurement surges that strain storage and transport infrastructure.
- High-moisture handling costs:Raw bales require immediate densification or drying to prevent decomposition, adding processing capex before value capture.
- Competing soil amendment demand:Direct field return of rice straw retains nutrients for subsequent rice-wheat rotations, reducing volumes available for commercial offtake.
Strategic Opportunities
- Indonesian power sector:State-owned electricity procurement is formalizing biomass co-firing targets, creating new demand nodes outside traditional Indian supply chains.
- Anaerobic digestion integration:Biogas facilities can co-digest rice straw with dairy and poultry waste, unlocking carbon credit revenues under evolving ISO 14064 methodologies.
- Blockchain traceability:Digital provenance systems are emerging to verify no-burn collection, enabling premium pricing for certified-sustainable straw in European offtake contracts.
Industry Challenges
- Mechanical densification expertise:Operating baling and pelletizing equipment requires skilled technicians scarce in rural Punjab and Haryana.
- Carbon accounting standardization:Divergent national biogenic CO2 frameworks complicate cross-border certification and contract structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Straw Market |
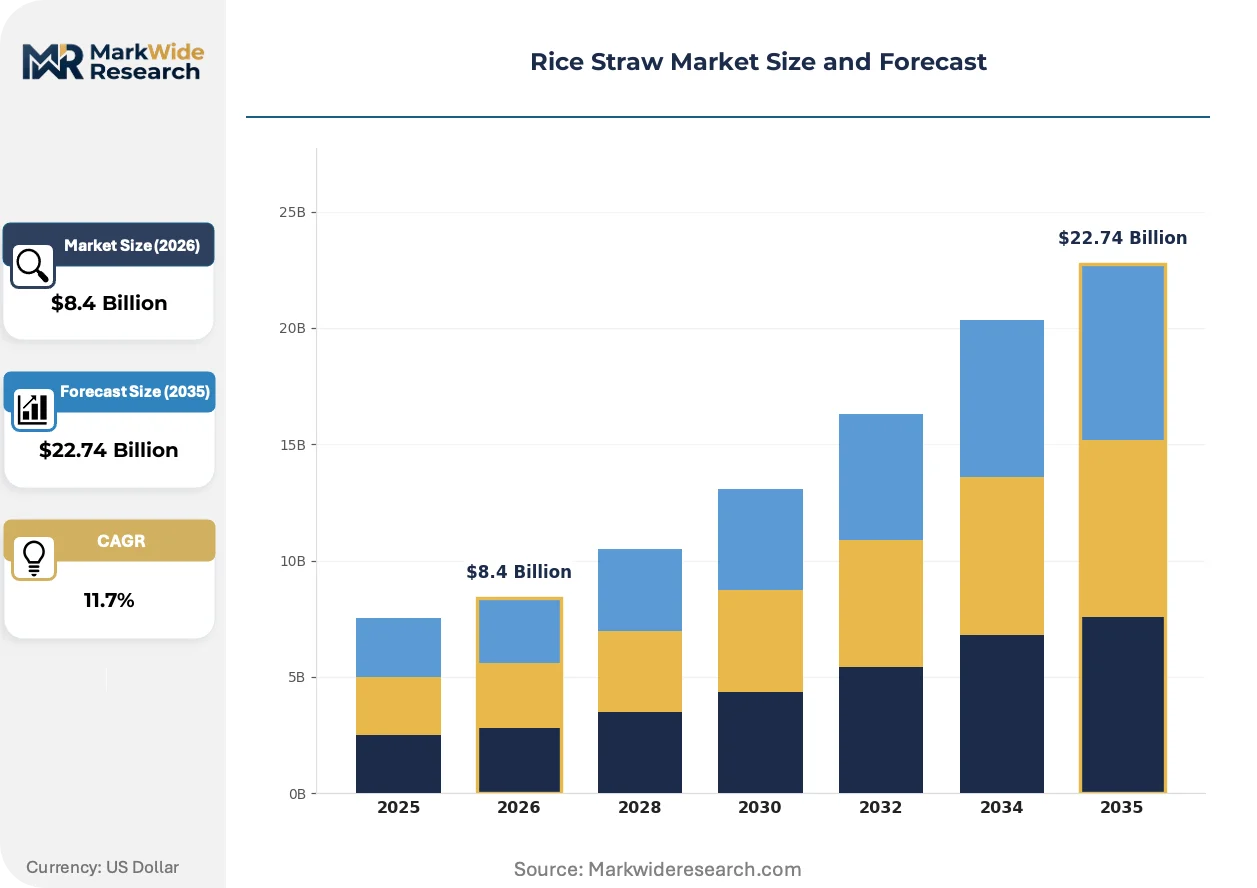
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Rice Straw, Processed Rice Straw, Rice Straw Pellets, Rice Straw Bales Application: Animal Feed, Bioenergy Production, Paper Manufacturing, Mulching End User: Agricultural Sector, Energy Producers, Packaging Industry, Construction Distribution Channel: Direct Sales, E-commerce, Distributors, Retail Stores |
| Companies Covered | Solvay S.A., Bee Chems, Brisil, AGI MILLTEC, K V Metachem, Gia Gia Nguyen Co., Ltd., Usher Agro Ltd, JASORIYA RICE MILL, Agreka Builds & Straw Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Straw Market Strategic Shifts
Processing technology is leapfrogging traditional baling economics, while regulatory pressure on residue burning accelerates formal market formation. Three developments are restructuring competitive positioning.
Torrefaction systems are absorbing higher-moisture feedstocks than conventional pellet lines, expanding the geographic catchment for viable procurement. Vietnamese power developers are piloting these units to reduce transport cost burdens from Mekong Delta collection points. The technology is absorbing margin pressure from dispersed biomass logistics by upgrading energy density before long-haul shipment.
REACH registration requirements for imported biomass are tightening traceability obligations on European buyers sourcing from South Asia. Industrial consequence includes mandatory supplier audits and chain-of-custody documentation. Pellet exporters to Germany and the Netherlands are responding by integrating collection cooperatives under single certification umbrellas.
Buyer concentration among state power utilities is compressing contract negotiation cycles and standardizing quality specifications. Aggregators serving Vietnam Electricity and PLN Indonesia are displacing spot-market traders with multi-year supply agreements. This pattern is most visible in Mekong Delta farming networks where Gia Gia Nguyen Co., Ltd. anchors long-term procurement relationships.
Rice Straw Market Segmentation
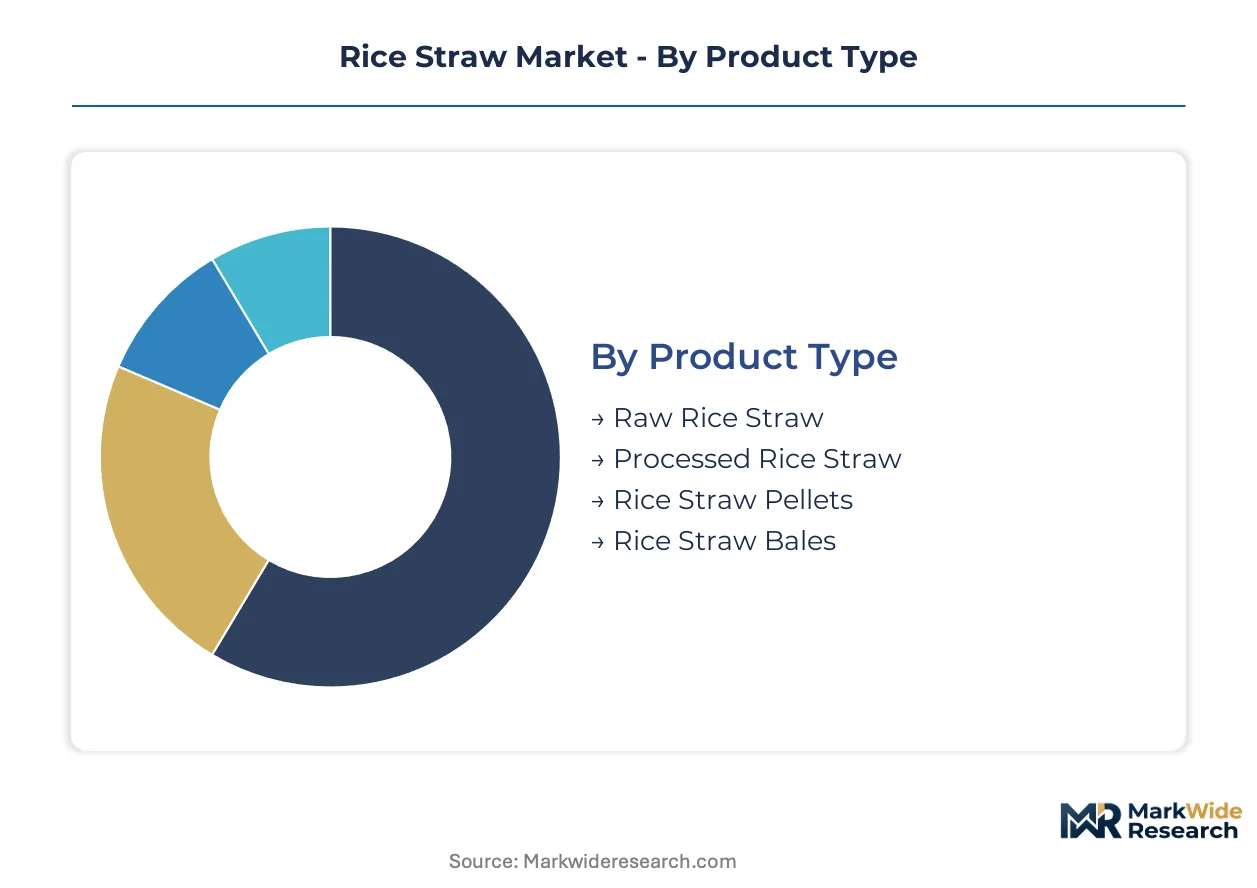
Rice straw valorization routes diverge sharply by processing intensity, with unprocessed bales serving field-return markets while pelletized and chemically fractionated products capture premium energy and materials contracts. Segmentation clarity enables suppliers to match capital deployment against margin profiles and offtake certainty across disparate end-use channels.
Product Type:
Upgrade cycles from loose biomass to densified fuel forms are shortening as power utilities impose stricter handling specifications and carbon certification requirements.
- Raw Rice Straw:Field-collected residue with 35-40% cellulose, 20-25% hemicellulose, and 15-20% silica content by dry weight. Punjab, Haryana, and Uttar Pradesh agricultural cooperatives move the largest volumes during October-November harvest windows, though high moisture content forces immediate consumption or rapid drying to prevent decomposition losses.
- Processed Rice Straw:Chemically or mechanically treated material enabling silica extraction, pulp production, or enhanced digestibility. Bee Chems refines this stream for industrial silica applications serving rubber and coatings sectors, with fractionation protocols commanding price multiples over raw biomass.
- Rice Straw Pellets:Densified fuel form standardized for co-firing systems. Vietnam Electricity and PLN Indonesia procurement mandates are pulling Mekong Delta and Javanese supply into formal long-term contracts, with torrefaction pilots expanding viable catchment areas.
- Rice Straw Bales:Mechanically compressed field residue reducing transport cost burdens. AGI MILLTEC baling systems dominate Indo-Gangetic Plain collection infrastructure, though margins compress against seasonal price volatility and storage limitations.
Raw rice straw bales sit at the top of the volume ranking, with rice straw pellets climbing the fastest.
Application:
Cost tier differentiation separates commodity soil amendment from premium energy and materials pathways, with regulatory carbon pricing widening the spread.
- Animal Feed:Processed roughage substituting for wheat straw and green fodder in South Asian dairy cooperatives. Urea treatment and ensiling protocols improve palatability and protein absorption, with procurement concentrating in Haryana and Gujarat milk shed networks.
- Bioenergy Production:Anaerobic digestion and combustion feedstock. India's Central Pollution Control Board Graded Response Action Plan mechanically redirects straw from field burning toward approved biogas and power facilities, compressing supply windows.
- Paper Manufacturing:Pulp substitute reducing wood fiber dependence. Vietnamese mills pilot straw pulping for corrugated medium production, though silica content complicates chemical recovery cycles.
- Mulching:Direct field application for moisture retention and weed suppression. Competes with commercial offtake by retaining nutrients for subsequent rice-wheat rotations across the Indo-Gangetic Plain.
Animal feed commands the deepest volume penetration, while bioenergy production gains share fastest on regulatory coercion and utility procurement formalization.
End User:
Customer type determines specification stringency, with energy producers imposing the most demanding certification and handling protocols.
- Agricultural Sector:On-farm consumption for livestock bedding and mulching. Direct field return dominates this segment, with minimal processing value capture.
- Energy Producers:Power utilities and biogas facility operators. Vietnam Electricity co-firing mandates and Indonesian state procurement are consolidating supply chains under multi-year agreements.
- Packaging Industry:Molded fiber and paperboard manufacturers. Gia Gia Nguyen Co., Ltd. anchors Mekong Delta supply relationships for Vietnamese export processors.
- Construction:Insulation panels and composite materials. Silica-rich ash applications remain nascent, with Bee Chems extraction chemistry enabling industrial-grade feedstock qualification.
The agricultural sector absorbs the greatest tonnage, with energy producers expanding most quickly on mandated procurement targets.
Distribution Channel:
Supply concentration in harvest-belt farming networks favors direct procurement relationships over arm's-length retail or digital channels.
- Direct Sales:Aggregator-to-producer contracts with farming cooperatives and large landholders. Gia Gia Nguyen Co., Ltd. and similar anchors sustain consistent raw material flows despite seasonal variability.
- E-commerce:Digital platforms for specialty processed products and equipment. Limited penetration given bulk logistics and quality verification requirements.
- Distributors:Regional intermediaries consolidating smallholder collections. Strain storage infrastructure during six-month procurement surges across Punjab and Haryana.
- Retail Stores:Local agricultural supply outlets for garden mulch and small-scale feed applications. Thin margins reflect low-value commodity positioning.
Direct sales dominates transaction value, with distributor networks handling the greatest physical volume through seasonal consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as European buyers source certified Asian biomass to meet EU Renewable Energy Directive II compliance costs that domestic feedstocks cannot match. Processors in South and Southeast Asia capture this cost-of-compliance gap through formal certification chains.
India
Bioenergy producers scale procurement for anaerobic digestion facilities across Punjab, Haryana, and Uttar Pradesh. The Central Pollution Control Board enforces the Graded Response Action Plan, banning crop residue burning and mechanically redirecting straw toward approved offtake channels. The Indo-Gangetic Plain concentrates collection infrastructure where AGI MILLTEC baling systems dominate mechanized densification.
Vietnam
Power utilities scale pellet procurement under co-firing mandates that pull processed straw into formal energy supply chains. State-owned Vietnam Electricity procurement is formalizing biomass co-firing targets. The Mekong Delta anchors supply relationships through Gia Gia Nguyen Co., Ltd., sustaining consistent raw material flows despite seasonal harvest variability.
Indonesia
State-owned electricity procurement formalizes biomass co-firing targets, creating new demand nodes outside traditional Indian supply chains. PLN Indonesia consolidates supply chains under multi-year agreements. Javanese farming networks are integrating into these procurement systems as aggregators displace spot-market traders.
China
Industrial silica applications expand as refiners develop higher-purity extraction protocols for rubber and coatings sectors. National biogenic CO2 frameworks under ISO 14064 methodologies shape carbon accounting for straw valorization routes. Processing clusters in eastern provinces upgrade energy density through torrefaction pilots before long-haul shipment.
Netherlands
European energy producers source certified Asian biomass to create compliance pathways under EU Renewable Energy Directive II. REACH registration requirements tighten traceability obligations, mandating supplier audits and chain-of-custody documentation. Rotterdam and Amsterdam ports serve as consolidation points for pellet imports from South and Southeast Asia.
Rice Straw Market Competitive Environment
Capacity expansion dominates the current landscape as processors race to secure harvest-window supply before competitor offtake locks in farming cooperatives. The vendor base organizes around three strategic archetypes: chemical processors extracting industrial silica, mechanized baling equipment suppliers, and supply chain anchors integrating collection networks. Geographic expansion and strategic partnerships constitute the two dominant competitive moves, with European certification requirements forcing cross-border alliance structures.
Among chemical processing specialists, Bee Chems occupies a position exemplifying industrial silica extraction from rice straw ash. Gia Gia Nguyen Co., Ltd. anchors Mekong Delta supply relationships, representing the supply chain integration archetype. AGI MILLTEC sits within the mechanized densification tier, with its name signaling Indian origin and equipment-focused positioning.
| Leading Market Players |
|---|
| Solvay S.A. |
| Bee Chems |
| Brisil |
| AGI MILLTEC |
| K V Metachem |
| Gia Gia Nguyen Co., Ltd. |
| Usher Agro Ltd |
| JASORIYA RICE MILL |
| Agreka Builds & Straw Innovations |
| Others |
Value Chain & Pricing Dynamics
State-owned electricity procurement in Vietnam and Indonesia anchors the dominant pricing model through multi-year offtake contracts that compress spot-market premiums. These utility buyers impose standardized quality specifications and carbon certification requirements, forcing suppliers to absorb processing costs before value capture.
Pricing Analysis
Direct-to-utility contracts command thinner distributor margins than spot-market sales to smaller bioenergy operators. Three-tier pricing structure across certified-sustainable, standard-grade, and raw-bale tiers separates European compliance buyers from Asian power utilities and local agricultural offtakers. Pricing pressure stems from seasonal harvest gluts in Punjab and Haryana that force rapid densification before decomposition losses. Smallholder cooperatives exhibit the highest price sensitivity, while European energy producers under EU Renewable Energy Directive II compliance obligations show the least.
Supply Chain Analysis
Skilled technician shortages in rural Punjab and Haryana constrain operating capacity for baling and pelletizing equipment. Supply concentrates in India, Vietnam, and Indonesia, with raw material flows drawing from Mekong Delta, Indo-Gangetic Plain, and Javanese farming networks. Silica content variability and high-moisture handling requirements create quality-control dependencies. Single-source vulnerability runs through Gia Gia Nguyen Co., Ltd. and similar collection anchors that lock in multi-year procurement relationships. Distribution runs through direct aggregator-to-producer contracts rather than arm's-length retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rice straw market functions as a stable compounder under persistent regulatory coercion that mechanically redirects agricultural residue from field burning toward formal valorization channels.
For Market Incumbents: Extend certification coverage under ISO 14064 methodologies to capture premium European offtake contracts before REACH registration requirements tighten further. Deepen backward integration into Mekong Delta and Javanese collection networks to lock in supply ahead of PLN Indonesia and Vietnam Electricity procurement formalization. Threat substitution from direct soil amendment return competes for volume in rice-wheat rotation zones. For New Entrants and Emerging Players: Begin with torrefaction pilot deployments in Vietnamese provinces outside traditional Mekong Delta supply anchors, where transport cost burdens from dispersed biomass collection remain unaddressed. Target Indonesian state power procurement as the most penetrable demand node outside established Indian supply chains. Go-to-market angle centers on blockchain traceability verification for no-burn collection premiums in European compliance markets. For Investors and Strategic Acquirers: European energy producers under EU Renewable Energy Directive II obligations are the most active acquirer in this space, seeking certified Asian biomass supply to close compliance cost gaps that domestic feedstocks cannot match. Long-term viability rests on carbon accounting standardization across divergent national biogenic CO2 frameworks. Target acquisition archetype: collection-integrated processors with existing utility offtake relationships. Signal to watch is ISO 14064 methodology evolution that determines which straw valorization routes secure premium contract tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Secures harvest-window supply before competitor offtake locks in farming cooperatives across Punjab and Haryana. |
| Blockchain Traceability Implementation | Enables premium pricing for certified-sustainable straw in European offtake contracts under REACH requirements. |
| Torrefaction Capacity Buildout | Expands viable geographic catchment for procurement by upgrading energy density before long-haul shipment to Vietnamese power developers. |
| ISO 14064 Certification Investment | Positions suppliers for carbon credit revenues under evolving methodologies that favor anaerobic digestion integration. |
| Multi-Year Supply Agreement Structuring | Displaces spot-market traders with formal contracts to Vietnam Electricity and PLN Indonesia procurement mandates. |
Study Parameters
Coverage spans South Asia, Southeast Asia, and European import markets, with primary inputs from each region combined with secondary validation. Primary interviews engaged bioenergy facility operators, agricultural cooperative managers, utility procurement officers, and silica extraction chemists. Secondary sources included India's Central Pollution Control Board enforcement records, EU Renewable Energy Directive II implementation guidance, Vietnam Electricity procurement disclosures, and customs data on pellet trade flows. Bottom-up supply aggregation and top-down demand calibration were triangulated to reconcile volume estimates.
Granularity-level modeling tracked product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated rice-wheat rotation intensity patterns, anaerobic digestion facility buildout pipelines, and co-firing mandate implementation schedules in Vietnam and Indonesia.
Several conditions sit outside the modeled scope, including extreme weather disruptions to harvest windows, abrupt shifts in India's Graded Response Action Plan enforcement intensity, and breakthroughs in direct field-return nutrient retention economics. Forecasts reflect assumptions about regulatory continuity and infrastructure buildout pacing. Material deviation in carbon accounting standardization timelines or utility procurement formalization rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Seaweed Market