
 Colombia Hemp Market | 2026-2036
Colombia Hemp Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Hemp Market Intelligence
Product bundling is consolidating across Colombia's hemp sector as suppliers merge CBD oil with hemp seed derivatives into unified wellness portfolios. Canopy Growth Corp leverages its extraction infrastructure to anchor supply contracts with Andean processors. Tilray Brands Inc competes through pharmaceutical-grade certification pathways that differentiate its CBD oil offerings from commodity alternatives.
Colombia hemp comprises Cannabis sativa L. cultivars containing less than 1.0% THC by dry weight, cultivated primarily for CBD extraction, fiber yield, and seed oil production via cold-press or CO2 supercritical methods. The crop serves pharmaceutical formulators, textile producers, and nutraceutical manufacturers seeking non-psychoactive cannabinoid inputs. CBD oil dominates value capture due to pharmaceutical and cosmetic offtake, while hemp fiber extends into building materials where thermal insulation specifications command premium positioning. Extraction methods segment by solvent profile, with supercritical CO2 systems concentrating among export-oriented processors seeking EU pharmacopoeia compliance.
INVIMA regulates hemp-derived product registration and facility licensing under Colombia's cannabis decree framework, while the Ministry of Justice and Law oversees cultivation quota allocation through the National Narcotics Council. These bodies shape market access by distinguishing industrial hemp from psychoactive cannabis through THC threshold enforcement and export permit conditioning. Stakeholders must monitor quota liberalization trajectories and evolving pharmacopoeia alignment requirements that will determine which processing technologies qualify for international market entry.
Market Dynamics
Colombia's hemp sector is experiencing structural compression as INVIMA accelerates facility licensing timelines while simultaneously tightening THC threshold enforcement, forcing processors to choose between domestic compliance investments or export-oriented pharmacopoeia alignment.
Growth Catalysts
- INVIMA licensing liberalization:The national pharmaceutical regulator has streamlined facility certification pathways, reducing approval timelines for extraction operations serving pharmaceutical formulators.
- Andean highland cultivation clusters:Altitude-advantaged growing zones near Bogotá and Medellín concentrate premium cannabinoid production, attracting contract farming arrangements from export processors.
- EU pharmacopoeia alignment:Colombian processors investing in supercritical CO2 extraction infrastructure qualify for European cosmetic and pharmaceutical ingredient supply chains.
Market Restraints
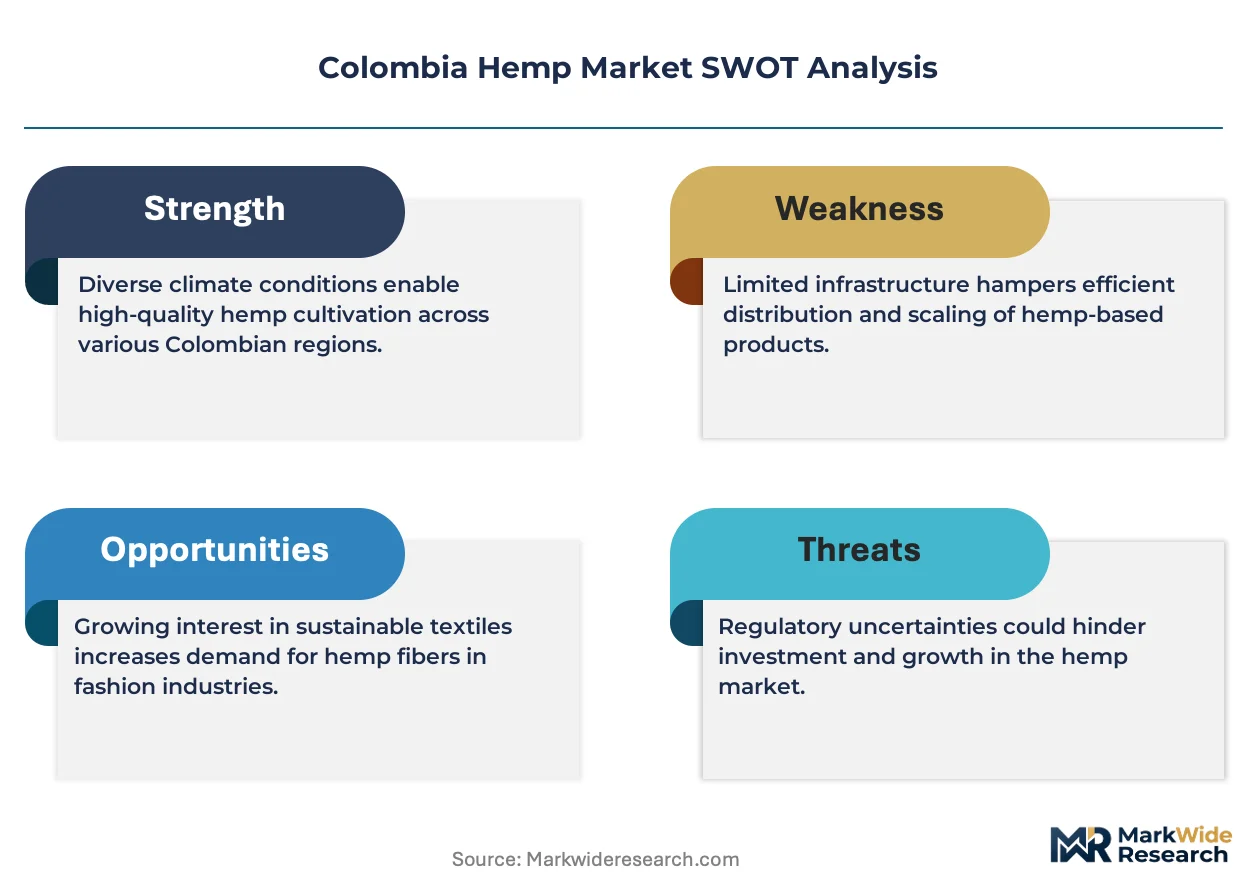
- THC threshold volatility:The 1.0% dry weight limit creates batch rejection risk during flowering stages, requiring continuous third-party testing that elevates working capital requirements for cultivators.
- Extraction equipment import dependence:Supercritical CO2 systems and chromatography units originate from German and Swiss suppliers, exposing processors to euro-denominated capex cycles and extended lead times.
- Fiber processing infrastructure gaps:Domestic decortication and textile-grade fiber refinement capacity remains concentrated in legacy cotton facilities ill-suited to hemp bast fiber handling.
Strategic Opportunities
- Antioquia department industrial hemp corridors:Medellín's manufacturing base offers underutilized warehouse conversion potential for integrated extraction-textile operations serving construction insulation markets.
- Pharmaceutical-grade CBD isolate demand:European cosmetic formulators are qualifying non-synthetic cannabinoid inputs, creating first-mover advantage for Colombian processors achieving GMP certification.
- Hempcrete building material substitution:Colombia's construction sector faces thermal efficiency mandates that hemp-lime composites satisfy, opening agricultural fiber offtake beyond traditional textiles.
Industry Challenges
- Extraction technician certification gaps:Supercritical CO2 system operation and chromatographic purification require specialized training unavailable through Colombia's agricultural extension networks.
- Batch-to-batch cannabinoid standardization:Outdoor cultivation in Andean microclimates produces variable CBD profiles, complicating pharmaceutical client qualification protocols.
- Dual-use facility design complexity:Processors seeking both domestic market sales and export certification must engineer redundant processing lines to satisfy divergent INVIMA and EU-GMP traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Hemp Market |
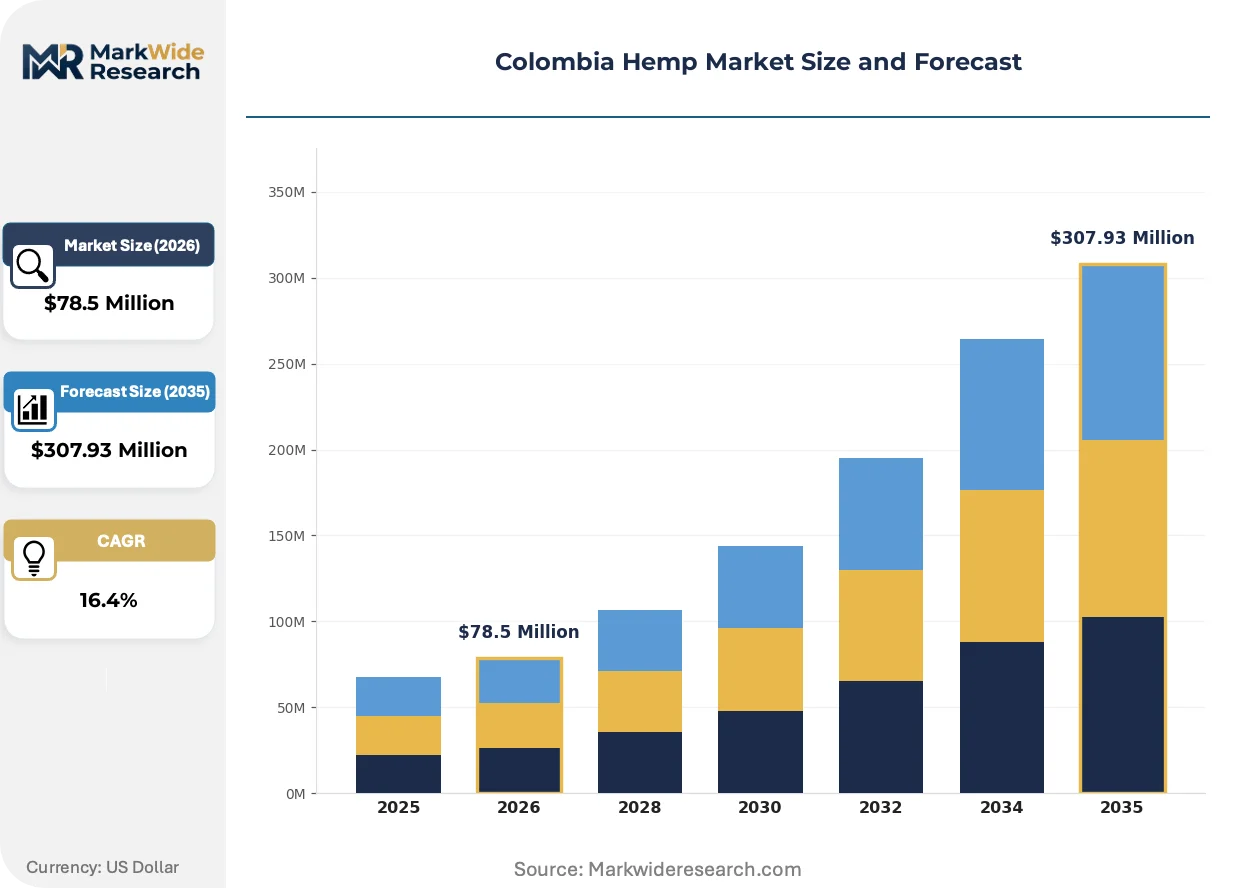
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $307.93 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Textiles, Food Products, Building Materials, Personal Care Product Type: CBD Oil, Hemp Seeds, Hemp Fiber, Hemp Seed Oil End User: Manufacturers, Retailers, Distributors, Consumers Technology: Extraction Methods, Cultivation Techniques, Processing Technologies, Testing Methods |
| Companies Covered | The Cronos Group, OrganiGram Holdings Inc, Aurora Cannabis, CannTrust Holdings Inc, The Hydropothecary Corp, Tilray Brands Inc, Cannabist Company Holdings Inc, Atlas Growers, Canopy Growth Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Hemp Market Strategic Shifts & Innovations
Colombian hemp processors are reconfiguring extraction infrastructure to capture value across multiple output streams simultaneously, moving beyond single-product CBD isolation toward integrated fiber-seed-cannabinoid recovery systems.
Supercritical CO2 extraction with integrated winterization is decentralizing processing capacity away from Bogotá's centralized pharmaceutical corridor toward cultivation-adjacent facilities in Boyacá and Cundinamarca departments. Mid-scale cooperatives are adopting skid-mounted extraction units that reduce biomass transport costs and preserve terpene profiles for cosmetic applications. This geographic diffusion is compressing the traditional processor-aggregator hierarchy and enabling direct cultivator-processor-contractor relationships.
INVIMA's 2024 technical guidance on novel food ingredient classification is forcing CBD oil suppliers to choose between pharmaceutical registration pathways or food supplement reclassification. The industrial consequence is a bifurcation in processing investment, with export-oriented facilities pursuing GMP-grade isolation while domestic-market processors reformulate for topical cosmetic applications. Antioquia-based formulators are most affected, redirecting R&D expenditure toward dermatological testing protocols.
Pharmaceutical laboratories are consolidating supplier relationships around vertically integrated cultivator-processors capable of batch-level traceability. This concentration is displacing spot-market biomass purchasing and replacing it with multi-year offtake agreements indexed to cannabinoid potency tiers. The Cauca Valley cultivation zone exhibits the strongest contract farming penetration, with processors providing genetics and technical assistance in exchange for exclusive supply commitments.
Colombia Hemp Market Segmentation
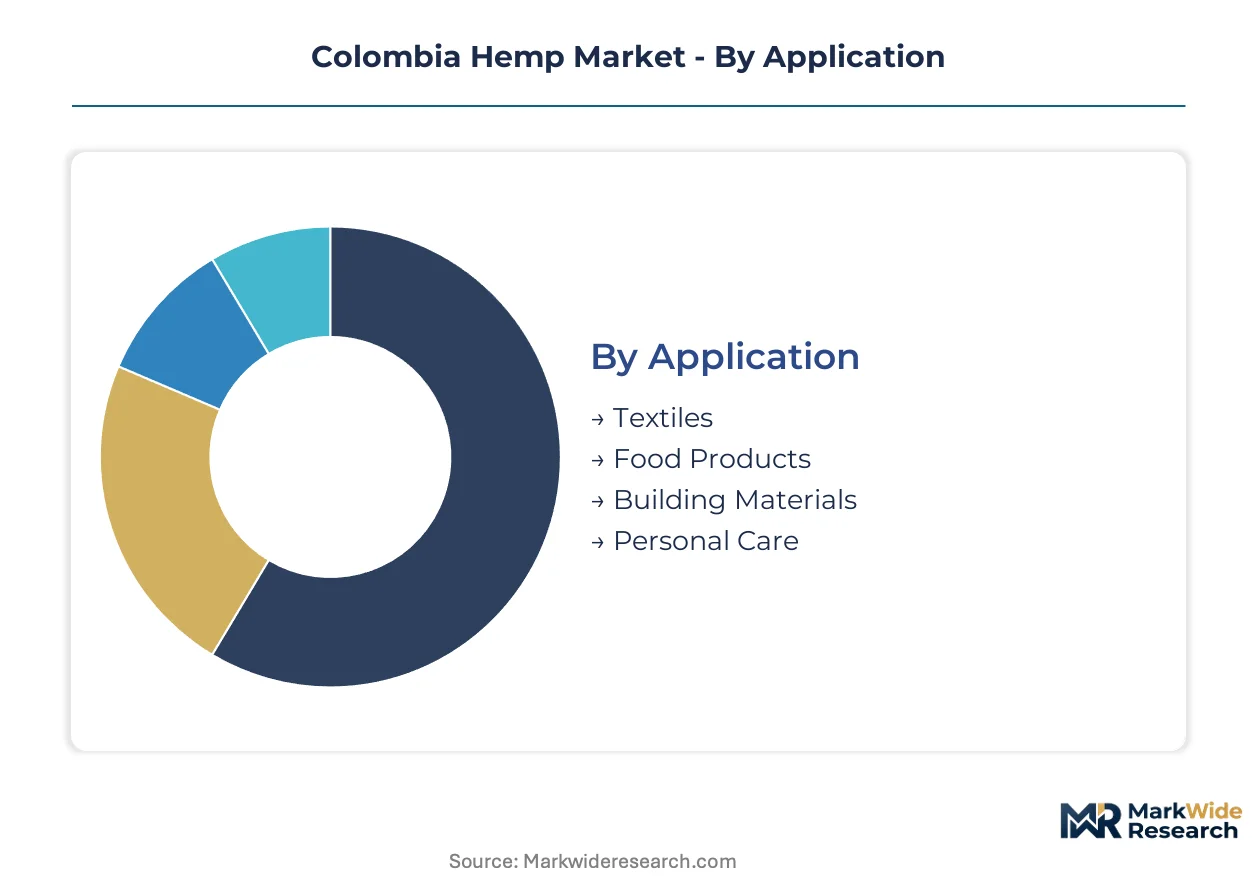
Colombia's hemp market segments reflect divergent margin profiles and regulatory burdens across the value chain. Processors must align product mix with INVIMA pathway requirements and export certification standards to optimize capital deployment.
Application:
Customization intensity varies sharply across end-uses, with pharmaceutical-grade outputs demanding batch-level traceability while construction materials tolerate broader specification bands.
- Textiles:Bast fiber applications span apparel yarns to industrial cordage, with decortication quality determining downstream textile mill acceptance. Demand clusters in Medellín's legacy garment district where cotton processors retrofit equipment for hemp handling. Thermal insulation specifications in building codes are accelerating technical textile offtake.
- Food Products:Hulled hemp seeds and protein isolates require novel food registration under INVIMA's evolving guidance, creating compliance lag against import competition. Functional food formulators in Bogotá source domestically for clean-label positioning despite higher input costs versus Canadian imports.
- Building Materials:Hempcrete and fiber-reinforced composites serve thermal efficiency mandates in Colombia's construction sector.
- Personal Care:CBD-infused topicals dominate cosmetic applications with dermatological testing protocols governing shelf placement.
Most installed capacity flows through Textiles. Expansion is steepest in Building Materials.
Product Type:
Margin concentration tracks extraction sophistication, with isolate products commanding pharmaceutical premiums against commodity seed derivatives.
- CBD Oil:Full-spectrum, broad-spectrum, and isolate grades segment by cannabinoid retention profile and THC remediation depth. Supercritical CO2 extraction infrastructure in Cundinamarca supplies EU cosmetic formulators seeking non-synthetic cannabinoid inputs. INVIMA's pharmaceutical registration pathway requires GMP compliance that filters out smaller processors.
- Hemp Seeds:Whole seed, hulled hearts, and pressed cake serve nutraceutical and animal feed applications with lower regulatory barriers. Andean highland cultivation clusters near Boyacá supply domestic food manufacturers prioritizing origin claims over cost optimization.
- Hemp Fiber:Primary bast and secondary hurd fractions diverge in decortication equipment requirements and end-use specifications.
- Hemp Seed Oil:Cold-pressed and refined grades compete in cosmetic and culinary markets with distinct fatty acid profile positioning.
CBD Oil captures the highest value per kilogram. Hemp Seeds are gaining share fastest in domestic food applications.
End User:
Procurement sophistication escalates from spot-market consumer purchases to multi-year offtake agreements with integrated cultivator-processors.
- Manufacturers:Pharmaceutical laboratories, textile mills, and construction material producers require batch consistency and documentation depth that favors vertical supplier relationships. Cauca Valley processors secure exclusive supply through genetics provision and technical assistance.
- Retailers:Pharmacy chains and natural product stores stock CBD oils with INVIMA registration numbers displayed for consumer verification.
- Distributors:Regional wholesalers aggregate biomass from smallholder cooperatives for processor delivery.
- Consumers:Direct-to-customer channels concentrate in urban wellness segments with education-intensive purchase journeys.
Manufacturers absorb the majority of processed output. Retailers are expanding shelf space most aggressively.
Technology:
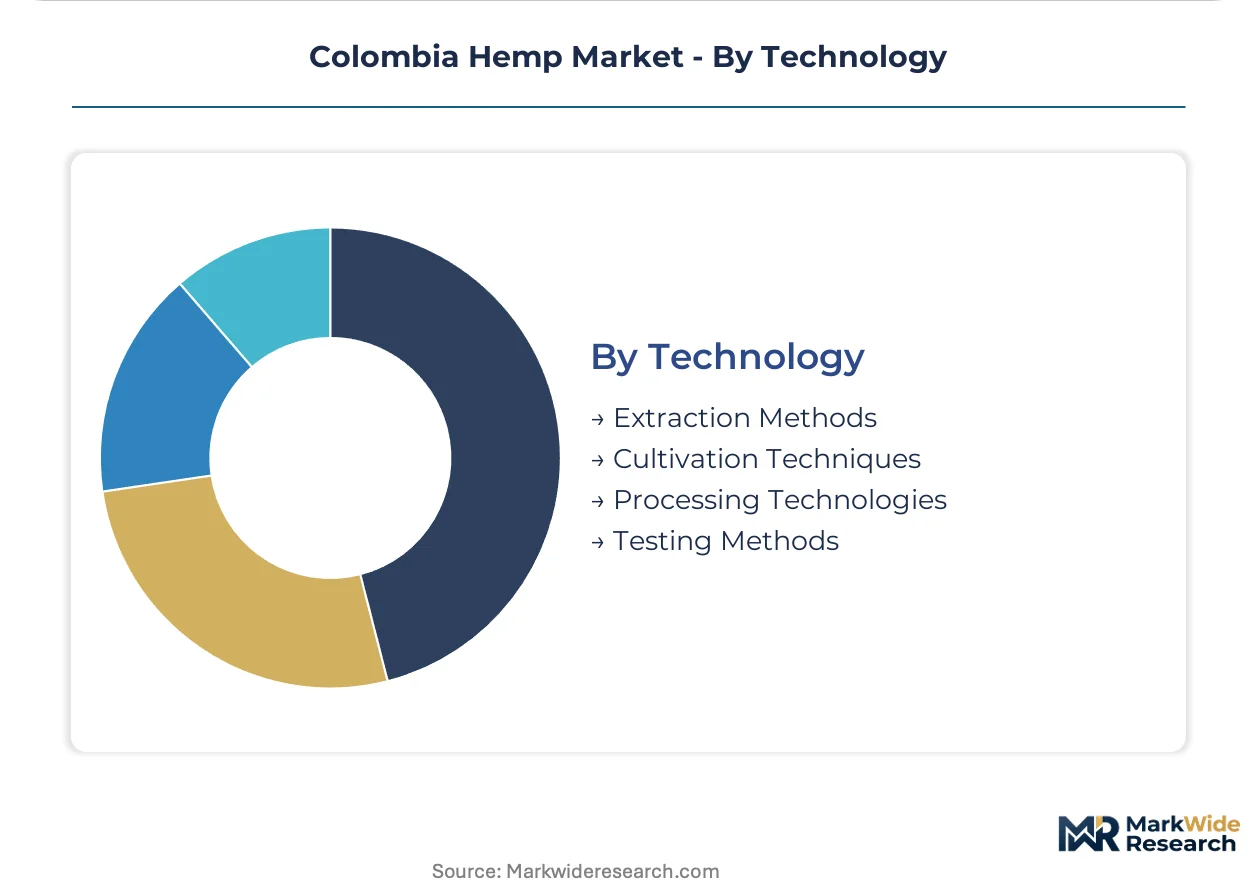
Capital intensity and operator skill requirements segment processing infrastructure into export-tier and domestic-market tiers.
- Extraction Methods:Supercritical CO2, ethanol, and hydrocarbon systems differ in capex, solvent recovery, and product portfolio flexibility. CO2 infrastructure qualifies for EU pharmacopoeia supply chains but requires German and Swiss equipment imports with euro-denominated cycles.
- Cultivation Techniques:Outdoor Andean highland production dominates CBD yield economics against controlled-environment alternatives.
- Processing Technologies:Decortication, degumming, and spinning preparation equipment for fiber applications remains undersupplied domestically.
- Testing Methods:HPLC and GC-MS potency verification with third-party certification manages THC threshold compliance risk.
Extraction Methods concentrate the most capital. Testing Methods are scaling fastest to meet INVIMA enforcement tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's hemp sector traces its modern lineage to 2016 regulatory reforms that distinguished industrial hemp from psychoactive cannabis, establishing the Andean nation as Latin America's first mover in cannabinoid extraction for export markets.
Bogotá-Cundinamarca Corridor
Pharmaceutical-grade CBD extraction concentrates in Bogotá's industrial periphery where INVIMA-licensed facilities cluster near El Dorado International Airport for temperature-controlled export logistics. The national pharmaceutical regulator maintains its headquarters here, streamlining facility inspections and registration renewals. Zipaquirá and Facatativá host the densest supercritical CO2 processing infrastructure, with processors converting highland biomass into EU pharmacopoeia-compliant isolates.
Medellín-Antioquia Manufacturing Belt
Textile heritage from Medellín's garment district drives hemp fiber demand for technical insulation applications in construction. The Ministry of Justice and Law allocates expanded cultivation quotas to Antioquia's Andean highland municipalities above 2,000 meters elevation. Rionegro and La Ceja concentrate decortication pilot projects retrofitting legacy cotton equipment for bast fiber handling.
Boyacá Highlands
Seed oil production dominates Boyacá's lower-altitude cultivation zones where cold-press infrastructure serves domestic nutraceutical manufacturers. INVIMA's novel food guidance has delayed full market access for hulled seed products, forcing processors toward cosmetic-grade oil refinement. Tunja anchors regional aggregation with warehouse capacity for cooperative biomass consolidation.
Cauca Valley Cultivation Zone
Contract farming arrangements penetrate deepest in Valle del Cauca where processors provide genetics and technical assistance in exchange for exclusive supply commitments. Palmira and Buga concentrate outdoor cultivation benefiting from consistent photoperiods and irrigation infrastructure inherited from sugarcane operations. Batch-to-batch cannabinoid variability here complicates pharmaceutical client qualification protocols.
Amazon Foothills (Caquetá-Putumayo)
Emerging low-THC cultivation permits extend into southern departments where land costs support larger-scale fiber operations. INVIMA enforcement capacity thins with distance from Bogotá, elevating compliance risk for export-oriented processors. Florencia hosts nascent cooperative formation linking smallholders to Andean processing corridors through refrigerated transport contracts.
Colombia Hemp Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and export market access, creating a stratified competitive map where GMP-compliant isolators capture pharmaceutical premiums while domestic-market processors compete on cosmetic formulation speed. The vendor base spans three strategic archetypes: vertically integrated cultivator-processors with proprietary genetics, tolling extraction specialists serving contract biomass suppliers, and diversified Canadian cannabis multinationals leveraging existing Andean infrastructure. Competitive moves concentrate on multi-year offtake agreement formation and redundant processing line installation to satisfy divergent INVIMA and EU-GMP traceability requirements.
Within the multinational cannabis tier, Canopy Growth Corp and Tilray Brands Inc occupy positions as North American publicly traded entities with established Colombian extraction infrastructure. Aurora Cannabis represents the mid-cap specialist archetype with Andean cultivation exposure. These entities exemplify the strategic pattern of leveraging existing South American operational footprints to access altitude-advantaged cannabinoid production without greenfield facility construction.
| Leading Market Players |
|---|
| The Cronos Group |
| OrganiGram Holdings Inc |
| Aurora Cannabis |
| CannTrust Holdings Inc |
| The Hydropothecary Corp |
| Tilray Brands Inc |
| Cannabist Company Holdings Inc |
| Atlas Growers |
| Canopy Growth Corp |
| Others |
Cost & Logistics Intelligence
EU cosmetic formulators' pharmacopoeia compliance requirements compress procurement timelines for Colombian processors, forcing Andean suppliers to absorb euro-denominated equipment costs and batch-testing overhead that elevates working capital thresholds. This demand-side specification tightening stratifies pricing power between GMP-certified isolators and domestic-market cosmetic processors.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade isolate, broad-spectrum cosmetic, and commodity seed derivative levels separates certified EU-compliant outputs from INVIMA-registered domestic products. Price differentiation rests on GMP certification status and cannabinoid potency standardization, with pharmaceutical laboratories least sensitive to unit cost. Cost compression in broad-spectrum tiers is intensifying as Antioquia-based processors redirect R&D toward dermatological testing protocols.
Supply Chain Analysis
Refrigerated transport corridors from Andean highland cultivation zones to Bogotá extraction facilities concentrate logistics spend in biomass consolidation and temperature-controlled export staging. Colombian supply draws from domestic highland clusters, German and Swiss extraction equipment imports, and EU pharmacopoeia certification services. Single-source vulnerability sits with supercritical CO2 system suppliers. Distribution runs through vertically integrated cultivator-processors with multi-year offtake agreements displacing spot-market aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's hemp sector compounds steadily as INVIMA licensing liberalization expands addressable processing capacity while altitude-advantaged cultivation zones lock in cannabinoid yield premiums.
For Market Incumbents: Extend GMP-certified extraction capacity in Cundinamarca to capture pharmaceutical-grade CBD isolate demand from European cosmetic formulators. Secure exclusive genetics licensing with Cauca Valley contract farming arrangements to defend batch consistency against emerging tolling specialists. INVIMA's novel food reclassification threat demands redundant processing line investment for dual domestic-export qualification. For New Entrants and Emerging Players: Regional wholesalers in Amazon foothill departments offer lowest-friction channel access for biomass aggregation plays serving Andean processing corridors. Target Caquetá-Putumayo cultivation permits where land costs support fiber-scale operations and INVIMA enforcement capacity thins. Decortication equipment retrofit partnerships with legacy cotton facilities in Medellín provide defensible textile-grade fiber positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale cooperatives adopting skid-mounted extraction units that compress cultivator-processor hierarchies. Long-term viability hinges on pharmacopoeia alignment trajectory rather than domestic market scale. Watch EU cosmetic ingredient qualification protocols as inflection indicator for Colombian processor tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | Unlocks EU pharmacopoeia supply chains for pharmaceutical-grade CBD isolate exports. |
| Backward Integration into Genetics | Secures proprietary cultivars with altitude-optimized cannabinoid profiles for contract farming. |
| Skid-Mounted Extraction Deployment | Enables cultivation-adjacent processing in Boyacá and Cundinamarca departments reducing transport costs. |
| Decortication Equipment Retrofit | Repurposes Medellín's legacy cotton infrastructure for hemp bast fiber thermal insulation output. |
| Multi-Year Offtake Agreement Formation | Replaces spot-market biomass purchasing with potency-tiered supply commitments from Cauca Valley. |
Research Approach
Coverage spans Colombia's Andean highland cultivation zones and processing corridors, with primary inputs from each. Cultivation directors at Boyacá cooperatives, extraction facility operators in Cundinamarca, INVIMA regulatory affairs specialists, and EU cosmetic formulator procurement managers provided structured interviews. Secondary validation drew from INVIMA facility registration databases, Colombian Ministry of Justice quota allocation records, EU pharmacopoeia monographs, and customs export declarations. Bottom-up biomass volume estimates triangulated against top-down pharmaceutical ingredient demand projections.
Rate-of-change decomposition separates volume expansion from price realization across the projection horizon. Segmentation dimensions modeled include application type, product grade tier, extraction technology sophistication, and regional cultivation cluster. CAGRs derived from fitted growth curves incorporating INVIMA licensing trajectory assumptions and EU cosmetic ingredient qualification timelines. Forecast inputs include altitude-adjusted cannabinoid yield coefficients and supercritical CO2 equipment import lead time cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to INVIMA THC threshold enforcement volatility and EU novel food classification rulings. Forecasts reflect documented assumptions about quota liberalization pace and pharmacopoeia alignment feasibility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
Sugar Cane Market